
 Kids Swimwear Market | 2026-2036
Kids Swimwear Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Swimwear Market Intelligence
Subscription-based seasonal refresh programs is shifting how families replenish children's swimwear as kids outgrow sizes rapidly. Ralph Lauren Corporation leverages its heritage branding to sustain premium positioning across resort and poolside collections. Hanna Andersson anchors its competitive stance through organic cotton blends and durable construction for repeat purchases. Milky Clothing specializes in sun-safe UPF-rated designs that differentiate its catalog from fashion-only competitors.
Kids swimwear encompasses purpose-built aquatic garments engineered with chlorine-resistant fibers, four-way stretch recovery, and ultraviolet protection factors typically rated UPF 30–50+ for pediatric skin safety. Manufacturers bond polyester with elastane to achieve shape retention through repeated saltwater and pool chemical exposure. Rash guards and swim shorts command expanding shelf space as parents prioritize sun-blocking coverage over traditional minimal suits. Online sales channels capture accelerating volume as size-prediction algorithms and flexible return policies reduce fit-risk hesitation for repeat buyers.
The Consumer Product Safety Commission enforces flammability standards and drawstring regulations for children's apparel, while OEKO-TEX and bluesign certifications increasingly filter wholesale procurement decisions. State-level sunscreen and sun-safety education programs in California and Florida indirectly elevate demand for UPF-labeled swimwear through pediatrician recommendations. Stakeholders must monitor how chemical disclosure mandates and extended producer responsibility frameworks for textiles reshape material sourcing costs and retail pricing architecture.
Market Dynamics
Subscription replenishment models and EU Green Deal textile mandates are compressing traditional seasonal buying cycles while forcing rapid material transitions across supplier bases.
Growth Catalysts
- EU Green Deal textile requirements:Manufacturers pivot toward recycled polyester and certified production processes to maintain wholesale access across European distribution channels.
- Pediatric sun-safety education programs:California and Florida state-level initiatives elevate physician recommendations for UPF-rated garments, expanding functional swimwear penetration.
- Chlorine-resistant fiber bonding:Polyester-elastane composites with four-way stretch recovery extend garment lifespan, justifying premium price points for repeat purchasers.
Market Restraints
- Petrochemical input volatility:Virgin and recycled polyester feedstock costs fluctuate with crude oil indices, compressing margin stability for mid-tier producers.
- Asian manufacturing concentration:Fabric mills and cut-and-sew operations cluster in Guangdong and Zhejiang provinces, creating single-source vulnerability for Western brands.
- Drawstring and flammability compliance:Consumer Product Safety Commission enforcement adds testing overhead and design constraints for children's apparel categories.
Strategic Opportunities
- Size-prediction algorithm deployment:Online platforms reduce fit-risk hesitation through machine learning tools, capturing volume from hesitant first-time buyers.
- Extended producer responsibility frameworks:EU textile waste directives create first-mover advantage for brands with closed-loop take-back infrastructure.
- Year-round aquatic recreation programs:Coastal states with heated indoor facilities generate off-season demand, flattening traditional revenue seasonality.
Industry Challenges
- OEKO-TEX and bluesign certification timelines:Multi-month approval processes delay product launches and strain working capital for seasonal collections.
- Legacy size-grade standardization:Inconsistent pediatric sizing across brands elevates return rates and logistics costs for direct-to-consumer channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Swimwear Market |
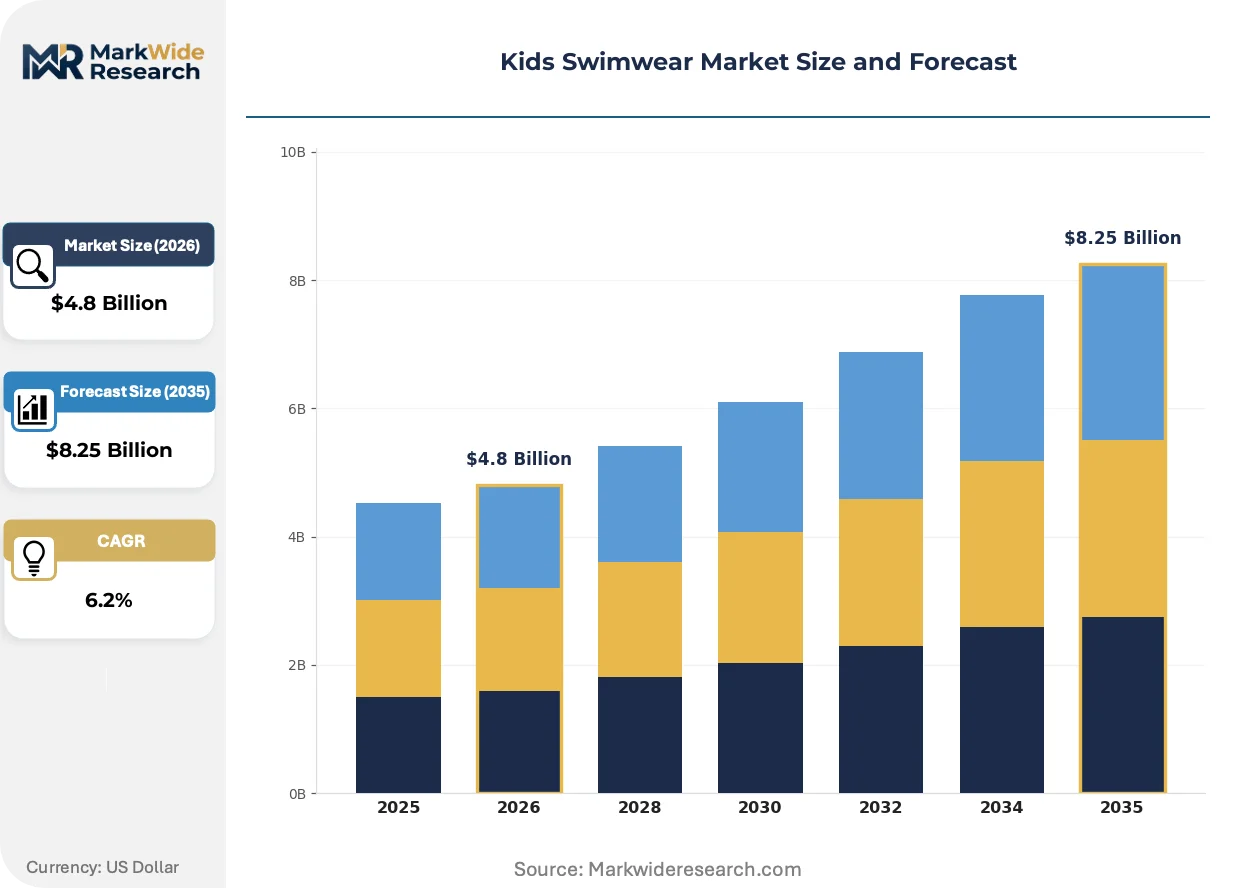
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swimsuits, Rash Guards, Swim Shorts, Cover-Ups Material: Polyester, Nylon, Spandex, Cotton Age Group: Infants, Toddlers, Children, Preteens Distribution Channel: Online Sales, Retail Stores, Specialty Boutiques, Department Stores |
| Companies Covered | Tom & Teddy, Olga Valentine Swimwear, French Soda, Boden Co., Ralph Lauren Corporation, Cheeky Chickadee Store, Milky Clothing, Hanna Andersson, Tyoub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Swimwear Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure mandates are rewiring how swimwear manufacturers formulate fabrics, certify safety, and engage repeat purchasers through digital channels.
UPF-rated textile engineering is converging with nanoscale mineral finishing to block ultraviolet radiation without chemical absorbers. Parents of infants and toddlers prioritize these mineral-based barriers after pediatric dermatologist consultations. This convergence is compressing demand for traditional chemical-based UV treatments that face growing disclosure scrutiny.
REACH chemical restriction updates in Europe now mandate expanded substance-of-very-high-concern screening for textile auxiliaries and dyes. Dye houses serving children's apparel must reformulate coloration chemistry or exit EU supply chains. Swimwear lines with skin-contact surfaces face the most intensive retesting burdens under these protocols.
Seasonal refresh subscriptions now displace one-off purchases for families with multiple children in adjacent size grades. Specialty boutiques and direct-to-consumer platforms capture this switching behavior through automated size progression and flexible exchange policies. California and Florida households with pool access show the highest subscription attachment rates.
Kids Swimwear Market Segmentation
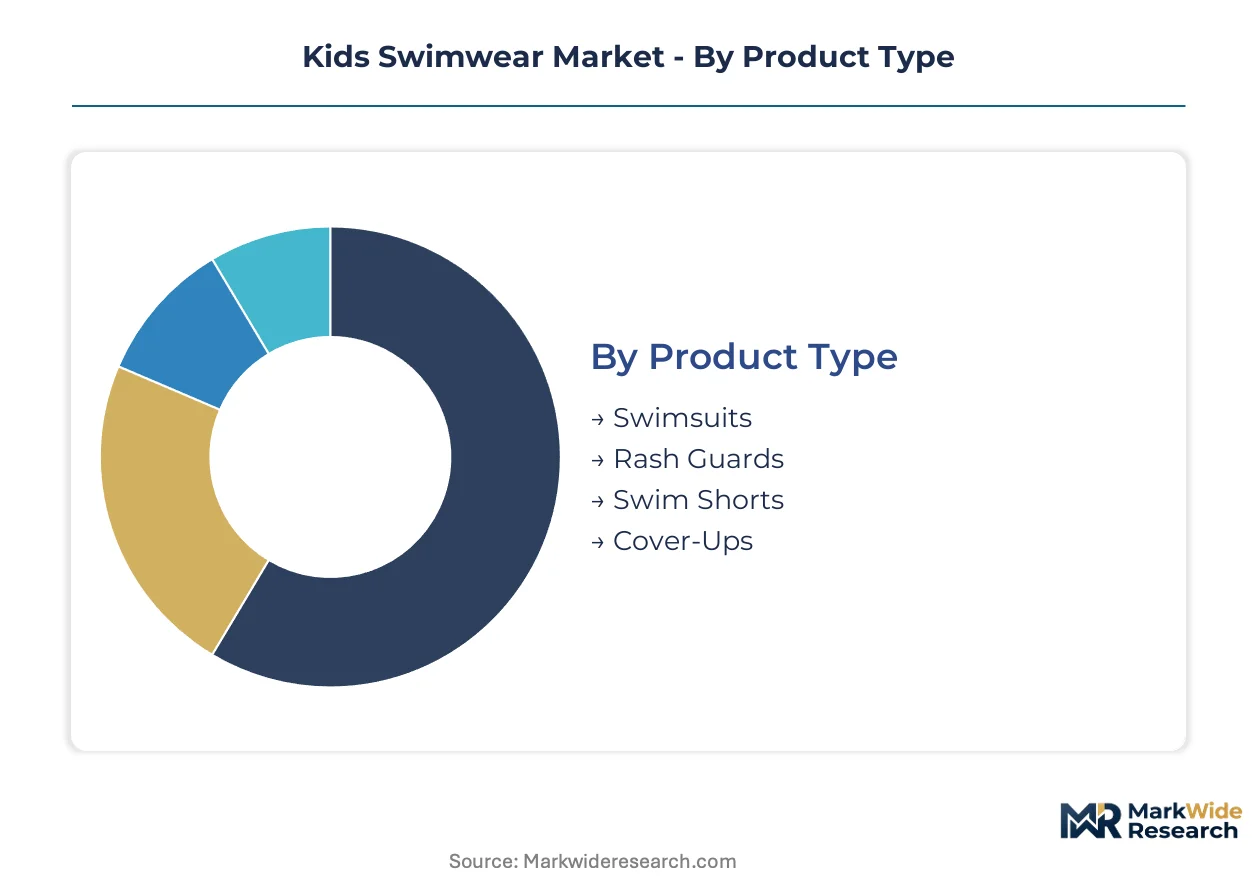
Kids swimwear segmentation reflects how garment function, material performance, and purchase channel intersect with rapid pediatric growth cycles. Manufacturers align production lines to these splits because sizing volatility and seasonal compression reward specialized supply configurations.
Product Type:
Standalone swim garments dominate shelf space, while embedded protective layers gain share through sun-safety positioning.
- Swimsuits:One-piece and two-piece designs engineered with chlorine-resistant polyester-elastane blends for repeated pool exposure. California and Florida households with year-round aquatic programs drive replenishment frequency through rapid size turnover.
- Rash Guards:UPF-rated long-sleeve tops bonded with mineral-based UV barriers rather than chemical absorbers. Pediatric dermatologist recommendations in coastal states elevate demand for full-coverage sun protection over traditional minimal suits.
- Swim Shorts:Quick-dry boardshorts with mesh linings for active water play.
- Cover-Ups:Post-swim transition garments in terry or lightweight woven fabrics.
Volume placements concentrate in Swimsuits; the faster expansion belongs to Rash Guards.
Material:
Cost tier stratification separates performance synthetics from natural fiber alternatives, with recycled feedstocks commanding premium positioning.
- Polyester:Virgin and recycled PET fibers dominate chlorine-resistant construction, with four-way stretch recovery through saltwater and chemical exposure. EU Green Deal textile mandates push manufacturers toward certified recycled streams to maintain wholesale access across European distribution channels.
- Spandex:Elastane content typically ranges 15-20% for shape retention through repeated wear cycles.
- Nylon:Hydrophobic base fabric with superior abrasion resistance for high-activity use.
- Cotton:Organic blends in cover-up and loungewear categories for skin-sensitive infants.
Procurement is shifting toward recycled Polyester; Spandex blends capture the steepest expansion trajectory in performance segments.
Age Group:
Customer type segmentation tracks developmental stages where fit precision and safety features diverge sharply.
- Infants:One-piece suits with snap closures and integrated swim diapers for containment. Parents prioritize OEKO-TEX certified fabrics after pediatrician consultations on skin barrier development.
- Toddlers:Rapid growth velocity drives subscription replenishment models through automated size progression.
- Children:Gendered styling emergence with character licensing and team sport alignment.
- Preteens:Fashion-forward silhouettes approaching adult styling with modesty considerations.
Subscription attachment rates peak among Toddlers; Preteens show the fastest channel shift toward direct-to-consumer platforms.
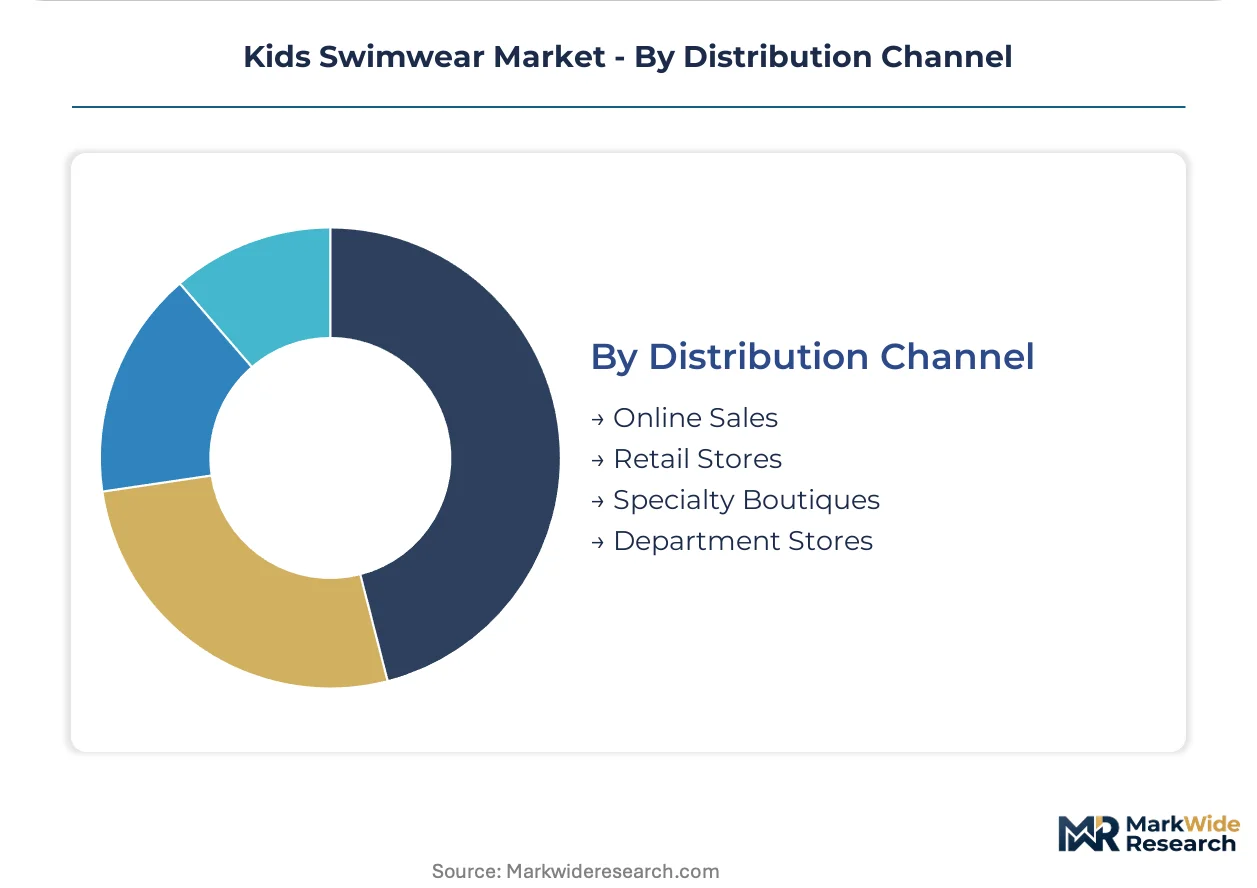
Distribution Channel:
Geography of purchase behavior splits between convenience-driven digital adoption and tactile validation needs for fit-critical categories.
- Online Sales:Machine learning size-prediction algorithms reduce fit-risk hesitation for repeat buyers. Flexible return policies and automated replenishment capture volume from specialty boutiques in California and Florida markets with high pool-access household density.
- Specialty Boutiques:Curated assortments with certified organic and UPF-rated selections for discerning parents.
- Retail Stores:Mass-market volume through seasonal floor sets and impulse purchase placement.
- Department Stores:Legacy channel with shrinking swimwear square footage amid apparel consolidation.
Order concentration sits with Online Sales; Specialty Boutiques are gaining share fastest in premium certified segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangzhou anchors the world's densest concentration of swimwear fabric mills and cut-and-sew operations, supplying Western brands with chlorine-resistant polyester-elastane composites.
United States
California and Florida households with year-round pool access drive the highest subscription attachment rates for automated size progression services. The Consumer Product Safety Commission enforces drawstring and flammability standards that add testing overhead for imported children's apparel. Miami and Los Angeles serve as coastal distribution hubs where specialty boutiques curate UPF-certified assortments for sun-safety-conscious parents.
China
Guangdong and Zhejiang provinces host the dominant share of global swimwear manufacturing capacity, from fiber spinning to finished garment export. The Ministry of Ecology and Environment's dual carbon goals pressure dye houses to reformulate coloration chemistry or lose access to EU-bound production. The Pearl River Delta industrial corridor concentrates polyester recycling infrastructure for brands pivoting toward certified sustainable feedstocks.
Germany
Discerning parents in Bavaria and North Rhine-Westphalia prioritize OEKO-TEX and bluesign certifications when selecting pediatric swimwear from specialty retailers. The EU Green Deal's extended producer responsibility frameworks for textiles mandate closed-loop take-back infrastructure for market access. Hamburg functions as the primary Northern European logistics gateway for Asian-manufactured swimwear entering the continental wholesale network.
Australia
Sydney and Melbourne households with coastal proximity show elevated demand for mineral-based UPF barriers following pediatric dermatologist recommendations. The Therapeutic Goods Administration's oversight of sun-protection claims filters product labeling standards for imported rash guards. Queensland's Gold Coast hosts domestic design studios that specify fabric performance requirements for Asian contract manufacturers.
United Kingdom
London and Southeast England concentrate direct-to-consumer platform headquarters deploying machine learning size-prediction algorithms to reduce fit-risk hesitation. REACH chemical restriction updates mandate expanded substance-of-very-high-concern screening for textile auxiliaries entering EU supply chains. The Midlands region maintains limited cut-and-sew capacity focused on premium organic cotton cover-up categories.
Kids Swimwear Market Key Industry Players
Capital-heavy producers with captive manufacturing compete with asset-light designers sourcing through Asian contract networks. The vendor base splits between vertically integrated textile-to-retail conglomerates and specialized digital-native brands. Three archetypes dominate: heritage luxury houses leveraging resort branding, sustainability-focused specialists with certified supply chains, and direct-to-consumer platforms with algorithmic fit tools. Competitive moves concentrate on geographic diversification of manufacturing bases and portfolio expansion into adjacent sun-protection categories.
Within the heritage luxury tier, Ralph Lauren Corporation occupies a position exemplifying premium resort positioning across poolside collections. Sustainability-focused specialists include Hanna Andersson, which anchors the organic cotton blend segment, and Milky Clothing, representing the UPF-rated functional design archetype. These three entities illustrate how brand positioning around material certification and sun-safety engineering differentiates procurement decisions for discerning parent demographics.
| Leading Market Players |
|---|
| Tom & Teddy |
| Olga Valentine Swimwear |
| French Soda |
| Boden Co. |
| Ralph Lauren Corporation |
| Cheeky Chickadee Store |
| Milky Clothing |
| Hanna Andersson |
| Tyoub |
| Others |
Cost & Logistics Intelligence
Cut-and-sew technician clusters in Guangdong and Zhejiang provinces create labor-cost differentials that widen pricing spreads between premium certified tiers and mass-market alternatives. Recycled polyester feedstock premiums and OEKO-TEX certification overhead compress margins for mid-tier producers while insulating heritage brands with captive sourcing.
Pricing Analysis
UPF-rated performance outcomes anchor value-based pricing for mineral-barrier rash guards recommended by pediatric dermatologists. Three-tier pricing structure across premium certified, standard performance, and economy basic levels stratifies by OEKO-TEX tier and chlorine-resistance grade. Cost compression in economy tiers intensifies because virgin polyester feedstock tracks crude oil volatility. Mass-market retail buyers show highest price sensitivity; subscription-based parents of toddlers in California and Florida exhibit lowest.
Supply Chain Analysis
Workforce availability for bonded seam technicians concentrates in China's Pearl River Delta, Vietnam's Ho Chi Minh City corridor, and Bangladesh's Dhaka industrial zone. Fabric mills draw from virgin PET, recycled ocean plastic, and elastane feedstocks. Single-source vulnerability runs through Guangdong province's dye house concentration for EU-bound certified production. Distribution runs through Hamburg and Los Angeles as primary wholesale gateways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kids swimwear sits in a materials-transition phase as mineral-based UPF barriers displace legacy chemical UV absorbers facing REACH disclosure scrutiny. Stakeholders must position around certified feedstock access and algorithmic fit tools.
For Market Incumbents: To counter subscription-platform disintermediation, backward integration into recycled polyester spinning secures certified feedstock access under EU Green Deal mandates. Channel control through owned direct-to-consumer platforms with size-prediction algorithms retains high-lifetime-value households. For New Entrants and Emerging Players: Direct-to-consumer marketplace routes offer lowest customer acquisition cost entry for UPF-certified toddler segments with highest replenishment frequency. White-space sits with preteen modest-fashion lines and year-round aquatic program states. For Investors and Strategic Acquirers: Re-rating potential sits with sustainability-focused specialists given EU extended producer responsibility catalysts accelerating take-back infrastructure requirements. Long-term viability favors vertically integrated textile-to-retail archetypes with certified supply chains. Watch California and Florida pediatric sun-safety program expansion as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Feedstock Certification | EU Green Deal textile mandates force rapid supplier base transition to maintain wholesale access. |
| Size-Prediction Algorithm Deployment | Machine learning fit tools reduce return rates and capture subscription volume from hesitant first-time buyers. |
| Closed-Loop Take-Back Infrastructure | Extended producer responsibility frameworks create first-mover advantage in European distribution channels. |
| Mineral-Based UPF Barrier R&D | Pediatric dermatologist recommendations elevate demand for chemical-free sun protection over legacy absorbers. |
| Direct-to-Consumer Platform Launch | Automated replenishment and flexible returns capture volume from specialty boutiques in high pool-access markets. |
Research Approach
Trade databases, customs records, and SEC apparel sector filings formed the secondary backbone for supply chain mapping and pricing tier analysis. Primary interviews with brand sourcing directors, specialty boutique buyers, dye house technical managers, and pediatric dermatologists validated material transition timelines and certification burden estimates. Bottom-up unit economics and top-down retail audit data triangulated volume and value estimates.
Historical trendline analysis of seasonal replenishment patterns and subscription attachment rates informed the projection framework. Segmentation dimensions modeled include product type, material certification tier, age group developmental stage, and distribution channel format. CAGRs derived from fitted growth curves applied to pediatric population cohorts and aquatic program penetration rates across coastal states.
The model holds under stable EU regulatory implementation timelines; deviation in REACH enforcement intensity or recycled feedstock cost spikes would shift manufacturer margin structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO