
 Table Top Games Market | 2026-2036
Table Top Games Market Size, Share, and Industry Trends Forecast 2026-2036
Table Top Games Market Analysis
Sustainable bioplastics derived from cornstarch and recycled wood fibers is restructuring cost structures across mid-tier and premium product lines. Ravensburger AG leverages its vertically integrated European manufacturing footprint to control quality and margin on complex puzzle and board game assemblies. Hasbro Inc. sustains mass-market dominance through licensed IP tie-ins and direct-to-retailer distribution scale. CMON Limited specializes in high-detail miniatures production, competing on paint-ready sculpt quality and Kickstarter-backed release cycles.
Table top games encompass analog recreational products played on flat surfaces, typically incorporating printed boards, cards, dice, tokens, or sculpted miniatures with rule systems governing competitive or cooperative outcomes. Card stock weight measured in grams per square meter, miniature resin composition, and offset lithography color fidelity define production-grade specifications for commercial viability. Board games and card games occupy the largest revenue pools, with established replacement cycles and family-oriented gifting sustaining volume. Role-playing games represent the fastest-expanding category, driven by digital-native player migration toward tactile social experiences and live-streamed actual play content.
The US Consumer Product Safety Commission enforces ASTM F963 toy safety standards, while the EU Toy Safety Directive and REACH regulate chemical content and mechanical hazards in components sold across member states. These frameworks elevate compliance costs for small publishers but also create market access barriers that favor scaled manufacturers with dedicated testing protocols. Stakeholders must monitor evolving extended producer responsibility mandates in the European Union and shifting state-level chemical disclosure laws in California as determinants of material strategy and geographic market prioritization.
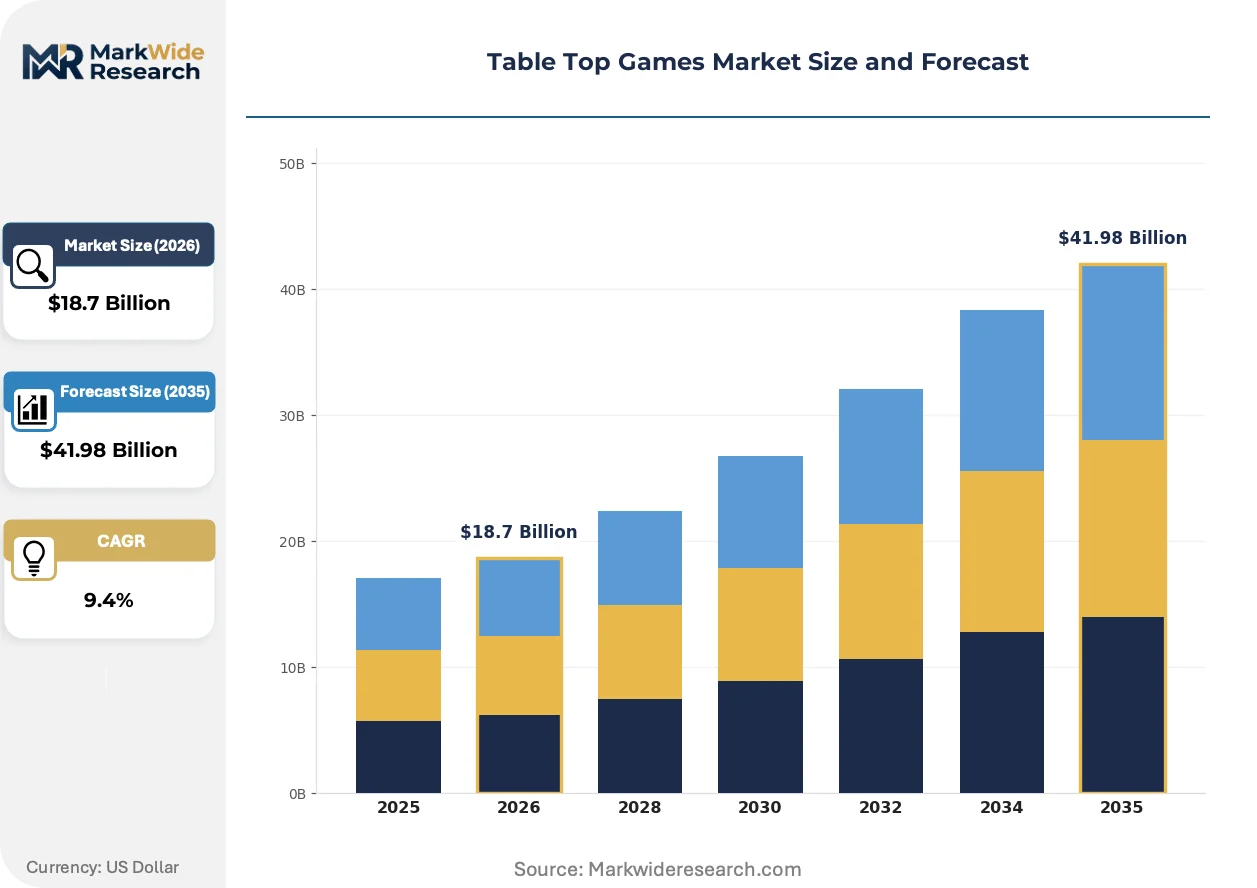
Market Dynamics
Live-streamed actual play content on Twitch and YouTube is converting digital-native audiences into tactile product purchasers, compressing traditional marketing cycles and reshaping how publishers build pre-launch demand for complex miniature and narrative-driven releases.
Growth Catalysts
- Hobby Game Café Proliferation:Social entertainment venues across the United States, Canada, and the United Kingdom are installing retail libraries and event spaces that introduce casual consumers to premium board game experiences.
- REACH Phthalate Restrictions:The EU's chemical compliance framework is accelerating material innovation toward bio-based alternatives, creating differentiation opportunities for early-adopting manufacturers.
- Role-Playing Game Resurgence:Tactile social experiences are pulling video game players into analog formats, expanding the addressable audience beyond traditional family gifting occasions.
Market Restraints
- Resin Supply Concentration:Miniature-grade polyurethane and epoxy resin production clusters in East Asia, exposing premium publishers to shipping cost volatility and tariff exposure.
- ASTM F963 Compliance Burden:The US Consumer Product Safety Commission's toy safety testing protocols impose fixed costs that disproportionately constrain small-batch independent publishers.
- Digital Substitution Pressure:Tabletop Simulator and other virtual tabletop platforms offer zero-marginal-cost alternatives for geographically dispersed player groups.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:The EU Green Deal's packaging waste mandates are creating first-mover advantage for publishers with closed-loop recycling programs and plastic-free component strategies.
- India Market Underpenetration:English-language role-playing game content remains largely unavailable through organized retail channels in Indian metropolitan centers.
- AI-Assisted Narrative Tools:Large language model integration with campaign management software is converging with physical book sales to create hybrid digital-physical subscription offerings.
Industry Challenges
- Sculptor Talent Scarcity:Paint-ready miniature design requires specialized digital sculpting skills in ZBrush and traditional casting knowledge that outpaces vocational training pipeline output.
- Kickstarter Fulfillment Complexity:Crowdfunding-backed release cycles demand precise logistics coordination across ocean freight, customs brokerage, and regional distribution partnerships.
- Licensed IP Contract Negotiation:Major entertainment franchises impose strict approval timelines and minimum volume guarantees that strain working capital for mid-tier publishers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Table Top Games Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Board Games, Card Games, Miniatures, Role-Playing Games Target Audience: Adults, Families, Children, Strategy Gamers Distribution Channel: Online Retailers, Specialty Stores, Mass Merchants, Conventions Theme: Fantasy, Sci-Fi, Historical, Horror |
| Companies Covered | Ravensburger AG, Buffalo Games, Asmodee, Grand Prix International, CMON Limited, Hasbro Inc., Goliath Games, Lifestyle Boardgames Ltd., Mattel Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Table Top Games Market Emerging Trajectories
Material science breakthroughs and regulatory pressure are converging to transform how components are sourced, certified, and positioned in the market. Publishers are rethinking supply chain architecture in response.
Bioplastic formulations derived from cornstarch and mycelium substrates are decentralizing raw material sourcing away from petroleum-dependent supply chains. Mid-tier publishers in Germany and the Netherlands are adopting these alternatives to satisfy retailer sustainability scorecards. The shift is compressing cost advantages for vertically integrated manufacturers with legacy plastic molding infrastructure.
REACH compliance deadlines for restricted substance lists are forcing reformulation of card stock coatings and miniature resin systems across EU-bound product lines. Manufacturers are consolidating testing protocols with accredited laboratories in France and Germany to reduce certification cycle times. Premium puzzle and children's game categories face the steepest compliance cost escalation.
Direct-to-consumer pre-order campaigns are displacing traditional distributor-led allocation models for complex narrative and miniature-heavy releases. Established publishers are building proprietary e-commerce fulfillment operations in Texas and Pennsylvania to capture margin and customer data. This channel migration is most visible in the United States, where backer fatigue has intensified competition for crowdfunding visibility.
Table Top Games Market Segmentation
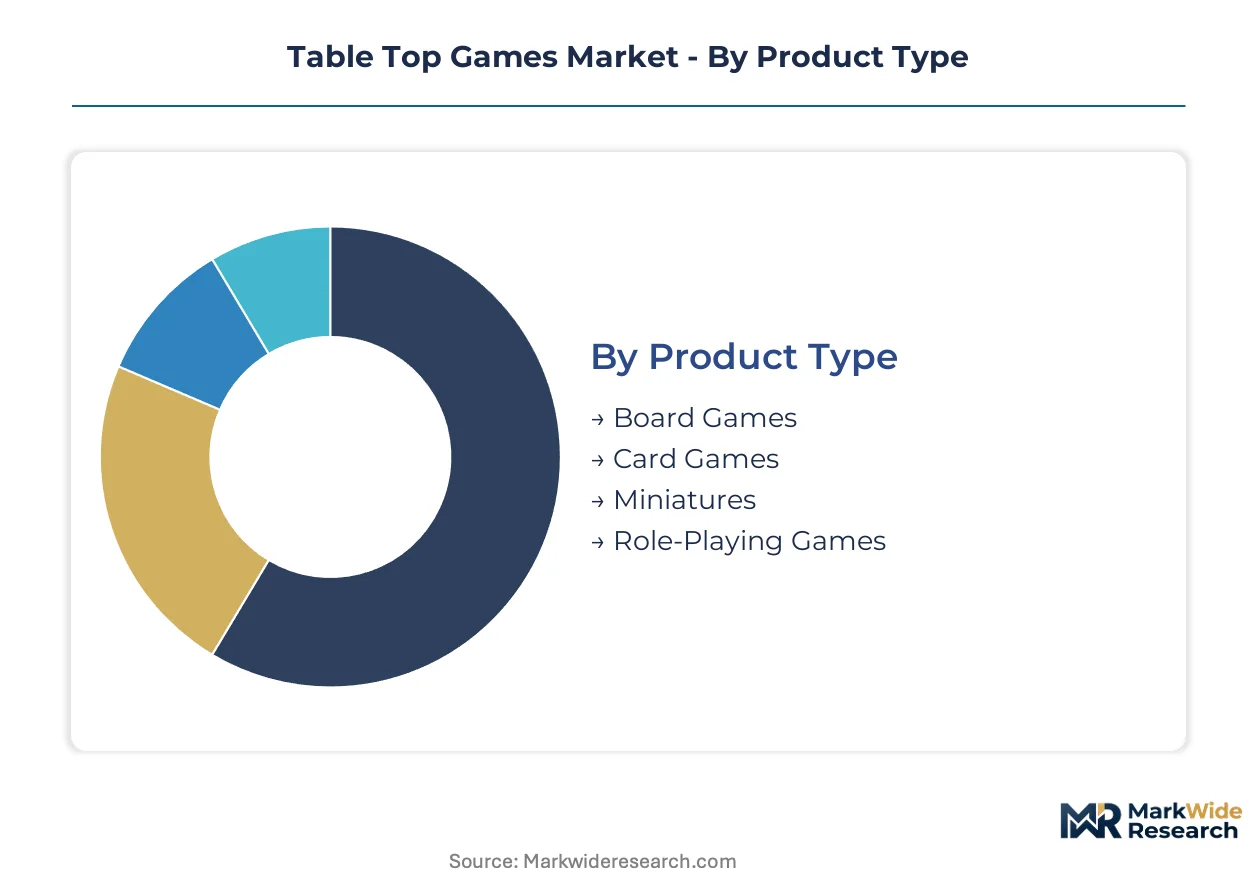
Product differentiation in table top games hinges on component complexity, session duration, and social mechanics rather than price alone. Publishers calibrate material specifications and rule depth to distinct buyer profiles across four intersecting dimensions.
Product Type:
Buyers in this category select based on cognitive load tolerance, component durability expectations, and social group size preferences.
- Board Games:Printed boards, tokens, and dice assemblies dominate family gifting and casual social occasions. German and US hobby cafés stock extensive libraries, with replacement cycles tied to holiday seasons and social entertainment venue openings.
- Card Games:Compact 52- to 300-card decks with minimal packaging suit travel and quick-session play. Strategy gamers in metropolitan US and UK markets sustain demand for expandable living-card-game formats with regular content releases.
- Miniatures:Paint-ready resin or plastic sculpts requiring assembly and customization attract dedicated hobbyists. East Asian resin supply concentration exposes publishers to freight volatility and tariff uncertainty.
- Role-Playing Games:Rulebooks, character sheets, and narrative supplements enable collaborative storytelling campaigns. Digital-native players migrating from video games are expanding the addressable audience beyond traditional tabletop enthusiasts.
Board games lead volumes today; role-playing games are gaining share fastest.
Target Audience:
Purchase frequency and price elasticity vary sharply across life stage and engagement depth.
- Adults:Discretionary spending on complex strategy titles and premium miniatures with 90-180 minute playtimes. Hobby game cafés in Toronto and Austin target this cohort with event programming and retail integration.
- Families:Cooperative mechanics and 30-60 minute sessions drive repeat purchases for household entertainment. REACH phthalate compliance elevates material costs for children's adjacent product lines.
- Children:Durability and safety certification priorities shape component selection, with ASTM F963 testing protocols filtering small publishers from mass retail placement.
- Strategy Gamers:Rules-heavy euro-style designs with minimal luck elements command premium pricing and direct-to-consumer pre-order campaigns.
Families anchor volume today; strategy gamers show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture, customer data ownership, and geographic reach.
- Online Retailers:Amazon and specialized platforms aggregate long-tail inventory with review-driven discovery. Publishers building proprietary e-commerce operations in Texas and Pennsylvania bypass platform fees.
- Specialty Stores:Curated selection and staff expertise sustain premium pricing for complex releases. Independent retailers in Berlin and Chicago function as community hubs with organized play events.
- Mass Merchants:Target and Walmart placements require volume guarantees and simplified packaging, favoring scaled manufacturers with licensed IP portfolios.
- Conventions:Gen Con and Spiel Essen generate concentrated pre-orders and direct fan feedback for narrative-heavy and miniature-driven titles.
Online retailers dominate transaction volume; specialty stores are climbing fastest in margin contribution.
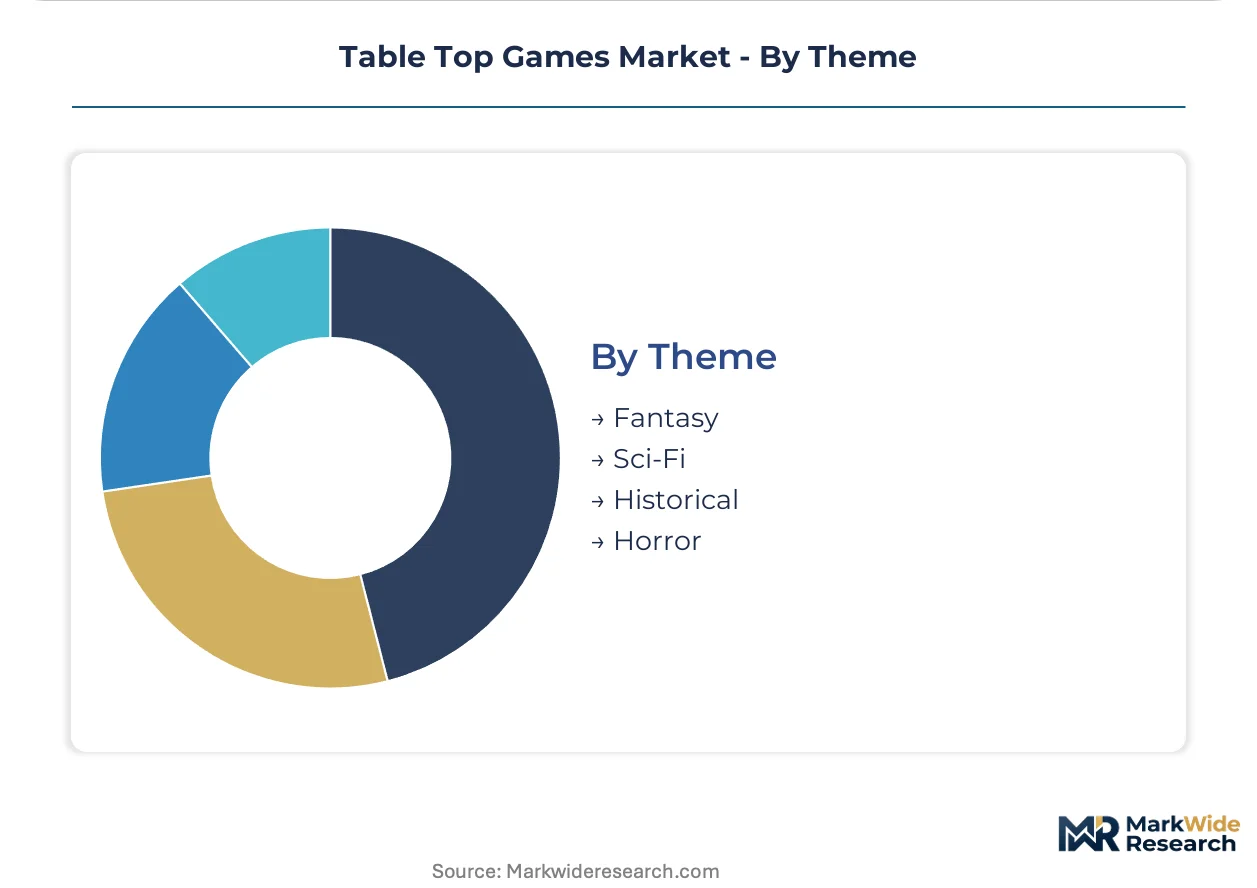
Theme:
Intellectual property licensing costs and artist talent availability differentiate competitive positioning.
- Fantasy:Established tropes in medieval magic settings reduce creative risk and enable modular expansion content. Dungeons & Dragons and adjacent properties sustain the largest dedicated player base.
- Sci-Fi:Space opera and cyberpunk aesthetics attract miniature painters seeking distinctive visual palettes. High-detail sculpt requirements strain sculptor talent pipelines.
- Historical:Accuracy demands and public domain source material limit licensing overhead. Wargaming communities in the UK and Germany sustain niche but loyal demand.
- Horror:Atmospheric art direction and narrative tension mechanics suit live-streamed actual play content conversion. Call of Cthulhu and indie successors capitalize on streaming platform visibility.
Fantasy commands the largest installed base; horror themes are expanding most quickly through streaming-driven discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Essen's Spiel convention campus anchors continental distribution networks for German-language board game exports. Domestic cafés in Berlin and Hamburg sustain community-driven demand through organized play infrastructure. Regulatory pressure from Brussels accelerates material transitions across the Rhine manufacturing corridor.
United States
Hobby game cafés in Austin, Toronto satellite markets, and Pacific Northwest metros convert casual visitors into premium purchasers. ASTM F963 toy safety protocols filter small publishers from mass retail placement at Target and Walmart. Texas and Pennsylvania host proprietary e-commerce fulfillment hubs serving direct-to-consumer pre-order campaigns.
Germany
Entrenched board game culture sustains replacement cycles tied to holiday gifting and social entertainment venue openings. REACH phthalate restrictions force reformulation of card stock coatings and miniature resin systems for EU-bound lines. Ravensburger AG leverages vertically integrated manufacturing across the Ravensburg region to control quality on complex puzzle assemblies.
United Kingdom
Independent retailers in London and Manchester function as community hubs with curated selection and staff expertise. The UKCA marking transition post-Brexit imposes parallel testing burdens alongside retained EU Toy Safety Directive requirements. Edinburgh and Glasgow hobby scenes sustain demand for narrative-heavy role-playing game releases through convention programming.
China
Miniature-grade polyurethane and epoxy resin production clusters in Guangdong and Zhejiang expose premium publishers to freight volatility and tariff exposure. SAMR toy safety standards and GB compliance frameworks govern domestic market access. Shenzhen and Dongguan mold-making infrastructure supports paint-ready sculpt output for Kickstarter-backed release cycles.
India
English-language role-playing game content remains largely unavailable through organized retail channels in Mumbai and Bangalore metropolitan centers. BIS toy safety certification creates market access barriers for imported premium lines. Delhi-NCR and Hyderabad hobby communities drive parallel import demand through online aggregator platforms.
Table Top Games Market Vendor Landscape
Backward integration into captive resin sourcing and in-house sculpting capacity dominates the current landscape for premium miniature publishers. The vendor base separates into three distinct tiers: mass-market licensors with entertainment IP portfolios, mid-cap specialists with vertically controlled European manufacturing, and crowdfunding-native studios with direct fan relationships. Consolidation pressure concentrates among scaled manufacturers seeking testing protocol efficiencies under REACH and ASTM frameworks. Geographic expansion into underpenetrated Indian and Southeast Asian markets represents the second dominant competitive vector.
Among German-based publishers, Ravensburger AG exemplifies the integrated manufacturing archetype with European production footprint control. Hasbro Inc. and Mattel Inc. occupy positions within the mass-market licensor tier, leveraging entertainment franchise relationships and retailer scale guarantees. CMON Limited represents the crowdfunding-native specialist model with Kickstarter-backed release cycles and paint-ready miniature focus.
| Leading Market Players |
|---|
| Ravensburger AG |
| Buffalo Games |
| Asmodee |
| Grand Prix International |
| CMON Limited |
| Hasbro Inc. |
| Goliath Games |
| Lifestyle Boardgames Ltd. |
| Mattel Inc. |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's packaging waste mandates are gating qualified supply access and premium-tier pricing power for table top game publishers, forcing material certification investments that separate compliant from non-compliant tier positioning.
Pricing Analysis
Resin and card stock cost pass-through from East Asian suppliers is compressing margins for miniature-heavy and premium puzzle lines. Three-tier pricing structure across premium, standard, and economy levels differentiates on REACH compliance certification and paint-ready sculpt quality. Pricing pressure stems from bioplastic reformulation costs and extended producer responsibility fees. Families show highest price sensitivity on mass-market titles; strategy gamers accept premium positioning for complex euro-style releases.
Supply Chain Analysis
Ocean freight rate volatility from Guangdong and Zhejiang resin clusters is reshaping landed cost calculations for Kickstarter-backed miniature releases. Raw material sourcing draws from Chinese polyurethane production, German card stock mills, and Dutch bioplastic innovators. Single-source vulnerability concentrates in East Asian mold-making infrastructure. Distribution runs through direct-to-consumer pre-order platforms, specialty retailer networks, and mass merchant allocation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
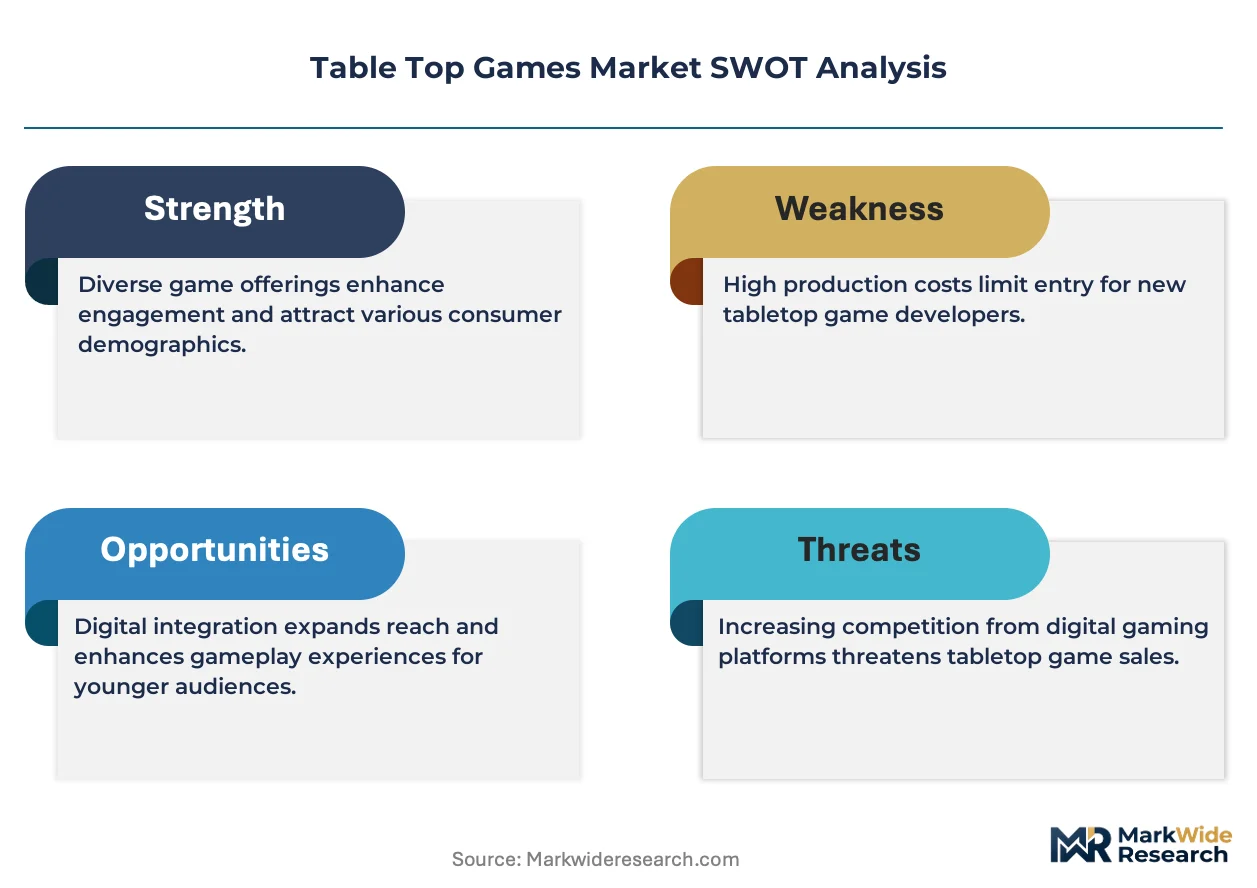
This market reads as a late-cycle quality story, with demand shifting toward REACH-certified bioplastic components and paint-ready miniature specifications that justify premium positioning.
For Market Incumbents: Hedge against resin supply concentration by diversifying sourcing partnerships across German bioplastic suppliers and captive mold-making capacity in Eastern Europe. Digital tabletop substitution threats demand accelerated investment in tactile component differentiation and live-streamed actual play content partnerships.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium Kickstarter releases and mass-market licensed titles offers white-space entry through narrative-heavy role-playing game supplements. Target English-language organized retail gaps in Indian metropolitan centers. Pursue direct-to-consumer pre-order campaigns with AI-assisted campaign management tools.
For Investors and Strategic Acquirers: Valuations sit cheapest among crowdfunding-native studios with established fan relationships but limited fulfillment infrastructure. Long-term viability hinges on backward integration into resin sourcing and proprietary e-commerce operations. Monitor REACH compliance deadline acceleration as inflection signal for material strategy winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioplastic Component Transition | REACH compliance deadlines in Germany and Netherlands favor early adopting publishers with certified supply chains. |
| Direct-to-Consumer Fulfillment Buildout | Texas and Pennsylvania hub investments capture margin from Amazon-dependent discovery models. |
| AI-Assisted Narrative Tool Integration | Large language model deployment in campaign software creates hybrid subscription revenue streams. |
| Indian Market Organized Retail Entry | Mumbai and Bangalore distribution partnerships address underpenetrated English-language role-playing game demand. |
| In-House Sculpting Capacity Expansion | ZBrush talent pipelines in Shenzhen and Dongguan reduce dependency on freelance sculptor scarcity. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with game publishers, hobby café operators, specialty retailers, and logistics coordinators alongside secondary validation from customs records, toy safety certification databases, and crowdfunding platform disclosures. Bottom-up assembly of publisher shipment data triangulates against top-down retail audit estimates from Nielsen and Circana.
Granularity-level modeling disaggregates volume and value across product type, target audience, distribution channel, and regional regulatory cluster throughout the forecast period. CAGRs derive from segment-level growth trajectory analysis incorporating Kickstarter backer conversion rates, hobby café expansion pipelines, and REACH compliance cost pass-through assumptions.
Caveats apply where bioplastic raw material availability or extended producer responsibility mandate acceleration could materially shift the outlook. Forecasts reflect assumptions about resin supply chain stability and streaming platform content conversion efficiency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Board Games and Puzzles Market
Toys and Games
Blind Box Toys Market
Toys and Games
Action Figures Market
Toys and Games
Arcade Games Machine Market
Toys and Games
Air Hockey Table Market
Toys and Games
Indoor Soft Play Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Coaster Market
Toys and Games
Claw Machine Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Global Blind Boxes Market
Toys and Games
Australia Toys and Games Market
Toys and Games
Bounce House Market