
 Winery Management Software Market | 2026-2036
Winery Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Winery Management Software Market Analysis
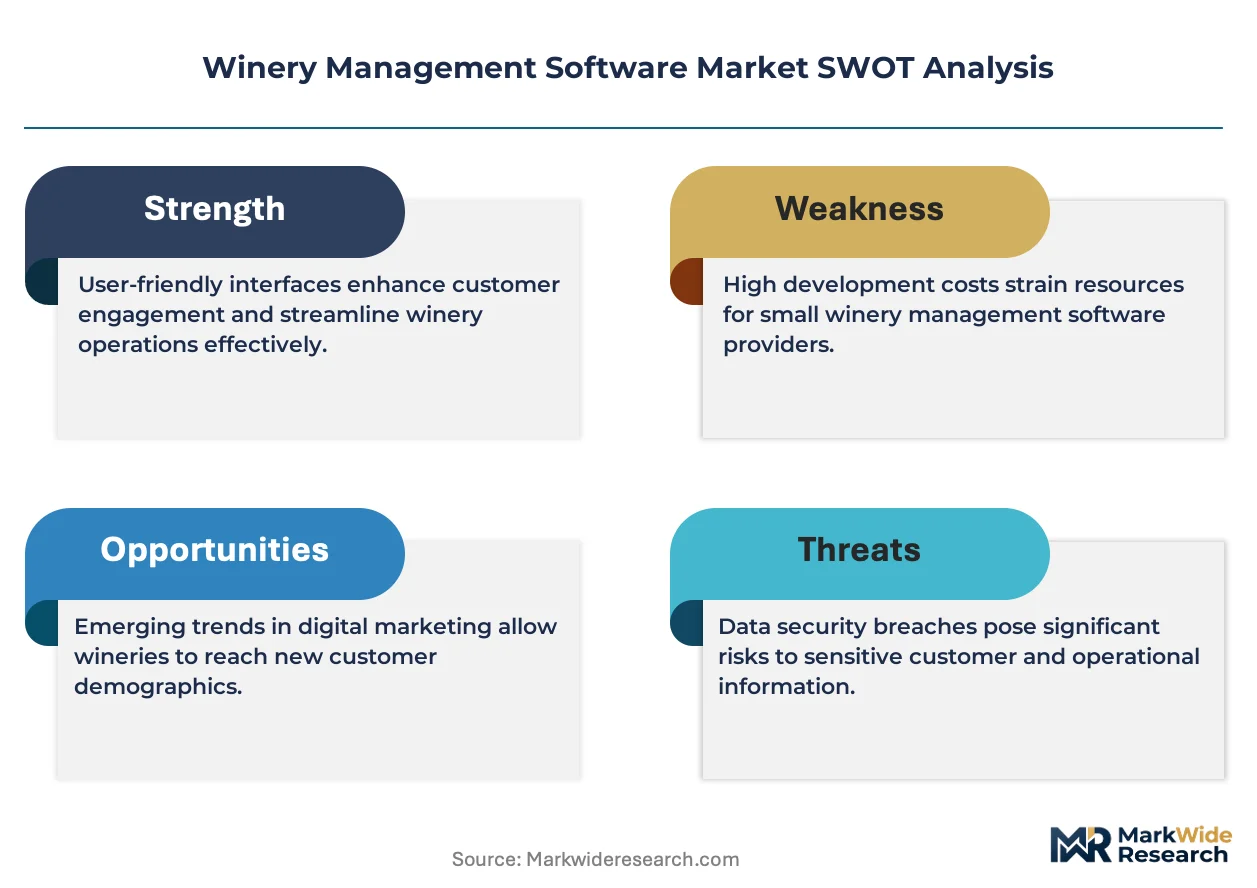
Modular bundling of CRM, inventory, and compliance tools is consolidating buyer preference toward unified platforms rather than point solutions. Ekos leverages its vertical focus on beverage production workflows to anchor mid-market winery adoption. Commerce7 competes through direct-to-consumer specialization, particularly in subscription and club management. Vintrace differentiates with harvest and cellar tracking depth that sustains loyalty among premium producers in Australia and North America.
Winery management software denotes integrated digital platforms that coordinate viticulture operations, fermentation monitoring, inventory tracking, sales fulfillment, and regulatory reporting through centralized databases with API connectivity to laboratory equipment and accounting systems. These systems serve the commercial purpose of reducing manual data entry, ensuring traceability from grape intake to bottle shipment, and enabling data-driven blending and pricing decisions. Cloud-based deployment leads in new installations because it eliminates server maintenance and enables remote access for vineyard managers, though on-premises retention persists among large estates with legacy ERP integration requirements. CRM software captures disproportionate attention as wineries prioritize direct-to-consumer revenue streams and tasting room personalization.
The Alcohol and Tobacco Tax and Trade Bureau mandates detailed production, storage, and transfer records that shape software requirements for American wineries. FDA Food Safety Modernization Act traceability rules and EU REACH compliance for packaging materials further condition feature roadmaps for vendors serving export-oriented producers. Stakeholders must monitor how evolving excise tax structures and emerging state-level sustainability disclosure rules reshape platform prioritization between compliance automation and consumer-facing transparency tools.
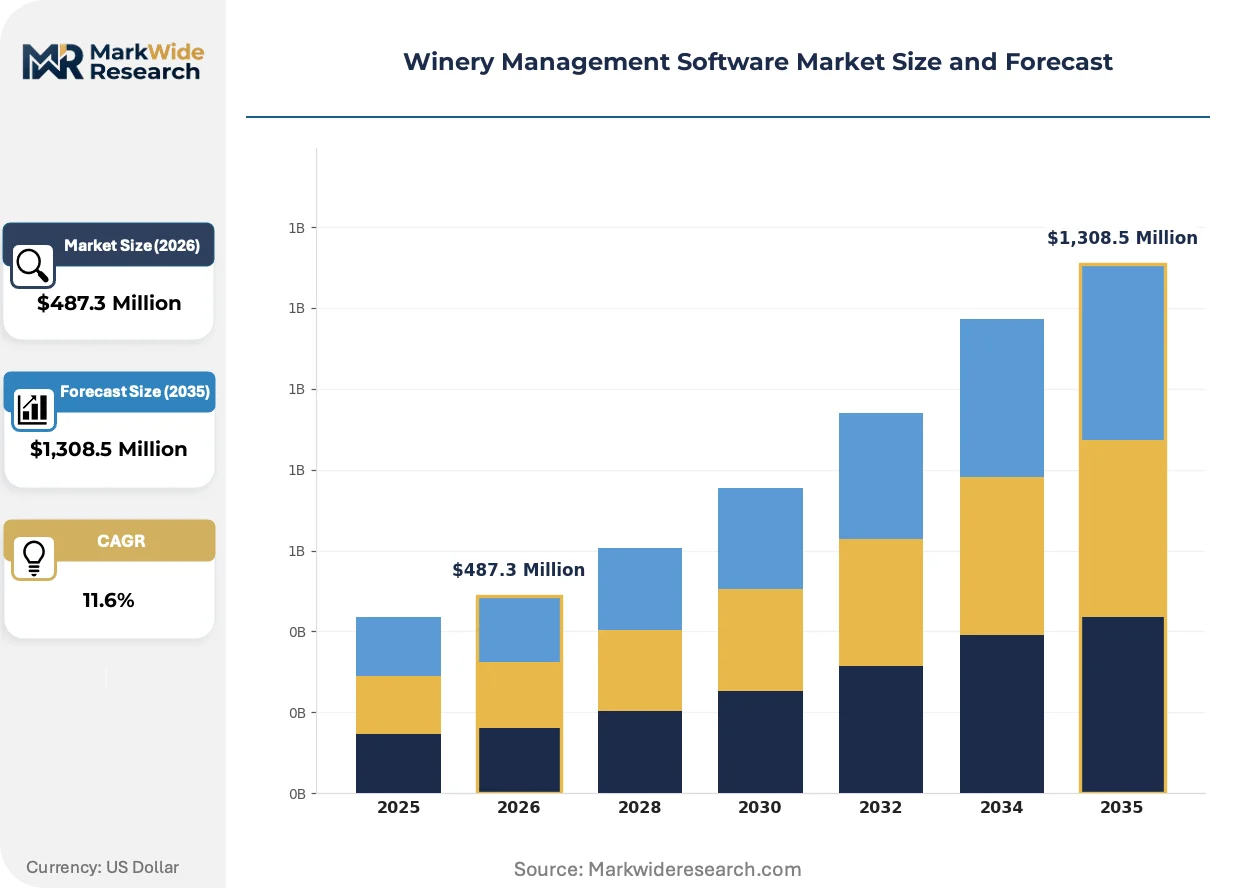
Market Dynamics
Cloud-native architectures are compressing replacement cycles as boutique producers abandon legacy on-premises systems that cannot support remote vineyard monitoring or real-time compliance dashboards.
Growth Catalysts
- TTB Record-Keeping Mandates:The Alcohol and Tobacco Tax and Trade Bureau's detailed production and transfer documentation requirements force wineries to automate reporting workflows, accelerating software procurement across American operations.
- Direct-to-Consumer Channel Expansion:Wine clubs and tasting room personalization tools now require unified CRM and inventory layers that point solutions cannot deliver, pulling mid-market buyers toward integrated platforms.
- API-Connected Laboratory Equipment:Fermentation monitoring sensors and titration devices with standardized data feeds eliminate manual cellar logging, reducing labor costs for premium producers.
Market Restraints
- Legacy ERP Integration Complexity:Large estates with decades-old accounting and inventory systems face prohibitive migration costs when connecting modern vineyard management tools to entrenched financial databases.
- Broadband Infrastructure Gaps:Rural vineyard locations in eastern Washington and southern Oregon lack reliable connectivity for real-time cloud synchronization, limiting deployment options.
- Cybersecurity Insurance Requirements:Underwriters increasingly demand SOC 2 certification from software vendors, filtering smaller providers from competitive bidding for enterprise contracts.
Strategic Opportunities
- Sustainability Disclosure Rules:Emerging state-level carbon accounting mandates for agricultural operations create demand for embedded emissions tracking modules that current platforms lack.
- Blockchain Provenance Verification:Converging distributed ledger technology with harvest-to-bottle databases enables premium producers to command price premiums through transparent supply chain storytelling.
- Mobile-First Field Operations:Native smartphone applications for irrigation scheduling and pest scouting capture adoption among younger vineyard managers who reject tablet-based legacy interfaces.
Industry Challenges
- Viticulture-Technology Skill Gap:Experienced winemakers lack data literacy for interpreting predictive analytics outputs, forcing vendors to invest in change management services that compress margins.
- Multi-Jurisdiction Compliance Stacking:Export-oriented producers must simultaneously satisfy FDA Food Safety Modernization Act traceability rules, EU REACH packaging requirements, and destination-country labeling laws within single workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winery Management Software Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRM Software, Inventory Management, Accounting Software, POS Systems Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions End User: Wineries, Vineyards, Distributors, Retailers Feature: Harvest Management, Tasting Room Management, Compliance Monitoring, Reporting Tools |
| Companies Covered | Rockit Systems, Commerce7, Vintrace, InnoVint, 360Winery, Ekos, WineDirect, The Wine Club, Vint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winery Management Software Market Emerging Trajectories
Artificial intelligence is embedding into core production decisions, shifting competitive advantage from historical intuition to predictive modeling across fermentation, blending, and pricing workflows.
Machine learning-based yield forecasting is overtaking manual cluster counting and sugar sampling as the dominant pre-harvest planning methodology. Premium producers in Napa and Sonoma counties now deploy computer vision drones that feed convolutional neural networks trained on vintage-specific canopy development patterns. This compression of prediction error rates is enabling forward-contracting strategies that lock in grape pricing before veraison completes.
The FDA Food Safety Modernization Act Section 204 traceability mandate is reshaping data architecture requirements for American wineries shipping to retail chains. Lot code granularity must now extend to individual vineyard blocks with two-hour response windows for contamination tracing. Mid-sized producers are responding by prioritizing platforms with pre-built FDA compliance templates over customizable but labor-intensive alternatives.
Subscription-based software licensing is displacing perpetual purchase models among emerging wineries with constrained capital reserves. Monthly per-user fees align vendor incentives with customer success metrics, reducing upfront implementation friction. This shift is most visible in Oregon's Willamette Valley incubator programs, where angel-funded startups prioritize operational flexibility over long-term total cost optimization.
Winery Management Software Market Segmentation
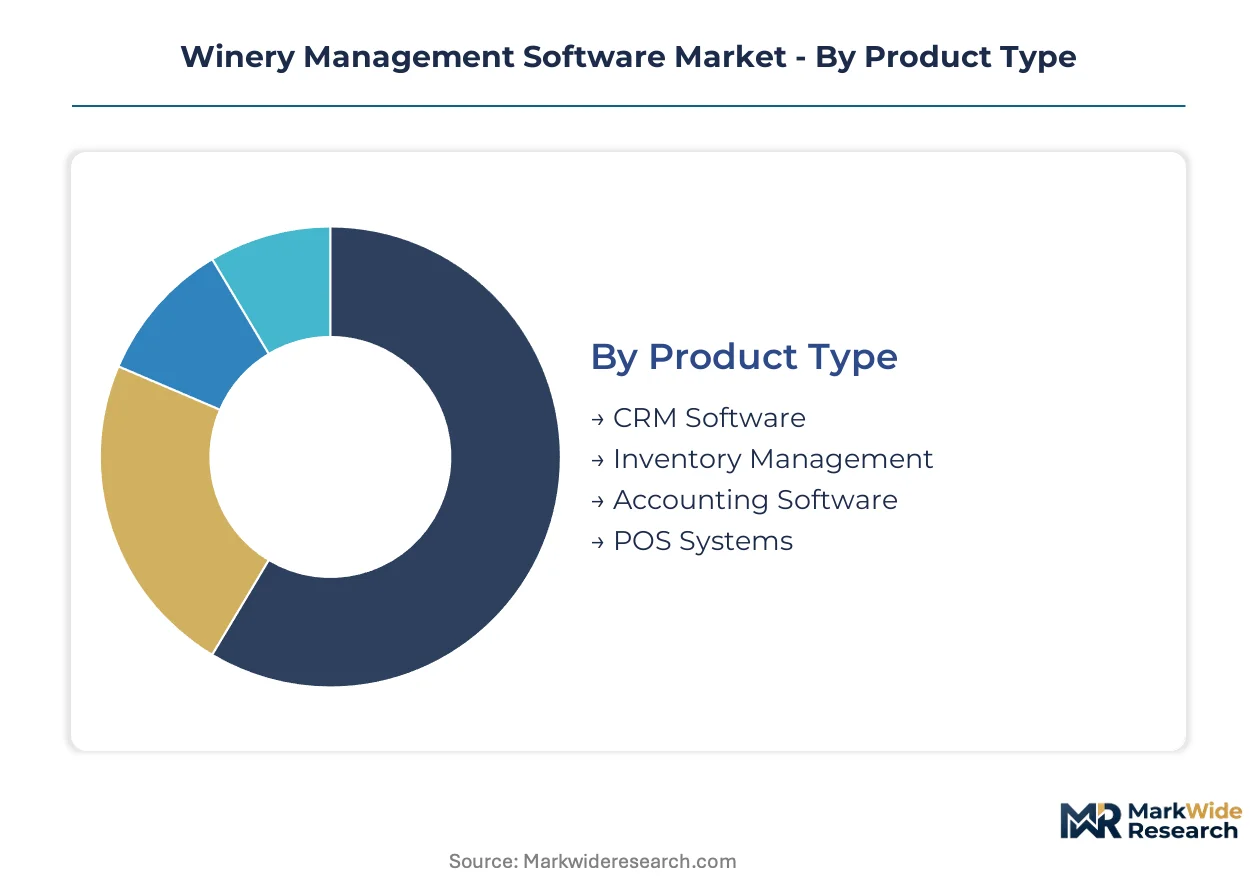
Winery management software segments reflect divergent buyer priorities across production scale and channel strategy. Deployment choices separate capital-constrained startups from established estates with legacy infrastructure investments. Feature selection reveals whether buyers optimize for cellar operations or consumer-facing revenue capture.
Product Type:
Buyers select modules based on which operational bottleneck consumes the most labor hours or regulatory risk.
- CRM Software:Unified customer databases integrate tasting room visits, wine club subscriptions, and e-commerce transactions into single profiles. Demand concentrates among direct-to-consumer wineries in California's Napa and Sonoma counties, where personalized outreach drives repeat purchase rates. TTB compliance requirements for customer record retention accelerate replacement of spreadsheet-based contact management.
- Inventory Management:Lot-level tracking from grape intake through bottle shipment enables traceability mandates and optimizes warehouse space utilization. Large estates in Washington's Columbia Valley prioritize this module to coordinate multi-vintage blending programs across distributed cellar facilities. Real-time depletion alerts prevent stockouts during peak tasting room seasons.
- Accounting Software:General ledger integration with production cost allocation satisfies winery-specific tax reporting requirements. Oregon's boutique producers favor cloud-native solutions that automate excise tax calculations without dedicated accounting staff.
- POS Systems:Tablet-based tasting room checkout with integrated inventory deduction streamlines high-volume weekend operations. Mobile card readers with offline sync capability address connectivity gaps in rural vineyard locations.
Inventory management leads on scale; CRM software leads on momentum.
Deployment:
Connectivity infrastructure and IT staffing levels dictate architecture selection across vineyard geographies.
- On-Premises:Server installations within winery facilities maintain data sovereignty and integrate with legacy ERP systems. Large family-owned estates in France's Bordeaux region retain this model to preserve decades of historical production data without cloud migration costs. Dedicated IT teams manage security patching and backup protocols.
- Cloud-Based:Browser-accessible platforms eliminate hardware capital expenditure and enable remote vineyard monitoring from smartphones. Australia's premium producers in Barossa Valley and McLaren Vale adopt this model to coordinate harvest crews across dispersed vineyard blocks. Automatic vendor-managed updates ensure compliance template currency.
- Hybrid:Sensitive production data remains on local servers while customer-facing functions migrate to cloud instances. German Mittelstand wineries favor this architecture to satisfy GDPR data residency requirements while enabling e-commerce scalability.
- Mobile Solutions:Native smartphone applications for irrigation scheduling, pest scouting, and harvest crew coordination prioritize field usability over desktop feature depth. Younger vineyard managers in New Zealand's Marlborough region reject tablet-based legacy interfaces for pocket-sized tools.
Cloud-based deployment captures the steepest expansion trajectory; on-premises retains entrenched positions among heritage estates.
End User:
Each stakeholder type demands different data granularity and workflow integration depth from platform vendors.
- Wineries:Integrated vineyard-to-bottle platforms coordinate fermentation monitoring, barrel tracking, and compliance reporting through unified databases. California's mid-market producers between 5,000 and 50,000 cases annually drive demand for modular systems that scale with production growth.
- Vineyards:Standalone viticulture modules focus on canopy management, irrigation scheduling, and yield forecasting without cellar integration. Large grape growers in Washington's Walla Walla Valley supplying multiple wineries prioritize block-level data export compatibility.
- Distributors:Warehouse management and route accounting tools track allocation compliance and depletion velocity across retail accounts. Three-tier system requirements in the US mandate specific invoice formatting and tax reporting capabilities.
- Retailers:Inventory replenishment and customer loyalty systems for wine shops and grocery chains require supplier-agnostic data import. Independent retailers in urban markets prioritize recommendation engines that suggest pairings based on purchase history.
Wineries dominate current revenue concentration; vineyards are gaining share fastest as precision agriculture investments accelerate.
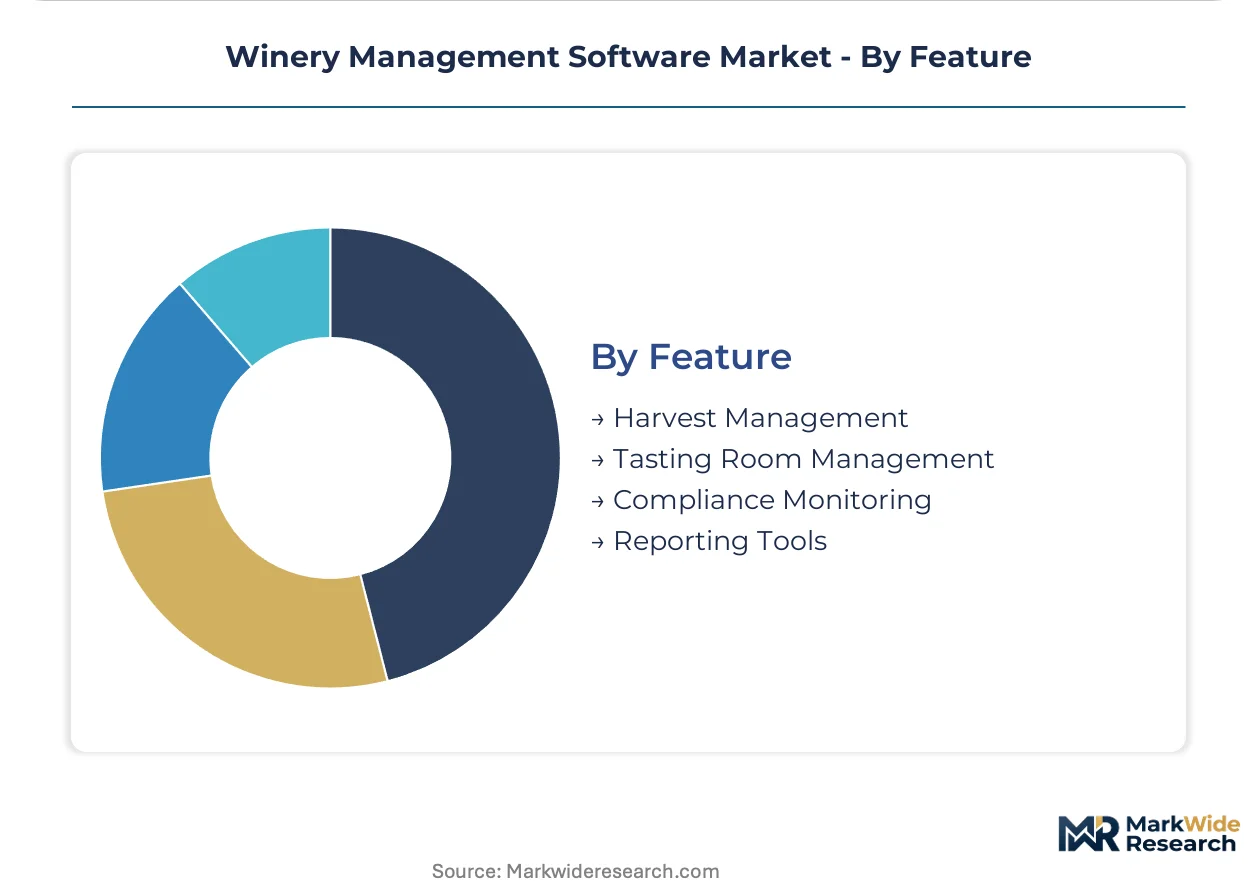
Feature:
Feature prioritization reveals whether buyers optimize for operational efficiency or regulatory risk mitigation.
- Harvest Management:Brix tracking, fermentation curve monitoring, and cap management scheduling coordinate crush pad logistics. Premium producers in Italy's Tuscany region deploy computer vision-integrated modules that predict optimal picking windows from canopy imagery.
- Tasting Room Management:Reservation systems, pour tracking, and club signup workflows convert visitor traffic into recurring revenue. Oregon's Willamette Valley tasting rooms prioritize this feature to manage weekend capacity constraints and comply with dram shop liability documentation.
- Compliance Monitoring:Automated TTB reporting, FDA traceability lot coding, and EU labeling requirement checks reduce audit preparation labor. Export-oriented American wineries shipping to European retail chains treat this as non-negotiable procurement criteria.
- Reporting Tools:Customizable dashboards for cost per ton, case production economics, and channel margin analysis support strategic pricing decisions. Private equity-backed winery portfolios require consolidated multi-entity reporting for investor communications.
Compliance monitoring leads on deal-breaker status; tasting room management leads on expansion velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Winery management software originated in California's Napa Valley during the 1990s digitization wave, then spread to Australia's Barossa Valley and France's Bordeaux region as cloud architectures matured.
United States
California's mid-market producers between 5,000 and 50,000 cases annually drive cloud-native procurement, while Oregon's Willamette Valley incubators prioritize subscription licensing for capital flexibility. The Alcohol and Tobacco Tax and Trade Bureau mandates detailed production records that accelerate compliance automation. Washington's Walla Walla Valley and Columbia Valley clusters anchor Pacific Northwest adoption, where broadband gaps in rural vineyard blocks limit real-time synchronization.
Australia
Barossa Valley and McLaren Vale premium producers deploy smartphone-native field tools to coordinate harvest crews across dispersed vineyard blocks. The country's national wine regulator enforces strict export documentation standards that shape software feature roadmaps. Adelaide-based technology clusters support vendor development, while Margaret River operations prioritize API-connected laboratory equipment for fermentation monitoring.
France
Bordeaux's large family-owned estates retain on-premises architectures to preserve decades of historical production data without cloud migration costs. The country's national data protection authority enforces GDPR data residency requirements that favor hybrid deployment models. Burgundy and Champagne sub-regions concentrate demand for harvest management modules with computer vision integration.
Germany
Mittelstand wineries across Baden-Württemberg and Rhineland-Palatinate favor hybrid architectures that satisfy GDPR requirements while enabling e-commerce scalability. The country's federal data protection commissioner maintains strict cross-border transfer rules. Mosel and Rheingau valley operations prioritize mobile-first field applications for steep-slope vineyard management.
Italy
Tuscany's premium producers deploy computer vision-integrated harvest modules that predict optimal picking windows from canopy imagery. The country's national agricultural ministry enforces traceability standards for export-oriented operations. Piedmont and Veneto clusters anchor northern Italian adoption, where heritage estates balance legacy system retention against cloud migration pressures.
Winery Management Software Market Vendor Landscape
The competitive structure tilts toward vertical specialists rather than horizontal ERP incumbents. Mid-market wineries consolidate procurement around unified vineyard-to-bottle platforms, fragmenting the point-solution vendor base. Two archetypes dominate: beverage-production workflow specialists and direct-to-consumer CRM purists. M&A activity concentrates on API connectivity assets, while geographic expansion targets emerging wine regions with compliance automation bundles.
Within the vertical-specialist tier, Ekos anchors mid-market adoption through beverage-production workflow depth, Commerce7 occupies the direct-to-consumer vector with club management specialization, and Vintrace exemplifies harvest-cellar tracking loyalty among premium producers. These three represent contrasting strategic bets: production operations versus consumer revenue capture versus fermentation monitoring granularity.
| Leading Market Players |
|---|
| Rockit Systems |
| Commerce7 |
| Vintrace |
| InnoVint |
| 360Winery |
| Ekos |
| WineDirect |
| The Wine Club |
| Vint |
| Others |
Supply Flow & Price Mechanics
Cloud-native software engineering talent concentration in California's Bay Area compresses development cost differentials between premium-tier vineyard-to-bottle platforms and mid-market SaaS alternatives, widening pricing spreads as vendors pass through specialized labor premiums.
Pricing Analysis
Subscription-based SaaS licensing with three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by API integration depth and TTB compliance automation grade. Pricing pressure stems from capital-constrained emerging wineries in Oregon's incubator programs demanding monthly-per-user flexibility over perpetual licenses. Boutique producers between 5,000 and 50,000 cases exhibit highest price sensitivity, while large family-owned estates with legacy ERP integration requirements absorb premium tiers for data sovereignty guarantees.
Supply Chain Analysis
Domestic-content mandates in data residency regulations across France, Germany, and Australia reshape vendor hosting strategies toward regional cloud infrastructure partnerships. Software development draws from engineering clusters in California, Adelaide, and Bordeaux, with critical dependencies on API-standardized laboratory equipment from fermentation sensor manufacturers and payment processor integrations for tasting room transactions. Single-source vulnerability concentrates in cloud infrastructure providers serving rural vineyard locations with unreliable broadband, while distribution runs through direct vendor sales teams and regional value-added resellers serving heritage estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Winery management software functions as a stable compounder anchored by perpetual TTB compliance automation demand that sustains replacement cycles regardless of vintage variability.
For Market Incumbents: Lock in mid-market winery loyalty through backward integration into laboratory equipment APIs that deepens fermentation monitoring data capture, while investing in SOC 2 certification to satisfy cybersecurity insurance requirements filtering smaller competitors from enterprise bidding. Prioritize mobile-first field application development to retain younger vineyard managers rejecting tablet-based legacy interfaces. For New Entrants and Emerging Players: Begin with sustainability disclosure modules targeting California and Oregon producers facing emerging state-level carbon accounting mandates, where incumbent platforms lack embedded emissions tracking. White-space concentration sits with vineyard-specific viticulture modules serving large grape growers in Washington's Walla Walla Valley supplying multiple wineries, using block-level data export compatibility as the primary go-to-market wedge. For Investors and Strategic Acquirers: Private equity-backed winery portfolios are the most active acquirer in this space, consolidating fragmented point-solution vendors into unified platform stacks. Long-term viability rests on API connectivity assets that enable harvest-to-bottle traceability storytelling for premium producers. Watch for FDA Food Safety Modernization Act Section 204 enforcement acceleration as the inflection signal reshaping data architecture procurement criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CRM, inventory, and compliance layers that point solutions cannot deliver for direct-to-consumer wineries. |
| Acquisition of Specialist Firm | Captures API connectivity assets enabling fermentation sensor integration and laboratory equipment data feeds. |
| Product Launch | Introduces mobile-first field applications addressing younger vineyard manager rejection of tablet-based interfaces. |
| Strategic Partnership | Establishes regional cloud hosting alliances satisfying GDPR data residency requirements in France and Germany. |
| Geographic Expansion | Targets Australia's Barossa Valley and McLaren Vale clusters with smartphone-native harvest crew coordination tools. |
Methodological Framework
Direct dialogue with winery operations directors, vineyard managers, software vendor product leads, and TTB compliance officers combined with secondary validation against SEC filings, cloud infrastructure capex disclosures, and national wine regulator export documentation standards. Bottom-up case production estimates triangulate against top-down software spend allocation models across deployment modes and end-user segments.
Market size outputs incorporate segmentation across deployment architecture, organization scale, feature module prioritization, and regional adoption pattern throughout the forecast period. CAGRs derive from vintage-adjusted replacement cycle analysis and cloud migration penetration curves, with inputs including broadband infrastructure expansion timelines in rural vineyard locations and TTB regulatory enforcement intensity indicators.
Caveats apply where FCC rural broadband deployment delays or state-level sustainability disclosure rule acceleration could materially shift the outlook. Forecasts reflect assumptions about compliance automation demand persistence and API standardization timelines for laboratory equipment integration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America Restaurant Management Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Computer Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Petcare Software Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
IT Professional Services Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Tenant Billing Software Market
Software & Services
Enterprise-Grade Saas Market
Software & Services
Low Code Development Platform Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Product Optimization Software Market
Software & Services
Global Technical Illustration Software Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Global Offshore Software Development Market