
 Household Pet Water Dispenser Market | 2026-2036
Household Pet Water Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Household Pet Water Dispenser Market Insights
Subscription-based filter replacement programs is decoupling hardware margins from recurring revenue streams across the household pet water dispenser landscape. PetSafe leverages its veterinary clinic distribution network to sustain institutional channel dominance, while Petkit competes through app-connected flow monitoring that extends consumer engagement beyond the point of sale. Rolf C. Hagen Inc. anchors its position in European specialty retail through ceramic and glass material specialization that commands shelf placement in premium pet boutiques.
Household pet water dispensers are electromechanical or gravity-fed hydration appliances designed to provide continuous fresh water access to companion animals, typically incorporating activated carbon or multi-stage filtration media with flow rates between 0.5 and 2 liters per hour. Automatic dispenser variants dominate value generation due to pump-driven circulation and integrated UV sterilization, while gravity dispensers occupy the mass-market entry tier where price sensitivity constrains feature adoption. Stainless steel reservoirs command margin premiums over plastic alternatives because of antimicrobial properties and dishwasher-safe maintenance protocols that align with veterinary clinic procurement standards.
Consumer Product Safety Commission guidelines and California Proposition 65 disclosure requirements shape material selection and labeling obligations for manufacturers selling into the United States. FDA food-contact substance regulations apply to reservoir polymers and filter housings, creating compliance barriers for imported assemblies that lack domestic certification documentation. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances, as these chemicals appear in legacy non-stick coatings found in some budget dispenser models.
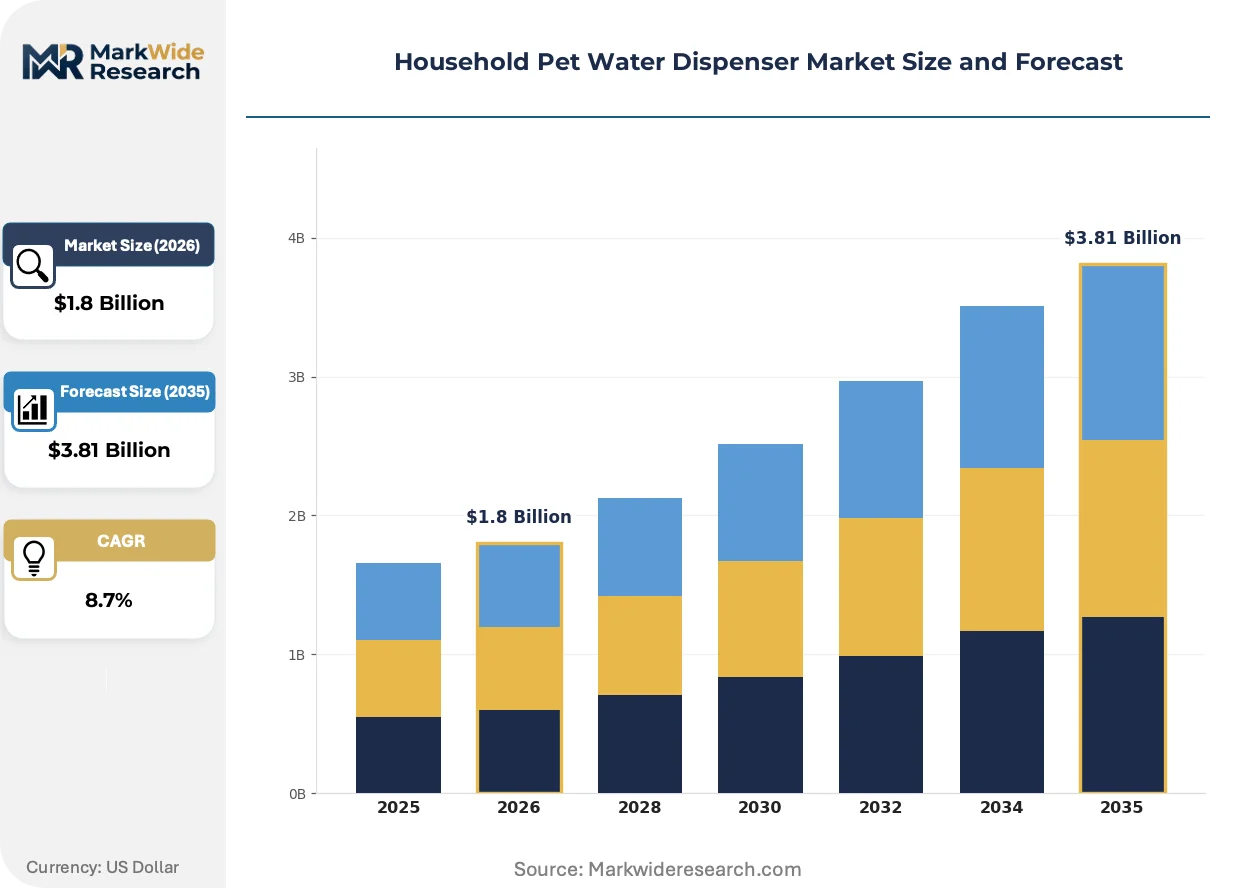
Market Dynamics
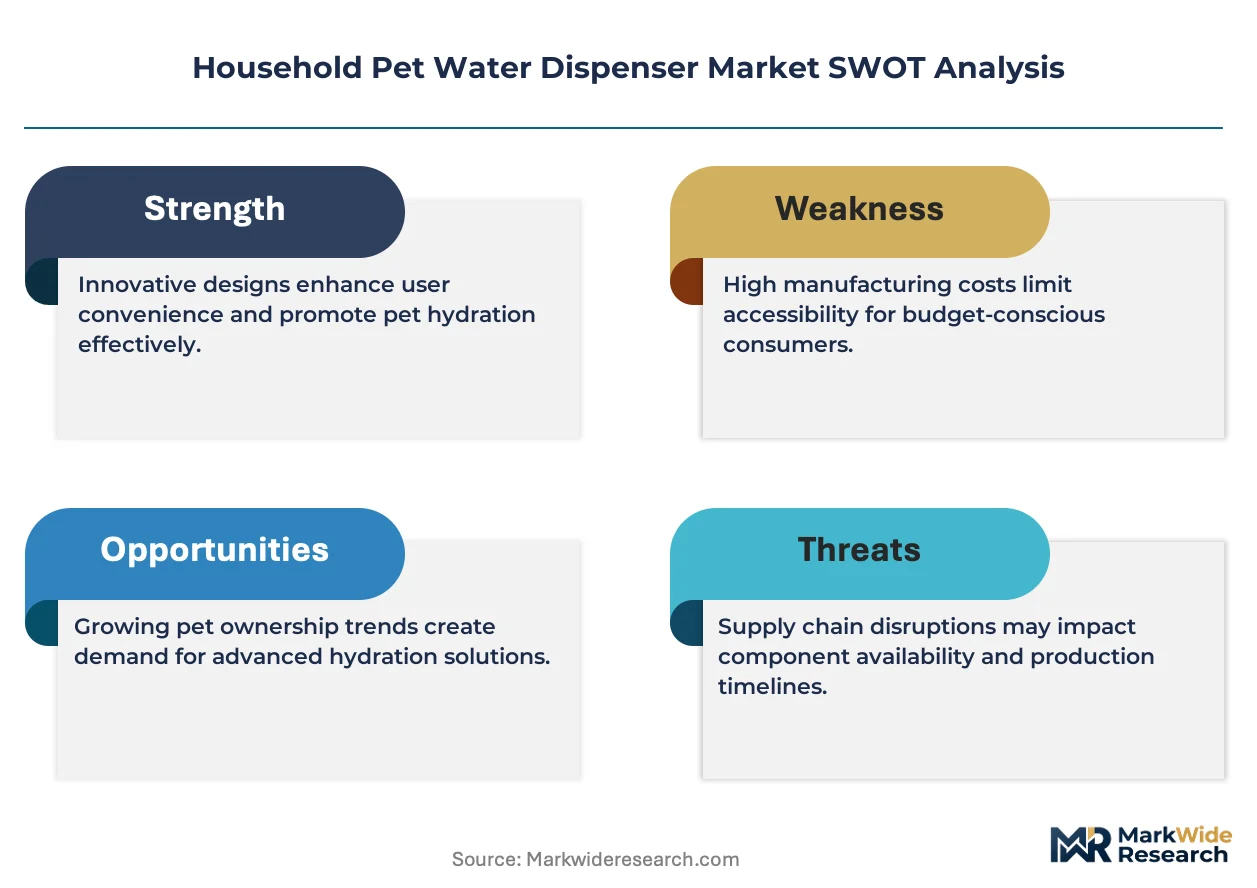
Subscription filter replacement programs are decoupling hardware margins from recurring revenue streams, forcing manufacturers to restructure business models around lifetime value capture rather than point-of-sale profitability.
Growth Catalysts
- EPA Filter Standards:Federal drinking water quality guidelines are elevating consumer expectations for multi-stage filtration in home pet hydration products.
- Stainless Steel Adoption:Veterinary clinic procurement standards favor antimicrobial reservoirs, creating pull-through demand into household segments.
- Urban Household Concentration:Dense metropolitan populations in the United States sustain premium automatic dispenser penetration rates above suburban and rural markets.
Market Restraints
- Polymer Input Volatility:Food-grade ABS and polycarbonate resin prices fluctuate with petrochemical feedstock costs, compressing margins on plastic reservoir models.
- California Proposition 65:Disclosure requirements for chemical constituents create compliance friction and labeling costs for manufacturers without domestic legal infrastructure.
- Gravity Dispenser Substitution:Low-cost passive hydration systems retain price-sensitive consumers who reject electromechanical complexity and filter subscription commitments.
Strategic Opportunities
- App-Connected Monitoring:Flow sensor integration with smartphone platforms creates engagement touchpoints that extend consumer relationships beyond initial purchase.
- Ceramic and Glass Specialization:Premium pet boutiques in European markets command shelf placement for non-plastic material alternatives that differentiate from mass-market competitors.
- State-Level PFAS Restrictions:Emerging prohibitions on per- and polyfluoroalkyl substances in California and New York create first-mover advantage for manufacturers with certified coating-free assemblies.
Industry Challenges
- Domestic Certification Documentation:FDA food-contact substance approvals for imported reservoir polymers require 12-18 month timeline extensions that delay market entry.
- Pump Reliability Engineering:Continuous-duty submersible motor design demands specialized fluid dynamics expertise scarce among consumer appliance engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Pet Water Dispenser Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Dispenser, Gravity Dispenser, Bottle Dispenser, Large Capacity Dispenser End User: Pet Owners, Veterinary Clinics, Animal Shelters, Pet Stores Material: Plastic, Stainless Steel, Ceramic, Glass Feature: Filter System, LED Indicators, Adjustable Flow, Easy Clean |
| Companies Covered | Critter Concepts, K&H Pet Products, Petmate, Petkit, Pioneer Pet, PetSafe, Van Ness, CatH2O, Rolf C. Hagen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Pet Water Dispenser Market Trends and Innovations
UV sterilization modules and IoT connectivity layers are transforming electromechanical dispensers from passive hydration appliances into active health monitoring platforms that capture veterinary referral revenue.
UV-C LED sterilization is overtaking chemical tablet treatments as the preferred bacterial control method in premium automatic dispensers. Millennial pet owners in United States urban centers adopt these systems at rates that compress replacement cycles for legacy carbon-only filtration models. The technology is enabling hardware manufacturers to capture recurring revenue through integrated filter-UV cartridge bundles that command 40% lifetime value premiums over baseline units.
REACH substance restrictions in the European Union are prohibiting certain phthalate plasticizers previously common in pump housing manufacturing. Industrial consequence includes accelerated migration toward glass-filled nylon and metal pump components that add unit cost but satisfy ECHA registration requirements. Premium European specialty retail channels are responding by sourcing exclusively from manufacturers with full material disclosure documentation.
Millennial and Gen Z pet owners are consolidating hydration product selection around veterinary clinic recommendations rather than independent retail research. Independent pet specialty stores in United States coastal cities are losing traffic to clinic-affiliated dispensary programs that bundle automatic dispensers with wellness plan subscriptions. This channel compression is most visible in California and New York metropolitan statistical areas where clinic consolidation has concentrated referral authority among fewer veterinary practice groups.
Household Pet Water Dispenser Market Segmentation
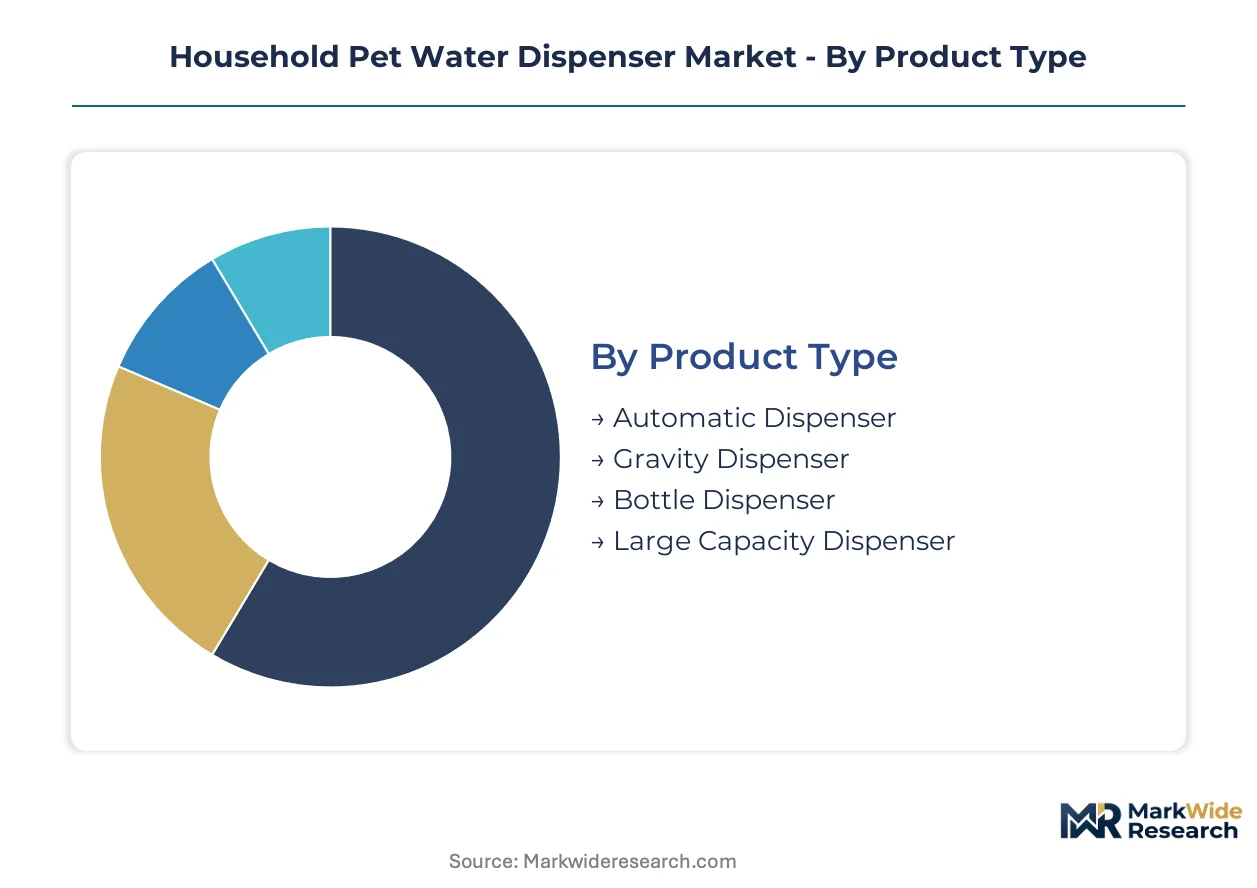
Pet water dispenser purchasing decisions split sharply between electromechanical sophistication and passive simplicity, with material compliance emerging as a non-negotiable filter for United States household penetration. Channel concentration in veterinary clinics and specialty retail creates divergent margin structures across each segment axis.
Product Type:
Purchase motivation pivots on the trade-off between convenience automation and maintenance burden tolerance among millennial and Gen Z pet owners.
- Automatic Dispenser:Pump-driven circulation systems integrate UV sterilization and multi-stage filtration with flow rates between 0.5 and 2 liters per hour. Urban United States households sustain premium penetration where subscription filter programs generate recurring revenue that decouples hardware margins from point-of-sale profitability.
- Gravity Dispenser:Passive hydration systems rely on reservoir weight displacement without electromechanical components. Price-sensitive consumers in suburban and rural United States markets reject filter subscription commitments, constraining feature adoption to basic carbon filtration.
- Bottle Dispenser:Portable units designed for travel and temporary placement prioritize compact reservoir geometry over filtration sophistication.
- Large Capacity Dispenser:Multi-pet households and institutional settings demand reservoir volumes exceeding 5 liters with reinforced pump duty cycles.
Volume sits with gravity dispensers; growth tilts toward automatic dispensers.
End User:
Procurement authority is consolidating around veterinary clinic recommendations rather than independent retail research across United States coastal metropolitan areas.
- Pet Owners:Individual households drive the majority of unit volume, with millennial and Gen Z demographics consolidating selection around clinic-affiliated wellness plan bundles in California and New York metropolitan statistical areas.
- Veterinary Clinics:Institutional procurement standards favor stainless steel reservoirs with antimicrobial properties and dishwasher-safe maintenance protocols that align with clinical hygiene requirements.
- Animal Shelters:High-throughput facilities prioritize durability and ease of sanitation over connected features or aesthetic design.
- Pet Stores:Specialty retail channels in European markets command shelf placement for ceramic and glass alternatives that differentiate from mass-market plastic competitors.
Revenue concentrates with pet owners; margin expansion favors veterinary clinics.
Material:
Regulatory pressure from FDA food-contact substance approvals and California Proposition 65 disclosure requirements is elevating material documentation above unit cost in supplier selection.
- Plastic:Food-grade ABS and polycarbonate resin construction dominates unit economics but faces margin compression from petrochemical feedstock volatility. REACH substance restrictions in the European Union are accelerating migration toward alternative polymers.
- Stainless Steel:Antimicrobial reservoir properties command premium positioning in both veterinary clinic procurement and health-conscious United States households. Dishwasher-safe maintenance protocols extend replacement cycles compared to plastic alternatives.
- Ceramic:European specialty retail channels source exclusively from manufacturers with full material disclosure documentation to satisfy ECHA registration requirements.
- Glass:Premium pet boutiques in urban European markets position non-plastic alternatives as differentiation from mass-market competitors.
Unit volume rests with plastic; value capture shifts toward stainless steel.
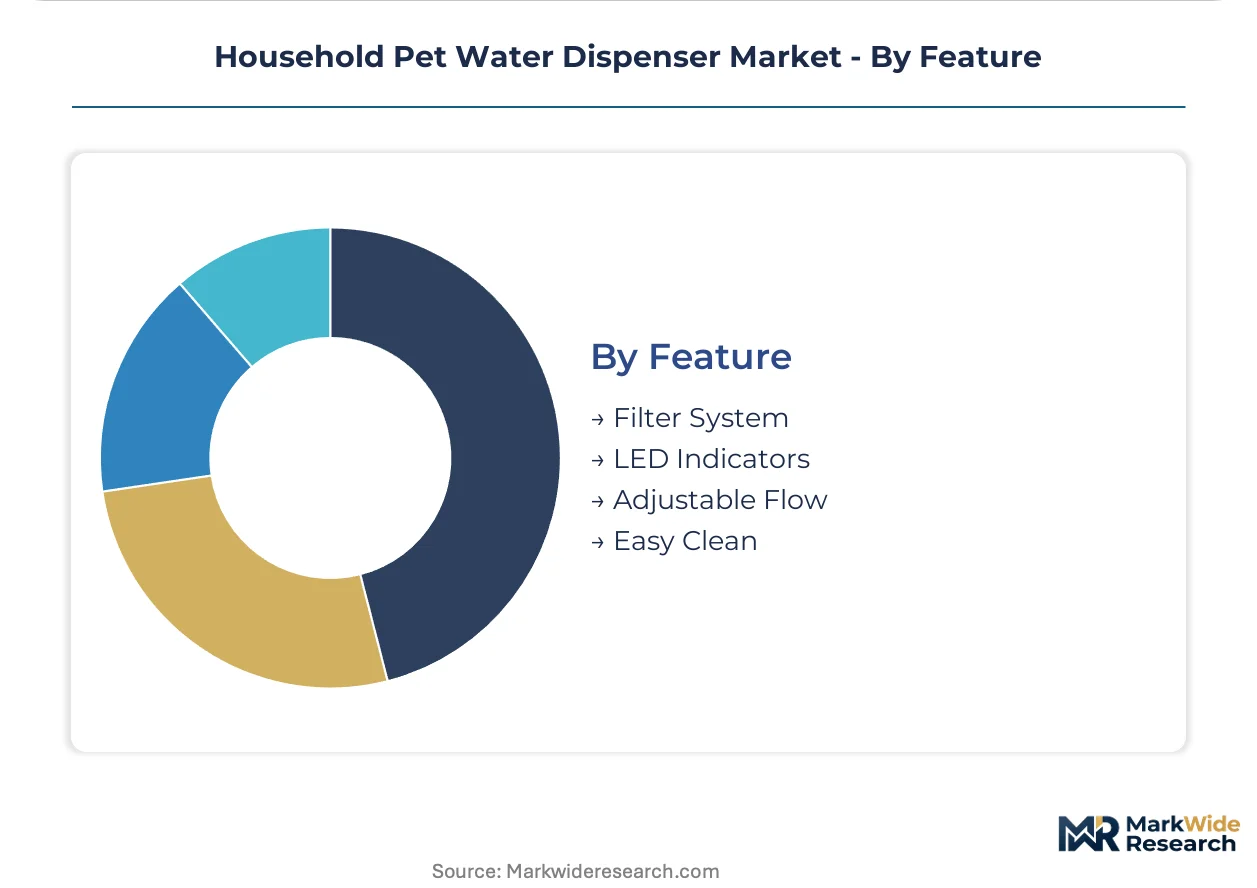
Feature:
Technology integration intensity separates subscription-viable hardware from commodity replacement cycles in United States urban markets.
- Filter System:Activated carbon and multi-stage filtration media respond to EPA drinking water quality guidelines elevating consumer expectations. UV-C LED sterilization modules are overtaking chemical tablet treatments in premium automatic dispensers.
- LED Indicators:Visual maintenance alerts reduce filter replacement lag time and sustain subscription program retention rates among app-connected device owners.
- Adjustable Flow:Pump-driven circulation customization accommodates multi-pet households with varying species hydration preferences.
- Easy Clean:Modular reservoir design and dishwasher-safe component separation reduce maintenance abandonment that drives premature product replacement.
Adoption concentrates with filter systems; feature bundling accelerates fastest around LED-integrated UV sterilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of electromechanical pet water dispensers concentrates in Chinese industrial zones, while consumption tilts toward United States urban households where subscription filter programs sustain premium pricing. European specialty retail channels source ceramic and glass alternatives from regional fabricators to satisfy REACH documentation requirements.
United States
Millennial and Gen Z pet owners in California and New York metropolitan statistical areas consolidate purchasing around veterinary clinic wellness plan bundles. FDA food-contact substance regulations for reservoir polymers create 12-18 month certification delays for imported assemblies. Los Angeles and San Francisco Bay Area clusters drive automatic dispenser penetration above national averages through dense apartment-dwelling pet populations.
Germany
REACH substance restrictions from ECHA accelerate migration from phthalate plasticizers toward glass-filled nylon pump components. Bavaria and North Rhine-Westphalia host precision injection molding suppliers serving European pet appliance brands. Stuttgart industrial corridor manufacturers specialize in dishwasher-safe stainless steel reservoir fabrication for veterinary clinic procurement channels.
China
Guangdong and Zhejiang provinces dominate electromechanical dispenser assembly with integrated pump and UV-C LED module supply chains. GB standards for food-contact materials shape export documentation requirements for North American and European bound shipments. Shenzhen electronics clusters produce flow sensors and IoT connectivity layers for app-connected monitoring features.
United Kingdom
London and Southeast England retail channels favor premium ceramic dispensers from European specialty importers over mass-market plastic alternatives. Veterinary clinic consolidation in Greater Manchester and Birmingham concentrates referral authority among fewer practice groups. UKCA marking requirements post-Brexit create parallel conformity assessment pathways for reservoir polymers and filter housings.
Japan
Tokyo and Osaka metropolitan households sustain demand for compact automatic dispensers suited to limited apartment space. METI energy efficiency guidelines influence pump motor specifications in domestic-market products. Kansai region manufacturers specialize in antimicrobial surface treatments for stainless steel reservoirs targeting veterinary clinic standards.
Household Pet Water Dispenser Market Competitive Landscape
Top-tier vendors anchor the premium automatic dispenser segment, while mid-tier fabricators compete on gravity-fed systems and regional specialty retail placement. The vendor base stratifies across three archetypes: electromechanical specialists with subscription filter programs, ceramic and glass material specialists serving European boutiques, and mass-market plastic reservoir manufacturers competing on unit economics. Consolidation pressure intensifies as veterinary clinic channel concentration favors suppliers with institutional certification documentation. Competitive moves center on backward integration into pump assembly and geographic expansion through clinic-affiliated distribution networks.
Among North American appliance specialists, PetSafe and Petkit occupy positions exemplifying divergent strategic archetypes. PetSafe leverages veterinary clinic distribution infrastructure to sustain institutional channel presence. Petkit represents the connected-device tier through app-integrated flow monitoring capabilities. Rolf C. Hagen Inc. anchors European specialty retail positioning through non-plastic material specialization. These three fabricators illustrate how geographic origin and channel focus shape competitive differentiation without overlapping core customer segments.
| Leading Market Players |
|---|
| Critter Concepts |
| K&H Pet Products |
| Petmate |
| Petkit |
| Pioneer Pet |
| PetSafe |
| Van Ness |
| CatH2O |
| Rolf C. Hagen Inc. |
| Others |
Pricing and Supply Chain Analysis
Automatic dispenser premiumization against gravity-fed commodity tiers manifests divergent margin architectures across electromechanical sophistication levels and raw material sourcing strategies. Stainless steel reservoir procurement from Kansai region fabricators commands unit cost premiums that filter through to veterinary clinic channel pricing, while Guangdong plastic injection molding sustains mass-market entry point economics through ABS resin spot market exposure.
Pricing Analysis
Margin tightening in plastic reservoir tiers reflects petrochemical feedstock volatility compressing unit economics for gravity dispenser manufacturers. Three-tier pricing structure across premium automatic, standard electromechanical, and economy gravity levels separates subscription-viable hardware from commodity replacement cycles. FDA food-contact certification documentation creates tiered quality premiums that price-sensitive suburban households reject in favor of basic carbon filtration models. Urban millennial pet owners in California and New York metropolitan statistical areas exhibit lowest price sensitivity, absorbing UV-C LED sterilization premiums through wellness plan bundling.
Supply Chain Analysis
Dual-sourcing requirements for pump motor assemblies mandate qualification of both Guangdong and Zhejiang province suppliers to mitigate single-source vulnerability. Electromechanical dispenser production draws from Chinese industrial zones for integrated UV-C LED modules, Japanese Kansai region fabricators for antimicrobial stainless steel surface treatments, and German Stuttgart corridor specialists for dishwasher-safe reservoir engineering. Food-grade ABS and polycarbonate resin dependencies tether margin stability to petrochemical benchmark fluctuations. Distribution runs through veterinary clinic consolidation networks in United States coastal cities and European specialty retail channels requiring REACH documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pump reliability engineering scarcity constrains electromechanical capacity expansion, propping premium pricing for manufacturers with proven continuous-duty motor expertise. This supply bottleneck sustains hardware margin capture for qualified suppliers against commodity gravity dispenser alternatives.
For Market Incumbents: Cement institutional channel dominance through backward integration into submersible pump assembly, capturing the 12-18 month FDA certification moat that delays import competition. Deepen veterinary clinic distribution control by bundling automatic dispensers with subscription filter programs that lock out gravity dispenser substitution threats. Invest in ceramic and glass material documentation for European specialty retail shelf placement against REACH-compliant competitors. For New Entrants and Emerging Players: California Proposition 65 disclosure requirements in the United States open a window for coating-free assembly specialists to capture first-mover advantage as PFAS restrictions proliferate. Target price-sensitive suburban households with simplified gravity dispenser variants that reject electromechanical complexity and filter subscription commitments. Pursue direct-to-consumer launch through app-connected flow monitoring features that extend engagement beyond initial purchase. For Investors and Strategic Acquirers: Re-rating potential sits with electromechanical specialists possessing proven pump reliability engineering and veterinary clinic certification documentation given channel consolidation concentrating referral authority. Long-term viability across the 5-10 year window favors manufacturers with backward integration into UV-C LED sterilization module sourcing and multi-material reservoir fabrication capabilities. Monitor state-level PFAS restriction adoption velocity as inflection indicator for coating-free assembly demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Filter Subscription Program Launch | Recurring revenue decouples hardware margins from point-of-sale profitability for automatic dispenser manufacturers. |
| Stainless Steel Reservoir Expansion | Antimicrobial properties align with veterinary clinic procurement standards driving premium household adoption. |
| UV-C LED Sterilization Integration | Bacterial control modules command 40% lifetime value premiums over legacy carbon-only filtration systems. |
| REACH Documentation Investment | Full material disclosure satisfies ECHA requirements for European specialty retail channel access. |
| App-Connected Monitoring Platform | Flow sensor smartphone integration extends consumer engagement touchpoints beyond initial hardware purchase. |
Research Methodology
Independent corroboration across veterinary clinic procurement managers, pet specialty retail category buyers, electromechanical appliance engineers, and polymer supply chain specialists underwrites the qualitative findings. Primary interviews with FDA regulatory consultants and ECHA compliance officers cross-validate secondary sourcing from EPA drinking water quality guidelines, FDA food-contact substance filings, REACH substance restriction databases, and customs trade documentation for reservoir polymer imports. Bottom-up unit shipment estimates triangulate against top-down consumer expenditure patterns across the analysis window.
Rate-of-change decomposition separates volume expansion from value capture across product type segmentation by electromechanical sophistication, material tier by antimicrobial certification level, end user channel by procurement authority concentration, and feature bundle by subscription viability. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points and technology substitution curves. Forecast inputs incorporate petrochemical feedstock price trajectory assumptions and veterinary clinic consolidation velocity metrics.
The model assumes a particular technology adoption path; alternative pathways for UV-C LED sterilization diffusion would alter the outlook if chemical tablet treatments retain cost-sensitive segments. Deviation in pump reliability failure rates or state-level PFAS restriction enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Dog Brush Market
Pet Care Products
Dog Bed Covers Market
Pet Care Products
Dog Life Jacket Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Cat Condos and Indoor Houses Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Pet Daycare Market
Pet Care Products
Europe Pet Food Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
Pet Collar Market
Pet Care Products
Japan Pet Clothing Market