
 Express and Parcel Market | 2026-2036
Express and Parcel Market Size, Share, and Industry Trends Forecast 2026-2036
Express and Parcel Market Foresight
E-commerce fulfillment is rebalancing the express and parcel sector toward last-mile density and urban micro-fulfillment nodes. United Parcel Service anchors North American ground networks through its integrated hub-and-spoke infrastructure. FedEx Corporation differentiates via international priority services and cross-border customs brokerage capabilities. DHL Group dominates European express lanes while extending pharmaceutical cold-chain certification across its network.
Express and parcel services encompass time-definite pickup, sortation, line-haul transport, and delivery of documents and packages weighing from envelopes to palletized freight, with transit commitments ranging from same-day to standard multi-day ground service. The primary commercial purpose is enabling just-inventory replenishment, direct-to-consumer fulfillment, and business-critical document exchange. Same-day delivery captures premium pricing in dense urban corridors where mobile apps and GPS tracking reduce failed delivery rates. Small parcels generate the highest volume velocity within e-commerce channels, while automated sortation technology concentrates capital investment at superhub facilities.
The EPA regulates commercial vehicle emissions standards for last-mile diesel and electric fleets, while the EU Green Deal mandates corporate sustainability reporting that affects carrier fuel choices and scope-three disclosure. The FAA governs air cargo operations for express integrators operating dedicated freighter aircraft, constraining night-flight access at certain hubs. Stakeholders must monitor regulatory divergence between emissions trading schemes and local noise ordinances as they configure network assets.
Market Dynamics
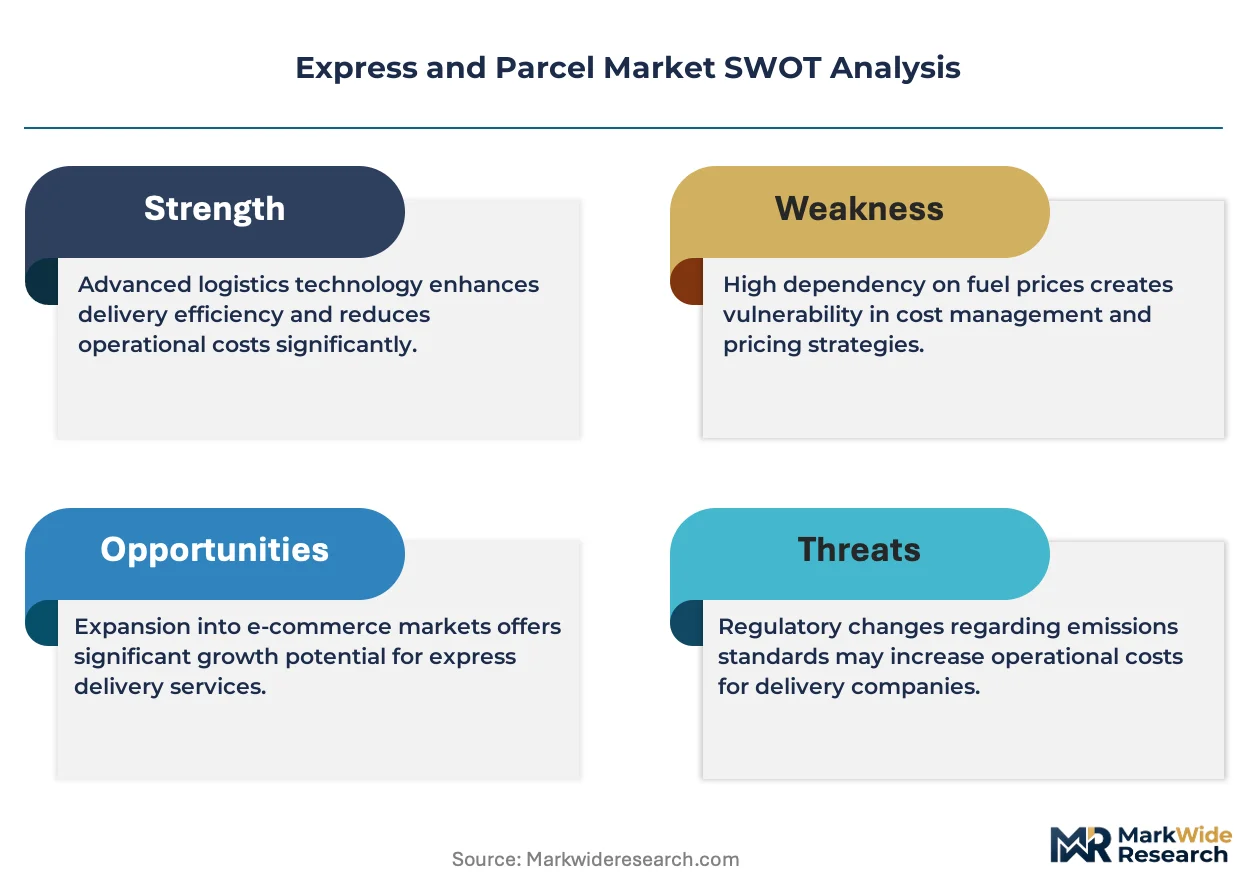
E-commerce fulfillment density is compressing delivery windows and forcing capital reallocation toward urban micro-hubs and electric last-mile fleets. Carrier networks must now balance speed commitments against scope-three emissions disclosure requirements.
Growth Catalysts
- EU Green Deal carbon reporting:Mandatory corporate sustainability disclosure is accelerating fleet electrification procurement across European express lanes. Carriers retrofit depots with charging infrastructure to maintain contract eligibility.
- Pharmaceutical cold-chain certification:Temperature-controlled parcel volumes expand as biologics distribution shifts from bulk freight to patient-direct delivery. Express integrators invest in validated packaging and real-time monitoring.
- China's domestic express consolidation:SF Express and ZTO Express anchor superhub automation that compresses sortation costs and enables next-day coverage of tier-two cities.
Market Restraints
- Lithium-ion battery input volatility:Electric van and cargo bike procurement faces cell supply concentration and price swings that distort total-cost-of-ownership calculations for fleet operators.
- Air cargo slot scarcity:FAA night-flight restrictions at Memphis and Louisville hubs constrain integrator network velocity during peak e-commerce windows.
- Last-mile labor cost escalation:Dense urban corridors face driver wage compression that erodes margin on standard ground parcels despite volume growth.
Strategic Opportunities
- India's underpenetrated tier-three cities:E-commerce penetration lags in secondary urban clusters where postal infrastructure remains dominant. Private express operators can capture share through franchise partner networks.
- Returns automation technology:Reverse logistics integration with AI-powered condition assessment and instant refund processing reduces working capital lockup for apparel retailers.
- Japan's pharmaceutical direct-to-patient mandate:METI guidelines favor specialized couriers with PMDA-aligned cold-chain protocols for temperature-sensitive biologics.
Industry Challenges
- Electric fleet technician scarcity:High-voltage powertrain maintenance requires certified specialists that outstrip vocational training pipeline output in Germany and California.
- Cross-border customs system fragmentation:Divergent data formats between EU ICS2, US ACE, and China's Golden Customs platforms force redundant IT integration spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Express and Parcel Market |
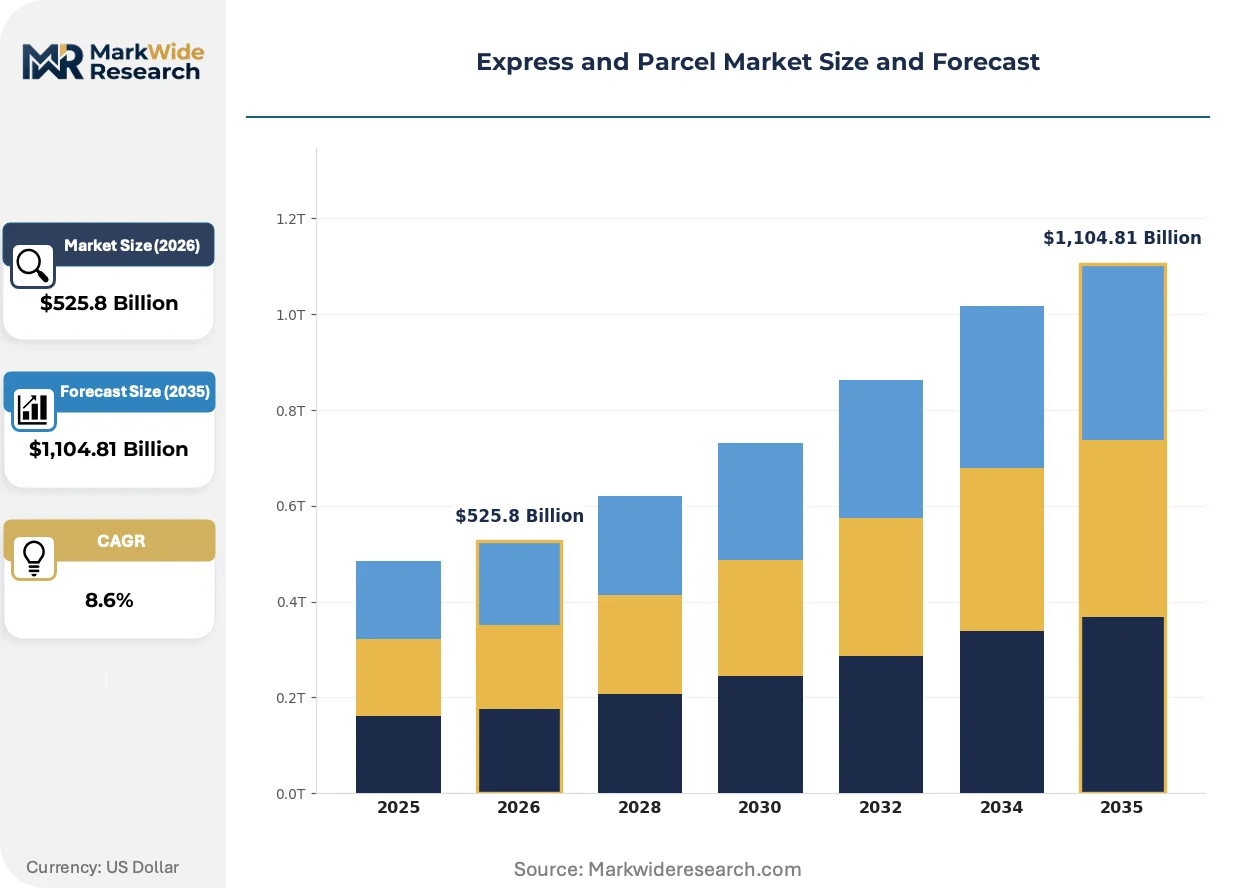
| Market Size in 2026 | $525.8 Billion |
| Market Size in 2035 | $1,104.81 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, Scheduled Delivery Package Type: Documents, Small Parcels, Large Parcels, Pallets End User: E-Commerce, Retailers, Corporations, Individuals Technology: Barcode Scanning, GPS Tracking, Automated Sorting, Mobile Apps |
| Companies Covered | United Parcel Service, FedEx Corporation, DHL Group, SF Express, Aramex, Japan Post Holdings, Royal Mail Group, Australia Post, ZTO Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Express and Parcel Market Shifts & Advancements
Automation and emissions accountability are reconfiguring how express networks deploy capital, sort volume, and price service tiers. Three developments dominate strategic planning.
Autonomous mobile robots are integrating into superhub sortation floors to reduce parcel handling labor and increase throughput per square meter. DHL Group and UPS deploy these systems at European and North American hubs to manage e-commerce volume surges without proportional headcount expansion. The technology is integrating human-robot workflow protocols that redefine shift staffing models and facility design specifications.
EPA commercial vehicle emissions standards are tightening diesel fleet compliance costs while accelerating electric van adoption timelines. Carriers must now account for total-cost-of-ownership across battery lifecycle and charging infrastructure depreciation. The regulation most affects last-mile ground operators in California and New York where state-level zero-emission mandates run ahead of federal minimums.
Buyer procurement of express services is consolidating through platform-based tendering that aggregates volume across multiple brands. Retailers now benchmark guaranteed delivery windows and carbon intensity metrics through centralized dashboards rather than bilateral carrier negotiations. This shift is most advanced in Germany and the Netherlands where large e-commerce aggregators dominate parcel spend.
Express and Parcel Market Segmentation
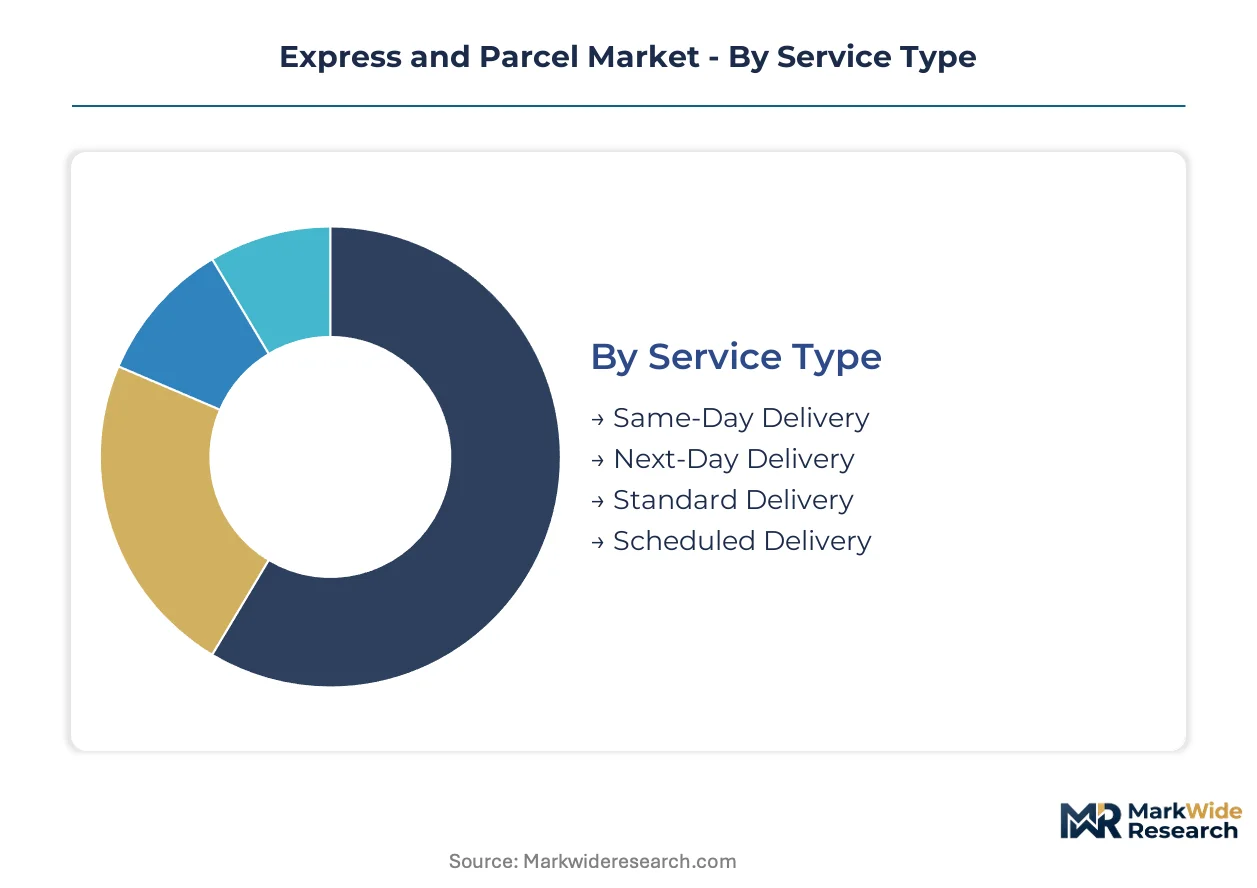
Express and parcel operators configure network assets around service velocity commitments and package handling requirements. Segmentation reveals where capital concentrates across sortation automation, fleet electrification, and last-mile density investments.
Service Type:
Same-day and next-day segments command the highest infrastructure deployment, requiring urban micro-fulfillment nodes and dynamic route optimization systems.
- Same-Day Delivery:Time-definite urban service within metropolitan corridors relies on gig-economy couriers and electric cargo bikes. Demand clusters in Shanghai, London, and New York where mobile app penetration enables real-time dispatch.
- Next-Day Delivery:Hub-and-spoke sortation with overnight line-haul positioning dominates premium B2B document exchange and fashion e-commerce. Carriers invest in superhub automation to compress cutoff times and extend geographic coverage.
- Standard Delivery:Ground network consolidation of multi-day parcels optimizes trailer utilization across less-than-truckload densities.
- Scheduled Delivery:Appointment-based windows for bulky goods coordinate customer availability with specialized handling equipment.
Next-day delivery absorbs the bulk of installed capacity; same-day delivery is expanding most quickly.
Package Type:
Physical dimensions dictate sortation technology selection and vehicle fleet composition across the network.
- Small Parcels:Envelope-to-shoebox dimensions flow through high-speed tilt-tray sorters at throughput rates exceeding manual handling capacity. E-commerce apparel and electronics drive volume concentration in automated facilities.
- Documents:Lightweight envelopes with priority handling protocols retain premium pricing in legal and financial services despite digital displacement trends.
- Large Parcels:Oversized items require manual induction and specialized last-mile vehicles with liftgate equipment.
- Pallets:Unitized freight moves through dedicated less-than-truckload terminals with forklift-based cross-docking rather than parcel sortation.
Small parcels dominate volume throughput; large parcels command the highest revenue per piece.
End User:
Customer type determines service tier procurement patterns and contract structuring mechanisms.
- E-Commerce:Platform-aggregated volume from online marketplaces drives demand for injection into postal networks and alternative last-mile providers. Returns processing integration shapes contract terms.
- Retailers:Brick-and-mortar chains utilize express services for inter-store inventory balancing and direct-to-customer fulfillment from physical locations.
- Corporations:B2B accounts negotiate guaranteed delivery windows and carbon reporting alignment for supply chain visibility requirements.
- Individuals:Occasional shipper segment purchases services through retail access points and mobile applications with limited loyalty concentration.
E-commerce absorbs the bulk of network volume; corporate accounts sustain premium pricing tiers.
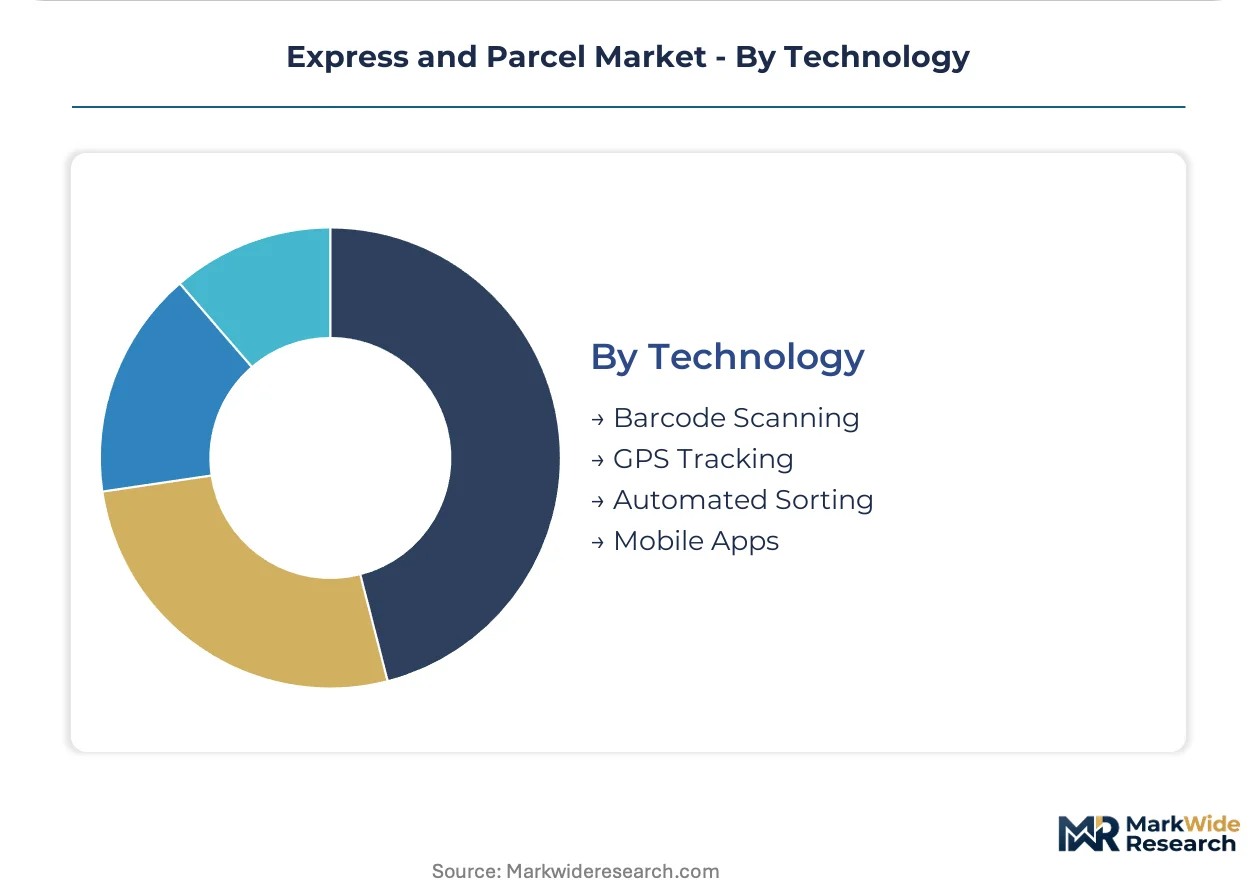
Technology:
Digital infrastructure investments separate operational efficiency leaders from cost-competitive followers.
- Automated Sorting:Robotic parcel singulation and dimensioning systems reduce labor dependency at peak volume periods. European and Chinese superhubs deploy these systems for e-commerce surge capacity.
- GPS Tracking:Real-time location data enables predictive delivery windows and exception management for time-definite commitments.
- Mobile Apps:Customer-facing interfaces consolidate booking, payment, and delivery preference management.
- Barcode Scanning:Legacy data capture infrastructure persists at origin points and delivery confirmation stages.
Automated sorting commands the largest capital allocation; GPS tracking delivers the fastest operational returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones across China, the UAE, and Singapore concentrate express sorting infrastructure and customs-bonded warehousing capacity. These zones attract carrier investment through duty deferral and streamlined clearance protocols. Tax incentives for logistics asset deployment accelerate network densification in corridor economies.
United States
E-commerce volume from Amazon, Walmart, and Target compresses delivery windows toward same-day and next-day commitments. The FAA regulates night-flight operations at Memphis and Louisville superhubs, constraining peak-season air cargo velocity. The Dallas-Fort Worth metroplex anchors ground network consolidation with automated sortation facilities serving cross-border Mexico lanes.
Germany
Industrial B2B parcel demand from automotive and machinery exporters sustains premium express pricing tiers. The EU Green Deal mandates corporate sustainability reporting that accelerates electric van procurement across DHL Group's European road network. The Rhine-Ruhr corridor concentrates last-mile micro-fulfillment nodes serving Benelux and Northern France density.
China
Domestic e-commerce from Alibaba and Pinduoduo drives superhub automation investment at SF Express and ZTO Express facilities. MIIT standards govern cross-border data flows for logistics platforms operating international express lanes. The Yangtze River Delta cluster around Shanghai anchors automated sortation capacity with next-day coverage extending to tier-two interior cities.
India
Flipkart and Amazon India expansion into tier-three cities creates franchise partner opportunities for private express operators. The PLI scheme incentivizes domestic manufacturing of electric commercial vehicles for last-mile fleet deployment. The Mumbai-Pune corridor concentrates pharmaceutical cold-chain infrastructure serving export markets with temperature-validated packaging.
Japan
Aging demographics and pharmaceutical direct-to-patient distribution shift biologics volumes toward specialized temperature-controlled parcel services. METI guidelines align courier certification with PMDA cold-chain protocols for patient-direct delivery. The Kanto region around Tokyo maintains highest last-mile density with automated locker networks reducing failed delivery rates.
Express and Parcel Market Competitive Landscape
Top-tier vendors anchor integrated global networks, while regional specialists and postal incumbents occupy differentiated service tiers. The market structure concentrates around three strategic archetypes: integrators with dedicated air cargo fleets, ground-network specialists with hub-and-spoke density, and platform-integrated last-mile providers. Consolidation pressures favor M&A activity between e-commerce platforms and delivery networks, alongside capacity expansion into underpenetrated secondary cities.
Within the integrator tier, United Parcel Service and FedEx Corporation represent North American hub-and-spoke infrastructure models, while DHL Group exemplifies European pharmaceutical cold-chain certification and emerging market penetration. These entities occupy positions defined by fleet composition, customs brokerage depth, and superhub automation scale rather than interchangeable service commoditization.
| Leading Market Players |
|---|
| United Parcel Service |
| FedEx Corporation |
| DHL Group |
| SF Express |
| Aramex |
| Japan Post Holdings |
| Royal Mail Group |
| Australia Post |
| ZTO Express |
| Others |
Supply & Pricing Matrix
Captive hub-and-spoke infrastructure anchors both supply positioning and pricing power across express networks. Carriers with dedicated superhub assets in Memphis, Louisville, and Leipzig command premium rates for time-definite commitments while insulating margin from third-party sortation costs. The EU Green Deal's scope-three disclosure mandates further entrench integrated operators that control emissions data across owned fleets.
Pricing Analysis
Lead-time compression drives pricing stratification across service tiers. Three-tier pricing structure across premium, standard, and economy levels captures value from same-day urban density through multi-day ground consolidation. Price differentiation rests on guaranteed delivery windows and carbon intensity certification under EU CSRD frameworks. Cost compression in standard ground parcels is intensifying because e-commerce volume aggregates through platform tendering that benchmarks rates across carriers. Small e-commerce shippers exhibit highest price sensitivity; pharmaceutical and financial services accounts sustain premium tiers.
Supply Chain Analysis
Dual-sourcing requirements for electric van procurement mandate multi-supplier qualification across battery cell and powertrain vendors. Supply concentration centers on China for lithium-ion cells, Germany for sorting automation equipment, and the United States for aviation-grade logistics software. Raw material dependencies include lithium carbonate, rare earth magnets, and high-grade aluminum for airframes. Single-source vulnerability in semiconductor-based sortation controllers creates exposure to foundry capacity constraints. Distribution runs through bonded free-trade zones in Singapore, Dubai, and Shanghai that defer duty and accelerate customs clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. The EU Green Deal's mandatory carbon disclosure creates a barrier-to-entry moat for carriers with validated emissions tracking and electrified fleet infrastructure.
For Market Incumbents: Deepen superhub automation density to compress sortation costs per parcel and defend margin against platform-based tendering that aggregates shipper volume. Invest in PMDA-aligned cold-chain certification for pharmaceutical direct-to-patient lanes where METI guidelines favor specialized compliance. Prioritize charging infrastructure retrofit at European depots to maintain contract eligibility under tightening EPA and state-level zero-emission mandates. For New Entrants and Emerging Players: Begin with franchise partner networks in India's tier-three cities where postal infrastructure remains dominant and e-commerce penetration lags metro corridors. Target pharmaceutical cold-chain segments in Japan where aging demographics and biologics distribution shift create demand for PMDA-certified patient-direct delivery. Pursue asset-light aggregation models that inject volume into postal last-mile networks rather than replicating hub infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by e-commerce platforms seeking captive delivery capacity and by integrators acquiring regional cold-chain specialists. Long-term viability favors carriers with scope-three data infrastructure and superhub automation scale that cannot be replicated within a five-to-ten year capital deployment window. Monitor lithium-ion cell supply agreements as the signal indicating which fleet electrification timelines are executable versus aspirational.| Strategic Initiative | Industry Significance |
|---|---|
| Superhub Automation Scale-Up | DHL Group and UPS deployments at European and North American hubs compress labor cost per parcel handled. |
| Electric Fleet Procurement | EPA commercial vehicle standards and California zero-emission mandates accelerate total-cost-of-ownership recalculation. |
| Pharmaceutical Cold-Chain Certification | PMDA-aligned protocols under METI guidelines unlock patient-direct biologics distribution in Japan. |
| Platform-Based Tendering Integration | German and Dutch e-commerce aggregators consolidate parcel spend through centralized carbon and delivery benchmarking. |
| Franchise Network Expansion | Private operators capture share in Indian tier-three cities where Flipkart and Amazon India drive fulfillment demand. |
Research Methodology
Trade flow databases, carrier financial disclosures, and regulatory filings formed the secondary backbone of this analysis. Primary interviews with network operations directors, fleet procurement managers, customs brokerage leads, and e-commerce logistics executives provided operational validation. SEC 10-K filings, EU emissions trading registry data, and MIIT cross-border logistics notifications supplied quantitative anchors. Bottom-up volume modeling triangulated against top-down market sizing across service tiers and geographic clusters.
Historical trendline analysis established baseline growth patterns across express and parcel segments before applying driver-based projection frameworks. Segmentation dimensions modeled include service velocity commitment, package handling requirements, end-user procurement patterns, and technology deployment intensity. CAGRs were derived from elasticity-adjusted volume forecasts incorporating e-commerce penetration curves and fleet electrification timelines. Battery cost trajectories and charging infrastructure buildout schedules informed electric vehicle adoption assumptions.
Underlying measurement precision varies by segment; same-day and next-day delivery carry tighter precision than standard ground due to concentrated carrier reporting. Forecasts reflect assumptions regarding e-commerce volume persistence, regulatory enforcement continuity, and battery supply chain expansion. Deviation in lithium-ion cell availability or FAA night-flight restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Indonesia Alcohol E-Commerce Market
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
Metaverse in E-Commerce Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
North America Dropshipping Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
India E-Commerce Warehousing Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
Resale E-Commerce Platform Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Japan Same Day Delivery Market