
 US Life Coaching Market | 2026-2036
US Life Coaching Market Size, Share, and Industry Trends Forecast 2026-2036
US Life Coaching Market Intelligence
Corporate human resources departments are pivoting toward blended coaching models that combine executive development with mental health support. Torch leverages its platform architecture to anchor enterprise contracts across technology and healthcare employers. Vida Health competes by integrating life coaching with chronic condition management, creating stickier payer relationships. The Life Coach School differentiates through proprietary certification pathways that command premium pricing from independent practitioners seeking credential differentiation.
Life coaching constitutes a structured, goal-oriented intervention delivered through one-on-one or group sessions designed to enhance personal or professional performance without clinical therapeutic intent. Practitioners typically employ evidence-based frameworks such as GROW or cognitive-behavioral techniques, with session structures ranging from thirty minutes to two hours depending on client objectives and delivery modality. The coaching niche dimension shows health and wellness commanding the largest revenue pool, while career coaching exhibits the fastest trajectory as labor market churn elevates transition demand. Delivery method segmentation reveals online platforms capturing disproportionate growth, though in-person retains margin concentration in C-suite engagements where relationship depth justifies premium pricing.
The International Coach Federation accreditation framework shapes market access by establishing baseline competency standards that corporate procurement departments increasingly require in vendor selection. State regulatory bodies in California and Texas are scrutinifying scope-of-practice boundaries between licensed counselors and unlicensed coaches, creating compliance complexity for multi-state operators. Stakeholders must monitor evolving definitions of coaching versus therapy as enforcement actions by state attorney general offices could reshape liability structures and insurance reimbursement eligibility.
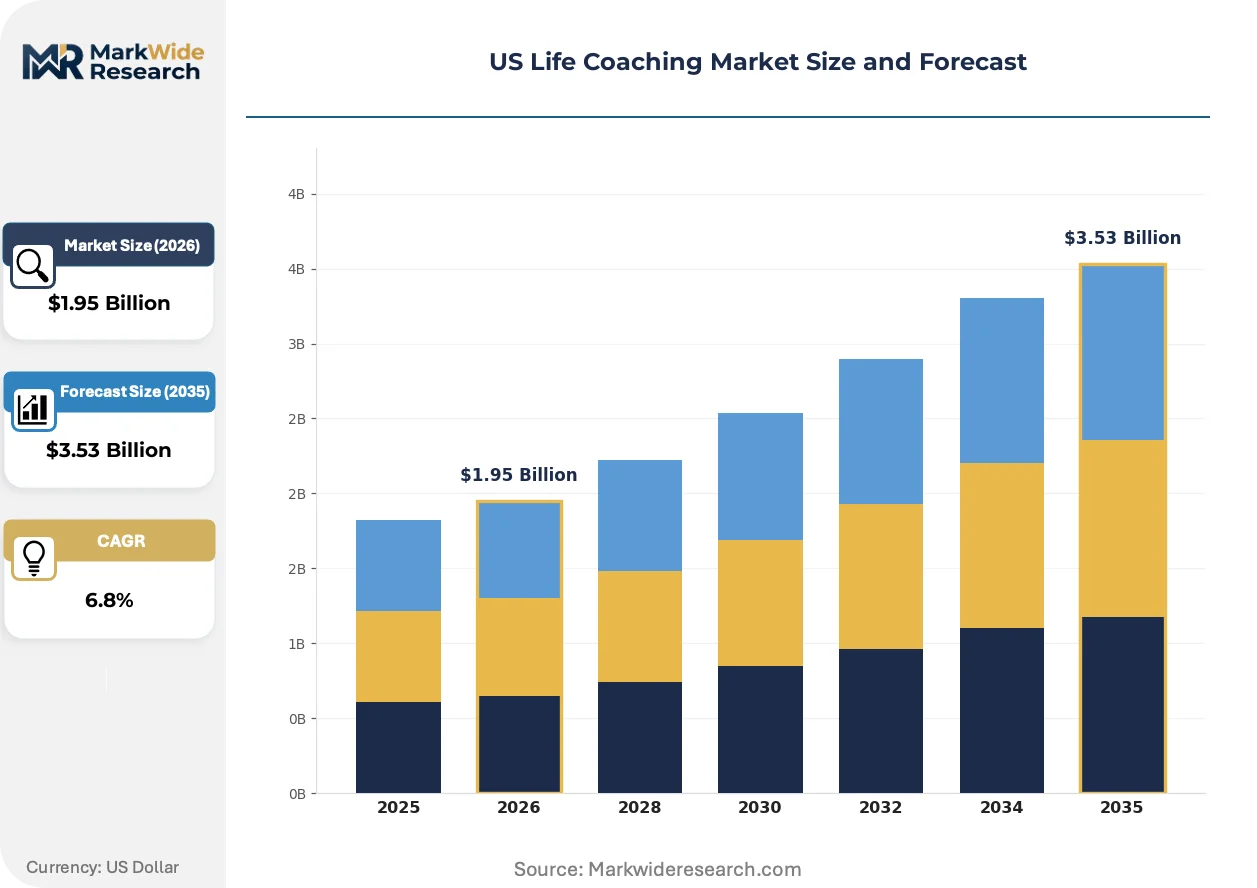
Market Dynamics
Corporate wellness program expansion at Fortune 500 employers is restructuring demand architecture for executive coaching services, while state-level occupational licensing debates in California and New York reshape practitioner credential requirements and market access conditions.
Growth Catalysts
- Remote-work migration:Metropolitan clusters across Texas, Florida, and Illinois are generating concentrated demand for career-transition coaching as professionals relocate and seek occupational pivots.
- ICF accreditation framework:Corporate procurement departments increasingly mandate baseline competency standards from the International Coach Federation in vendor selection processes.
- Chronic condition integration:Payer relationships are strengthening where life coaching bundles with health management services, creating stickier contract structures.
Market Restraints
- Scope-of-practice ambiguity:State attorney general offices in California and Texas are scrutinifying boundary definitions between licensed counselors and unlicensed coaches, elevating compliance costs.
- Credential fragmentation:Proprietary certification pathways from independent training institutions create non-transferable qualifications that limit practitioner mobility across state lines.
- Insurance reimbursement exclusion:Life coaching services lack eligibility under most employer-sponsored health plans and commercial payer networks, constraining addressable wallet share.
Strategic Opportunities
- Blended coaching models:Human resources departments are combining executive development with mental health support, opening integrated service contracts.
- Online platform delivery:Digital infrastructure investments by technology and healthcare employers are capturing disproportionate growth in session volume.
- C-suite in-person retention:Relationship-depth requirements at senior executive levels justify premium pricing for face-to-face engagements that resist platform commoditization.
Industry Challenges
- Talent pipeline constraints:Practitioners seeking differentiation through proprietary certification pathways face extended training timelines and elevated tuition costs.
- Multi-state operational complexity:Compliance with divergent state regulatory postures requires legal infrastructure that disadvantages independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Life Coaching Market |
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: Individuals, Corporate Clients, Groups, Athletes Coaching Niche: Career Coaching, Health & Wellness, Personal Development, Relationship Coaching Delivery Method: In-person, Online, Telephone, Workshops Coaching Certification: IAPRC Certification, ICF Accreditation, LCSW Credential, Others |
| Companies Covered | Hone Group Inc., Allego, Vida Health, iPEC (Institute for Professional Excellence in Coaching), The Life Coach School, ReUp Education, Torch, Coach U, Pathrise, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Life Coaching Market Strategic Shifts & Innovations
Platform-based delivery architectures are restructuring how coaching services reach enterprise buyers and individual consumers, compressing traditional intermediary layers while enabling new data-driven personalization capabilities.
Artificial intelligence-powered session scheduling and progress tracking is overtaking manual coordination methods in employer-sponsored programs. Technology sector human resources departments are adopting these tools at accelerated paces to manage dispersed workforces. The shift is compressing administrative overhead and enabling outcome measurement that strengthens contract renewal rates.
State regulatory bodies in California and New York are actively debating occupational licensing frameworks that would impose formal credential requirements on life coaching practitioners. The industrial consequence is elevated compliance preparation costs for multi-state operators and potential market exit by uncredentialed independents. Corporate procurement departments are responding by tightening vendor qualification standards ahead of statutory mandates.
Enterprise buyers are consolidating vendor relationships around platforms that demonstrate measurable return-on-investment metrics for coaching engagements. Traditional hourly billing structures are yielding to packaged outcome guarantees in technology and healthcare employer contracts. This pattern is most visible in metropolitan clusters across Texas and Illinois where remote-work migration has intensified competition for talent retention budgets.
US Life Coaching Market Segmentation
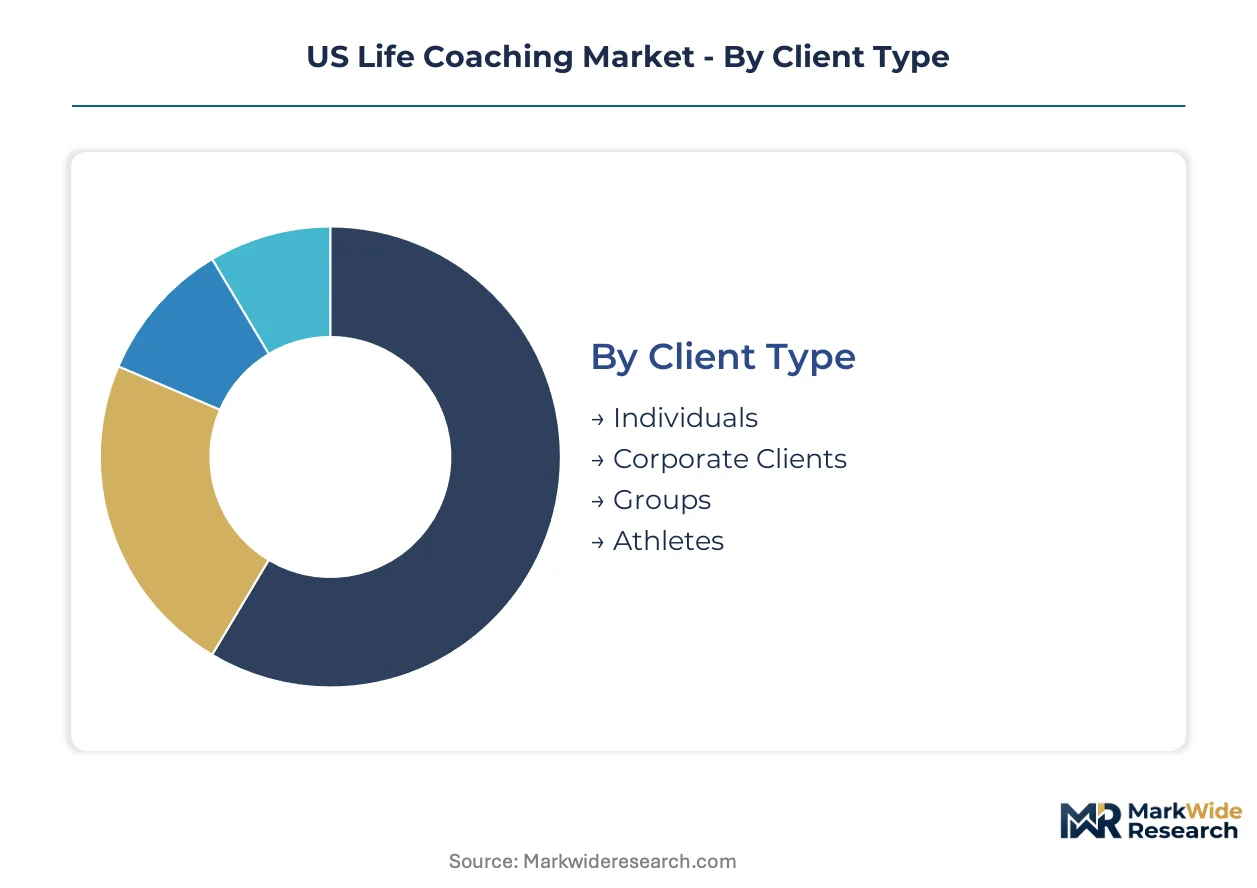
Segmentation in the US life coaching market reveals distinct procurement patterns across client types and delivery modalities. Corporate buyers prioritize scalable platforms while individual consumers seek specialized niche expertise.
Client Type:
Technology architecture and session scalability define how practitioners structure their service portfolios across client categories.
- Corporate Clients:Fortune 500 human resources departments contract for executive development programs spanning leadership transitions and team alignment. Procurement concentrates in technology and healthcare employers across Texas and Illinois metropolitan clusters where remote-work migration has intensified talent retention pressures.
- Individuals:Solo practitioners seeking career pivots or personal transitions purchase single-session or packaged engagements. Demand clusters in Florida and California where state-level occupational licensing debates are reshaping credential requirements and consumer trust thresholds.
- Groups:Cohort-based coaching delivers cost efficiency for mid-level professionals navigating similar transitions. Employers in Illinois and Texas favor this format for manager development at scale.
- Athletes:Performance optimization for collegiate and professional competitors requires specialized mental conditioning protocols. NCAA institutions and professional sports franchises in Florida and California represent primary contract sources.
Mature deployment sits with Corporate Clients. Newer deployment is concentrated in Athletes as sports psychology integration accelerates.
Coaching Niche:
Margin concentration and certification complexity vary sharply across specialty domains, with health-related niches commanding distinct regulatory scrutiny.
- Health & Wellness:Chronic condition management integration creates stickier payer relationships when bundled with clinical services. Vida Health competes in this space by combining life coaching with disease management for technology and healthcare employers.
- Career Coaching:Labor market churn in Texas, Florida, and Illinois metropolitan areas generates concentrated demand for occupational transition support. This segment is expanding most quickly as remote-work migration intensifies professional relocation needs.
- Personal Development:Goal-setting frameworks like GROW dominate session structures for clients seeking accountability systems. Independent practitioners in California and New York differentiate through proprietary methodologies.
- Relationship Coaching:Couples and family dynamics work operates closest to licensed counseling boundaries, elevating compliance preparation costs in California and Texas where state attorney general offices scrutinize scope-of-practice definitions.
Margin concentration sits with Health & Wellness. Volume expansion is concentrated in Career Coaching.
Delivery Method:
Platform infrastructure investments by enterprise buyers are compressing traditional in-person intermediaries while enabling outcome measurement capabilities.
- Online:Artificial intelligence-powered scheduling and progress tracking overtakes manual coordination in employer-sponsored programs. Technology sector human resources departments adopt these tools at accelerated paces to manage dispersed workforces across state lines.
- In-person:C-suite engagements in Texas and Illinois retain premium pricing where relationship depth justifies face-to-face investment. Executive coaching contracts at Fortune 500 firms anchor this modality.
- Telephone:Audio-only sessions persist for rural clients and accessibility-focused programs. Medicare Advantage plans in Florida experiment with this format for senior wellness coaching.
- Workshops:Intensive multi-day formats concentrate demand for team alignment and corporate culture initiatives. Corporate wellness programs in healthcare and technology sectors favor this structure for leadership cohorts.
Enterprise procurement sits with Online. Premium retention is concentrated in In-person.
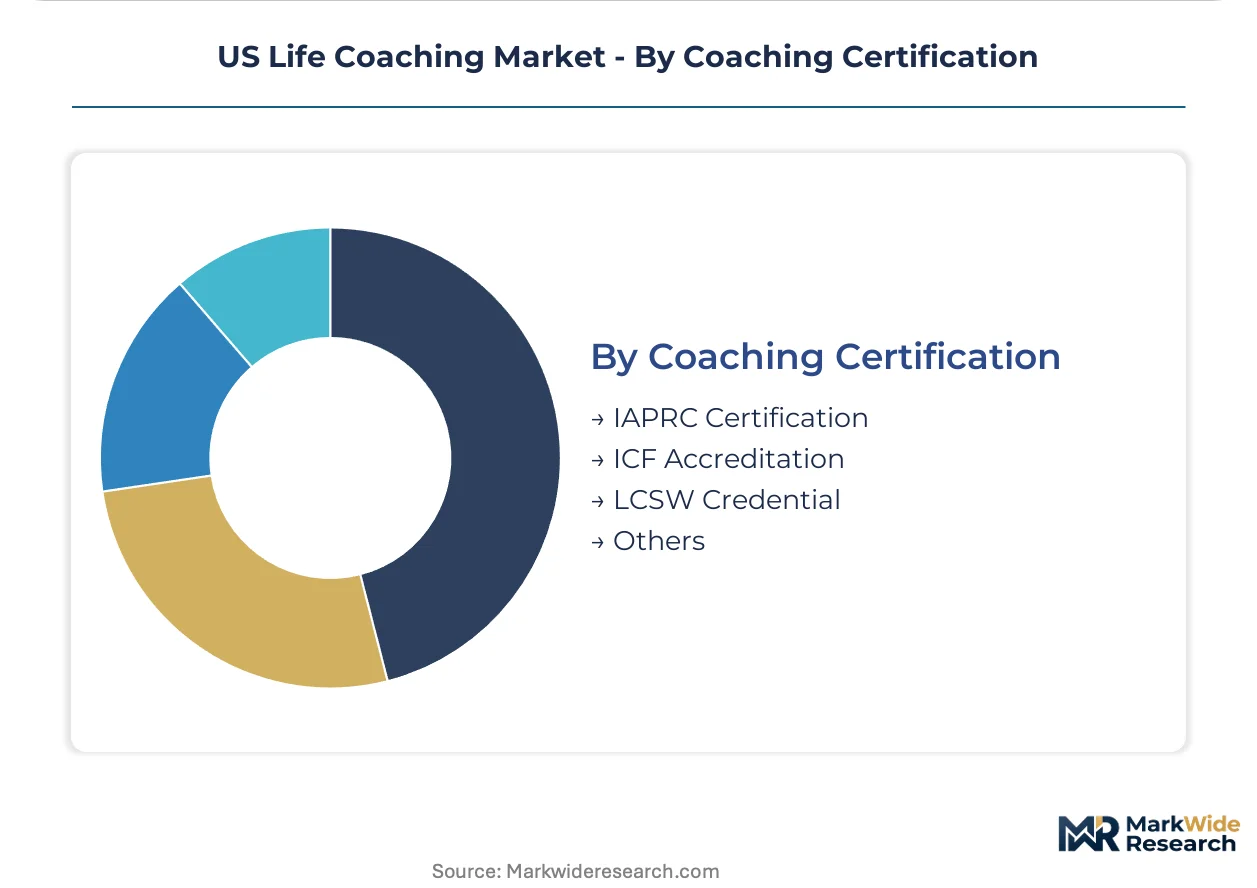
Coaching Certification:
Credential recognition and transferability determine practitioner mobility across state regulatory environments, with corporate procurement tightening qualification standards.
- ICF Accreditation:The International Coach Federation framework establishes baseline competency standards that corporate procurement departments increasingly mandate in vendor selection. Multi-state operators prioritize this credential for compliance simplicity.
- IAPRC Certification:Specialized pathways for relationship and wellness coaching carry variable recognition across state lines. California and New York licensing debates are elevating this credential's visibility.
- LCSW Credential:Licensed clinical social workers bridge coaching and therapy boundaries, reducing regulatory risk in scope-of-practice scrutiny. Healthcare employers in Texas and Illinois favor this qualification for integrated service contracts.
- Others:Proprietary certifications from independent training institutions create non-transferable qualifications that limit practitioner mobility. The Life Coach School commands premium pricing for its differentiated pathway.
Corporate standardization sits with ICF Accreditation. Regulatory hedging is concentrated in LCSW Credential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan opportunity zones in Texas, Florida, and Illinois concentrate coaching demand through remote-work migration incentives and corporate relocation packages. State-level regulatory divergence creates compliance complexity for multi-state operators.
Texas
Corporate headquarters migration to Dallas-Fort Worth and Austin generates executive coaching contracts at technology and healthcare employers. The Texas Workforce Commission administers skills development grants that subsidize career-transition coaching for displaced workers. Houston's energy sector employers anchor premium in-person engagements for leadership cohorts.
California
State attorney general scrutiny of scope-of-practice boundaries elevates compliance preparation costs for unlicensed practitioners. The California Department of Consumer Affairs debates occupational licensing frameworks that would impose formal credential requirements. San Francisco Bay Area technology employers drive demand for blended coaching models integrating executive development with mental health support.
Illinois
Chicago metropolitan employers consolidate vendor relationships around platforms demonstrating measurable return-on-investment metrics for coaching engagements. The Illinois Department of Commerce and Economic Opportunity funds workforce development programs incorporating career coaching. Corporate wellness program expansion at Fortune 500 firms headquartered in the region restructures demand architecture for executive services.
Florida
Medicare Advantage plans experiment with audio-only wellness coaching formats for senior populations in Miami-Dade and Tampa Bay markets. The Florida Department of Health monitors boundary definitions between licensed counselors and unlicensed coaches. NCAA institutions and professional sports franchises in Orlando and Jacksonville represent primary contract sources for athlete performance optimization.
New York
State-level occupational licensing debates reshape practitioner credential requirements and consumer trust thresholds in the New York City metropolitan area. The New York State Education Department scrutinizes proprietary certification pathways from independent training institutions. Financial services employers in Manhattan anchor premium pricing for C-suite in-person engagements where relationship depth justifies face-to-face investment.
US Life Coaching Market Key Industry Players
Top-tier vendors anchor enterprise platform contracts, while independent certification providers occupy the practitioner-enablement tier. The market structure reflects dual concentration: technology-enabled coaching platforms serving corporate procurement departments, and proprietary training institutions commanding premium tuition from independent practitioners seeking credential differentiation. Three archetypes dominate: integrated health-coaching hybrids, pure-play executive development platforms, and certification-centric educator-practitioners. Competitive moves center on strategic partnerships with healthcare payers and portfolio diversification into adjacent mental health services.
Within the integrated health-coaching tier, Vida Health and Torch represent archetypes of platform-based delivery architectures restructuring enterprise procurement. The Life Coach School occupies a position within the certification-centric tier, exemplifying proprietary pathway providers that differentiate through non-transferable qualifications. These three entities anchor distinct competitive vectors: payer-integrated health management, technology-enabled executive development, and practitioner credential premiumization.
| Leading Market Players |
|---|
| Hone Group Inc. |
| Allego |
| Vida Health |
| iPEC (Institute for Professional Excellence in Coaching) |
| The Life Coach School |
| ReUp Education |
| Torch |
| Coach U |
| Pathrise |
| Others |
Cost & Logistics Intelligence
Fortune 500 corporate procurement departments concentrate contract volume and anchor subscription-based pricing models across the US life coaching market. Platform vendors command annual commitments while independent practitioners compete through session packages.
Pricing Analysis
Short lead-time premiums apply to executive coaching engagements booked within two weeks, while extended booking windows unlock standard-rate access. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and session modality. Cost compression in the independent practitioner tier is intensifying because platform aggregators consolidate demand and squeeze margins. Individual consumers exhibit highest price sensitivity, whereas C-suite buyers prioritize relationship depth over rate negotiation.
Supply Chain Analysis
Freight and travel reimbursement costs concentrate in the in-person delivery tier, elevating total engagement expense for geographically dispersed corporate clients. Practitioner supply draws from California, New York, and Texas training pipelines, with credential issuance resting on ICF-accredited institutions and proprietary academies. Single-source vulnerability emerges where dominant certification providers control practitioner pipeline access. Distribution runs through direct platform subscriptions for enterprise buyers and referral networks for independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Practitioner supply constraints prop pricing power for credentialed coaches, with ICF accreditation bottlenecks limiting rapid market entry.
For Market Incumbents: To counter platform-aggregator margin compression, Torch and Vida Health should deepen proprietary certification partnerships and secure exclusive enterprise channel control. Capacity addition in Texas and Illinois metropolitan clusters captures remote-work migration demand. Certification investment in ICF-aligned pathways strengthens procurement eligibility ahead of state licensing mandates. For New Entrants and Emerging Players: AI-powered scheduling platforms offer the lowest barrier-to-market entry for technology-enabled coaching delivery. White-space concentration sits with Medicare Advantage wellness coaching in Florida and athlete performance optimization at NCAA institutions. Direct employer pilot programs bypass incumbent platform relationships and establish proof-of-concept traction. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated health-coaching hybrids in California and Texas where regulatory scrutiny elevates compliance costs for uncredentialed independents. Five-to-ten-year viability hinges on payer relationship durability and outcome measurement infrastructure. The signal to watch is state attorney general enforcement actions redefining coaching-therapy boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| ICF Accreditation Investment | Corporate procurement departments at technology and healthcare employers mandate this credential in vendor selection processes. |
| Platform Integration Partnership | Torch leverages its architecture to anchor enterprise contracts across dispersed workforces in Texas and Illinois. |
| Chronic Condition Bundling | Vida Health strengthens payer relationships by combining life coaching with disease management services. |
| Geographic Expansion | Metropolitan clusters in Florida and California concentrate demand from remote-work migration and sports franchise contracts. |
| Proprietary Certification Pathway | The Life Coach School commands premium tuition from practitioners seeking non-transferable credential differentiation. |
Research Approach
Multi-period observation of ICF credential issuance rates, platform subscription growth, and state regulatory filing volumes anchored the trend analysis, supplemented by interviews with coaching platform executives, corporate HR procurement officers, independent practitioners, and state regulatory staff. Secondary validation drew from SEC filings of publicly traded wellness platforms, state attorney general enforcement records, ICF membership databases, and corporate wellness program RFP documents. Bottom-up practitioner supply estimates and top-down enterprise spending analysis were triangulated to cross-check market sizing.
Input-output matrices modeled coaching hours delivered against client acquisition costs and retention rates across the projection horizon. Segmentation dimensions included client type, coaching niche, delivery method, and certification pathway. CAGRs were derived from regression analysis of historical platform growth and practitioner pipeline expansion. Forecast inputs incorporated remote-work migration patterns and state licensing probability assessments.
Inputs from ICF membership databases and state regulatory filings were available through the study window; gaps in uncredentialed independent practitioner income data introduce uncertainty bands around individual consumer segment estimates. Forecasts reflect assumptions about regulatory enforcement intensity and corporate wellness budget allocation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Human Resource Professional Services Market
Professional Development and Training
GCC Soft Skills Training Market
Professional Development and Training
HSE Consulting Training Services Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
Executive Education Program Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
Equipment Maintenance Training Services Market
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
North America IT Training Market
Professional Development and Training
Coding Bootcamp Market
Professional Development and Training
Business Coaching Service Market
Professional Development and Training
Technical and Vocational Education Market
Professional Development and Training
Global Social and Emotional Learning (SEL) Market
Professional Development and Training
HR Professional Services Market
Professional Development and Training
Canada Executive Education Program Market