
 HR Professional Services Market | 2026-2036
HR Professional Services Market Size, Share, and Industry Trends Forecast 2026-2036
HR Professional Services Market Outlook
Workforce analytics and talent platform licensing is reconfiguring margin pools away from traditional staffing placement toward recurring SaaS-based advisory models. Randstad NV leverages its global delivery network to embed AI-driven candidate matching into enterprise contracts. Mercer LLC anchors its position through proprietary compensation benchmarking databases that sustain multi-year client retention. Accenture differentiates by integrating HR transformation consulting with cloud-based human capital management implementations.
HR professional services encompass the external provision of workforce management functions including recruitment process outsourcing, learning and development program design, payroll tax compliance administration, and benefits brokerage, typically delivered through dedicated technology platforms with service-level agreements governing accuracy and response times. The service type dimension shows payroll services and employee benefits commanding the most stable margin pools due to regulatory complexity and switching costs, while recruitment services face faster growth but greater fee pressure from automated sourcing tools. Delivery model segmentation reveals hybrid consulting arrangements expanding fastest as clients demand both virtual self-service portals and on-site strategic advisors for change management.
OSHA workplace safety mandates, the EU AI Act's employment algorithm provisions, and India's PLI scheme labor compliance requirements collectively elevate demand for specialized HR regulatory advisory across multiple jurisdictions. ISO 30414 human capital reporting standards further shape product specifications by requiring auditable workforce metrics that drive technology investment in reporting infrastructure. Stakeholders must monitor how generative AI tools reshape the cost structure of candidate screening and whether regulatory bodies impose algorithmic accountability rules that favor established compliance-oriented service providers over automation-first entrants.
Market Dynamics
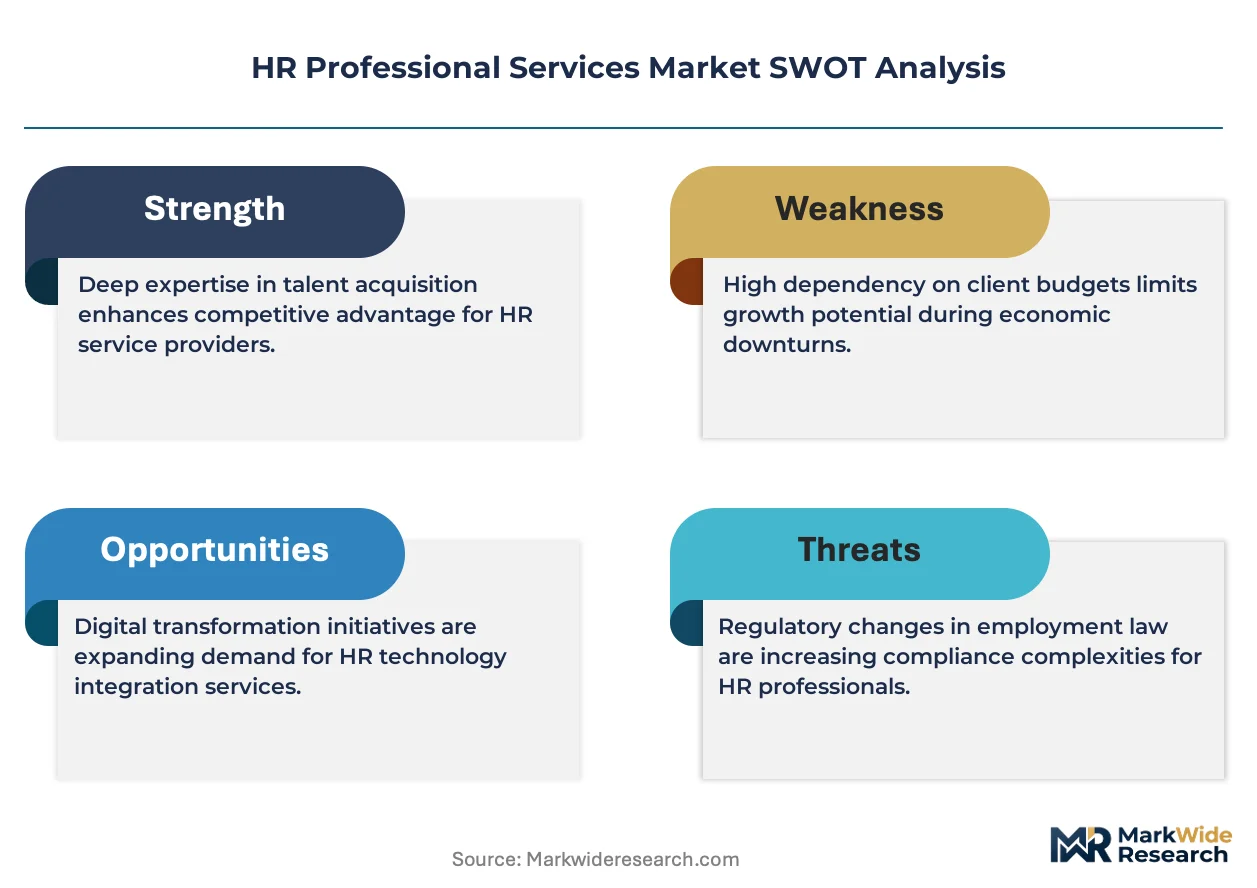
Generative AI is compressing the cost structure of candidate screening and workforce analytics, forcing established providers to reconfigure service delivery models around algorithmic accountability and human-in-the-loop validation protocols.
Growth Catalysts
- EU AI Act employment algorithm provisions:European employers face mandatory risk classification for automated hiring tools, creating specialized advisory demand for compliance architecture and audit documentation.
- Cloud-based human capital management platforms:Enterprise technology firms are consolidating vendor relationships around integrated payroll, benefits, and workforce analytics suites with multi-year service-level agreements.
- ISO 30414 human capital reporting standards:Auditable workforce metrics requirements are driving technology investment in reporting infrastructure across publicly traded employers in Germany, France, and the United Kingdom.
Market Restraints
- Algorithmic liability concentration:Automated decision-making in hiring and performance management creates uninsurable legal exposure in jurisdictions with strict anti-discrimination frameworks.
- Specialized compliance talent scarcity:Shortage of professionals credentialed in both employment law and machine learning operations limits service expansion velocity.
- Legacy system integration friction:Enterprise clients maintain decades-old payroll and benefits administration infrastructure with proprietary data formats resistant to API standardization.
Strategic Opportunities
- India PLI scheme labor compliance requirements:Manufacturing incentives tied to workforce documentation standards are creating localized advisory demand for statutory compliance and industrial relations management.
- Skills-based credentialing platforms:Micro-certification verification systems are converging with applicant tracking systems to create new subscription revenue streams in technical and healthcare staffing verticals.
- Contingent workforce management:Platform-based gig worker classification and benefits portability solutions represent underdeveloped white space in jurisdictions with evolving independent contractor definitions.
Industry Challenges
- Cross-border data residency requirements:GDPR localization mandates and emerging national data sovereignty laws fragment cloud infrastructure deployment and increase operational complexity for multi-country service delivery.
- Generative AI output validation:Hallucination risks in automated candidate matching and compensation benchmarking demand costly human oversight layers that erode automation-driven margin expansion.
- Client consolidation of vendor relationships:Procurement departments are reducing preferred supplier lists from dozens of specialized agencies to single-source integrated workforce solutions, compressing mid-tier provider survival rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HR Professional Services Market |
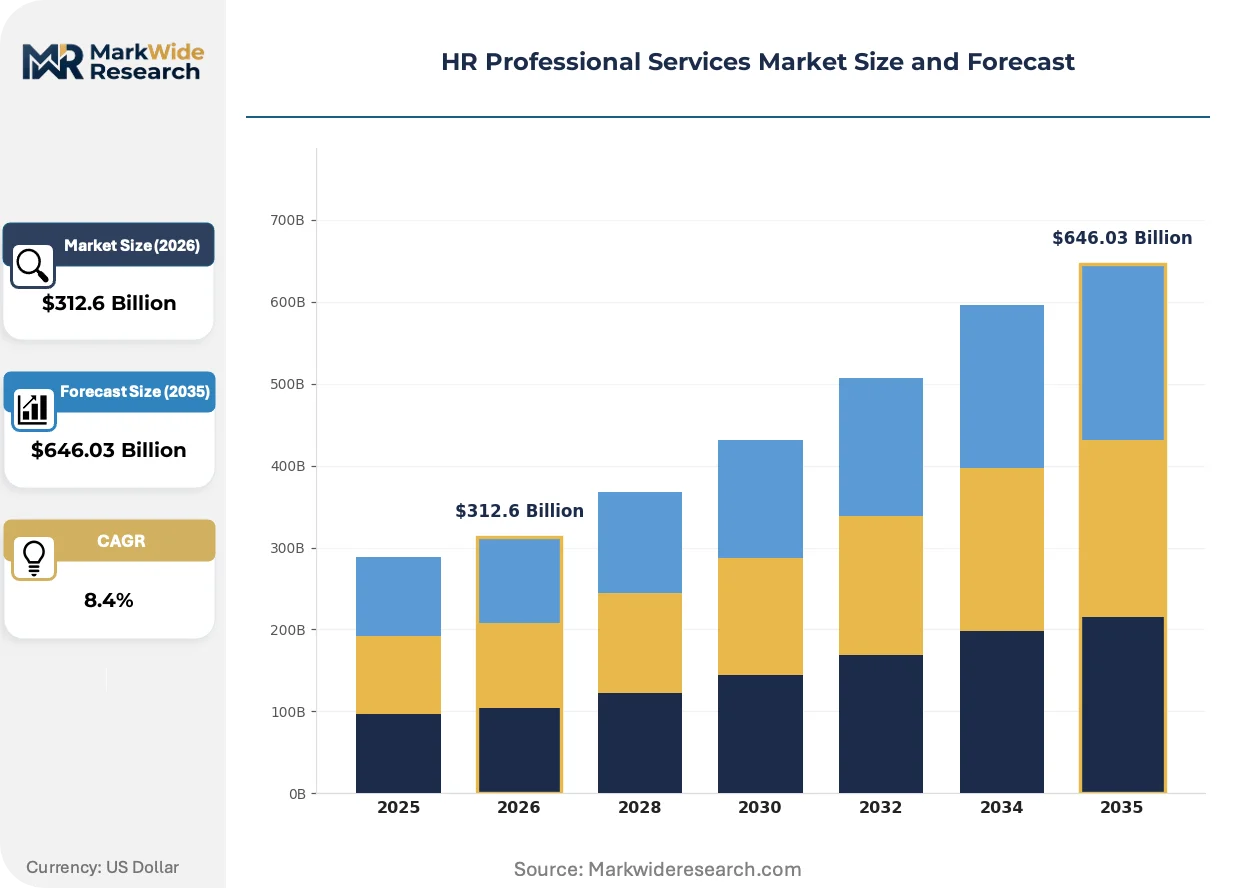
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recruitment, Employee Training, Payroll Services, Employee Benefits Delivery Model: On-site, Remote Consulting, Hybrid, Outsourced Client Type: Small Enterprises, Large Corporations, Nonprofits, Startups Industry Vertical: Manufacturing, Technology, Healthcare, Retail |
| Companies Covered | ADP, Randstad NV, Adecco Group, ManpowerGroup, Korn Ferry, Accenture, Ernst & Young Global Limited, Mercer LLC, Robert Half, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HR Professional Services Market Strategic Shifts
Workforce management technology is converging with embedded finance and real-time analytics, compressing the traditional separation between transactional HR administration and strategic human capital advisory.
AI-driven candidate matching engines are virtualizing the traditional recruiter function by automating sourcing, screening, and initial engagement workflows. Large enterprise employers in technology and financial services are deploying these systems at scale, reducing time-to-fill metrics by eliminating manual resume review. The technology is virtualizing margin pools away from placement fees toward recurring platform licensing arrangements with outcome-based performance guarantees.
The EU AI Act's risk-based classification system for employment-related algorithms is mandating human oversight documentation and bias testing protocols. Providers serving European multinational employers must now maintain algorithmic impact assessments and conformity declarations as deliverable artifacts. This regulatory architecture most affects recruitment process outsourcing contracts, where vendors are embedding compliance specialists and audit trails into standard service definitions.
Subscription-based workforce analytics is displacing project-based compensation benchmarking engagements. Chief human resource officers in the United States and United Kingdom are consolidating spend around platforms delivering real-time pay equity analysis and flight-risk modeling. This procurement model change compresses traditional consulting revenue cycles and rewards providers with proprietary data assets and machine learning infrastructure over relationship-driven advisory practices.
HR Professional Services Market Segmentation
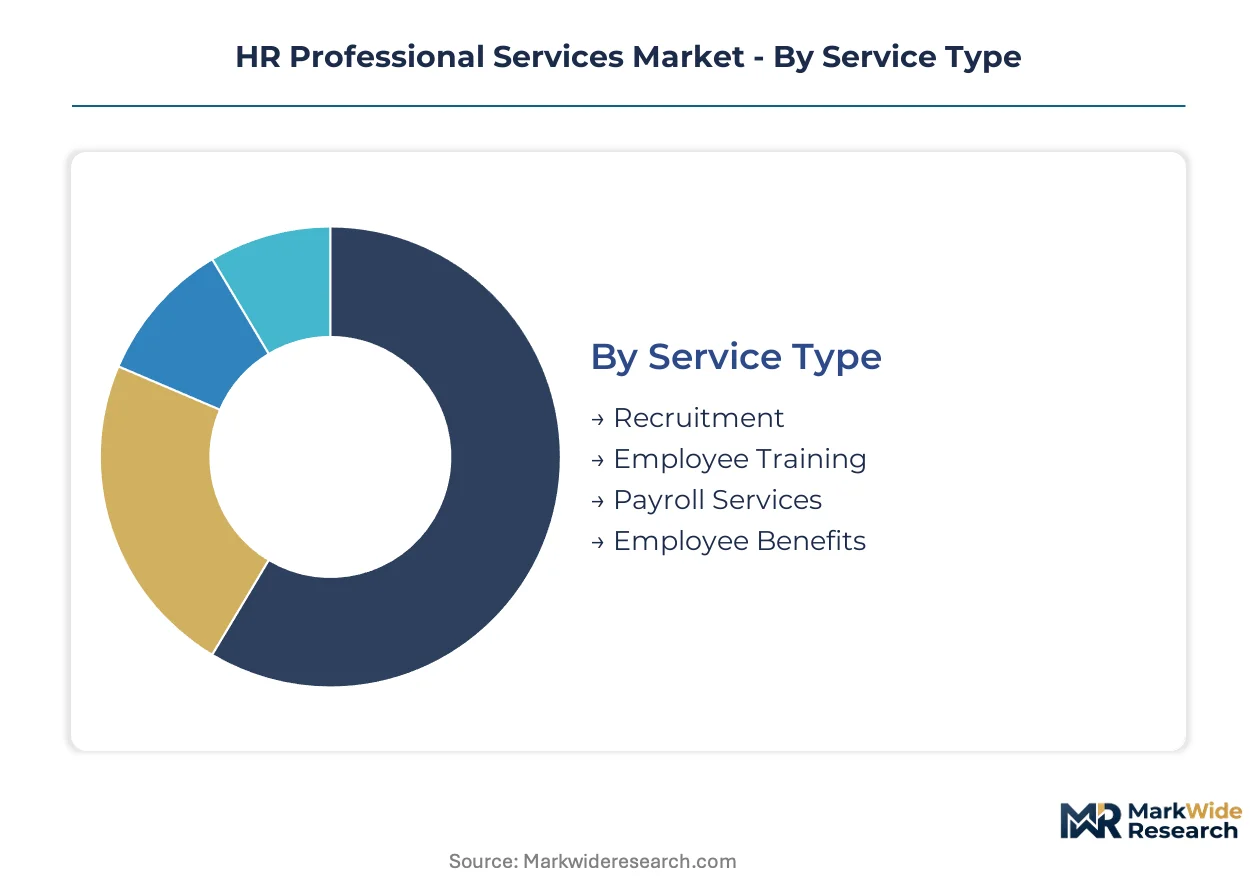
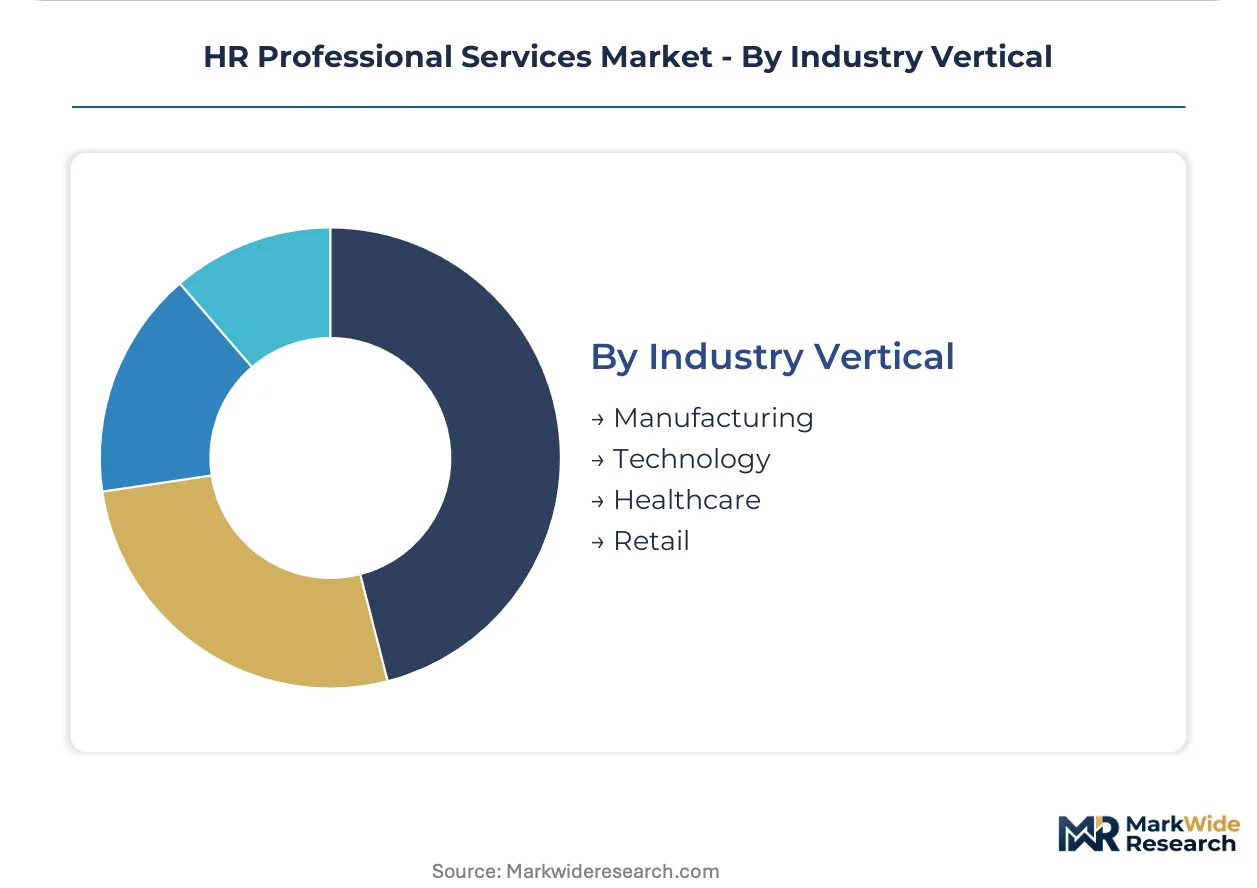
HR professional services segment along four intersecting dimensions that determine pricing power, contract duration, and technology intensity. Service type and delivery model together shape margin architecture, while client scale and industry vertical dictate compliance complexity and solution customization requirements.
Service Type:
Mature regulatory administration services coexist with emerging AI-enabled talent platforms across this spectrum.
- Recruitment:Sourcing and placement functions are migrating toward algorithmic candidate matching engines with outcome-based fee structures. Technology firms in the United States and United Kingdom are consolidating vendor relationships around platforms that automate resume screening and initial engagement workflows, compressing traditional placement margins while expanding recurring licensing revenue pools.
- Payroll Services:Tax compliance administration and wage calculation systems anchor the most stable margin pools due to jurisdictional regulatory complexity and high client switching costs. Enterprise demand concentrates in the United States and Germany where multi-state and multi-country employment tax frameworks require specialized expertise and auditable accuracy guarantees.
- Employee Training:Learning and development program design spans compliance-mandated certifications to leadership coaching engagements, delivered through both synchronous virtual sessions and asynchronous module libraries.
- Employee Benefits:Brokerage and administration of health insurance, retirement plans, and wellness programs sustains multi-year client relationships through proprietary plan design expertise and carrier negotiation leverage.
Payroll services handles the majority of throughput; recruitment is expanding most quickly on share.
Delivery Model:
Cost tier differentiation separates premium integrated advisory from transactional self-service portals.
- Hybrid:Combinations of virtual self-service platforms with on-site strategic advisors for change management are expanding fastest as enterprise clients demand both efficiency and high-touch transformation support. This model commands premium pricing in the United States and United Kingdom where CHROs prioritize workforce analytics implementation alongside executive coaching.
- Outsourced:Full function delegation through multi-year service-level agreements governs accuracy and response times for payroll, benefits, and compliance administration. Manufacturing employers in Germany and France favor this model to manage statutory workforce documentation requirements without building captive HR infrastructure.
- On-site:Embedded consultants and dedicated staff augmentation place personnel within client facilities for immediate response and cultural integration.
- Remote Consulting:Virtual advisory engagements delivered through video conferencing and collaborative platforms enable geographic flexibility and cost efficiency for standardized compliance and policy projects.
Outsourced arrangements capture the largest contract value; hybrid delivery is gaining share fastest.
Client Type:
Volume concentration and margin profile diverge sharply across organizational scale and lifecycle stage.
- Large Corporations:Enterprise technology and financial services firms in the United States drive integrated platform adoption, consolidating spend around vendors offering payroll, benefits, and workforce analytics through unified cloud architectures with multi-year SLAs.
- Small Enterprises:Professional employer organizations and administrative services organizations deliver bundled HR compliance and benefits access that would be uneconomical to build internally.
- Startups:Venture-backed technology companies prioritize scalable applicant tracking and equity compensation administration to support rapid headcount expansion.
- Nonprofits:Mission-driven organizations require specialized grant compliance reporting and volunteer workforce management capabilities distinct from commercial sector solutions.
Large corporations contribute the dominant share of revenue; startups are climbing fastest on contract velocity.
Industry Vertical:
Application-specific compliance requirements and workforce composition shape solution customization depth.
- Healthcare:Credential verification, continuing education tracking, and shift scheduling optimization dominate HR service specifications for hospital systems and clinical staffing agencies. HIPAA compliance requirements and joint commission standards create specialized advisory demand in the United States.
- Technology:Skills-based credentialing platforms, equity compensation administration, and distributed workforce management define service requirements for software and platform companies with globally dispersed engineering teams.
- Manufacturing:Industrial relations management, OSHA workplace safety compliance, and shift-based payroll administration characterize HR service needs for production facilities.
- Retail:High-volume hourly hiring, seasonal workforce scaling, and distributed location management drive demand for streamlined applicant tracking and mobile-first scheduling platforms.
Healthcare commands the highest compliance-driven pricing; technology is the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider concentration clusters in jurisdictions with complex employment tax frameworks and stringent workforce documentation requirements. The United States, Germany, United Kingdom, India, and Japan collectively anchor the majority of contract value through distinct regulatory and industrial drivers.
United States
Enterprise technology and financial services firms drive integrated platform adoption for payroll, benefits, and workforce analytics. OSHA workplace safety mandates and multi-state employment tax frameworks create specialized advisory demand. New York and San Francisco metropolitan areas concentrate headquarters procurement decisions for cloud-based human capital management suites.
Germany
Manufacturing employers favor outsourced arrangements to manage statutory workforce documentation without building captive HR infrastructure. ISO 30414 human capital reporting standards drive technology investment in auditable workforce metrics. Industrial clusters in Bavaria and North Rhine-Westphalia anchor contract value for compliance-oriented service delivery.
United Kingdom
Chief human resource officers consolidate spend around platforms delivering real-time pay equity analysis and flight-risk modeling. GDPR compliance requirements push employers toward specialized HR advisory services for cross-border data residency. London anchors procurement for subscription-based workforce analytics displacing project-based engagements.
India
Manufacturing incentives tied to workforce documentation standards under the PLI scheme create localized advisory demand for statutory compliance. Technology firms expand reliance on outsourced talent acquisition and workforce analytics platforms. Karnataka and Telangana concentrate delivery center operations for global recruitment process outsourcing contracts.
Japan
Enterprise clients seek integrated payroll and benefits administration solutions with multi-year service-level agreements. METI industrial policy shapes human capital reporting requirements for publicly traded employers. Tokyo and Osaka metropolitan areas concentrate demand for hybrid consulting arrangements combining virtual platforms with on-site strategic advisors.
HR Professional Services Market Competitive Environment
Global staffing networks and technology consulting conglomerates split the market between relationship-driven placement economics and platform-based recurring revenue models. The vendor base organizes around three strategic archetypes: integrated workforce solutions providers, specialized compensation and benefits advisors, and cloud-native human capital management platforms. Dominant competitive moves include embedding AI-driven candidate matching into enterprise contracts and consolidating multi-year service-level agreements that span payroll, benefits, and analytics functions.
Within the integrated workforce solutions tier, Randstad NV and ManpowerGroup exemplify global delivery networks that have reconfigured margin pools toward recurring SaaS-based advisory models. Mercer LLC occupies a position as a specialized compensation benchmarking database provider sustaining multi-year client retention through proprietary data assets. Accenture anchors the technology consulting archetype by integrating HR transformation advisory with cloud-based human capital management implementations.
| Leading Market Players |
|---|
| ADP |
| Randstad NV |
| Adecco Group |
| ManpowerGroup |
| Korn Ferry |
| Accenture |
| Ernst & Young Global Limited |
| Mercer LLC |
| Robert Half |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure concentration in the United States anchors margin pools downstream in hybrid consulting arrangements, where enterprise clients absorb premium pricing for on-site strategic advisors layered atop virtual self-service platforms.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European recruitment process outsourcing contracts, mandating algorithmic impact assessments and conformity declarations that separate premium compliance-oriented providers from economy-tier automation-first entrants. ISO 30414 certification tiers further stratify pricing in Germany and the United Kingdom, where auditable workforce metrics command sustained multi-year engagements. Pricing pressure stems from generative AI compression of candidate screening costs, eroding traditional placement fee margins. Small enterprises exhibit highest price sensitivity, while large corporations in technology and financial services prioritize outcome-based performance guarantees over unit cost minimization.
Supply Chain Analysis
Export control regimes limiting cross-border data flows under GDPR localization mandates fragment cloud infrastructure deployment and elevate operational complexity for multi-country service delivery. Technology talent concentrates in India, the United States, and Ireland, where delivery center operations feed global recruitment process outsourcing contracts. Proprietary compensation benchmarking databases, machine learning infrastructure, and compliance credentialing systems constitute critical input dependencies. Single-source vulnerability runs through concentrated AI model providers. Distribution runs through direct enterprise sales teams and strategic partnerships with systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise technology spending cycles are recovering from prior compression, with workforce analytics platform procurement accelerating as CHROs prioritize flight-risk modeling and pay equity infrastructure.
For Market Incumbents: Entrench algorithmic accountability capabilities through human-in-the-loop validation protocols that address uninsurable legal exposure from automated hiring decisions. Deepen vertical integration into proprietary compensation benchmarking databases to sustain multi-year client retention against cloud-native platform competition. Prioritize ISO 30414 certification investment to defend margin position in European markets.
For New Entrants and Emerging Players: Establish a beachhead in contingent workforce management solutions for jurisdictions with evolving independent contractor definitions, where platform-based gig worker classification remains underdeveloped white space. Target India's PLI scheme labor compliance advisory segment, where manufacturing incentives create localized statutory documentation demand. Deploy skills-based credentialing verification systems integrated with applicant tracking platforms as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized compliance-oriented service providers with established algorithmic audit capabilities, positioned to capture advisory demand from the EU AI Act's risk classification mandates. Long-term viability hinges on recurring SaaS-based revenue models displacing transactional placement economics. Watch for procurement department consolidation of vendor relationships as the inflection indicator compressing mid-tier provider survival rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Compliance Certification | EU AI Act conformity declarations anchor premium pricing in European recruitment process outsourcing contracts. |
| Proprietary Data Asset Acquisition | Compensation benchmarking databases sustain multi-year client retention against commoditized platform competition. |
| Hybrid Delivery Model Expansion | Virtual self-service portals combined with on-site advisors capture premium pricing in United States and United Kingdom markets. |
| Contingent Workforce Platform Development | Gig worker classification and benefits portability solutions address underdeveloped regulatory white space. |
| ISO 30414 Reporting Infrastructure Investment | Auditable workforce metrics capabilities meet German and United Kingdom public company disclosure requirements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory submissions, and industry association workforce technology surveys to validate market sizing and growth trajectory assumptions. Primary interviews engaged CHROs at enterprise technology and financial services firms, regulatory compliance officers at multinational employers, and platform engineering leads at human capital management vendors. Secondary sources encompassed OSHA enforcement data, GDPR implementation guidance, and ISO standards documentation. Bottom-up contract value analysis triangulated against top-down sector spending estimates.
Forecast inputs span service type segmentation across recruitment, payroll, benefits, and training; delivery model differentiation between hybrid, outsourced, on-site, and remote consulting; and client scale tiers from startups through large corporations. CAGRs were derived from regression analysis of historical contract velocity and technology adoption curves, incorporating cloud platform penetration rates and regulatory compliance spend intensity across the analysis window. Workforce analytics platform licensing growth and AI-driven candidate matching engine deployment served as industry-specific demand indicators.
Sensitivities concentrate around algorithmic liability rulings in anti-discrimination frameworks and generative AI hallucination risks demanding costly human oversight layers. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and enterprise procurement consolidation velocity. Material shifts in EU AI Act implementation timelines or cross-border data residency requirement expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Europe Leadership Development Program Market
Professional Development and Training
Technical and Vocational Education Market
Professional Development and Training
Global Mechatronics and Robotics Courses Market
Professional Development and Training
Cognitive Assessment and Training Market
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
Executive Education Program Market
Professional Development and Training
HSE Consulting Training Services Market
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
US Life Coaching Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
Equipment Maintenance Training Services Market
Professional Development and Training
RPA Platform Training Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
Business Coaching Service Market
Professional Development and Training
Firefighter Simulator Training Services Market