
 Global Social and Emotional Learning (SEL) Market | 2026-2036
Global Social and Emotional Learning (SEL) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Social and Emotional Learning (SEL) Market Foresight
Subscription-based professional development for educators is expanding beyond one-time training workshops into recurring, outcome-verified service tiers. Committee for Children leverages decades of curriculum research to anchor premium positioning in district-level contracts. EVERFI competes through digital platform specialization, embedding SEL modules within broader financial literacy and wellness coursework. Panorama Education differentiates via data infrastructure, connecting SEL assessment tools to multi-source analytics dashboards that administrators already use.
Social and emotional learning encompasses structured curricula, assessment protocols, and educator training systems designed to cultivate self-awareness, interpersonal skills, and responsible decision-making in learners, typically delivered through evidence-based lesson sequences with defined competency benchmarks. Curriculum programs and digital platforms represent the dominant solution type pairing, with the former supplying standardized instructional content and the latter enabling scalable delivery, progress tracking, and real-time adaptation. Elementary education remains the most mature application area, while workforce training represents the fastest-growing segment as employers adopt SEL-derived frameworks for team cohesion and leadership development.
The US Department of Education's ESSA framework shapes procurement by permitting Title I and IV-A funds for SEL interventions, while state-level departments such as California's Department of Education enforce explicit SEL standards that create compliance-driven demand. The EU's emphasis on lifelong learning competencies through frameworks like the European Commission's Key Competences for Lifelong Learning indirectly elevates SEL-aligned instruction across member states. Stakeholders must monitor how evolving privacy regulations affect student emotional data collection, as assessment tools that capture sensitive psychological metrics face heightened scrutiny from regulators and parent advocates alike.
Market Dynamics
Federal funding flexibility under the US ESSA framework is redirecting Title I and IV-A dollars toward student wellness platforms, compressing procurement cycles for districts previously constrained by narrow curriculum mandates. This fiscal reallocation is accelerating vendor consolidation around platforms that bundle assessment, curriculum, and professional development into unified district contracts.
Growth Catalysts
- California Department of Education mandates:Explicit SEL standards from kindergarten through grade twelve create compliance-driven procurement volume that vendors can forecast with precision. Districts must demonstrate standards alignment to maintain state funding eligibility.
- Workforce training adoption:Employers across healthcare and technology verticals are importing SEL-derived frameworks for leadership development and team cohesion, expanding addressable market beyond traditional education.
- Cloud-based assessment infrastructure:Real-time emotional data capture and progress dashboards are unifying previously siloed student information systems, reducing administrative friction for multi-site district deployments.
Market Restraints
- Student data privacy friction:GDPR in Europe and emerging state-level student privacy laws in the US are constraining cross-border data flows for platforms capturing psychological metrics, complicating international expansion for assessment-heavy vendors.
- District budget cyclicality:K-12 procurement concentrates in July-September windows tied to fiscal year resets, creating revenue recognition lumpiness and working capital strain for subscription-model providers.
- Evidence standard elevation:The US Department of Education's What Works Clearinghouse criteria are tightening, requiring randomized controlled trials that smaller curriculum developers cannot fund, concentrating supply among research-capable incumbents.
Strategic Opportunities
- Brazil's national curriculum reform:The BNCC framework's socioemotional competency pillars create first-mover advantage for platforms localizing Portuguese-language content and educator training infrastructure.
- Artificial intelligence and natural language processing convergence:Emotion recognition algorithms embedded in learning management systems are enabling adaptive content delivery that responds to student engagement signals in real time.
- Direct-to-parent subscription channels:District procurement delays are driving demand for supplemental home-based SEL programming, opening recurring revenue streams outside institutional sales cycles.
Industry Challenges
- Educator credentialing bottlenecks:State-level teaching certification programs lack SEL-specific preparation requirements, forcing districts to fund redundant professional development and slowing implementation velocity.
- Interoperability with legacy student information systems:Proprietary data formats in entrenched platforms like PowerSchool and Infinite Campus require expensive API development, fragmenting analytics across incompatible dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Social and Emotional Learning (SEL) Market |
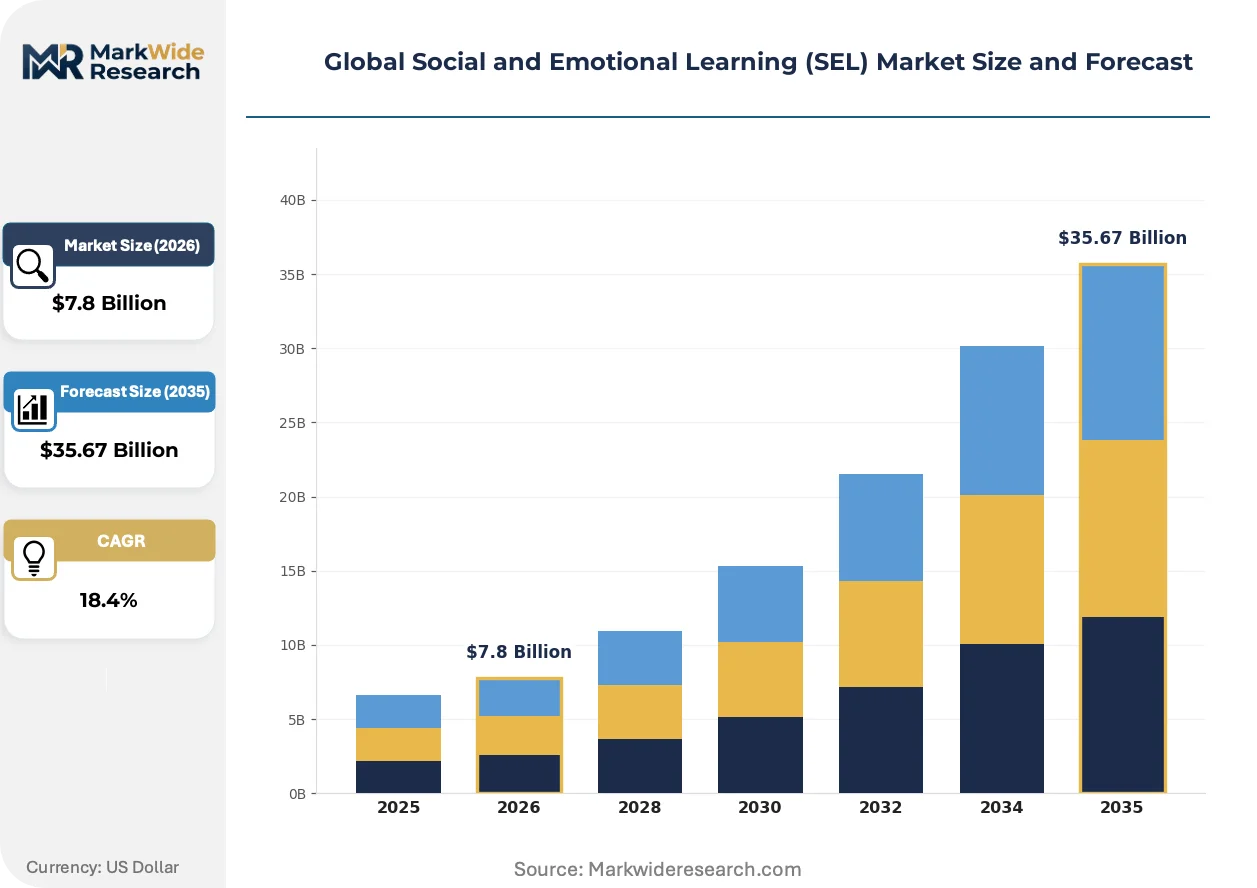
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $35.67 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Curriculum Programs, Assessment Tools, Professional Development, Digital Platforms Application Area: Elementary Education, Secondary Education, Higher Education, Workforce Training End User: School Administrators, Educators, Counselors, Corporate Trainers Delivery Mode: In-Person, Online, Blended Learning, Mobile Applications |
| Companies Covered | Committee for Children, EVERFI, Panorama Education, Illuminate Education, Nearpod, Positive Action, 7 Mindsets, Playworks, Imagine Learning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Social and Emotional Learning (SEL) Market Shifts & Advancements
Adaptive learning engines are compressing the feedback loop between assessment and instructional intervention, collapsing the traditional lag between data collection and curriculum adjustment from weeks to minutes. This acceleration is redefining competitive advantage around real-time responsiveness rather than content library depth alone.
Artificial intelligence-powered emotion detection is unifying previously separate functions of behavioral observation, academic performance tracking, and wellness screening into single-platform workflows. K-12 districts with multi-site deployments are adopting these integrated systems fastest, consolidating vendor relationships and reducing training overhead for administrative staff. The structural consequence is compression of point-solution vendors into broader platform ecosystems, as standalone assessment tools lose procurement viability.
The EU AI Act's risk classification framework is elevating compliance requirements for automated emotion recognition systems deployed in educational settings. Vendors must now document algorithmic transparency and bias mitigation protocols to access European markets, raising R&D overhead but also creating defensible positioning for compliant incumbents. Assessment platforms with EU presence are restructuring data architecture to satisfy these mandates ahead of enforcement timelines.
Parental purchasing committees are displacing centralized district procurement for supplemental SEL programming, particularly in suburban districts with active PTAs and discretionary fundraising capacity. Direct-to-consumer channels are capturing volume previously routed through institutional RFP processes, with subscription retention exceeding district contract renewal rates. This behavioral shift is most visible in California and Texas metropolitan areas where household education spending per capita leads national benchmarks.
Global Social and Emotional Learning (SEL) Market Segmentation
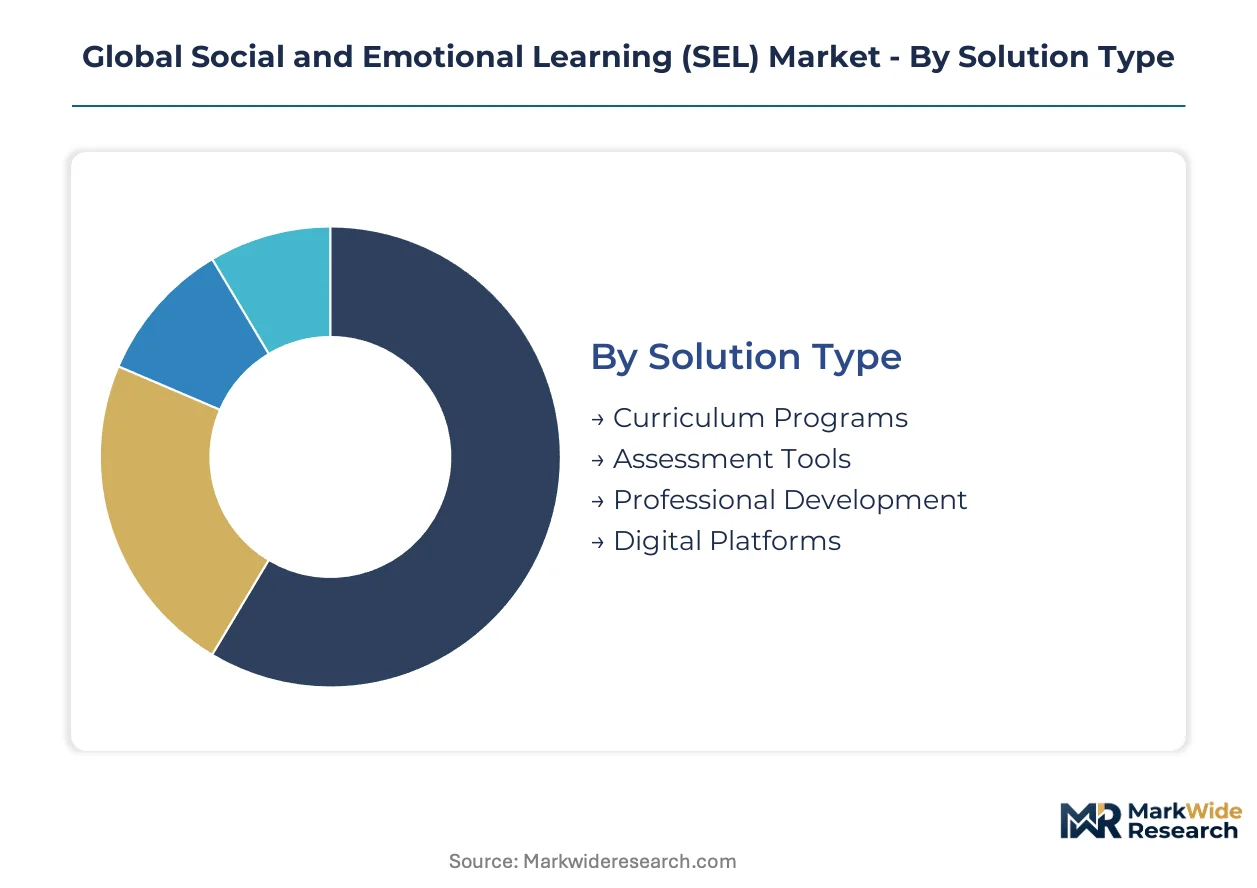
Segmentation in the SEL market reflects distinct procurement rhythms across institutional buyers. Solution architecture, delivery infrastructure, and end-user workflow integration create divergent vendor positioning strategies that reshape competitive boundaries.
Solution Type:
Districts approaching contract renewal cycles prioritize bundled platforms over standalone components, consolidating previously separate budget lines into unified wellness initiatives.
- Curriculum Programs:Standardized instructional sequences with defined competency benchmarks supply the foundational content layer. California school districts mandate explicit alignment with state SEL standards, compressing vendor qualification timelines. Volume placements concentrate in curriculum programs; the faster expansion belongs to digital platforms.
- Digital Platforms:Scalable delivery infrastructure enables real-time progress tracking and adaptive content sequencing. Cloud-native architectures reduce IT deployment friction for multi-site district deployments, particularly in Texas metropolitan clusters with decentralized administrative structures.
- Assessment Tools:Protocols capturing self-awareness, interpersonal skills, and responsible decision-making metrics face heightened GDPR and state-level student privacy scrutiny.
- Professional Development:Educator training systems are shifting from one-time workshops toward subscription-based, outcome-verified service tiers with recurring engagement models.
Procurement committees favor vendors spanning multiple solution types; single-category providers face margin compression.
Application Area:
Workforce training adoption is climbing the fastest as healthcare and technology employers import SEL-derived frameworks for leadership development.
- Elementary Education:The most mature segment with established state standards and dedicated ESSA funding streams. California's kindergarten-through-twelve mandate anchors procurement volume, with suburban districts in Los Angeles and San Diego counties leading per-capita spending.
- Workforce Training:Employers across healthcare verticals and technology sectors are adopting team cohesion and leadership development frameworks derived from K-12 SEL methodologies. This segment is gaining share fastest as corporate learning budgets expand beyond technical skills.
- Secondary Education:Implementation concentrates in advisory period structures and homeroom integrations rather than standalone courses.
- Higher Education:Student services departments are piloting wellness screening tools, though procurement remains fragmented across counseling, residential life, and career services divisions.
Revenue concentration remains in elementary settings; steepest expansion trajectory is workforce training.
End User:
Counselor-facing tools are displacing administrator-centric dashboards as the primary workflow integration point.
- School Administrators:Superintendents and principals control district-level contract authority, prioritizing multi-source analytics dashboards that unify previously siloed student information systems.
- Counselors:Direct student interaction creates demand for real-time emotional data capture and progress visualization tools. This user category is expanding most quickly as states mandate counselor-to-student ratio improvements.
- Educators:Classroom teachers require lesson-embedded SEL activities with minimal preparation overhead, favoring scripted sequences over open-ended frameworks.
- Corporate Trainers:Human resource departments in healthcare and technology sectors are adopting adapted SEL protocols for manager development and team intervention.
Administrator budgets dominate current procurement; counselor-facing solutions are climbing the fastest.
Delivery Mode:
Blended configurations are displacing pure online or in-person formats as the default architectural choice.
- Blended Learning:Combines synchronous educator facilitation with asynchronous digital practice, optimizing both relationship formation and scalable reach. This mode is expanding most quickly as districts seek to preserve in-person connection while capturing platform analytics.
- Online:Fully digital delivery enables rapid deployment across geographically dispersed sites, particularly valuable for rural districts with limited specialist staffing.
- In-Person:Traditional workshop and classroom-based delivery retains preference for initial educator certification and high-stakes intervention contexts.
- Mobile Applications:Direct-to-parent subscription channels are emerging in California and Texas metropolitan areas with active PTA fundraising capacity.
Blended learning captures the largest contract values; mobile applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Curriculum developers concentrate in the United States while platform scaling operations expand across Europe and Asia-Pacific. Content production anchors in research-intensive clusters with established education standards. Consumption patterns diverge sharply between compliance-driven state mandates and employer-led workforce adoption.
United States
K-12 procurement volume concentrates in California and Texas metropolitan corridors where state standards enforcement creates predictable contract cycles. The Department of Education's ESSA framework permits Title I and IV-A fund reallocation toward wellness platforms, compressing district decision timelines. Los Angeles and San Diego counties lead per-capita spending on elementary-level curriculum packages.
Brazil
The BNCC national curriculum framework's socioemotional competency pillars generate first-mover procurement opportunities for localized Portuguese-language platforms. ANVISA and the Ministry of Education coordinate implementation timelines for digital health-adjacent student assessments. São Paulo state districts pilot blended delivery models ahead of national rollout.
Germany
Lifelong learning competency frameworks through the EU Commission elevate SEL-aligned instruction across federal education ministries. GDPR compliance requirements constrain cross-border data flows for assessment platforms capturing psychological metrics. Bavaria and North Rhine-Westphalia lead Länder-level procurement for educator professional development systems.
United Kingdom
Department for Education guidance on personal, social, health and economic education creates procurement entry points for curriculum providers. Ofsted inspection criteria increasingly weight student wellbeing metrics, elevating demand for progress-tracking dashboards. Greater London academy trusts consolidate vendor relationships around unified platform contracts.
India
National Education Policy emphasis on holistic development creates state-level implementation demand for structured competency frameworks. CBSE and state board alignment requirements drive curriculum localization investments. Maharashtra and Karnataka lead metropolitan district adoption of digital assessment tools in tier-one cities.
Global Social and Emotional Learning (SEL) Market Competitive Landscape
Capital-heavy curriculum producers compete with asset-light platform designers for district contract authority. The vendor base organizes around three strategic tiers: research-anchored incumbents with decades of evidence libraries, cloud-native specialists optimizing for deployment velocity, and data infrastructure providers unifying previously siloed student information systems. Competitive moves concentrate on bundling adjacent solution types into unified district contracts and localizing content for emerging national curriculum frameworks.
Among research-anchored developers, Committee for Children exemplifies the premium-positioned archetype built on longitudinal curriculum studies. EVERFI occupies the digital platform specialization tier, embedding modules within broader financial literacy coursework. Panorama Education represents the data infrastructure convergence archetype, connecting assessment tools to multi-source analytics dashboards administrators already operate.
| Leading Market Players |
|---|
| Committee for Children |
| EVERFI |
| Panorama Education |
| Illuminate Education |
| Nearpod |
| Positive Action |
| 7 Mindsets |
| Playworks |
| Imagine Learning |
| Others |
Supply & Pricing Matrix
Horizontal platform bundling anchors vendor positioning in district procurement cycles, compressing margins for standalone curriculum providers while amplifying pricing power for integrated assessment-curriculum-professional development suites. This integration pattern concentrates margin capture among research-capable incumbents capable of spanning multiple solution types under unified contracts.
Pricing Analysis
Cost-down pressure on standard curriculum tiers accelerates because ESSA funding flexibility redirects Title I and IV-A dollars toward bundled wellness platforms rather than discrete content purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by evidence depth and professional development inclusion, with California Department of Education compliance certification commanding brand premium. District procurement committees exhibit highest price sensitivity in standalone assessment tools facing GDPR compliance overhead, while unified platform buyers demonstrate lower sensitivity due to consolidated budget line justification.
Supply Chain Analysis
Single-source vulnerability sits with cloud infrastructure providers concentrated in the United States, where AWS and Azure dominance creates chokepoint risk for multi-site district deployments. Content production draws from research-intensive clusters in California and Massachusetts, while platform development rests on software engineering talent pools in Texas and Washington. Tariff exposure on cross-border data flows complicates international expansion for assessment-heavy vendors. Distribution runs through direct district sales teams supplemented by regional education service agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around platforms bundling assessment, curriculum, and professional development, with the US Department of Education's What Works Clearinghouse criteria forcing weaker curriculum developers out due to unfundable randomized controlled trial requirements.
For Market Incumbents: Anticipate compression of point-solution vendors into broader platform ecosystems by accelerating API development for PowerSchool and Infinite Campus integration. Prioritize backward integration into professional development delivery to capture recurring subscription revenue outside July-September procurement windows. Defensive positioning requires EU AI Act compliance documentation ahead of enforcement timelines for emotion recognition systems. For New Entrants and Emerging Players: Brazil's BNCC national curriculum framework opens a window for Portuguese-language localization and educator training infrastructure ahead of national rollout completion. Workforce training adoption in healthcare and technology verticals presents the most penetrable segment, with corporate learning budgets expanding beyond technical skills. Direct-to-parent subscription channels in California and Texas metropolitan areas offer a go-to-market angle bypassing district RFP cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by cloud-native platform specialists seeking research-anchored curriculum libraries to deepen evidence credentials. Long-term viability favors vendors with demonstrated What Works Clearinghouse alignment and multi-state procurement presence. Watch for counselor-to-student ratio mandate expansions as the inflection signal for counselor-facing tool demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies assessment, curriculum, and professional development into single district contracts, reducing vendor fragmentation. |
| Geographic Expansion | Localizes content for Brazil's BNCC framework and EU lifelong learning competency requirements. |
| Regulatory Compliance Investment | Documents EU AI Act algorithmic transparency and bias mitigation protocols for emotion recognition systems. |
| Direct-to-Consumer Launch | Captures parent committee purchasing in California and Texas suburban districts with active PTA fundraising. |
| Strategic Partnership | Connects SEL assessment tools to existing student information systems through API development with PowerSchool. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with district superintendents, curriculum directors, school counselors, and corporate learning officers. State education department procurement databases, ESSA funding allocation reports, and EU Commission lifelong learning framework documents provided triangulation anchors. Bottom-up district contract analysis and top-down market sizing reconstructions were cross-validated for consistency.
Data-stream reconciliation across solution type, application area, end user, and delivery mode segmentation generated volume and value outputs across the projection horizon. CAGRs derived from historical procurement velocity and funding trajectory modeling. Cloud adoption rates in K-12 districts and workforce training budget expansion in healthcare verticals served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for AI-powered emotion recognition would alter the outlook. Forecasts reflect assumptions regarding ESSA funding continuity, state mandate expansion, and privacy regulation evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Technical and Vocational Education Market
Professional Development and Training
Equipment Maintenance Training Services Market
Professional Development and Training
HR Professional Services Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
Cognitive Assessment and Training Market
Professional Development and Training
Canada Executive Education Program Market
Professional Development and Training
North America IT Training Market
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
Business Coaching Service Market
Professional Development and Training
Coding Bootcamp Market
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
Firefighter Simulator Training Services Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
Executive Education Program Market
Professional Development and Training
Leadership Development Program Market
Professional Development and Training
HSE Consulting Training Services Market