
 Executive Coaching and Leadership Development Market | 2026-2036
Executive Coaching and Leadership Development Market Size, Share, and Industry Trends Forecast 2026-2036
Executive Coaching and Leadership Development Market Insights
Recurring certification revenue is reconfiguring how providers monetize relationships beyond initial engagements. Korn Ferry leverages its assessment science heritage to anchor premium advisory contracts across C-suite succession mandates. FranklinCovey sustains institutional reach through licensed facilitator networks that extend curriculum distribution without proportional headcount expansion. BetterUp competes by integrating behavioral analytics into virtual coaching workflows, positioning data-driven outcomes as a substitute for traditional relationship-based engagement models.
Executive coaching and leadership development encompasses structured interventions designed to enhance individual and collective leadership capability through behavioral assessment, goal-aligned dialogue, and sustained accountability mechanisms, typically delivered in modular sessions ranging from six months to two years with defined psychometric baselines and progress milestones. Its primary commercial purpose centers on reducing executive failure rates, accelerating role transitions, and aligning leadership behavior with strategic organizational priorities. One-on-one coaching commands the deepest margin pools due to customization intensity and sponsor willingness to pay for confidentiality, while virtual delivery models are expanding fastest as platform economics enable coach supply scaling without geographic constraint. Corporate executives represent the most mature client type with established procurement processes, whereas startup segments present fragmented demand characterized by shorter engagement cycles and price sensitivity.
The US Department of Labor's OSHA whistleblower protections and the SEC's climate disclosure rules indirectly elevate leadership accountability standards that coaching engagements must address. The EU's CSRD mandates granular workforce and leadership transparency that prompts European headquartered multinationals to document development investments with measurable governance outcomes. Stakeholders must monitor how regulatory disclosure requirements transform coaching from discretionary talent spend into auditable compliance infrastructure.
Market Dynamics
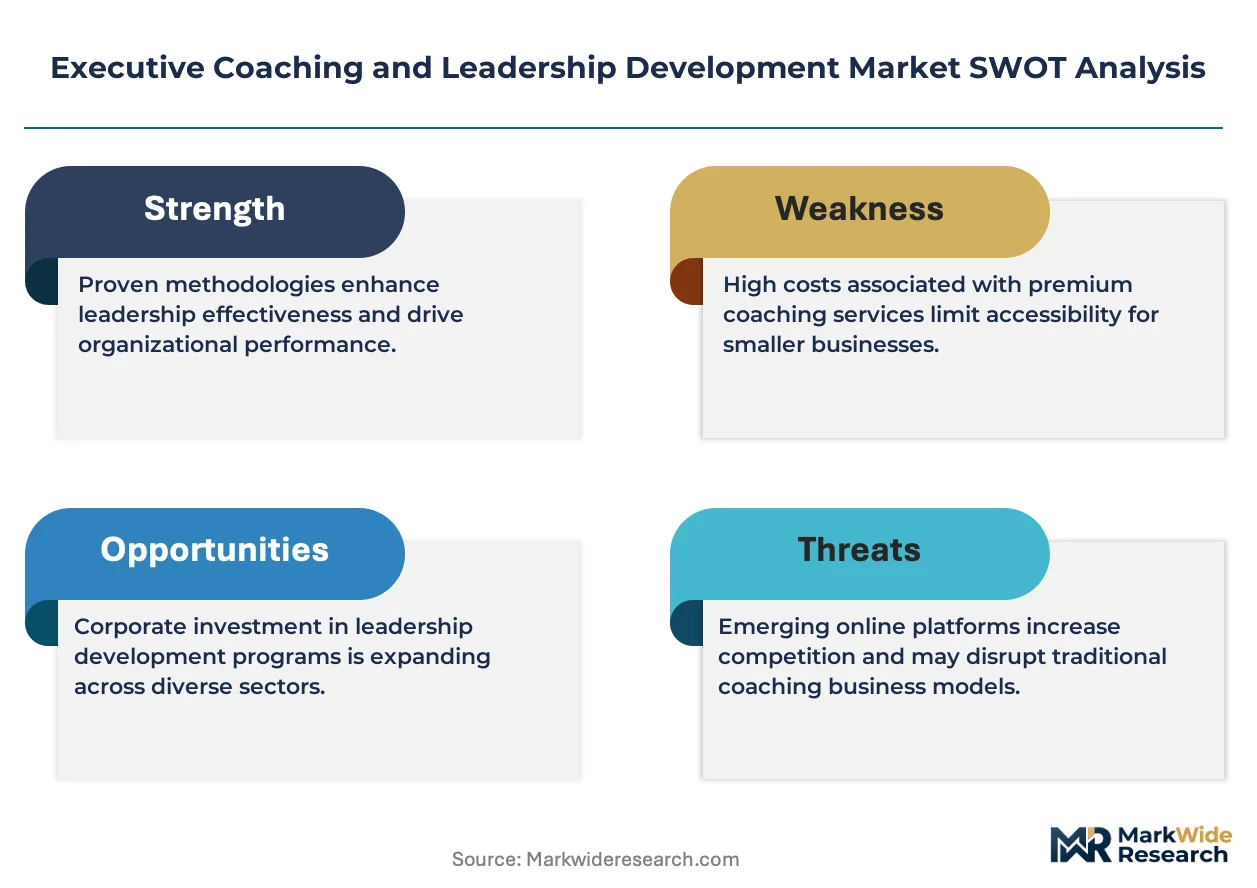
ISO 30414 human capital reporting standards and ESG-linked disclosure rules are transforming executive coaching from discretionary talent spend into auditable compliance infrastructure, forcing providers to restructure delivery models around measurable governance outcomes.
Growth Catalysts
- Technology sector digital leadership transitions:Enterprise software and cloud infrastructure companies are expanding coaching budgets to accelerate executive adaptation to AI-driven operating models and remote workforce management.
- EU CSRD workforce transparency mandates:European headquartered multinationals must document leadership development investments with quantifiable outcomes, creating procurement pull for outcome-linked coaching contracts.
- Fortune 500 headquarters clustering:Concentrated demand in New York, Chicago, and San Francisco Bay Area generates referral network effects and premium pricing power for established providers.
Market Restraints
- Coach supply concentration in tier-one cities:Certified executive coaches cluster disproportionately in London, New York, and Singapore, creating geographic access barriers for mid-market enterprises in secondary locations.
- Psychometric assessment licensing costs:Proprietary behavioral instruments from established assessment science providers impose fixed cost burdens that compress margins for independent coaching practitioners.
- Virtual delivery standardization gaps:Absence of unified ISO standards for remote coaching quality assurance creates procurement friction for risk-averse corporate sponsors.
Strategic Opportunities
- Mid-market enterprise underpenetration:Companies with 500-5,000 employees represent fragmented demand with shorter engagement cycles, offering volume scaling potential for platform-enabled coaching networks.
- Startup ecosystem leadership development:Venture-backed technology founders require accelerated role transition support as companies scale from seed to Series C, creating demand for modular, high-intensity coaching sprints.
- Behavioral analytics-virtual coaching convergence:Integration of passive digital behavioral data with synchronous video coaching sessions enables predictive intervention models that differentiate platform providers.
Industry Challenges
- Coach certification timeline compression:Accelerated credentialing programs risk diluting perceived quality standards, forcing established providers to invest in proprietary certification differentiation.
- Client data interoperability with HRIS systems:Coaching platforms face integration complexity with legacy human capital management infrastructure, particularly in regulated industries with strict data residency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Executive Coaching and Leadership Development Market |
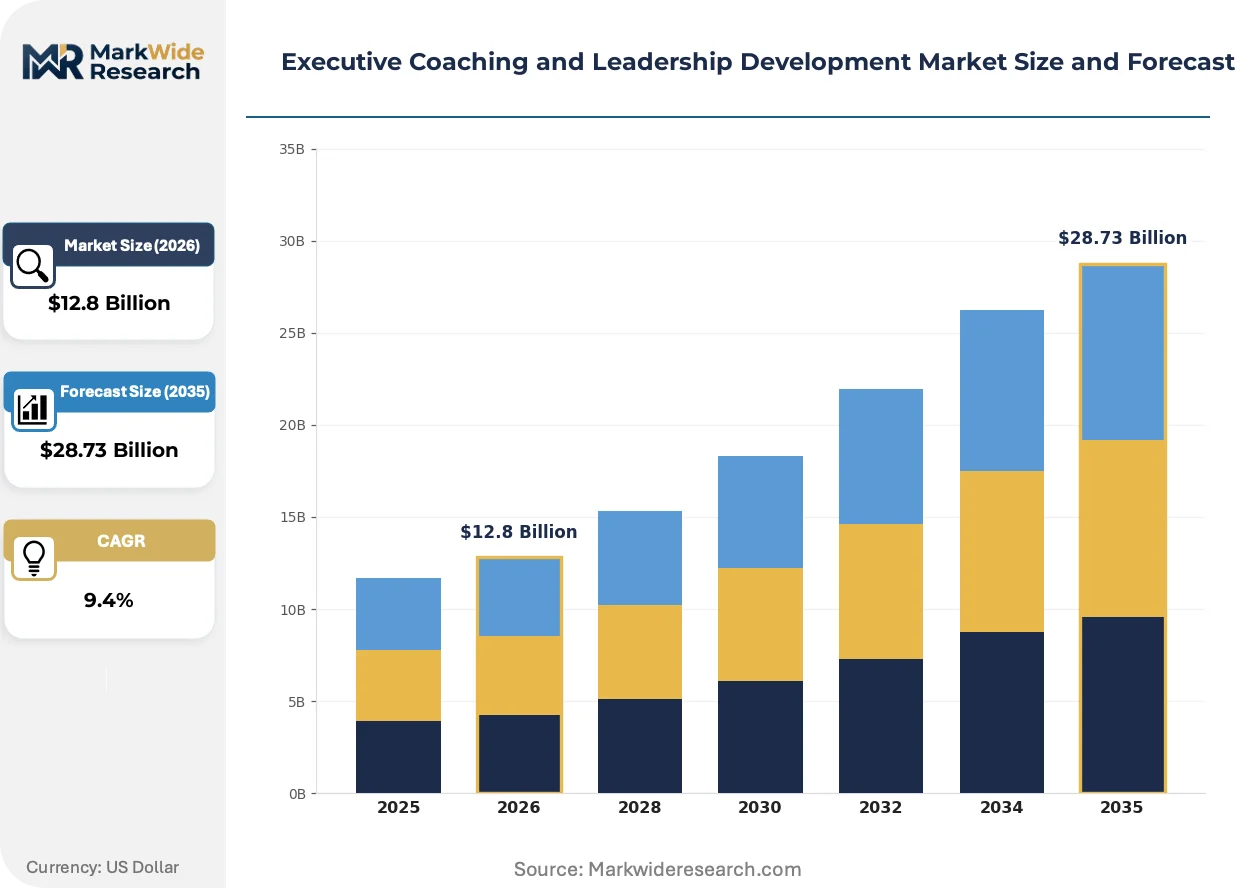
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: One-on-One Coaching, Group Coaching, Workshops, Online Training Delivery Model: In-Person, Virtual, Hybrid, Self-Paced Coaching Focus: Executive Presence, Team Dynamics, Performance Improvement, Conflict Resolution Client Type: Corporate Executives, Aspiring Leaders, Non-Profit Organizations, Startups |
| Companies Covered | Korn Ferry, FranklinCovey, Center for Creative Leadership, Dale Carnegie, The Ken Blanchard Companies, BetterUp, CoachHub, Marshall Goldsmith Group, Gallup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Executive Coaching and Leadership Development Market Trends and Innovations
Behavioral analytics platforms are collapsing the traditional relationship-based coaching model by embedding passive measurement into daily workflow tools, enabling continuous rather than episodic intervention.
Artificial intelligence-powered coaching assistants are collapsing the economics of 24/7 developmental support by automating routine accountability check-ins and goal-tracking functions previously requiring human coach hours. Fortune 500 technology functions are deploying these tools for first-line manager populations at scale. The structural consequence is a bifurcation between premium C-suite human coaching and algorithm-supported development for broader leadership layers.
The EU's Corporate Sustainability Reporting Directive is mandating granular workforce and leadership transparency that prompts European headquartered multinationals to document development investments with measurable governance outcomes. Industrial consequence includes procurement teams requiring coaching vendors to embed psychometric baselines and progress milestones into contract structures. German and French headquartered companies are most advanced in embedding these requirements into RFP criteria.
Subscription-based coaching access models are displacing traditional per-engagement procurement, with corporate buyers negotiating annual platform licenses that democratize leadership development beyond senior executive tiers. This procurement evolution disrupts incumbent providers dependent on high-margin one-on-one engagements. United States-based technology and financial services sectors are leading this transition, with procurement teams treating coaching as recurring workforce infrastructure rather than episodic intervention.
Executive Coaching and Leadership Development Market Segmentation
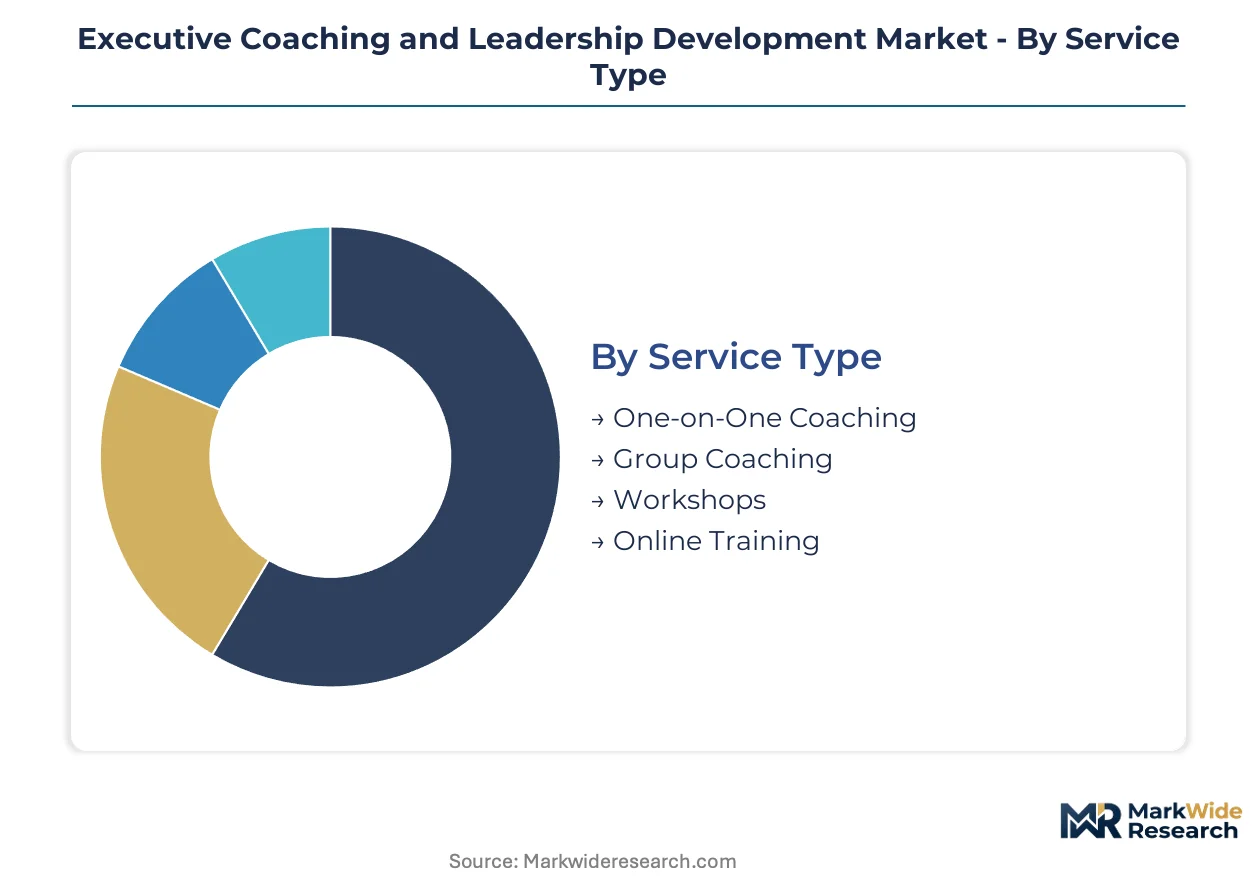
Executive coaching and leadership development markets fragment across service architecture, delivery modality, behavioral objective, and organizational maturity. Procurement patterns diverge sharply between Fortune 500 sponsors seeking confidential one-on-one engagements and mid-market buyers optimizing for scalable platform access. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume scaling operates.
Service Type:
Cost tier determines margin structure and contract duration across coaching delivery formats.
- One-on-One Coaching:High-intensity dyadic engagements spanning six to twenty-four months with defined psychometric baselines. Confidentiality premiums command the deepest margins; demand concentrates among C-suite sponsors in New York and San Francisco Bay Area headquarters clusters.
- Group Coaching:Cohort-based developmental experiences leveraging peer accountability and shared behavioral objectives. Technology sector enterprises deploy these for first-line manager populations seeking cost-efficient leadership calibration.
- Workshops:Intensive multi-day facilitated sessions targeting specific skill acquisition. Non-profit organizations and mid-market enterprises favor these for budget-constrained leadership interventions.
- Online Training:Asynchronous curriculum delivery through licensed facilitator networks. FranklinCovey and similar providers extend reach without proportional headcount expansion through this modality.
One-on-One Coaching holds installed capacity. Group Coaching is rotating up the share rankings.
Delivery Model:
Application context shapes technology requirements and quality assurance protocols.
- In-Person:Face-to-face engagements requiring physical presence and dedicated facility access. Sustains premium positioning for succession planning and high-stakes role transitions where sponsor visibility matters.
- Virtual:Synchronous video-based coaching collapsing geographic constraints on coach supply. BetterUp and platform competitors compete here by integrating behavioral analytics into workflow tools.
- Hybrid:Blended architectures combining initial in-person diagnostic sessions with ongoing virtual touchpoints. Balances relationship depth with logistical flexibility for distributed executive teams.
- Self-Paced:Algorithm-supported developmental modules with automated accountability check-ins. AI-powered assistants are collapsing economics for 24/7 support previously requiring human coach hours.
Virtual delivery is climbing the fastest. In-Person retains pricing power in governance-sensitive mandates.
Coaching Focus:
Customer type specificity determines assessment instrumentation and intervention design.
- Executive Presence:Interventions targeting gravitas, communication authority, and stakeholder influence. Board-facing roles in financial services generate concentrated demand for image and messaging calibration.
- Team Dynamics:Collective capability building addressing cohesion, psychological safety, and decision velocity. Enterprise software companies expanding AI-driven operating models prioritize these engagements.
- Performance Improvement:Corrective developmental support for executives at risk of role failure. HR sponsors mandate measurable behavioral milestones tied to retention decisions.
- Conflict Resolution:Mediation-adjacent skill building for high-stakes interpersonal friction. Private equity portfolio companies deploy these during post-acquisition leadership integration.
Executive Presence holds installed capacity. Team Dynamics is gaining share fastest as remote workforce management complexity mounts.
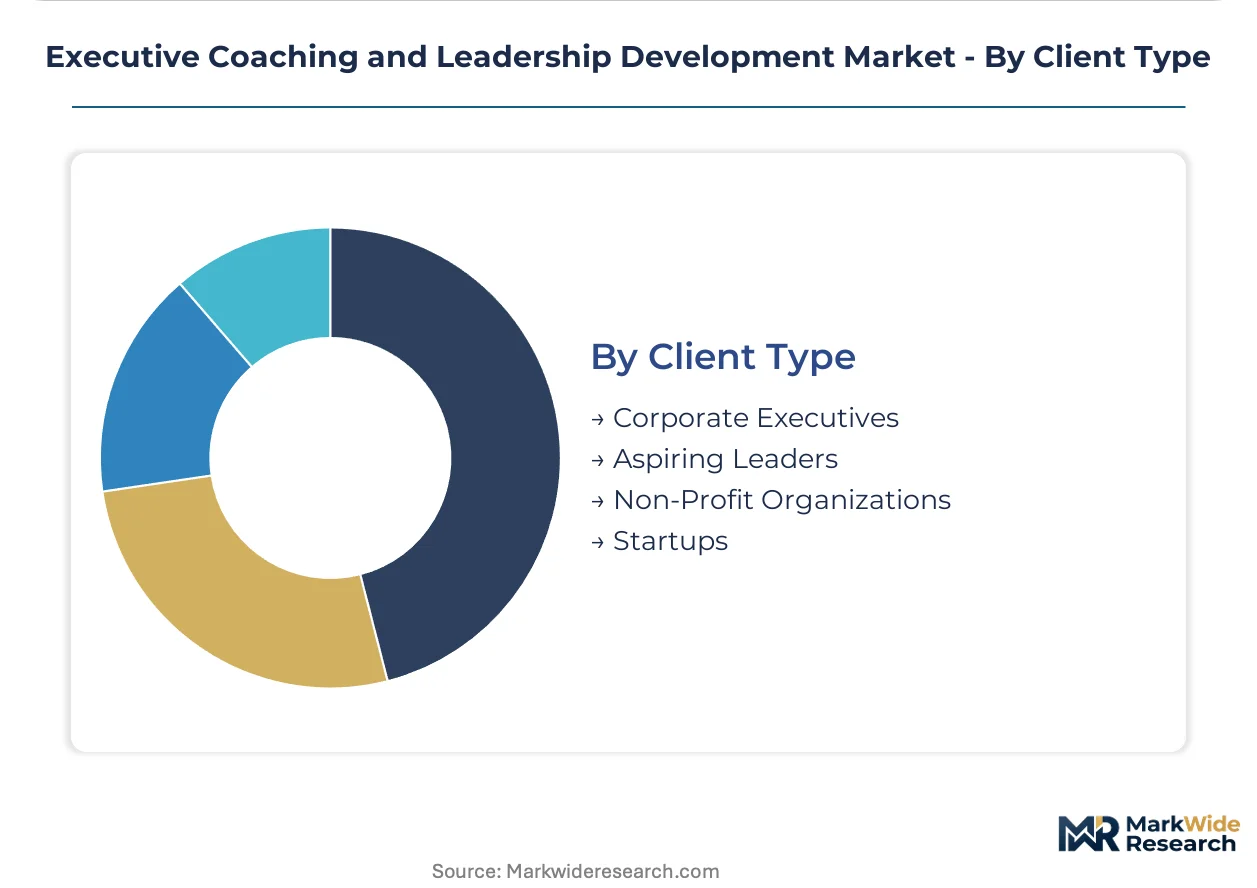
Client Type:
Maturity gradients separate established procurement processes from fragmented, price-sensitive demand.
- Corporate Executives:Mature buyers with structured RFP processes and defined success metrics. ISO 30414 human capital reporting standards and ESG-linked disclosure rules are transforming coaching from discretionary spend into auditable compliance infrastructure.
- Aspiring Leaders:High-potential populations below C-suite tier targeted for succession pipeline development. Subscription-based platform access models are democratizing development beyond senior executive tiers.
- Non-Profit Organizations:Budget-constrained buyers prioritizing workshop formats and group delivery. Shorter engagement cycles and grant-dependent funding create procurement friction.
- Startups:Venture-backed technology founders requiring accelerated role transition support. Modular, high-intensity coaching sprints address scaling pressures from seed to Series C.
Corporate Executives hold installed capacity. Aspiring Leaders is rotating up the share rankings as procurement teams treat coaching as recurring workforce infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with United States buyers prioritizing confidential one-on-one engagements while European sponsors emphasize auditable compliance outcomes and Asian markets concentrate demand in technology sector digital leadership transitions.
United States
Fortune 500 headquarters clusters in New York, Chicago, and the San Francisco Bay Area generate concentrated demand for premium C-suite coaching with confidentiality premiums. The SEC's climate disclosure rules and OSHA whistleblower protections elevate leadership accountability standards that engagements must address. Referral network effects in these metropolitan corridors sustain pricing power for established providers.
Germany
Industrial conglomerates and automotive manufacturers anchor demand for team dynamics coaching as AI-driven operating models reshape workforce management. The EU's CSRD mandates granular workforce transparency, prompting German-headquartered multinationals to embed psychometric baselines and progress milestones into procurement contracts. Munich and Frankfurt clusters lead in embedding these requirements into RFP criteria.
United Kingdom
Financial services and professional services firms drive demand for executive presence interventions targeting board-facing gravitas and stakeholder influence. The UK's Financial Conduct Authority maintains conduct standards that indirectly shape leadership development procurement specifications. London's City and Canary Wharf districts concentrate sponsor willingness to pay for image and messaging calibration.
France
Luxury goods conglomerates and pharmaceutical multinationals prioritize succession pipeline development for high-potential populations below C-suite tier. French implementation of EU CSRD disclosure rules advances faster than continental peers, creating procurement pull for outcome-linked coaching contracts with measurable governance documentation. Paris-based headquarters clusters favor hybrid delivery combining initial in-person diagnostics with ongoing virtual touchpoints.
Singapore
Regional headquarters for multinational corporations anchor demand for cross-cultural leadership capability building across Asia-Pacific distributed teams. Singapore's Monetary Authority and corporate governance codes emphasize director development, shaping procurement criteria for external leadership services. The city-state's status as a wealth management hub sustains premium positioning for succession planning and high-stakes role transitions.
Executive Coaching and Leadership Development Market Competitive Landscape
Capability concentration sits with assessment science heritage providers; scale advantage sits with platform-enabled networks. The market structures around three tiers: premium advisory firms anchoring C-suite succession mandates, licensed curriculum distributors extending reach without proportional headcount expansion, and behavioral analytics platforms competing on data-driven outcome substitution. Dominant competitive moves include recurring certification revenue models and virtual delivery standardization investments.
Within the premium advisory tier, Korn Ferry and FranklinCovey occupy positions anchored in psychometric instrumentation heritage and institutional facilitator networks respectively. BetterUp exemplifies the platform-native archetype, competing through behavioral analytics integration into virtual coaching workflows. These three entities represent the structural bifurcation between relationship-based human coaching and algorithm-supported development scaling.
| Leading Market Players |
|---|
| Korn Ferry |
| FranklinCovey |
| Center for Creative Leadership |
| Dale Carnegie |
| The Ken Blanchard Companies |
| BetterUp |
| CoachHub |
| Marshall Goldsmith Group |
| Gallup |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on certified coach credentialing bodies in London, New York, and Singapore determines both pricing tier spreads and supply chain shape for executive coaching services. This concentration creates geographic access barriers that compress margins for independent practitioners while amplifying premium capture for established providers with proprietary certification networks.
Pricing Analysis
Long-term subscription contracts are displacing traditional per-engagement procurement as corporate buyers negotiate annual platform licenses. Three-tier pricing structure across premium C-suite advisory, standard mid-manager cohorts, and economy self-paced modules reflects certification intensity and sponsor confidentiality requirements. Pricing pressure stems from virtual delivery standardization gaps that create procurement friction for risk-averse sponsors. Mid-market enterprises with 500-5,000 employees exhibit highest price sensitivity, while Fortune 500 headquarters clusters sustain premium willingness-to-pay.
Supply Chain Analysis
Export-control regimes on psychometric assessment technologies limit cross-border flows of proprietary behavioral instruments from established science providers. Coach supply concentrates disproportionately in the United States, United Kingdom, and Singapore, with raw material dependencies on ISO 30414-compliant reporting infrastructure and AI-powered coaching assistant platforms. Single-source vulnerability sits with proprietary assessment licensing costs that compress margins for independent practitioners. Distribution runs through licensed facilitator networks and direct enterprise sales teams serving headquarters clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as subscription-based access models democratize development beyond senior executive tiers. Procurement evolution toward recurring workforce infrastructure disrupts incumbent positioning dependent on high-margin one-on-one engagements.
For Market Incumbents: Insulate premium C-suite advisory positioning by deepening proprietary certification differentiation and anchoring outcome-linked contracts with measurable governance documentation. Platform-native entrants threaten relationship-based models through behavioral analytics integration; vertical integration into assessment science instrumentation preserves margin capture. For New Entrants and Emerging Players: Mid-market enterprises in secondary US metropolitan areas represent the most penetrable entry point, with 500-5,000 employee companies exhibiting fragmented demand and shorter engagement cycles. Venture-backed technology founders requiring modular, high-intensity coaching sprints offer second white-space target. Go-to-market through HRIS system integration partnerships reduces procurement friction. For Investors and Strategic Acquirers: The market sits at a platform-transition phase that favors behavioral analytics-enabled networks over legacy facilitator-dependent models. Long-term viability hinges on data interoperability capabilities and virtual delivery quality assurance investments. Acquisition target archetype: mid-scale coaching platforms with established enterprise client relationships and proprietary assessment IP. Signal to watch is EU CSRD procurement mandate penetration rates as inflection indicator for compliance-linked contract growth.| Strategic Initiative | Industry Significance |
|---|---|
| Behavioral Analytics Platform Integration | Embedding passive measurement into workflow tools enables predictive intervention models that differentiate from episodic human coaching. |
| Proprietary Certification Network Expansion | Licensed facilitator programs extend curriculum distribution without proportional headcount expansion, preserving margin structure. |
| HRIS System Interoperability Investment | Integration with legacy human capital management infrastructure reduces procurement friction in regulated industries with strict data residency requirements. |
| Outcome-Linked Contract Structuring | Psychometric baselines and progress milestones embedded into procurement contracts satisfy EU CSRD workforce transparency mandates. |
| Mid-Market Platform Access Launch | Subscription-based annual licenses democratize leadership development beyond senior executive tiers, capturing volume scaling potential. |
Research Methodology
Desk research of SEC climate disclosure filings, EU regulatory frameworks, and coaching platform technical documentation preceded structured interviews with CHROs, talent development executives, procurement officers at Fortune 500 enterprises, and independent coaching practitioners. Primary fieldwork combined with secondary validation across ISO 30414 implementation guidelines, ESG reporting standards, and behavioral science literature. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from corporate training budget disclosures.
Assumptions held fixed include prevailing regulatory disclosure requirements and technology sector digital leadership transition timelines; variables tested included virtual delivery adoption curves and mid-market penetration rates. Segmentation dimensions modeled encompass service architecture, delivery modality, coaching focus area, and organizational maturity tier across the projection horizon. CAGRs derived from regression analysis of historical procurement pattern shifts and forward-looking budget intention surveys, with AI-powered coaching assistant deployment rates and CSRD compliance timeline adherence as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in enterprise software hiring cycles or venture capital deployment patterns would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline compression and platform economics enablement. Material shifts in EU regulatory enforcement intensity or psychometric assessment licensing cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Technical and Vocational Education Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
Global Mechatronics and Robotics Courses Market
Professional Development and Training
Business Coaching Service Market
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
Executive Education Program Market
Professional Development and Training
HR Professional Services Market
Professional Development and Training
Europe Leadership Development Program Market
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
HSE Consulting Training Services Market
Professional Development and Training
RPA Platform Training Market
Professional Development and Training
Firefighter Simulator Training Services Market
Professional Development and Training
US Life Coaching Market
Professional Development and Training
Canada Executive Education Program Market
Professional Development and Training
Personal Development Market
Professional Development and Training
Global Virtual Training and Simulation Market