
 Healthcare LMS Software Market | 2026-2036
Healthcare LMS Software Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare LMS Software Market Insights
Multi-source vendor strategies among large hospital networks is shifting procurement patterns across the sector. Oracle Corporation leverages its cloud infrastructure dominance to anchor enterprise deployments. SAP SE competes through deep ERP integration that sustains renewal rates. Relias LLC specializes in clinical competency tracking, positioning it within compliance-heavy segments.
Healthcare LMS software constitutes a digital platform for administering, documenting, and tracking educational programs for medical professionals, typically featuring SCORM compliance, role-based access controls, and audit-trail logging for credential verification. Cloud-based deployment leads product type adoption due to lower IT overhead and faster implementation cycles. Compliance training applications command disproportionate attention from buyers because regulatory audits directly tie workforce certification to operational licensing. Hospitals dominate end-user demand as integrated delivery networks consolidate training budgets across multiple facilities.
FDA quality system requirements and HIPAA privacy rules shape product architecture by mandating encrypted data handling and granular permission hierarchies. OSHA bloodborne pathogen standards further extend platform functionality into mandatory annual refresher workflows. Buyers must weigh interoperability against vendor lock-in as health systems consolidate their technology stacks.
Market Dynamics
Hospital network consolidation is compressing vendor selection cycles as integrated delivery systems demand unified training platforms across dozens of facilities. Procurement committees now prioritize interoperability over point-solution depth.
Growth Catalysts
- HIPAA audit mandates:Documented workforce competency tracking has become non-negotiable for covered entities facing OCR investigations. Platforms with granular audit trails command priority placement.
- OSHA bloodborne pathogen standards:Annual refresher workflows for clinical staff create recurring license revenue. Automated recertification triggers reduce administrative burden for infection control officers.
- Cloud infrastructure maturation:Lower IT overhead and faster implementation cycles accelerate replacement of on-premise legacy systems. Hospital CIOs favor subscription models that shift capital expenditure to operational budgets.
Market Restraints
- Data migration complexity:Decades of SCORM-compliant course libraries resist seamless transfer between platforms. Switching costs lock health systems into incumbent vendors despite functional limitations.
- Specialized clinical content scarcity:High-fidelity simulation modules for rare procedures require subject-matter expertise that generic LMS providers cannot replicate internally.
- Interoperability standards fragmentation:Competing health IT frameworks prevent seamless integration with HRIS and credentialing databases. HL7 FHIR adoption remains uneven across vendor ecosystems.
Strategic Opportunities
- Rural health clinic penetration:Federally qualified health centers lack dedicated training staff. Shared-service LMS consortiums could aggregate demand across dispersed primary care networks.
- AI-driven competency prediction:Machine learning models analyzing completion patterns and assessment scores enable proactive remediation before audit exposure. Early movers capture quality-improvement budgets.
- Residency program digitization:ACGME milestone tracking requirements create specialized demand for graduate medical education modules. GME office budgets remain insulated from general IT austerity.
Industry Challenges
- Instructional design talent scarcity:Clinical educators with both bedside experience and adult-learning credentials command premium compensation. Vendor content development pipelines face recruitment bottlenecks.
- Multi-jurisdiction compliance layering:State-level nursing board requirements vary in continuing education hour calculations. Platform architectures must accommodate 50-plus regulatory permutations without customization sprawl.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare LMS Software Market |
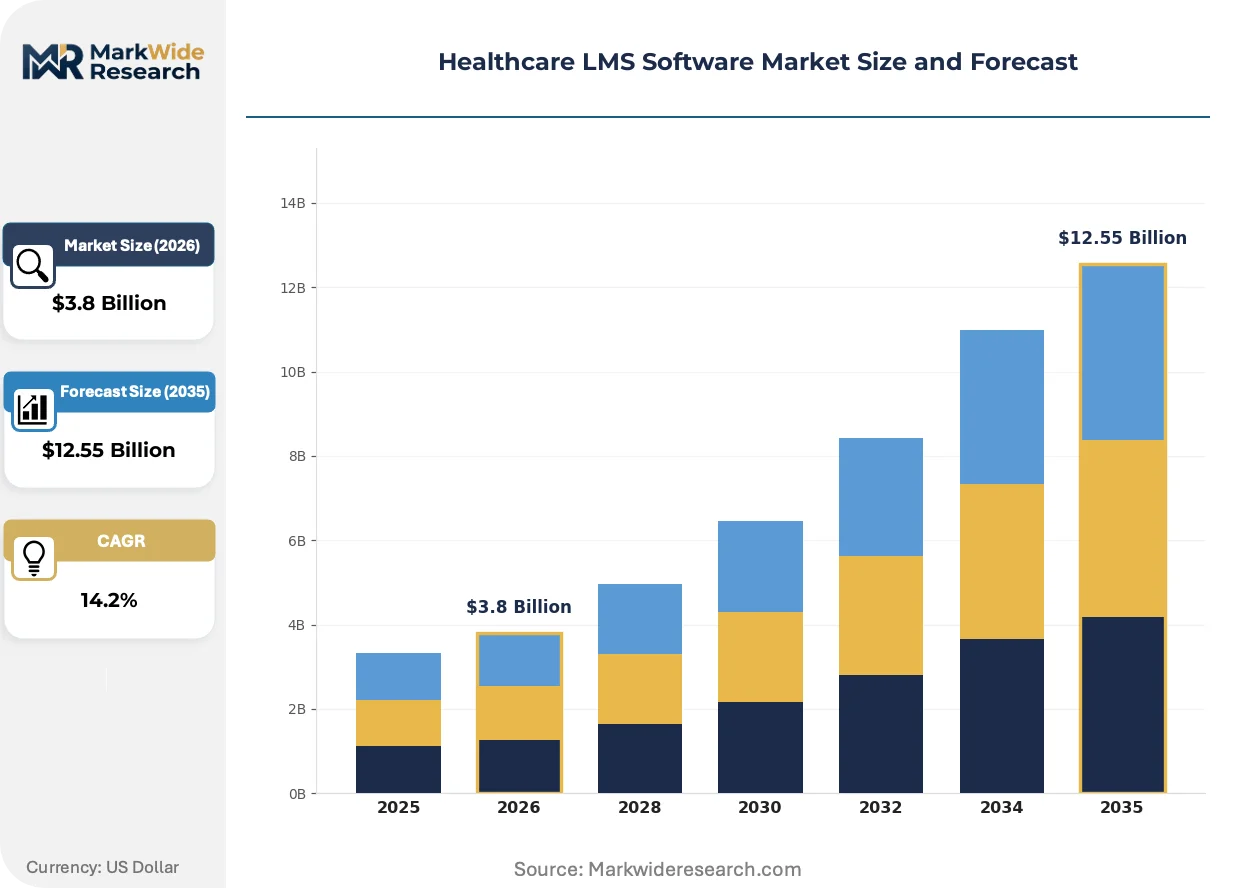
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Mobile Learning, Blended Learning End User: Hospitals, Clinics, Medical Schools, Health Organizations Delivery Mode: Synchronous, Asynchronous, Self-Paced, Instructor-Led Application: Compliance Training, Continuing Education, Employee Onboarding, Skills Development |
| Companies Covered | HealthStream Inc., Docebo S.p.A., Absorb Software Inc., Cornerstone OnDemand Inc., Relias LLC, Oracle Corporation, SAP SE, Adobe Inc., Instructure Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare LMS Software Market Trends and Innovations
Adaptive learning algorithms are personalizing competency pathways based on individual performance patterns rather than one-size-fits-all curricula. This shift compresses training time while improving knowledge retention metrics that regulators scrutinize.
Natural language processing is automating the generation of assessment questions from clinical protocol documents. Hospital education departments with lean staff are adopting these tools to maintain content freshness without dedicated instructional designers. The technology is automating what previously required weeks of manual item-writing, collapsing update cycles to match regulatory revision velocities.
FDA's updated Quality System Regulation guidance now explicitly references electronic training records as acceptable documentary evidence. Device manufacturers must demonstrate personnel qualification through timestamped, version-controlled learning management outputs. European notified bodies under MDR are similarly emphasizing documented competency trails for quality management system audits.
Subscription-based procurement is displacing perpetual license purchases as health systems prioritize cash-flow flexibility. CFOs negotiate seat-count elasticity clauses that accommodate seasonal hiring surges without renegotiation. This pattern is most visible among multi-state hospital networks consolidating vendor relationships under master service agreements.
Healthcare LMS Software Market Segmentation
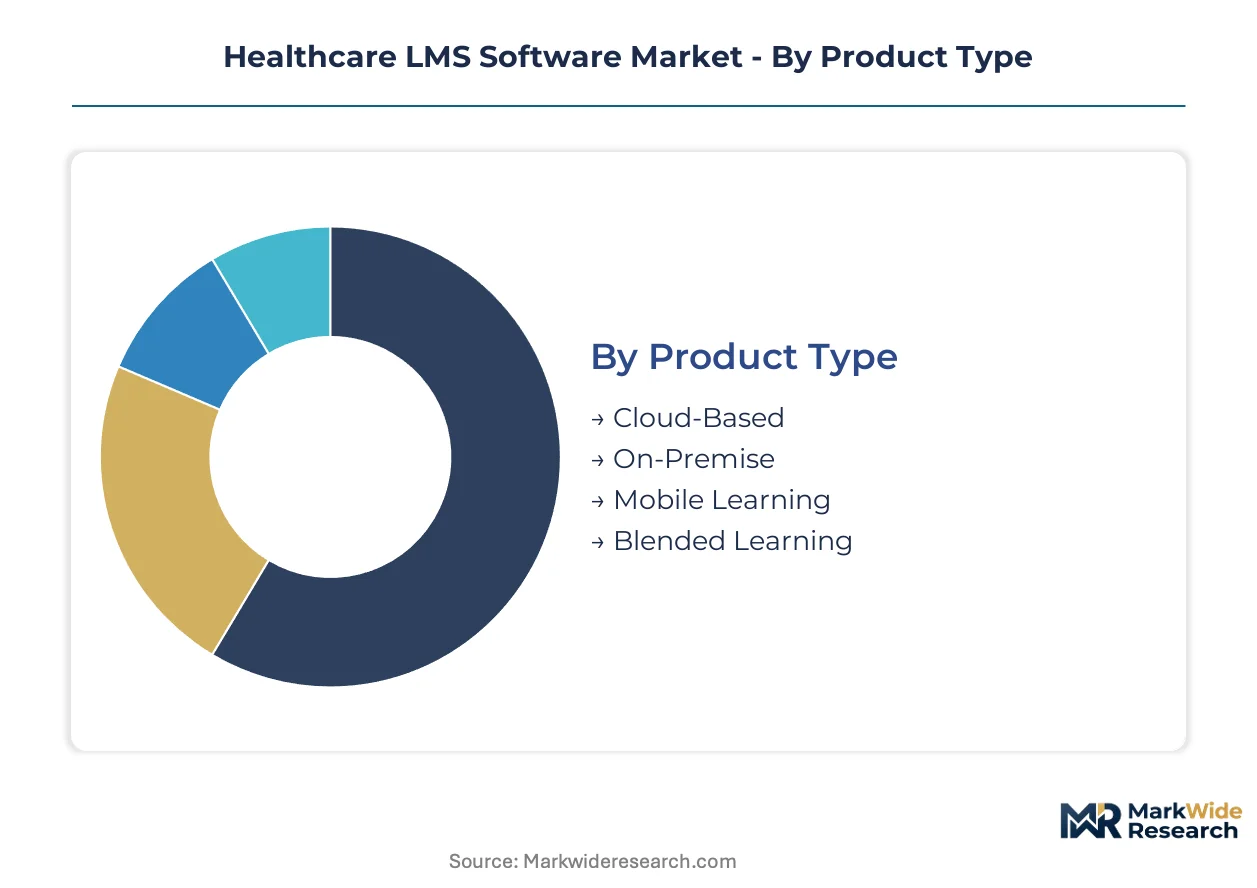
Healthcare LMS software segmentation reveals how procurement priorities diverge across buyer types. Cloud infrastructure preferences, regulatory compliance burdens, and workforce mobility requirements create distinct purchasing patterns that vendors must address through specialized configurations.
Product Type:
Deployment architecture separates buyers by IT resource availability and data sovereignty requirements.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance overhead for hospital IT departments. United States health networks with distributed facility footprints prioritize these platforms for centralized content administration and automatic security patching.
- On-Premise:Locally hosted installations maintain complete data control within institutional firewalls. Academic medical centers with research data restrictions and certain European hospitals under strict national data residency laws specify these deployments despite higher capital expenditure.
- Mobile Learning:Native iOS and Android applications enable bedside training completion for clinical staff with limited desk access. These solutions address the workflow realities of circulating nurses and emergency department personnel who cannot tether to workstations.
- Blended Learning:Hybrid configurations combine digital modules with in-person simulation sessions. Residency programs and surgical skills training rely on these platforms to document both online didactic completion and hands-on competency verification.
Cloud-Based deployments lead volumes today; Mobile Learning is gaining share fastest.
End User:
Organizational scale and regulatory exposure determine feature requirements and budget authorization levels.
- Hospitals:Enterprise-grade platforms serve integrated delivery networks with thousands of employees across multiple facilities. These buyers demand SCORM-compliant course libraries, granular role-based permissions, and automated recertification workflows tied to Joint Commission readiness.
- Clinics:Federally qualified health centers and specialty practices require streamlined implementations with minimal IT staff involvement. Shared-service consortiums aggregate demand across rural primary care networks that cannot sustain standalone training infrastructure.
- Medical Schools:Graduate medical education programs need specialized milestone tracking aligned with ACGME requirements. These institutions prioritize longitudinal competency portfolios that follow residents through rotational assignments.
- Health Organizations:Professional associations and public health departments deliver continuing education to dispersed member bases. These buyers emphasize credit-hour tracking for nursing board relicensure and multi-state regulatory compliance.
Hospitals dominate procurement value; Clinics show the steepest expansion trajectory as federal funding expands primary care access.
Delivery Mode:
Synchronous versus asynchronous preferences reflect workforce scheduling constraints and content complexity.
- Synchronous:Real-time virtual classrooms enable live interaction for complex clinical case discussions. These formats support interprofessional education requirements and team-based training scenarios that benefit from immediate instructor feedback.
- Asynchronous:Self-directed module completion accommodates shift workers and geographically distributed learners. The flexibility reduces training backlogs during staffing shortages while maintaining documented completion timestamps for audit trails.
- Self-Paced:Adaptive pathways adjust content sequencing based on individual assessment performance. These configurations compress training duration for experienced staff while ensuring remediation for knowledge gaps before competency sign-off.
- Instructor-Led:Traditional classroom formats persist for high-stakes procedural certification and simulation-based training. Device manufacturers and specialty societies retain these modalities for hands-on equipment training that cannot translate to screen-based instruction.
Asynchronous delivery leads volumes today; Self-Paced configurations are climbing the fastest as artificial intelligence personalizes learning pathways.
Application:
Use case prioritization varies by organizational risk profile and workforce composition.
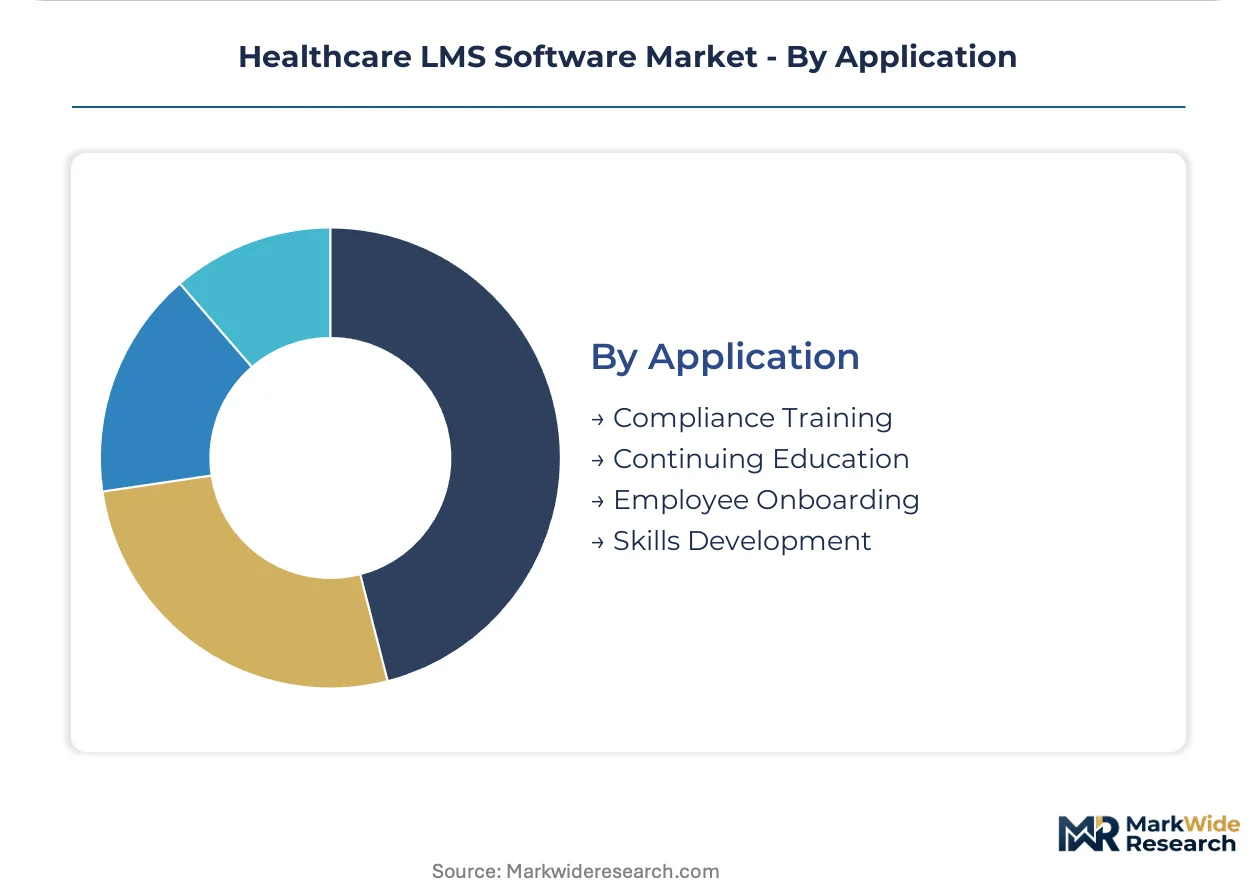
- Compliance Training:Mandatory modules address OSHA bloodborne pathogen standards, HIPAA privacy rule requirements, and Joint Commission patient safety goals. Automated enrollment based on job role ensures complete workforce coverage before audit cycles.
- Continuing Education:Professional development tracking maintains clinical licensure across nursing boards, medical boards, and specialty certification bodies. State-specific hour calculations and content accreditation requirements demand flexible platform architectures.
- Employee Onboarding:Standardized orientation sequences accelerate productivity for clinical and non-clinical hires. These workflows integrate with HRIS systems to trigger training assignments upon hire date and block payroll activation until completion.
- Skills Development:Competency-based pathways address specific clinical procedures, equipment operation, and quality improvement methodologies. Service line leaders purchase these modules to address identified performance gaps and support value-based care metrics.
Compliance Training leads volumes today; Skills Development is gaining share fastest as health systems link workforce capability to quality outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks drive the dominant share of procurement activity, with integrated delivery systems consolidating training infrastructure across multi-state footprints. Cloud migration accelerates as IT departments prioritize subscription models over capital-intensive on-premise deployments.
United States
HIPAA audit mandates from the Office for Civil Rights pressure covered entities toward platforms with granular audit trails. The FDA's Quality System Regulation explicitly recognizes electronic training records for device manufacturer compliance. Texas Medical Center clusters and Mayo Clinic's Rochester hub anchor enterprise-scale implementations serving thousands of clinical staff.
Germany
Academic medical centers with research data restrictions sustain demand for on-premise deployments despite higher capital requirements. The EU Medical Device Regulation from notified bodies emphasizes documented competency trails for quality management audits. Berlin's Charité and Munich's university hospital network concentrate procurement authority for centralized platform selection.
United Kingdom
NHS trust consolidation compresses vendor selection cycles as integrated care systems demand unified training across multiple hospitals. GDPR compliance requirements shape encrypted data handling and permission hierarchy architectures. London's academic health science centers and Manchester's hospital network drive specification standards adopted by regional trusts.
Canada
Provincial health authority consolidation creates procurement scale comparable to large US integrated delivery networks. Health Canada and PMRA regulations align with FDA quality system expectations for device manufacturer training documentation. Toronto's hospital network and Vancouver's coastal health authority concentrate platform deployment decisions for nationwide rollout patterns.
Australia
Rural health clinic penetration opportunities concentrate in federally qualified health centers lacking dedicated training staff. TGA compliance requirements for medical device manufacturers mirror FDA electronic record acceptance standards. Melbourne's hospital network and Sydney's academic medical centers anchor enterprise procurement that filters to regional health districts.
Healthcare LMS Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-driven competency prediction and mobile-first architectures. The vendor base stratifies across three tiers: cloud infrastructure giants anchoring enterprise deployments, specialized clinical competency trackers serving compliance-heavy segments, and ERP-integrated platforms sustaining renewal through workflow embedding. Market structure favors consolidation as hospital network procurement committees prioritize interoperability over point-solution depth. Dominant competitive moves include strategic partnerships with health IT consultancies and portfolio diversification into residency program digitization.
Within the cloud infrastructure tier, Oracle Corporation and SAP SE represent divergent anchoring strategies—one leveraging hyperscale dominance for enterprise deployments, the other embedding through deep ERP integration. Relias LLC exemplifies the specialized clinical competency archetype, occupying a position within compliance-heavy segments where regulatory audit exposure drives platform selection. These three anchors demonstrate how vendor positioning maps to buyer procurement priorities across hospital network consolidation cycles.
| Leading Market Players |
|---|
| HealthStream Inc. |
| Docebo S.p.A. |
| Absorb Software Inc. |
| Cornerstone OnDemand Inc. |
| Relias LLC |
| Oracle Corporation |
| SAP SE |
| Adobe Inc. |
| Instructure Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure maturation simultaneously compresses vendor cost structures and concentrates platform development among hyperscale providers, reshaping how procurement committees evaluate total cost of ownership against vendor lock-in risks.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers dominates SaaS-tiered subscription models, with seat-count elasticity clauses accommodating seasonal hiring surges without renegotiation. Price differentiation rests on HIPAA audit-trail granularity and ACGME milestone tracking certification tiers. Pricing pressure stems from hospital network consolidation demanding interoperability discounts. Federally qualified health centers exhibit highest price sensitivity; integrated delivery networks with master service agreements demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with AWS and Azure hyperscale regions for multi-tenant SaaS architectures, while specialized clinical content development concentrates in the United States, India, and Ireland. Raw material dependencies include NLP processing licenses, SCORM-compliant authoring tools, and FHIR integration modules. Supply chain risk centers on regulatory restriction: state-level nursing board requirement variations force platform customization sprawl. Distribution runs through health IT consultancies and GPO contracts to hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare LMS procurement has shifted toward late-cycle quality specifications, with buyers prioritizing AI-driven competency prediction and granular audit-trail architectures over baseline functionality.
For Market Incumbents: Lock in renewal rates through deep ERP integration that sustains workflow embedding against emerging mobile-first entrants. Invest in ACGME milestone tracking certification to capture insulated GME office budgets. Defensive consolidation through strategic partnerships with health IT consultancies protects positioning as hospital networks demand interoperability over point-solution depth. For New Entrants and Emerging Players: Rural health clinic networks present the most penetrable buyer archetype, with shared-service LMS consortiums aggregating demand across federally qualified health centers lacking dedicated training staff. Target AI-driven competency prediction to capture quality-improvement budgets before audit exposure. A mobile-first architecture with offline synchronization addresses bedside workflow realities of circulating nurses. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized clinical competency trackers with narrow compliance-heavy positioning but durable regulatory audit-driven demand. Long-term viability over a 5-10 year window favors platforms with proven FHIR integration and multi-jurisdiction compliance layering capabilities. Watch FDA Quality System Regulation enforcement intensity as inflection indicator for device manufacturer segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP embedding sustains renewal rates against point-solution competitors. |
| Strategic Partnership | Health IT consultancy alliances accelerate hospital network procurement cycles. |
| Acquisition of Specialist Firm | Clinical content developers address high-fidelity simulation module scarcity. |
| Product Launch | AI-driven competency prediction captures quality-improvement budgets pre-audit. |
| Geographic Expansion | Rural health clinic penetration aggregates demand through shared-service consortiums. |
Research Methodology
Direct dialogue with hospital CIOs, infection control officers, GME program directors, and health IT procurement managers grounded qualitative findings, cross-referenced against CMS Medicare data, hospital GPO contracts, FDA Quality System Regulation filings, and OCR audit documentation. Bottom-up facility-level deployment tracking and top-down vendor revenue analysis enabled triangulation across data sources.
Segmentation outputs across deployment model, organization scale, delivery mode, and regulatory compliance burden informed the analytical framework throughout the projection horizon. CAGRs derived from facility expansion patterns, cloud migration velocity, and ACGME residency program digitization rates. Forecast inputs incorporated HIPAA audit enforcement trends and OSHA bloodborne pathogen standard update frequencies.
Underlying measurement precision varies by segment; hospital network deployments carry tighter precision than rural clinic consortium estimates. Forecasts reflect assumptions about regulatory enforcement continuity and cloud infrastructure cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Global Training Software Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
Global Mobile Learning Market
Learning Management Systems (LMS)
Qatar E-Learning Management System Market
Learning Management Systems (LMS)
Corporate Learning Management System Market
Learning Management Systems (LMS)
School Management System Market
Learning Management Systems (LMS)
Smart Learning Systems Market