
 Academic Scheduling Software Market | 2026-2036
Academic Scheduling Software Market Size, Share, and Industry Trends Forecast 2026-2036
Academic Scheduling Software Market Outlook
GDPR enforcement in European education is pivoting procurement criteria toward data-sovereign scheduling architectures. Coursedog leverages native cloud infrastructure to compete in North American higher education. Ad Astra specializes in resource optimization algorithms for large research universities. TimeEdit anchors its position across Scandinavian public institutions with localized compliance tooling.
Academic scheduling software comprises algorithmic platforms that optimize temporal and spatial resource allocation across educational institutions, typically integrating constraint-based solvers with real-time calendar federation protocols. These systems orchestrate classroom utilization, faculty workload distribution, and student enrollment pathways to minimize scheduling conflicts and maximize institutional asset efficiency. Cloud-Based deployment leads structural growth due to lower capital barriers and elastic scaling during peak registration windows. Higher Education Institutions represent the deepest margin pool given complex multi-campus coordination needs, while K-12 Schools show faster uptake driven by district-wide standardization mandates. Automated Scheduling features command premium positioning as institutions seek to reduce manual timetable construction overhead.
FCC guidelines on educational broadband infrastructure shape connectivity assumptions underlying SaaS scheduling delivery in US territories. EDPB opinions on automated processing constrain how European platforms deploy AI-generated timetables without human oversight. ISO 27001 certification increasingly filters vendor shortlists for institutions handling sensitive student records. Stakeholders must weigh data residency requirements against the interoperability benefits of cross-border cloud architectures when selecting platform partners.
Market Dynamics
Cloud migration pressure from large public university systems is compressing deployment timelines for academic scheduling vendors, forcing architectural pivots toward elastic infrastructure that handles registration spikes without on-premise capital outlay.
Growth Catalysts
- EU AI Act compliance mandates:European higher education institutions must document human oversight for automated timetable generation, creating replacement demand for platforms with built-in audit trails and explainable constraint solvers.
- Multi-campus coordination complexity:Large research universities in the United States require real-time calendar federation across distributed facilities, pulling centralized SaaS solutions over fragmented legacy installs.
- Constraint-based solver advancement:Improvements in operations research algorithms now handle NP-hard scheduling problems with thousands of variables, enabling fully automated master timetable construction that previously required manual intervention.
Market Restraints
- Data residency requirements:GDPR and national implementations like France's CNIL guidance force European institutions toward sovereign cloud deployments, fragmenting vendor addressable market and raising infrastructure costs.
- Semiconductor supply concentration:Persistent tightness in advanced chip fabrication capacity constrains on-premise server refresh cycles for institutions maintaining hybrid scheduling architectures.
- Legacy system entrenchment:Decades-old student information systems with proprietary data formats create integration friction that prolongs implementation timelines and inflates professional services requirements.
Strategic Opportunities
- India's National Education Policy implementation:Mandates for digital infrastructure across 40,000+ higher education institutions create first-mover advantage for scheduling platforms with localized language support and UPI payment integration.
- K-12 district standardization wave:Consolidated procurement at state level in the United States enables single-vendor capture of entire district networks, compressing customer acquisition costs versus university-by-university sales.
- ISO 27001 certification as market filter:Institutions handling sensitive student records increasingly require certified information security management systems, creating defensive moat for compliant vendors against uncertified competitors.
Industry Challenges
- Operations research talent scarcity:Shortage of specialists capable of tuning constraint solvers for institution-specific academic rules forces vendors to invest in automated configuration tooling rather than bespoke consulting.
- Calendar protocol fragmentation:Incompatible implementations of iCalendar, CalDAV, and proprietary exchange formats across email and learning management systems demand costly middleware development for seamless integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Academic Scheduling Software Market |
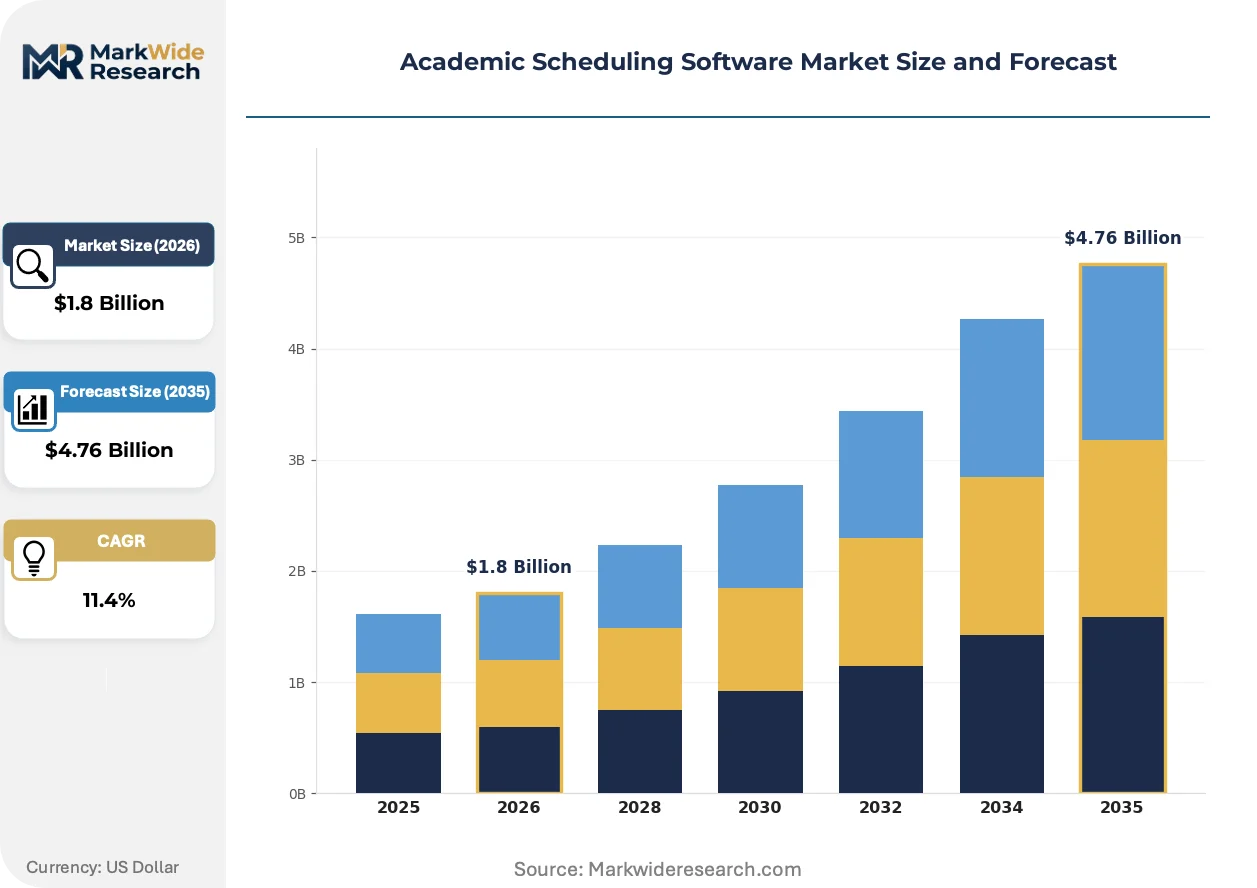
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: K-12 Schools, Higher Education Institutions, Training Centers, Corporations Feature: Automated Scheduling, Resource Management, Reporting, Customization Customer Type: Public Institutions, Private Institutions, Non-Profit Organizations, Others |
| Companies Covered | aSc Timetables, iSAMS, Ad Astra, Arlo, Creatrix Campus, Coursedog, Fedena, Skedda, TimeEdit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Academic Scheduling Software Market Strategic Shifts
Algorithmic transparency requirements and procurement centralization are forcing architectural and commercial model reinvention across academic scheduling software. Vendors must now demonstrate explainable automation while navigating compressed sales cycles.
Machine learning is integrating with traditional constraint-based solvers to predict enrollment patterns and preemptively flag scheduling conflicts before registration opens. Large public university systems in the United States are piloting these hybrid engines during peak registration windows. The technology is integrating predictive capacity planning with real-time room utilization sensors, compressing manual timetable revision cycles from weeks to hours.
The EU AI Act's risk classification framework for educational technology is mandating human-in-the-loop requirements for fully automated scheduling decisions. Vendors serving European higher education institutions must now engineer override workflows and decision logging that satisfy national supervisory authorities. Scandinavian public institutions are responding fastest, embedding compliance tooling directly into procurement specifications ahead of enforcement deadlines.
Centralized purchasing consortia are displacing decentralized academic department software selection across United States K-12 districts. State-level procurement vehicles now aggregate demand from hundreds of schools, compressing vendor sales cycles but intensifying price competition. Texas and California education agencies exemplify this concentration, issuing multi-year enterprise agreements that lock out point solutions lacking scale to meet consolidated service level requirements.
Academic Scheduling Software Market Segmentation
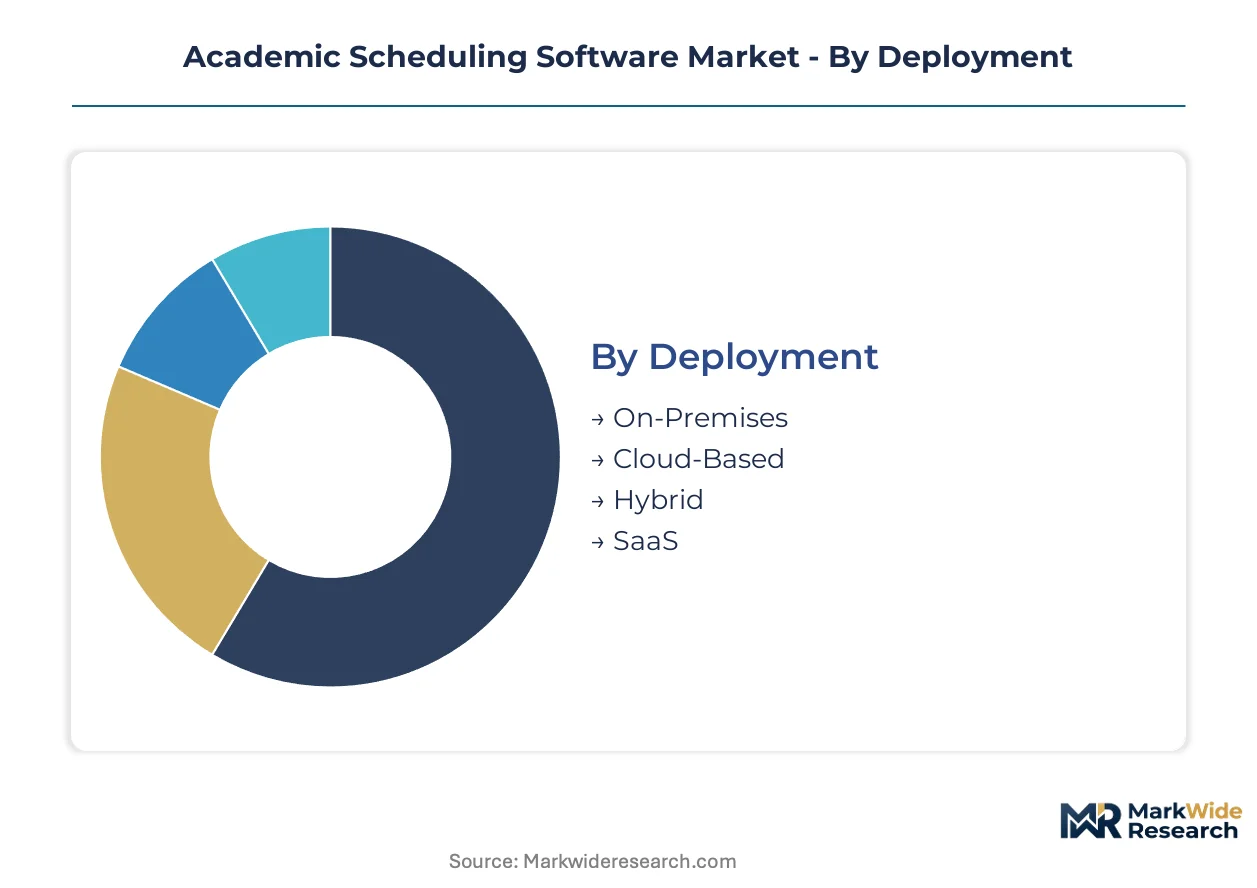
Segmentation in academic scheduling software reveals how certification burdens, infrastructure maturity, and procurement authority concentrate demand across distinct technology configurations. Institutions select deployment modes and feature sets based on regulatory exposure, IT legacy, and governance structures rather than functional requirements alone.
Deployment:
ISO 27001 certification filters vendor eligibility most aggressively in Cloud-Based and SaaS segments, while On-Premises deployments face semiconductor supply constraints that prolong refresh cycles. Hybrid architectures must satisfy both cloud security standards and on-premise data residency mandates simultaneously.
- Cloud-Based:Native cloud infrastructure delivers elastic scaling during peak registration windows without capital outlay. Demand concentrates in United States public university systems modernizing legacy infrastructure, pulled by FCC broadband guidelines that assume always-on connectivity. The EU AI Act's audit trail requirements are reshaping European procurement specifications toward platforms with built-in compliance tooling.
- SaaS:Subscription delivery compresses implementation timelines and shifts IT burden to vendors. Large research universities in the United States favor this model for multi-campus calendar federation, while GDPR enforcement in Europe forces evaluation of data-sovereign alternatives.
- On-Premises:Institutions with sensitive research partnerships or classified defense contracts maintain air-gapped installations. Persistent tightness in advanced chip fabrication constrains server refresh cycles.
- Hybrid:Combines local processing for sensitive workloads with cloud burst capacity for registration spikes. France's CNIL guidance on automated processing pushes European institutions toward this architecture for human-in-the-loop timetable oversight.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
End User:
Cost tier stratification separates enterprise-grade platforms serving complex coordination needs from lightweight solutions addressing standardized district mandates. Budget authority and implementation risk tolerance vary sharply across institutional types.
- Higher Education Institutions:Multi-campus research universities require constraint-based solvers handling thousands of variables across distributed facilities. Demand clusters in the United States where consolidated procurement vehicles aggregate demand, and in Scandinavia where localized compliance tooling anchors vendor selection. Operations research talent scarcity forces investment in automated configuration rather than bespoke consulting.
- K-12 Schools:District-wide standardization mandates in Texas and California enable single-vendor capture of entire school networks. State-level procurement compresses customer acquisition costs versus university-by-university sales cycles.
- Training Centers:Vocational and corporate training facilities prioritize rapid deployment and mobile accessibility over algorithmic sophistication. Shorter implementation timelines reduce professional services exposure.
- Corporations:Internal learning management systems demand seamless calendar protocol integration with existing enterprise software. Middleware development costs for iCalendar and Exchange compatibility filter vendor shortlists.
Highest margin concentration: Higher Education Institutions. Steepest expansion trajectory: K-12 Schools.
Feature:
Application criticality determines pricing power, with automation features commanding premium positioning while reporting functions face commoditization from embedded analytics in adjacent platforms.
- Automated Scheduling:Machine learning integration with traditional constraint solvers now handles NP-hard problems previously requiring manual intervention. Large public university systems pilot hybrid engines that compress timetable revision from weeks to hours. The EU AI Act mandates human oversight workflows for European deployments.
- Resource Management:Real-time room utilization sensors and predictive capacity planning optimize spatial asset efficiency. Research universities with extensive laboratory and shared facility networks drive specification requirements.
- Reporting:Standardized dashboards for enrollment analytics and classroom utilization face pressure from business intelligence tools already licensed institution-wide. Differentiation shifts toward export compatibility with external analytics platforms.
- Customization:Institution-specific academic rules and calendar structures demand configurable constraint definitions. Vendor investment in automated configuration tooling addresses operations research specialist scarcity.
Premium positioning: Automated Scheduling. Fastest feature integration: Resource Management.
Customer Type:
Procurement governance and funding stability create distinct vendor engagement models, with public institutions subject to competitive bidding mandates and private institutions offering faster decision cycles.
- Public Institutions:State funding cycles and competitive procurement regulations extend sales timelines. India's National Education Policy mandates for digital infrastructure across higher education institutions create volume opportunity with localized language requirements.
- Private Institutions:Board-level technology investment decisions bypass procurement committee delays. Tuition-dependent revenue models prioritize enrollment optimization features.
- Non-Profit Organizations:Grant-funded implementations face restricted overhead allowances that favor SaaS delivery over capital-intensive on-premise deployment. Donor reporting requirements drive demand for utilization transparency features.
- Others:International branch campuses and consortium arrangements require multi-jurisdictional compliance handling and currency flexibility in contracting.
Deepest addressable pool: Public Institutions. Shortest sales cycle: Private Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for educational technology in the United States, Germany, and India concentrate platform development, while regulatory divergence across GDPR jurisdictions and FCC broadband territories fragments deployment architectures.
United States
Large public university systems in Texas and California drive cloud migration through consolidated procurement vehicles. FCC educational broadband guidelines assume always-on connectivity for SaaS delivery. The Greater Boston research corridor demands constraint-based solvers for multi-campus coordination across MIT and Harvard facilities.
Germany
Technical universities in Baden-Württemberg and Bavaria require resource optimization for shared laboratory networks. The EU AI Act mandates human-in-the-loop workflows for automated timetable generation. Berlin-Brandenburg institutions pilot sovereign cloud deployments under BSI IT-Grundschutz standards.
United Kingdom
Oxford and Cambridge collegiate systems demand granular room utilization tracking across distributed historic facilities. ICO guidance on automated decision-making constrains AI-generated scheduling without audit trails. London's university consortiums aggregate demand for enterprise SaaS contracts.
India
National Education Policy mandates for digital infrastructure target 40,000 higher education institutions. UPI payment integration and localized language support filter vendor eligibility. Karnataka's Bangalore cluster anchors EdTech platform development with IISc and IIT deployment references.
Sweden
Scandinavian public institutions embed compliance tooling directly into procurement specifications ahead of EU AI Act enforcement. TimeEdit anchors market position through localized deployment. Stockholm's KTH Royal Institute drives specification requirements for research facility coordination.
Academic Scheduling Software Market Competitive Environment
United States vendors anchor the cloud-native tier; European specialists hold positions in compliance-heavy sovereign deployments. The vendor base separates into three strategic tiers: algorithmic optimization platforms, compliance-integrated suites, and lightweight district-standardization tools. Consolidation pressure intensifies as state-level procurement vehicles in Texas and California compress sales cycles toward multi-year enterprise agreements. M&A activity targets automated configuration capabilities to offset operations research talent scarcity.
Within the algorithmic optimization tier, Ad Astra and Coursedog exemplify contrasting geographic positioning. Ad Astra occupies a position among North American research university specialists, while Coursedog represents the cloud-native deployment archetype targeting large public university systems. TimeEdit anchors the European compliance-integrated segment with Scandinavian institutional relationships. These three companies collectively illustrate how vendor selection criteria diverge between constraint-solver sophistication in the United States and audit-trail engineering in GDPR jurisdictions.
| Leading Market Players |
|---|
| aSc Timetables |
| iSAMS |
| Ad Astra |
| Arlo |
| Creatrix Campus |
| Coursedog |
| Fedena |
| Skedda |
| TimeEdit |
| Others |
Value Chain & Pricing Dynamics
Large public university systems in Texas and California anchor procurement volume, compressing vendor pricing power toward multi-year SaaS subscription models with elastic scaling clauses. This buyer concentration forces tiered pricing stratification across premium compliance-integrated suites, standard cloud-native platforms, and economy-grade district-standardization tools.
Pricing Analysis
Short lead-time deployment premiums command pricing power as registration windows compress implementation timelines for cloud-native vendors. Three-tier pricing structure across premium compliance-integrated, standard multi-campus federation, and economy single-campus tiers differentiates by ISO 27001 certification status and constraint-solver sophistication. Cost compression in the economy tier intensifies because K-12 district procurement vehicles aggregate demand into consolidated RFPs. Training centers exhibit highest price sensitivity due to grant-funded budget constraints, while research universities with classified research partnerships show lowest sensitivity for air-gapped premium deployments.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center concentration in the United States, Ireland, and Singapore, with sovereign cloud alternatives emerging in Germany and India under BSI IT-Grundschutz and MeitY guidelines. Software development draws from operations research talent pools in Massachusetts, Bangalore, and Stockholm, while hardware sensor feeds for room utilization tracking source from Taiwanese and South Korean component manufacturers. Single-source vulnerability concentrates in advanced chip fabrication for on-premise hybrid architectures. Distribution runs through direct enterprise sales teams for higher education, with state-level procurement vehicles channeling K-12 demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from state-level procurement vehicles will force subscale vendors without ISO 27001 certification or automated configuration tooling into acquisition or exit. This dynamic favors algorithmic optimization platforms with compliance-integrated architectures.
For Market Incumbents: Anticipate margin compression from operations research talent scarcity by investing in automated constraint-solver configuration rather than bespoke consulting engagements. Acquire specialist firms with explainable AI audit-trail engineering to defend against EU AI Act displacement in European higher education. Channel control through multi-year enterprise agreements with Texas and California education agencies anchors recurring revenue against point-solution erosion. For New Entrants and Emerging Players: EU AI Act compliance mandates in Germany and France open a window for audit-trail-native scheduling platforms with human-in-the-loop workflow engineering. Target India's National Education Policy implementation as the most penetrable geography, where localized Hindi and Tamil language support combined with UPI payment integration filters incumbent eligibility. Pursue K-12 district standardization in Texas through partnership with existing student information system vendors rather than direct university sales cycles. For Investors and Strategic Acquirers: The window for entry favors vertically integrated platforms with both constraint-solver IP and compliance tooling. Long-term viability hinges on defensive moats around automated configuration capabilities that offset specialist scarcity. Watch for inflection where European institutions begin enforcement-phase procurement specifications with mandatory explainable AI documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Automated configuration tooling addresses operations research talent scarcity in constraint-solver tuning. |
| Platform Integration | Native calendar federation with MIT and Harvard systems anchors multi-campus research university references. |
| Geographic Expansion | Localized deployment in Karnataka's Bangalore cluster leverages IISc and IIT credibility for National Education Policy capture. |
| Strategic Partnership | Integration with Texas Education Agency procurement vehicles compresses customer acquisition costs across district networks. |
| Product Launch | Human-in-the-loop compliance tooling satisfies Berlin-Brandenburg BSI pilot requirements ahead of EU AI Act enforcement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with university CIOs, K-12 district technology directors, student information system integration specialists, and procurement officers at state education agencies. Bottom-up triangulation against top-down regulatory impact assessments validated segment-level demand estimates across deployment models and end-user categories.
Data-stream reconciliation across enrollment database disclosures, hyperscaler infrastructure expansion reports, and FCC broadband infrastructure filings informed the projection framework. Segmentation modeling incorporated deployment architecture, institutional governance type, constraint complexity tier, and regional regulatory cluster throughout the forecast period. CAGRs derived from institution-level digital transformation budget trajectories and procurement cycle velocity indicators specific to higher education and K-12 verticals.
Caveats apply where EU AI Act enforcement timing or semiconductor supply normalization could materially shift the outlook for hybrid architecture adoption. Forecasts reflect documented assumptions regarding cloud migration velocity and procurement centralization momentum. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Private Tutoring Market
Education & Training
HR Professional Services Market
Education & Training
Asia-Pacific Corporate Training Market
Education & Training
Smart Education System Market
Education & Training
E-Learning Services Market
Education & Training
GCC Private K12 Education Market
Education & Training
School Management System Market
Education & Training
University Management System Market
Education & Training
In-Person Learning Market
Education & Training
IT Training Market
Education & Training
Online K-12 Education Market
Education & Training
Language Learning Software Market
Education & Training
United States E-Learning Market
Education & Training
Virtual Reality in Education Market
Education & Training
Braille Book Market
Education & Training
Global Classroom Management Software Market