
 North America IT Training Market | 2026-2036
North America IT Training Market Size, Share, and Industry Trends Forecast 2026-2036
North America IT Training Market Intelligence
Modular credential stacking is pivoting how enterprises purchase workforce development, replacing monolithic degree programs with discrete, vendor-certified micro-credentials. Fast Lane leverages its Cisco and AWS authorized training status to anchor premium pricing in cloud certification pipelines. Pluralsight competes through subscription-based skill analytics that sustain recurring revenue from Fortune 500 technology budgets. INE differentiates through hands-on cyber ranges that dominate the offensive security training niche.
North America IT Training encompasses structured instructional programs designed to develop proficiency in information technology systems, software development, network administration, and cybersecurity operations, typically delivered through curricula mapped to vendor certification objectives or competency-based assessments. These programs serve commercial enterprises seeking workforce capability alignment with evolving technology stacks, government agencies requiring cleared personnel with current security credentials, and individual practitioners pursuing career mobility through validated skill demonstration. Cloud Computing and Cybersecurity segments command the largest current revenue pools as enterprise migration and threat surface expansion drive mandatory recertification cycles, while AI-focused coursework represents the fastest-expanding enrollment category as generative tool deployment creates urgent reskilling imperatives across non-technical roles. Bootcamp delivery models concentrate margin capture through compressed timelines and employer tuition reimbursement channels, whereas hybrid modalities are displacing purely in-person formats as organizations standardize distributed workforce development policies.
FCC workforce development initiatives, NIST cybersecurity framework compliance mandates, and Canadian Treasury Board Secretariat IT competency standards collectively shape procurement requirements for government-facing training vendors. OSHA-aligned instructional safety protocols and state-level professional licensing boards in Texas and California further filter market access for providers seeking public sector contracts. Stakeholders must monitor how federal zero-trust architecture deadlines and provincial privacy law harmonization reshape certification currency and cross-border program recognition.
Market Dynamics
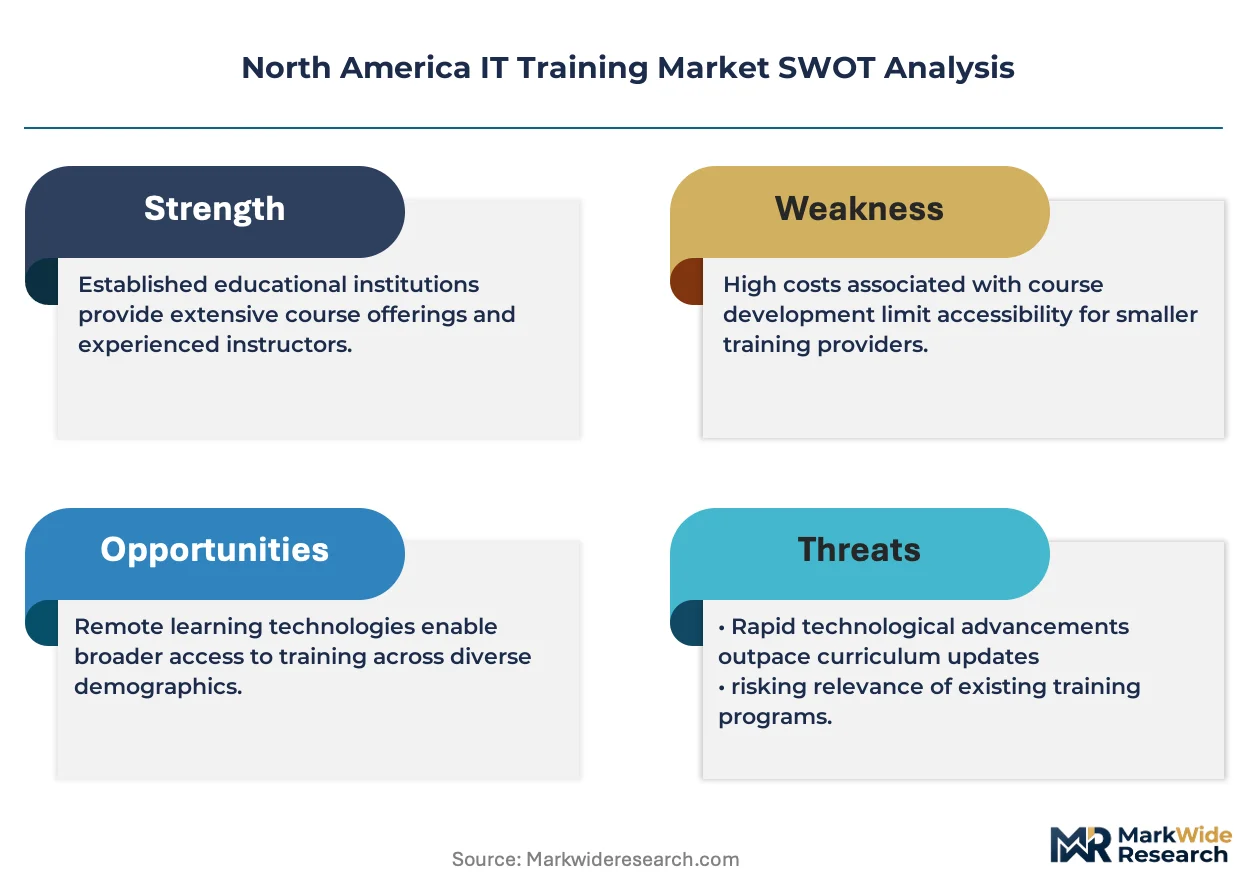
Zero-trust security mandates and cloud migration deadlines are compressing recertification cycles across federal and enterprise buyers, forcing training providers to accelerate curriculum refresh rates and modularize delivery formats.
Growth Catalysts
- FCC Workforce Development Initiatives:Federal broadband expansion programs mandate technical upskilling for installation and maintenance crews across underserved U.S. counties.
- Cloud Migration Deadlines:Enterprise infrastructure refresh cycles in financial services and healthcare are driving mandatory AWS and Azure certification pipelines for internal IT staff.
- Texas Defense Corridors:Concentrated defense contracting in Dallas-Fort Worth and Houston generates sustained demand for cleared personnel with current CompTIA Security+ and CISSP credentials.
Market Restraints
- Instructor Scarcity:Qualified cybersecurity practitioners command premium salaries in private sector roles, constraining available teaching talent for hands-on lab instruction.
- Certification Cost Volatility:Vendor exam fees for Cisco CCIE and AWS Solutions Architect certifications fluctuate with exchange rates and policy changes, squeezing provider margins.
- State Licensing Fragmentation:California and Texas maintain divergent professional licensing requirements for IT instructors, complicating cross-border program delivery.
Strategic Opportunities
- Canadian Provincial Expansion:Ontario and British Columbia technology hubs show underpenetrated demand for French-English bilingual cloud training programs.
- AI-Non-Technical Convergence:Generative tool deployment across marketing, legal, and HR functions creates white space for prompt engineering curricula targeting non-technical professionals.
- Employer Tuition Reimbursement Channels:Fortune 500 technology budgets increasingly route through HR-led learning and development platforms, bypassing traditional IT procurement.
Industry Challenges
- Lab Infrastructure Capex:Cyber range and sandbox environments require continuous hardware refresh to mirror evolving threat landscapes.
- Cross-Border Credential Recognition:Canadian Treasury Board Secretariat IT competency standards diverge from U.S. NIST frameworks, complicating program standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America IT Training Market |
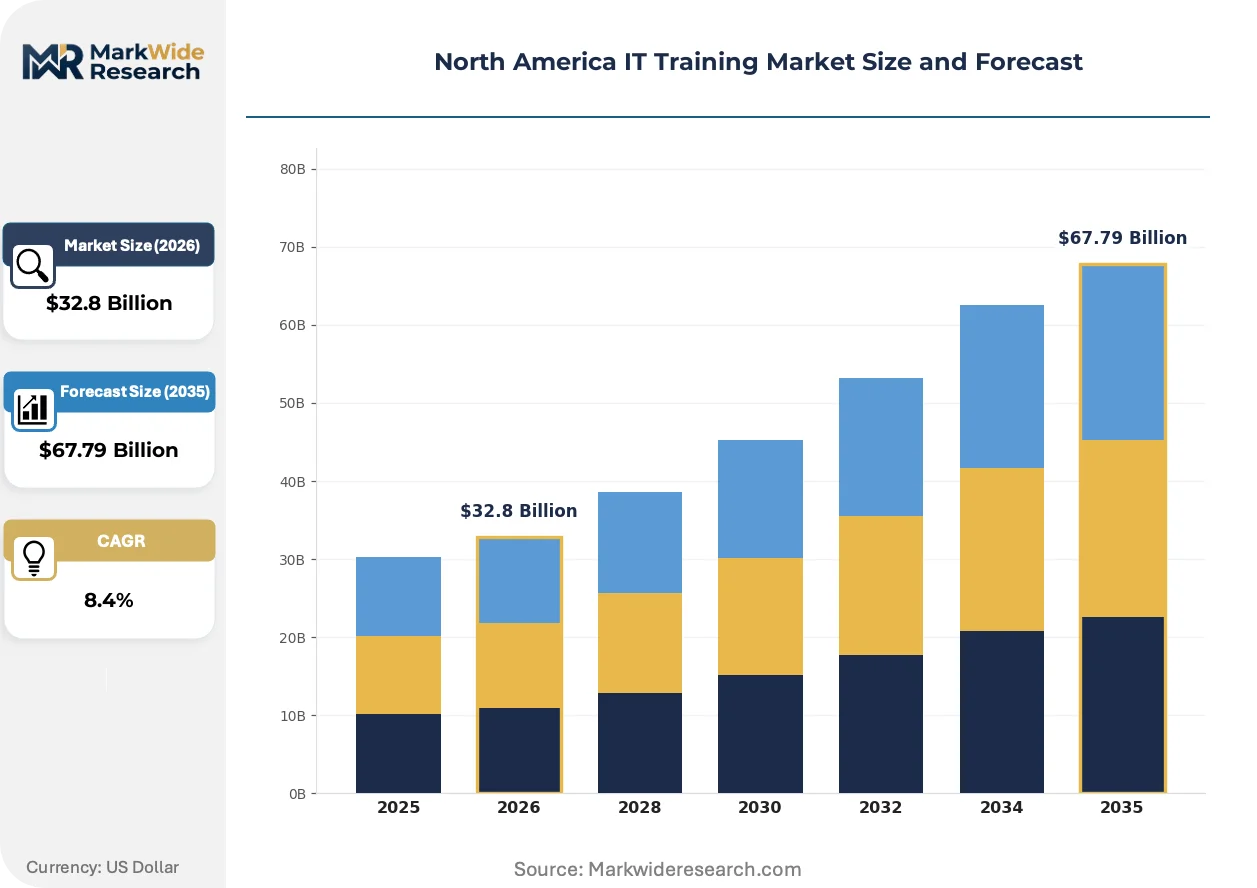
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Online, In-Person, Hybrid, Blended Course Type: Certification, Bootcamp, Degree, Workshop Technology Focus: Cloud Computing, Cybersecurity, Data Science, AI Target Audience: Individuals, Corporates, Educational Institutions, Government |
| Companies Covered | Fast Lane, ProTech Professional Technical Services, Microtek Learning, Edstellar, INE, Global Knowledge, LearnQuest, Pluralsight, New Horizons Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America IT Training Market Strategic Shifts & Innovations
Instructional delivery models are fragmenting as employers reject time-intensive degree pathways in favor of competency-verified micro-credentials that align directly to vendor certification objectives.
Immersive cyber range technology is rewriting how offensive security skills are validated. Defense contractors and financial institutions in Virginia and New York are adopting persistent virtual environments that simulate live adversarial engagement. This compression of lab-to-battlefield timelines is collapsing traditional classroom-based security training margins.
NIST cybersecurity framework compliance mandates are reshaping procurement requirements for government-facing training vendors. Federal agencies now require documented alignment to specific control families as a precondition for contract award. Providers lacking NIST mapping in their curricula are being filtered from defense and civilian agency RFPs.
Enterprise buyers are consolidating vendor relationships through subscription-based skill analytics platforms that track proficiency progression across distributed workforces. This behavioral shift displaces per-seat course licensing in favor of recurring revenue arrangements tied to measurable competency outcomes. The pattern is most visible among Fortune 500 technology budgets in California and Texas.
North America IT Training Market Segmentation
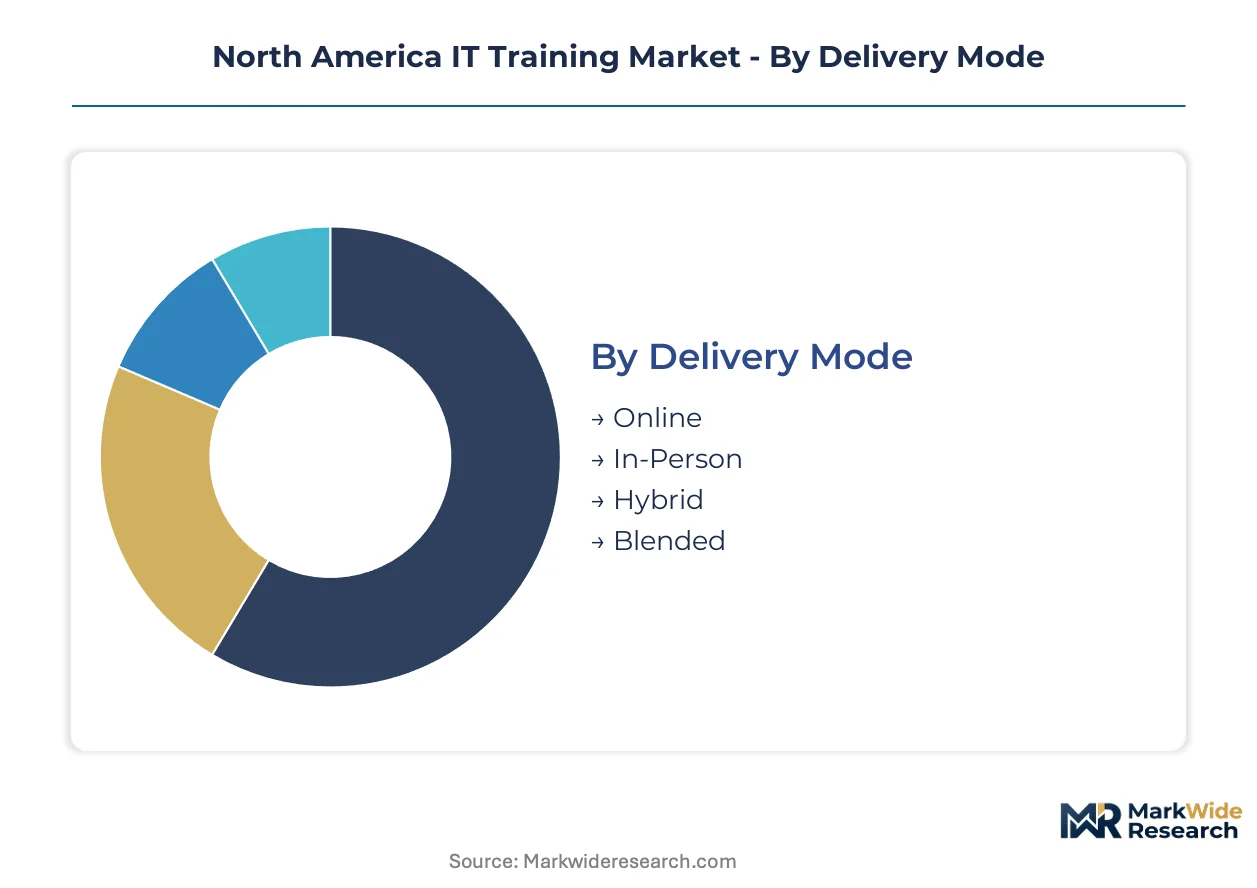
Segmentation in North American IT training reveals how procurement patterns diverge between federal compliance mandates and corporate workforce development budgets. Each dimension exposes distinct margin structures, refresh cycles, and vendor certification dependencies that reshape provider competitive positioning.
Delivery Mode:
Standalone delivery formats dominate enterprise procurement for cleared personnel, while embedded hybrid models capture distributed workforce mandates.
- Online:Self-paced modules with vendor-proctored examination integration. Texas and California enterprise buyers route procurement through HR-led learning platforms, bypassing traditional IT channels.
- In-Person:Instructor-led classroom formats with hands-on lab access. Defense contracting corridors in Virginia and Texas sustain premium pricing for cleared-facility instruction.
- Hybrid:Blended synchronous and asynchronous components with flexible scheduling.
- Blended:Structured rotation between virtual theory and concentrated in-person practicum.
Volume placements concentrate in Online; the faster expansion belongs to Hybrid.
Course Type:
Cost-tier stratification separates compressed timeline programs from extended degree pathways, with reimbursement channels determining margin capture.
- Certification:Vendor-aligned curricula mapped to Cisco, AWS, or CompTIA examination objectives. Federal zero-trust mandates in the United States compress recertification cycles to 18-24 months.
- Bootcamp:Intensive 12-16 week programs with employer tuition reimbursement integration. Financial services hubs in New York and Chicago drive sustained enrollment.
- Degree:Accredited academic programs with extended completion timelines.
- Workshop:Single-topic intensive sessions for targeted skill acquisition.
Certification captures the largest placement volume; Bootcamp climbs the fastest as enterprise buyers reject time-intensive alternatives.
Technology Focus:
Application-critical segments align with infrastructure migration deadlines and threat surface expansion, while emerging categories reshape non-technical role requirements.
- Cloud Computing:AWS, Azure, and Google Cloud platform curricula with hands-on sandbox environments. Canadian provincial hubs in Ontario and British Columbia show underpenetrated demand for bilingual program delivery.
- Cybersecurity:Offensive security, defensive operations, and compliance mapping to NIST frameworks. Virginia defense contractors adopt persistent cyber ranges for live adversarial simulation.
- Data Science:Analytics, visualization, and statistical modeling coursework.
- AI:Generative tool deployment and prompt engineering for non-technical professionals.
Cloud Computing holds the steepest placement trajectory; AI gains share fastest as legal, marketing, and HR functions deploy generative tools.
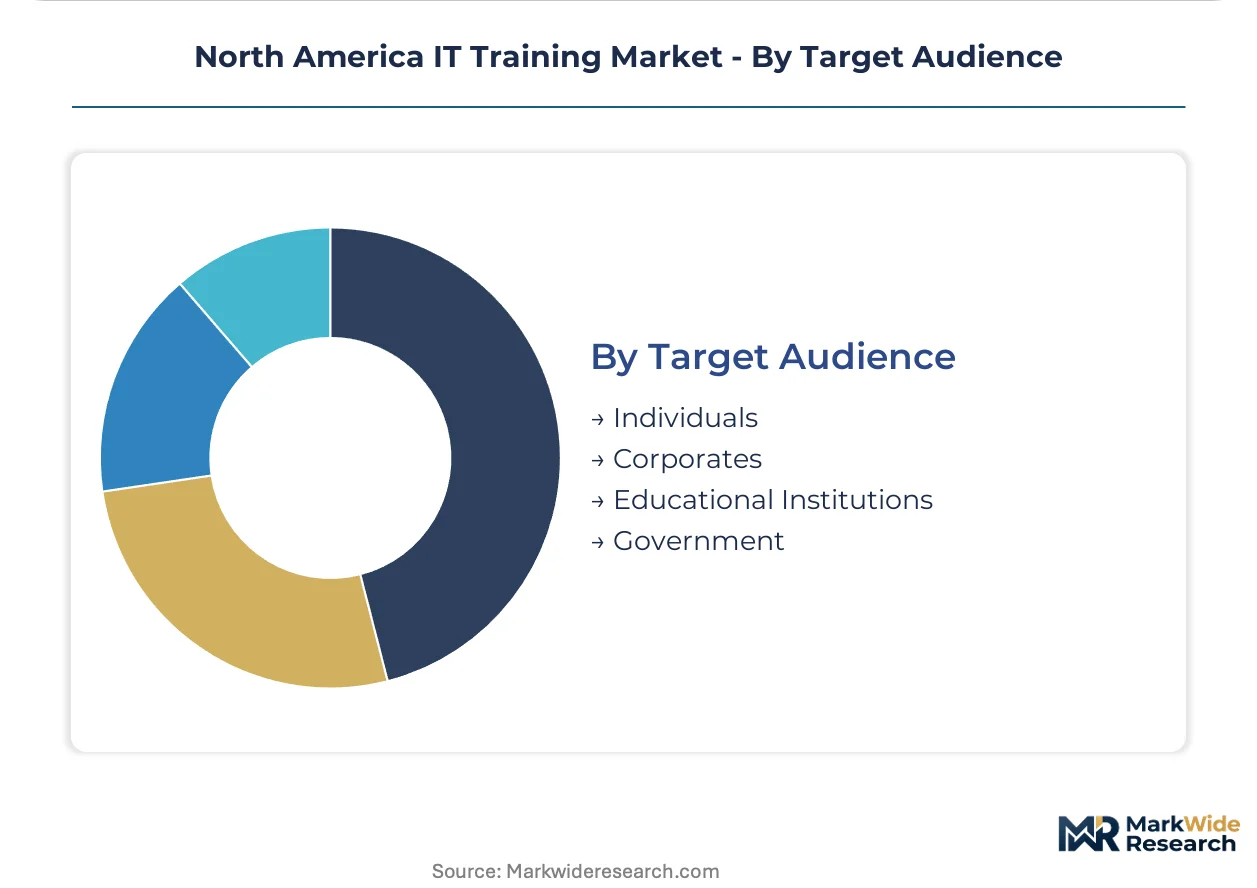
Target Audience:
Customer-type concentration determines procurement authority, with government mandates requiring documented NIST alignment and corporate budgets routing through learning analytics platforms.
- Individuals:Self-funded practitioners pursuing career mobility through validated credentials. CompTIA Security+ and CISSP dominate Texas defense corridor demand.
- Corporates:Fortune 500 technology budgets with subscription-based skill analytics requirements. California and Texas buyers consolidate vendor relationships through recurring revenue arrangements.
- Educational Institutions:University and college partnerships for credit-bearing program integration.
- Government:Federal agencies and Canadian departments with cleared personnel requirements.
Corporates anchor volume placement; Government contracts expand most quickly as zero-trust deadlines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of IT training value while Canada generates specialized bilingual delivery capacity. Mexico emerges as a nearshore delivery hub for compressed-format programs serving enterprise buyers.
United States
Federal zero-trust mandates and defense contracting requirements drive procurement volume. FCC workforce development initiatives mandate technical upskilling for broadband installation crews across underserved counties. Virginia defense corridors and Texas financial services hubs sustain premium pricing for cleared-facility instruction and cloud certification pipelines.
Canada
Ontario and British Columbia technology hubs generate underpenetrated demand for French-English bilingual cloud training programs. Canadian Treasury Board Secretariat IT competency standards shape procurement requirements for government-facing vendors. Toronto and Vancouver clusters concentrate delivery infrastructure for cross-border enterprise contracts.
Mexico
Nearshore delivery models capture compressed-format bootcamp demand from U.S. enterprise buyers seeking cost efficiency. State-level professional development programs in Nuevo León and Mexico City Metro support technical workforce expansion. Guadalajara technology corridor anchors delivery infrastructure for Spanish-language certification curricula.
North America IT Training Market Key Industry Players
The competitive structure tilts toward authorized training partners with vendor certification pipelines. Market concentration clusters around subscription-based skill analytics platforms and hands-on cyber range operators. Three archetypes dominate: vendor-authorized premium providers, recurring-revenue analytics platforms, and specialized offensive security labs. Competitive moves center on curriculum modularization and employer tuition reimbursement channel capture.
Within the vendor-authorized tier, Fast Lane and Global Knowledge anchor premium positioning through Cisco and AWS authorized training status. Pluralsight occupies a position exemplifying the subscription-based skill analytics archetype with Fortune 500 technology budget penetration. INE represents the specialized offensive security lab segment through hands-on cyber range differentiation.
| Leading Market Players |
|---|
| Fast Lane |
| ProTech Professional Technical Services |
| Microtek Learning |
| Edstellar |
| INE |
| Global Knowledge |
| LearnQuest |
| Pluralsight |
| New Horizons Worldwide |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up training specialists anchor supply consolidation across the United States and Canada, compressing vendor counts while hardening pricing discipline for authorized certification pipelines. Their platform economics favor recurring subscription models over transactional per-seat licensing, reshaping how enterprise buyers negotiate multi-year workforce development contracts.
Pricing Analysis
Margin tightening in vendor-authorized tiers reflects instructor scarcity and continuous cyber range infrastructure refresh cycles. Three-tier pricing structure across premium, standard, and economy levels separates Cisco CCIE bootcamps from CompTIA Security+ self-paced modules and generic workshop offerings. Price differentiation hinges on certification level and geographic delivery cost, with cleared-facility instruction in Virginia commanding substantial premiums over online equivalents. Corporate learning and development platforms exhibit lowest price sensitivity; individual self-funded practitioners face highest cost compression.
Supply Chain Analysis
Reverse-logistics flows for proctored examination hardware and refurbished lab equipment concentrate refurbishment operations in Texas and California distribution nodes. Content development draws from instructional design clusters in India, Poland, and the Philippines, while live instructor talent sources predominantly from United States defense contracting corridors. Single-source vulnerability persists in AWS and Cisco authorized training partner networks. Distribution runs through HR-led learning platforms and direct federal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor authorization requirements and cyber range capital intensity are forcing sub-scale providers toward exit or acquisition, consolidating competitive architecture around platform-scale operators.
For Market Incumbents: Extend authorized partner status into adjacent cloud platforms before Microsoft and Google tighten certification pipeline controls. Acquire specialized cyber range operators in Virginia and Texas to defend against pure-play immersive lab entrants. Vertical integration into employer tuition reimbursement channel management reduces customer acquisition cost erosion. For New Entrants and Emerging Players: Employer-sponsored learning platform integrations offer lowest-friction customer access for AI-focused non-technical curricula. White space concentrates in French-English bilingual cloud training for Ontario and British Columbia provincial contracts. Go-to-market through HR analytics platform partnerships bypasses entrenched IT procurement gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale bootcamp operators with cleared-facility access in Texas defense corridors. Long-term viability centers on recurring revenue platform conversion rather than transactional course licensing. Monitor federal zero-trust implementation deadline acceleration as enrollment inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Authorized Partner Expansion | Cisco and AWS certification pipelines lock in premium pricing for federal contracting eligibility. |
| Cyber Range Infrastructure Buildout | Persistent virtual environments in Virginia satisfy defense contractor live adversarial simulation mandates. |
| HR Platform Integration | Fortune 500 learning analytics consolidation routes procurement through non-IT budget owners. |
| Bilingual Curriculum Development | French-English delivery captures underpenetrated Ontario and British Columbia provincial demand. |
| AI Non-Technical Course Launch | Prompt engineering curricula for legal and marketing functions open enterprise beyond traditional IT buyers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with training provider executives, federal procurement officers, corporate learning and development directors, and vendor certification program managers. FCC workforce development databases, NIST cybersecurity framework documentation, Canadian Treasury Board Secretariat competency standards, and hyperscaler training partner disclosures furnished validation layers. Bottom-up enrollment tracking across delivery modes converged with top-down enterprise technology spending estimates.
Data-stream reconciliation across subscription billing systems, proctored examination volumes, and employer reimbursement claims generated consistent trajectory signals. Segmentation dimensions modeled include delivery mode, course type, technology focus, and target audience across the analysis window. CAGRs derived from fitted growth curves applied to vendor-certified pipeline expansion and federal mandate acceleration. Instructor supply constraints and cyber range depreciation schedules entered as boundary conditions.
The model holds under stable federal zero-trust implementation timelines and consistent vendor exam pricing; deviation in Canadian provincial harmonization or AWS certification requirement changes would shift enrollment patterns. Practitioners should monitor NIST framework revision cycles and hyperscaler partner program policy updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Global Mechatronics and Robotics Courses Market
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
Leadership Development Program Market
Professional Development and Training
Canada Executive Education Program Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
Equipment Maintenance Training Services Market
Professional Development and Training
Business Coaching Service Market
Professional Development and Training
RPA Platform Training Market
Professional Development and Training
HR Professional Services Market
Professional Development and Training
Personal Development Market
Professional Development and Training
Coding Bootcamp Market
Professional Development and Training
Europe Leadership Development Program Market
Professional Development and Training
US Life Coaching Market
Professional Development and Training
Cognitive Assessment and Training Market
Professional Development and Training
HSE Consulting Training Services Market
Professional Development and Training
GCC Soft Skills Training Market