
 United States Executive Education Program Market | 2026-2036
United States Executive Education Program Market Size, Share, and Industry Trends Forecast 2026-2036
United States Executive Education Program Market Analytics
Mid-career leadership pipeline gaps is rotating corporate training budgets toward structured executive development. Wharton Executive Education leverages its finance-centric curriculum to anchor Philadelphia's competitive position. MIT Sloan School of Management sustains technology leadership through analytics-intensive program design. Harvard Executive Education dominates the premium open-enrollment segment with its established brand authority.
United States Executive Education Programs comprise structured, non-degree learning modules delivered to senior managers and C-suite professionals, typically spanning intensive residencies of one to twelve weeks with cohort sizes of 20-60 participants, designed to sharpen strategic decision-making without conferring formal academic credentials. Custom Programs command the deepest client relationships through tailored curricula aligned to specific organizational transformation objectives. Online Programs represent the fastest-expanding delivery channel as enterprise buyers prioritize scalable talent development across distributed workforces. Open Enrollment formats retain strong margin pools by amortizing curriculum development across multiple paying cohorts.
The Department of Education oversees accreditation standards that determine institutional eligibility for Title IV funding pathways, while regional accreditors such as the Middle States Commission on Higher Education evaluate program quality benchmarks that influence corporate buyer trust. State-level workforce development boards in Texas and New York channel public subsidies toward reskilling partnerships that expand addressable demand. Stakeholders must monitor how artificial intelligence tooling reshapes curriculum design labor and whether employer-sponsored education tax treatments shift under congressional review.
Market Dynamics
Artificial intelligence tooling is compressing curriculum development cycles while reshaping how Fortune 500 firms evaluate program ROI. This structural shift forces providers to demonstrate measurable competency gains rather than credential prestige alone.
Growth Catalysts
- Gainful Employment Rules:The Department of Education's tightened accountability standards filter out low-quality providers, concentrating demand among accredited institutions with verified placement outcomes.
- Texas Workforce Development Board subsidies:State-level reskilling partnerships channel public funds toward executive education, expanding addressable demand among mid-market enterprises.
- AI-augmented personalization engines:Adaptive learning platforms enable scalable customization previously restricted to high-touch custom programs, broadening enterprise buyer access.
Market Restraints
- Accreditation compliance costs:Regional accreditors such as the Middle States Commission on Higher Education impose multi-year review cycles that freeze curriculum innovation timelines.
- Faculty supply concentration:Practitioner-scholars with C-suite experience cluster in Boston, Philadelphia, and Palo Alto, creating geographic hiring bottlenecks for new program launches.
- Employer tuition assistance tax uncertainty:Congressional review of Section 127 benefits threatens the pretreatment structure underpinning corporate sponsorship models.
Strategic Opportunities
- Midwestern manufacturing corridor:Ohio and Michigan's industrial automation transition creates unmet demand for operations leadership programs outside traditional financial services curricula.
- AI-human facilitation hybrids:Convergence of generative content engines with synchronous cohort coaching enables premium pricing at mass-market unit economics.
- Department of Labor WIOA incentives:Workforce Innovation and Opportunity Act funding streams support provider partnerships with state economic development agencies.
Industry Challenges
- Instructional design talent scarcity:Competency in learning experience design and data analytics remains concentrated among Silicon Valley edtech specialists, complicating incumbent faculty transitions.
- Legacy LMS integration friction:Enterprise clients demand seamless connectivity with Workday and SAP SuccessFactors, requiring costly API development for standalone program platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Executive Education Program Market |
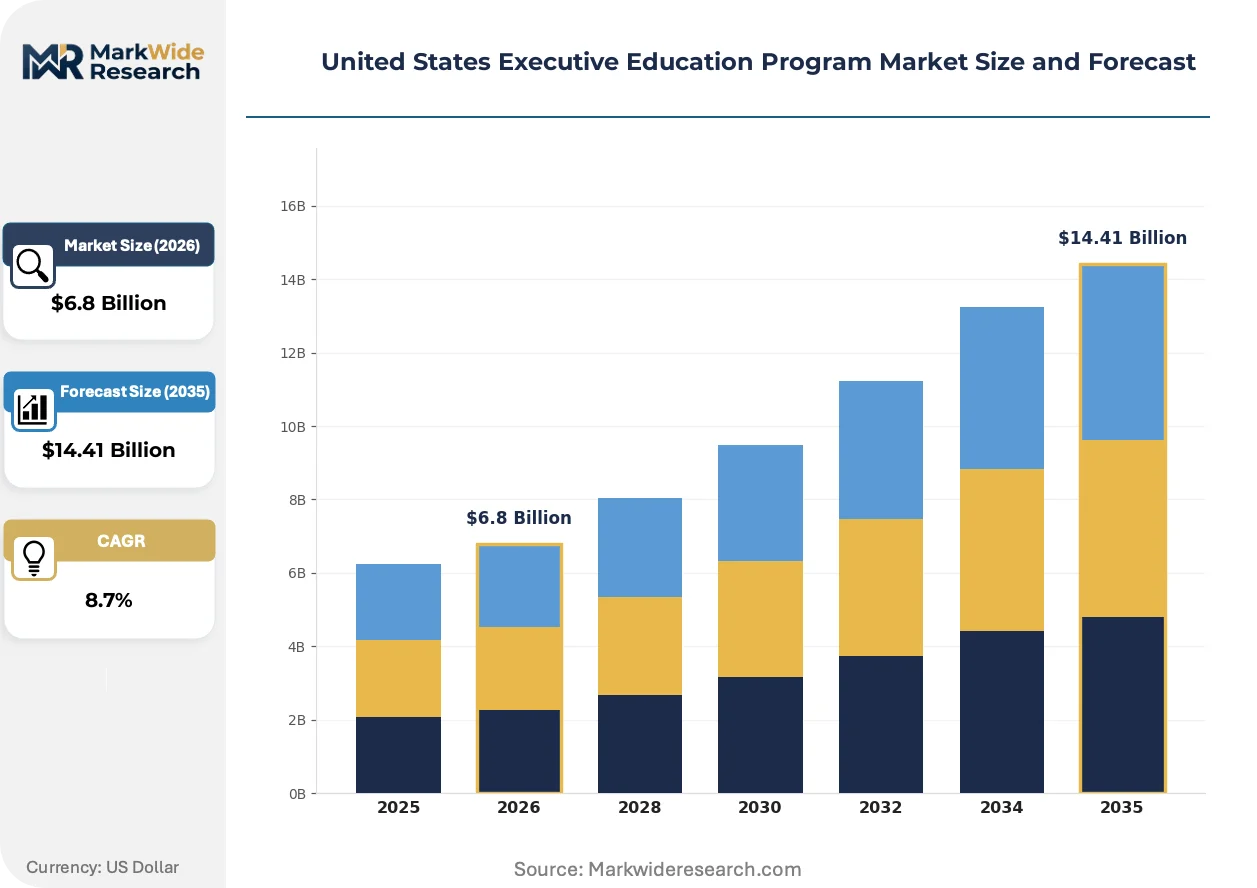
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Open Enrollment, Custom Programs, Online Programs, Certificate Programs Delivery Format: In-Person, Hybrid, Fully Online, Blended Learning Target Audience: C-Suite Executives, Middle Management, Senior Leaders, Aspiring Managers Subject Area: Leadership Development, Business Analytics, Strategic Management, Financial Acumen |
| Companies Covered | Stanford Graduate School of Business Executive Education, Duke Corporate Education, Michigan Ross Executive Education, Columbia Business School Executive Education, UCLA Anderson Executive Education, Wharton Executive Education, MIT Sloan School of Management, Center for Creative Leadership, Harvard Executive Education, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Executive Education Program Market Evolving Landscape
Delivery modality experimentation is fragmenting the traditional residency model as hybrid formats capture enterprise procurement preference. Three converging developments reshape competitive positioning.
Immersive simulation technology is bifurcating the case study methodology. Scenario-based learning platforms enable real-time strategic decision rehearsal. Fortune 500 learning and development directors now mandate experiential components for programs exceeding $50,000 per participant. This compression of theory-practice cycles is displacing passive lecture formats in open-enrollment portfolios.
The Department of Education's pending accreditation framework for short-term credential programs imposes new quality benchmarks on non-degree offerings. Institutions must demonstrate competency-based assessment protocols aligned with employer-validated skill taxonomies. Custom program providers in California and New York are accelerating curriculum redesigns to preempt compliance deadlines.
Enterprise buyers now unbundle program selection from centralized procurement, empowering business unit leaders to contract directly with providers. This disintermediation of corporate universities compresses sales cycles but intensifies price transparency. Technology sector buyers in Seattle and Austin increasingly pilot micro-credential subscriptions before committing to comprehensive leadership development engagements.
United States Executive Education Program Market Segmentation
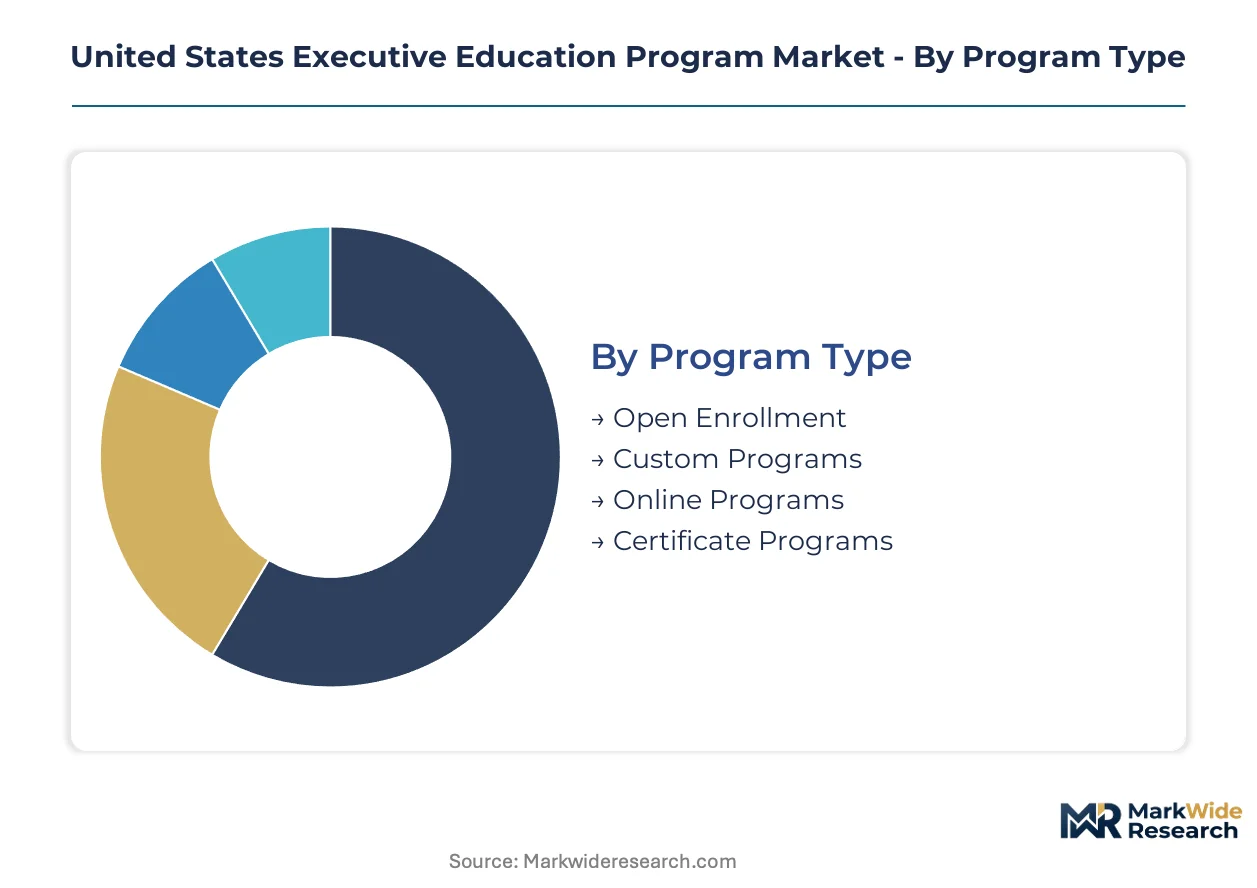
Enterprise procurement patterns diverge sharply across program architectures, with Fortune 500 learning and development directors applying distinct evaluation criteria to each segment. Geographic concentration of demand varies by delivery modality and customization depth.
Program Type:
Domestic corporate buyers dominate custom program procurement, while online formats attract distributed workforces across state lines. Export-led demand remains minimal given the non-degree nature of executive education.
- Open Enrollment:Standardized curricula delivered to mixed cohorts from multiple organizations. California technology firms and New York financial services buyers drive premium pricing in this segment. Fixed costs amortize across cohorts, preserving margin pools for established providers.
- Custom Programs:Tailored curricula aligned to specific organizational transformation objectives. Texas energy sector and Michigan automotive manufacturers commission the most complex multi-module engagements. Deep client relationships command sustained contract renewals.
- Online Programs:Scalable delivery reaching distributed workforces without residency requirements. Arizona and Colorado remote-work hubs generate disproportionate enrollment relative to population.
- Certificate Programs:Stackable credentials targeting specific competency verification. Healthcare systems in Massachusetts and Minnesota utilize these for compliance-driven leadership pipelines.
Custom programs command the established base. The steepest expansion runs through online programs.
Delivery Format:
Cost tier differentiation separates premium residency experiences from mass-market digital access, with hybrid formats capturing mid-budget procurement.
- In-Person:Intensive residencies at campus facilities requiring physical presence. Northeast corridor buyers maintain preference for this format despite travel costs.
- Hybrid:Synchronous online sessions punctuated by concentrated on-campus immersions. Illinois and Georgia enterprises favor this balance of flexibility and relationship-building.
- Fully Online:Asynchronous content with optional live facilitation. Pacific Northwest technology employers prioritize this format for engineering-to-management transitions.
- Blended Learning:Self-paced modules integrated with cohort-based project work. Virginia defense contractors and Maryland cybersecurity firms adopt this for classified-environment compatibility.
In-person delivery retains margin leadership. Hybrid formats are climbing the fastest as procurement budgets recalibrate.
Target Audience:
Volume concentrates in middle management development, though revenue per participant peaks at the C-suite tier.
- C-Suite Executives:Board-level governance and enterprise strategy modules. Fortune 100 headquarters in Delaware and Connecticut generate concentrated demand for this premium tier.
- Middle Management:Operational leadership and cross-functional coordination training. Ohio and Indiana manufacturing corridors require this segment at scale for automation transitions.
- Senior Leaders:Divisional P&L responsibility and change management preparation. Florida healthcare systems and Pennsylvania insurance carriers invest heavily here.
- Aspiring Managers:Early-career high-potential identification and foundational skills. Nevada and Utah emerging technology markets drive growth in this entry tier.
Middle management development commands the established base. The steepest expansion runs through aspiring manager segments.
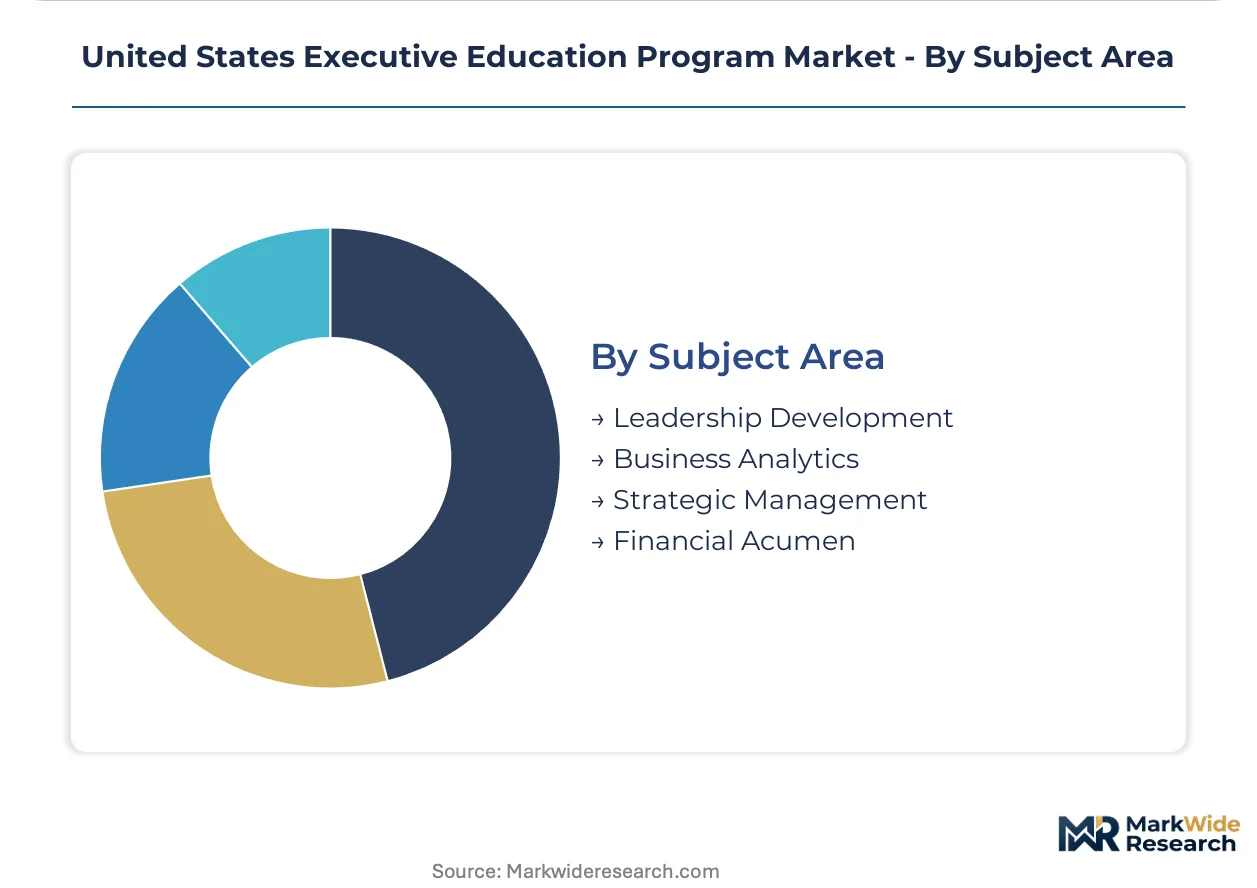
Subject Area:
Maturity varies across domains, with financial acumen offerings most established and business analytics experiencing technology-driven curriculum overhaul.
- Leadership Development:Communication, team dynamics, and organizational behavior competencies. Texas and North Carolina healthcare networks sustain demand for this foundational category.
- Business Analytics:Data interpretation, predictive modeling, and AI-augmented decision frameworks. Washington and Massachusetts technology employers mandate this for non-technical executives.
- Strategic Management:Competitive positioning, M&A evaluation, and portfolio optimization. New Jersey pharmaceutical headquarters and Missouri agricultural conglomerates prioritize this domain.
- Financial Acumen:Capital allocation, shareholder value analysis, and risk-adjusted returns. Connecticut hedge fund clusters and South Carolina automotive suppliers require this for general manager elevation.
Financial acumen commands the established base. The steepest expansion runs through business analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's technology corridor consumes executive education through modular, analytics-intensive formats, while the Northeast financial hub favors intensive residency-based leadership immersions. This bifurcation shapes provider curriculum design and delivery infrastructure investments across the country.
California
Silicon Valley technology firms and San Francisco venture capital clusters drive demand for AI-augmented decision-making curricula. The California Workforce Development Board channels WIOA Title I funds toward reskilling partnerships that expand mid-market enterprise access. Palo Alto and Mountain View anchor the highest concentration of custom program procurement for engineering-to-executive transitions.
New York Metro
Wall Street financial services and Midtown insurance headquarters sustain premium open-enrollment pricing for governance and risk management modules. New York State Department of Labor workforce development incentives support provider partnerships with regional economic development corporations. Manhattan and Stamford, Connecticut generate concentrated C-suite demand for board-level strategy intensives.
Texas
Houston energy sector and Dallas healthcare systems commission the most complex multi-module custom engagements for operational leadership transitions. The Texas Workforce Commission subsidizes executive reskilling through Skills Development Fund allocations that reduce employer cost burdens. Austin's emerging technology corridor is driving fastest growth in hybrid-format procurement for distributed engineering teams.
Illinois
Chicago financial exchanges and suburban manufacturing conglomerates balance cost discipline with leadership pipeline development needs. Illinois Department of Commerce and Economic Opportunity administers training tax credits that incentivize corporate education investments. The I-88 technology corridor sustains steady demand for data analytics and supply chain management certificate programs.
Massachusetts
Greater Boston biotechnology and Cambridge artificial intelligence clusters require specialized programs bridging technical expertise with commercial leadership competencies. Massachusetts Executive Office of Labor and Workforce Development coordinates sector partnerships that align provider curricula with industry-validated competency frameworks. Route 128 technology employers increasingly pilot micro-credential subscriptions before comprehensive leadership development commitments.
United States Executive Education Program Market Competitive Landscape
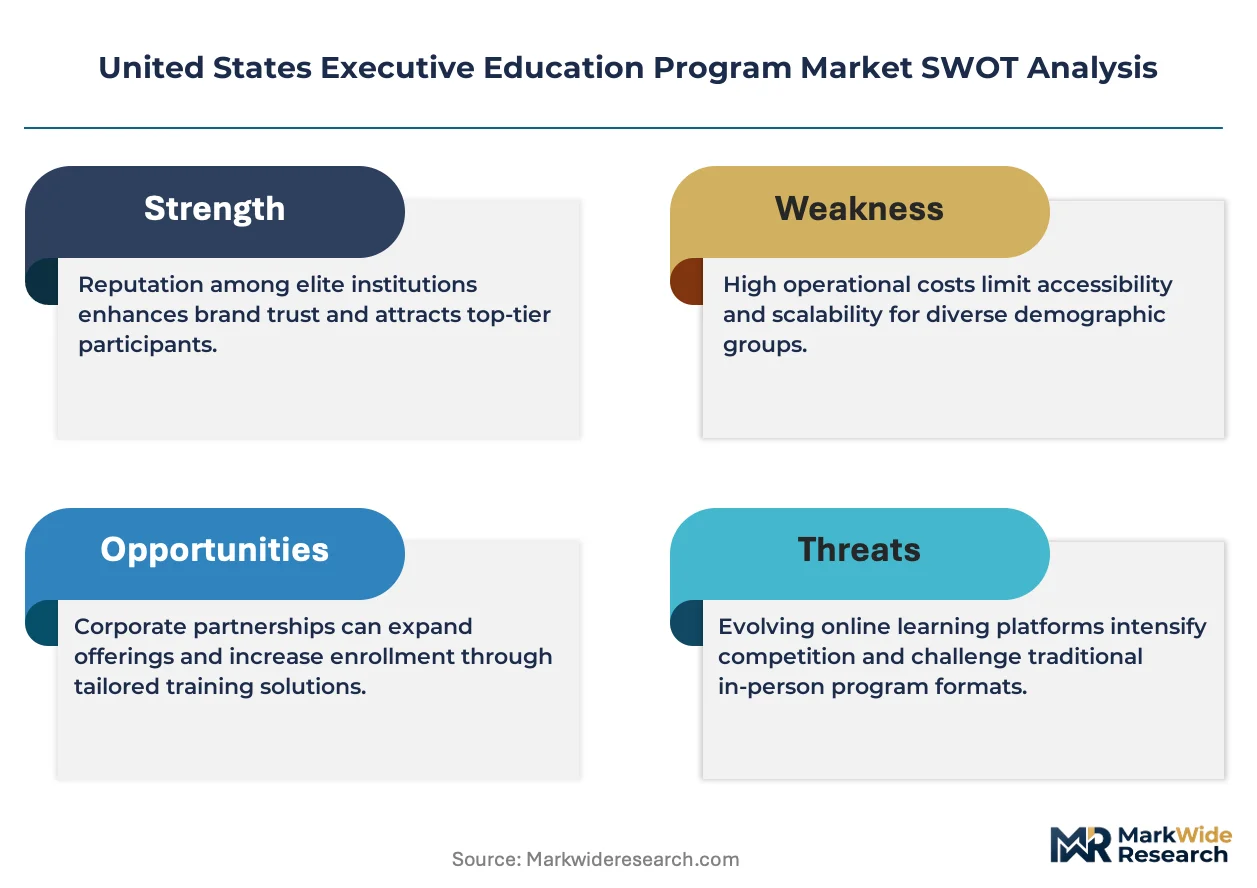
A small set of integrated leaders sits above a broader specialist tier, with business school-affiliated providers commanding premium positioning through brand authority and alumni network density. The market structure concentrates among Ivy League and elite private university extensions, while independent leadership institutes occupy mid-market segments. Two strategic archetypes dominate: research-intensive academic institutions leveraging faculty scholarship for curriculum differentiation, and practice-focused consultancies emphasizing applied organizational transformation. Competitive moves center on custom program capacity expansion and AI-augmented delivery platform development.
Within the academic elite tier, Harvard Executive Education and Stanford Graduate School of Business Executive Education exemplify research-intensive positioning through endowed faculty and global campus networks. Wharton Executive Education anchors the finance-specialist archetype with Philadelphia-based programming. MIT Sloan School of Management represents the technology-analytics convergence that attracts West Coast enterprise buyers. Duke Corporate Education and the Center for Creative Leadership occupy the independent practitioner tier, emphasizing organizational consulting integration over degree-granting institutional heritage.
| Leading Market Players |
|---|
| Stanford Graduate School of Business Executive Education |
| Duke Corporate Education |
| Michigan Ross Executive Education |
| Columbia Business School Executive Education |
| UCLA Anderson Executive Education |
| Wharton Executive Education |
| MIT Sloan School of Management |
| Center for Creative Leadership |
| Harvard Executive Education |
| Others |
Value Network & Pricing Analysis
Fixed-cost amortization across multiple cohorts anchors price floors for established providers, concentrating margin power among Ivy League-affiliated institutions with endowed faculty and global campus networks. This scale dynamic simultaneously compresses entry-level pricing for digital-native competitors while elevating premium tiers for custom engagements with Fortune 500 learning and development directors.
Pricing Analysis
Contract-based multi-year enterprise agreements dominate procurement for custom programs, while open-enrollment formats rely on per-seat transactional pricing with volume discounts. Price differentiation rests on faculty pedigree and alumni network density rather than delivery modality alone. Cost compression in fully online tiers is intensifying because AI-augmented content engines reduce instructional design labor. Mid-market enterprises in Texas and Ohio exhibit highest price sensitivity, whereas C-suite buyers in Connecticut and Delaware prioritize outcome verification over unit cost.
Supply Chain Analysis
Curriculum development lead times stretch 18-24 months for accredited custom programs, constraining provider responsiveness to emergent skill demands. Instructional design talent clusters in California, Massachusetts, and New York, creating geographic bottlenecks for new program launches. Content production draws from practitioner-scholar networks, learning experience design specialists, and immersive simulation technology vendors. Single-source vulnerability concentrates in faculty supply for specialized domains such as AI governance and biotechnology commercialization. Distribution runs through direct enterprise sales teams, alumni referral networks, and state workforce development board partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Executive education functions as a high-margin service-attach layer where recurring custom program renewals and alumni network subscriptions expand faster than one-time open-enrollment transactions. This recurring-revenue architecture rewards providers who embed measurement systems demonstrating competency gains to corporate learning and development directors.
For Market Incumbents: Fortify custom program capacity through dedicated client success teams and proprietary assessment platforms that quantify leadership competency development. Deepen vertical integration into immersive simulation technology to differentiate from AI-commoditized content providers. Accreditation compliance costs from the Department of Education's pending short-term credential framework threaten smaller competitors, creating consolidation opportunities for well-capitalized institutions. For New Entrants and Emerging Players: AI-human facilitation hybrids represent the most penetrable white-space where incumbents under-serve mid-market enterprises with budgets between mass-market digital and premium custom tiers. Target Ohio and Michigan manufacturing corridors with operations leadership curricula outside traditional financial services domains. Pursue state workforce development board partnerships in Texas and Illinois to access subsidized demand before scaling direct sales infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among custom program providers with multi-year enterprise relationships and proprietary competency assessment IP. Long-term viability favors institutions with endowed faculty positions and established accreditation standing that insulates against regulatory disruption. Monitor Department of Labor WIOA funding allocation shifts as an inflection indicator for public subsidy availability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Delivery Platform | Adaptive learning engines from MIT Sloan and Stanford enable scalable personalization previously restricted to high-touch custom engagements. |
| Competency Assessment Certification | Department of Education alignment with employer-validated skill taxonomies from Texas Workforce Commission preempts compliance deadlines. |
| Immersive Simulation Technology | Scenario-based platforms displace passive lecture formats as Fortune 500 L&D directors mandate experiential components above $50,000 per participant. |
| State Workforce Partnership | WIOA Title I fund access through California and New York workforce development boards expands addressable mid-market demand. |
| Alumni Network Monetization | Harvard and Wharton leverage dense executive alumni clusters for referral-driven custom program procurement and subscription micro-credentials. |
Research Methodology
Desk research of corporate learning and development budget disclosures, Department of Education accreditation filings, and state workforce development board program directories preceded structured interviews with Fortune 500 L&D directors, business school executive education deans, and HR technology procurement officers. Primary fieldwork combined with secondary validation against SEC filings from publicly traded education providers, trade association membership data, and federal WIOA expenditure reports. Bottom-up enrollment estimates by program type and delivery format triangulated against top-down corporate training spend allocations.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension. The analytical framework models program type, delivery format, target audience tier, and subject area maturity as distinct growth vectors. CAGRs derive from historical enrollment trajectories adjusted for AI tooling adoption curves and workforce development subsidy availability. Forecast inputs include corporate reskilling mandate intensity, distributed workforce normalization rates, and accreditation compliance timeline uncertainty.
Forecasts assume regulatory continuity in Department of Education short-term credential frameworks and Section 127 employer tuition assistance tax treatment; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
Technical and Vocational Education Market
Professional Development and Training
Executive Education Program Market
Professional Development and Training
Global Virtual Training and Simulation Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
Personal Development Market
Professional Development and Training
Canada Executive Education Program Market
Professional Development and Training
HSE Consulting Training Services Market
Professional Development and Training
Equipment Maintenance Training Services Market
Professional Development and Training
Global Mechatronics and Robotics Courses Market
Professional Development and Training
HR Professional Services Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
Cognitive Assessment and Training Market
Professional Development and Training
Coding Bootcamp Market
Professional Development and Training
Business Coaching Service Market