
 Technical and Vocational Education Market | 2026-2036
Technical and Vocational Education Market Size, Share, and Industry Trends Forecast 2026-2036
Technical and Vocational Education Market Intelligence
Competency-based subscription credentialing is repositioning how employers evaluate workforce readiness. Pearson leverages its BTEC qualification framework to anchor vocational pathways across British Commonwealth education systems. Udacity Inc. specializes in nanodegree stacks for cloud computing and data engineering, competing directly with university extension programs. Amazon Web Services Inc. extends its market presence through cloud practitioner certifications that feed directly into enterprise hiring pipelines.
Technical and vocational education comprises structured post-secondary training programs delivering occupational competencies through standardized curricula, typically ranging from six-week intensive workshops to four-year apprenticeship contracts combining classroom instruction with supervised workplace practice. These programs certify proficiency in applied skills ranging from CNC machining to medical coding, serving industries where regulatory licensure or employer-validated competence determines labor market access. Certification courses and apprenticeships represent the deepest margin pools, with the former scaling rapidly through digital delivery and the latter retaining institutional barriers that limit supplier entry. Blended learning formats are gaining share fastest among working professionals, while in-person delivery still dominates construction and healthcare applications where tactile skill verification remains mandatory.
The US Department of Education's Gainful Employment rules and the EU's European Qualifications Framework jointly shape program eligibility for federal student aid and cross-border credential recognition. India's National Council for Vocational Training, operating under the Ministry of Skill Development and Entrepreneurship, mandates curriculum standards and assessment protocols for all affiliated training providers. Stakeholders must monitor how AI-driven skills assessment tools alter the balance between standardized testing and employer-customized evaluation criteria.
Market Dynamics
Competency-based credentialing is fragmenting employer trust away from traditional degree pathways, forcing training providers to align curricula with real-time labor market signals rather than static academic calendars.
Growth Catalysts
- EU Skills Agenda:The European Commission's Pact for Skills mandates sectoral partnerships that channel corporate training budgets into certified reskilling programs across manufacturing and green energy trades.
- Healthcare workforce turnover:Accelerated retirement among nursing staff in the United States and Germany is expanding enrollment in accelerated medical assistant and phlebotomy certification tracks.
- Cloud infrastructure expansion:Enterprise migration to distributed systems is creating sustained demand for vendor-specific certifications in Kubernetes administration and cybersecurity operations.
Market Restraints
- Apprenticeship slot scarcity:German Mittelstand manufacturers and Australian construction consortiums control limited training positions, creating queuing bottlenecks that delay program completion.
- Assessment technology costs:Proctoring software and virtual reality simulation hardware impose per-student fees that erode margins in price-sensitive emerging markets.
- Regulatory fragmentation:India's National Council for Vocational Training and Australia's Australian Skills Quality Authority maintain non-mutually-recognized standards, complicating cross-border credential portability.
Strategic Opportunities
- Brazilian Sistema S expansion:Federal payroll tax allocations to SENAI and SENAC are funding new technical centers in Northeast industrial corridors underserved by post-secondary infrastructure.
- Green skills mandates:The EU Green Deal's Renovation Wave directive requires certified heat pump installers and energy auditors, opening curriculum gaps that training providers can fill.
- AI-assisted tutoring convergence:Adaptive learning algorithms layered onto mobile delivery platforms are enabling personalized competency pacing at scale previously restricted to elite coaching.
Industry Challenges
- Instructor credential lag:Trade professionals with current industry expertise rarely hold teaching certifications, forcing programs to choose between pedagogical compliance and practical relevance.
- Work-based learning placement:Coordinating supervised practice hours across dispersed employer sites consumes administrative overhead that digital-native competitors struggle to replicate.
- Equipment refresh cycles:CNC machining and medical device simulation labs require capital reinvestment every four to six years to maintain alignment with workplace technology standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical and Vocational Education Market |
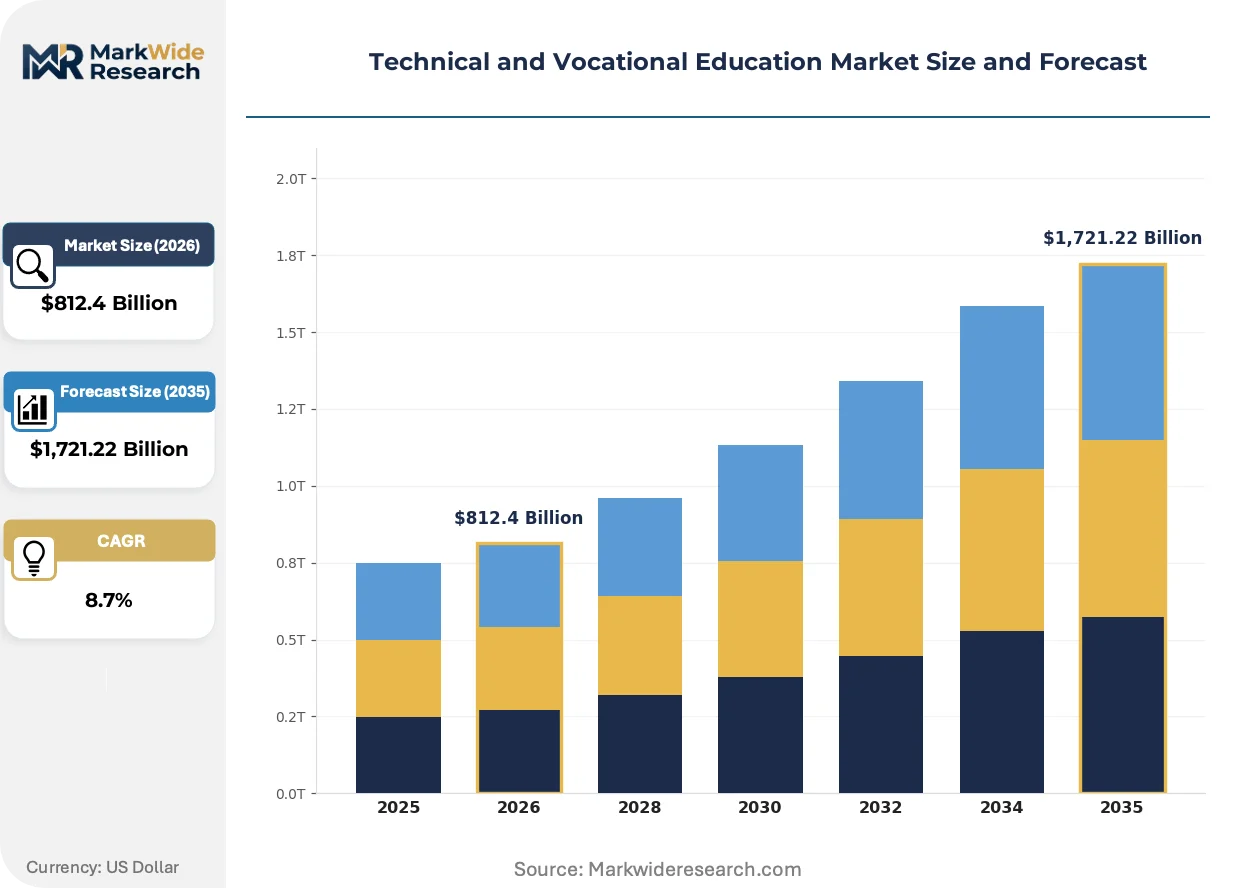
| Market Size in 2026 | $812.4 Billion |
| Market Size in 2035 | $1,721.22 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Trade Programs, Certification Courses, Apprenticeships, Skill Development Workshops Delivery Mode: In-Person, Online, Blended Learning, Hands-On Training Industry Application: Construction, Hospitality, Information Technology, Healthcare Target Audience: High School Graduates, Working Professionals, Unemployed Individuals, Career Switchers |
| Companies Covered | Pearson, Coursera Inc., Udacity Inc., Kaplan Inc., Adobe Inc., City and Guilds of London Institute, CEGOS, Articulate Global LLC, Amazon Web Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical and Vocational Education Market Strategic Shifts & Innovations
Digital credentialing infrastructure is dissolving the boundary between training completion and job placement, embedding assessment directly into hiring workflows rather than treating certification as a separate screening stage.
Extended reality simulation is modularizing tactile skill verification for hazardous trades. Oil rig operators and surgical technicians now complete immersive emergency response drills through mixed-reality headsets before entering physical training environments. German chemical manufacturers and Texan petrochemical clusters have adopted these systems to reduce insurance liability exposure during early-stage instruction.
The EU's AI Act imposes transparency requirements on automated hiring tools that evaluate vocational credentials. French and Dutch regulators are requiring algorithmic impact assessments for platforms that match certified workers to gig assignments. Training providers serving European markets must now document how their assessment data feeds into these decision systems.
Employer-sponsored tuition is displacing individual borrower financing as the dominant payment mechanism. Large logistics and healthcare systems in the United States are contracting directly with community colleges to deliver cohort-based upskilling during off-shift hours. This procurement consolidation reduces student acquisition costs for approved providers while locking out competitors lacking enterprise sales capabilities.
Technical and Vocational Education Market Segmentation
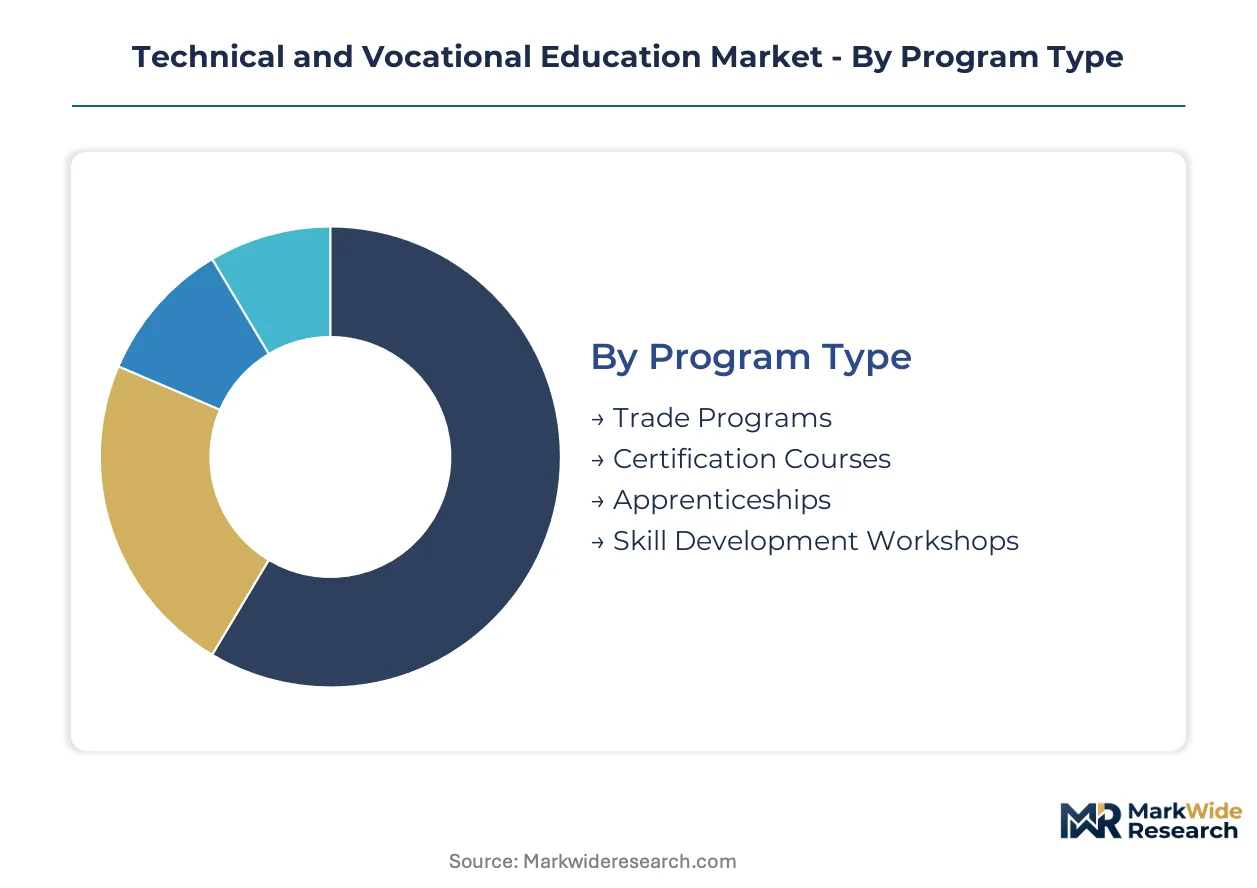
Program architecture determines funding eligibility and employer recognition in technical and vocational education. Certification requirements vary sharply across delivery modes and industry applications, shaping provider investment priorities and student enrollment patterns.
Program Type:
Certification burden clusters heaviest on apprenticeships and healthcare trade programs, where federal student aid eligibility and professional licensure boards mandate standardized assessment protocols.
- Certification Courses:Modular curricula stack toward industry-recognized credentials through proctored examinations. Healthcare workforce turnover in the United States and Germany drives accelerated enrollment in medical assistant and phlebotomy tracks.
- Apprenticeships:Dual-structure contracts combine classroom hours with supervised workplace practice under the German Vocational Training Act and EU apprenticeship directives. German Mittelstand manufacturers and Australian construction consortiums control limited training slots, creating queuing bottlenecks.
- Trade Programs:Comprehensive occupational preparation spanning six months to two years.
- Skill Development Workshops:Intensive short-cycle training, typically six weeks or less.
Leading the category by volume: Certification Courses. Growing fastest: Apprenticeships.
Delivery Mode:
Cost tier separation runs deepest between capital-intensive hands-on training and scalable online delivery, with blended formats capturing premium pricing from employer-sponsored tuition programs.
- Blended Learning:Hybrid formats combine asynchronous digital modules with scheduled in-person skill verification. Working professionals in logistics and healthcare systems favor this mode for off-shift upskilling cohorts.
- Hands-On Training:Tactile skill verification in physical labs using CNC machining and medical device simulation equipment. Construction and healthcare applications mandate this delivery where regulatory bodies require direct observation of competency.
- In-Person:Traditional classroom-based instruction without digital components.
- Online:Fully digital delivery through learning management platforms.
Dominant by enrollment volume: Blended Learning. Steepest expansion trajectory: Hands-On Training.
Industry Application:
Application-specific margin profiles reflect equipment refresh cycles and instructor credential requirements, with healthcare and IT commanding premium pricing against construction's volume-driven economics.
- Healthcare:Certification tracks for nursing assistants, medical coders, and surgical technicians align with state licensure boards and HIPAA training mandates. Accelerated retirement among nursing staff expands demand for phlebotomy and medical assistant credentials.
- Information Technology:Vendor-specific certifications in cloud computing and cybersecurity feed directly into enterprise hiring pipelines. Amazon Web Services and Kubernetes administration credentials dominate procurement conversations.
- Construction:Trade preparation for carpentry, electrical, and HVAC installation.
- Hospitality:Culinary and service management certification programs.
Highest revenue concentration: Healthcare. Gaining share fastest: Information Technology.
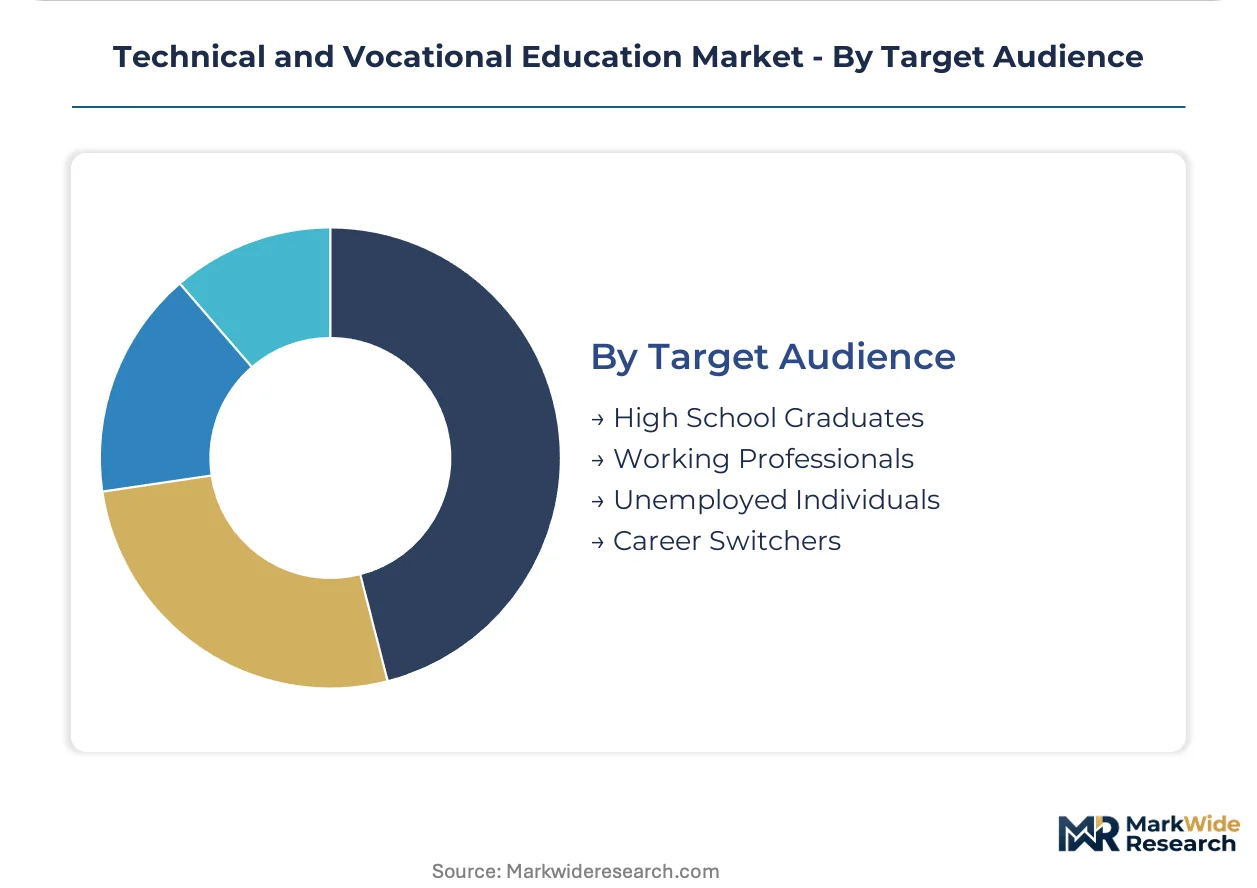
Target Audience:
Customer type determines payment mechanism, with employer-sponsored tuition displacing individual borrower financing among working professionals while unemployed individuals rely on federal workforce development allocations.
- Working Professionals:Upskilling during employment through employer-contracted community college programs. Large logistics and healthcare systems in the United States procure cohort-based delivery during off-shift hours.
- Career Switchers:Mid-career transitions into regulated trades requiring complete credential stacks. India's Skill India Mission channels federal funding specifically toward this demographic in construction and IT trade programs.
- High School Graduates:Entry-level occupational preparation immediately post-secondary.
- Unemployed Individuals:Workforce re-entry through publicly funded training slots.
Largest addressable population: Working Professionals. Fastest enrollment growth: Career Switchers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors European vocational training policy development, with the German capital's dual-system standards radiating outward through EU apprenticeship directives and bilateral technical assistance programs.
United States
Accelerated nursing retirements and healthcare system consolidation are expanding demand for medical assistant and phlebotomy certification tracks. The Department of Education's Gainful Employment rules shape federal student aid eligibility for for-profit training providers. Houston's petrochemical corridor and Atlanta's logistics hub are deploying employer-contracted community college programs for off-shift upskilling cohorts.
Germany
Mittelstand manufacturers face acute apprenticeship slot scarcity as demographic contraction reduces trainee pipelines. The Vocational Training Act codifies dual-structure contracts combining classroom hours with supervised workplace practice. Bavaria's automotive clusters and North Rhine-Westphalia's chemical industry are adopting extended reality simulation systems to reduce insurance liability during early-stage instruction.
India
Federal funding through the Skill India Mission concentrates demand in construction and IT trade programs for mid-career switchers. The National Council for Vocational Training mandates curriculum standards and assessment protocols for all affiliated providers. Karnataka's Bangalore tech corridor and Gujarat's industrial estates are channeling payroll-linked training investments into certified reskilling infrastructure.
Brazil
Federal payroll tax allocations to SENAI and SENAC are funding new technical centers in Northeast industrial corridors underserved by post-secondary infrastructure. The country's national workforce development regulator coordinates sectoral partnerships between training providers and regional employer associations. São Paulo's manufacturing belt and Pernambuco's emerging logistics corridor are capturing the bulk of Sistema S expansion capital.
Australia
Construction consortiums control limited apprenticeship positions, creating queuing bottlenecks that delay program completion for trades candidates. The Australian Skills Quality Authority maintains assessment standards that lack mutual recognition with Indian and European counterparts. Western Australia's mining regions and New South Wales' infrastructure projects are prioritizing blended learning formats for remote workforce certification.
Technical and Vocational Education Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the technical and vocational education market, with physical campus networks and simulation labs requiring sustained reinvestment against digital-native platforms scaling through subscription credentialing. The vendor base separates into three tiers: legacy qualification bodies with embedded regulatory relationships, technology platforms delivering modular nanodegree stacks, and cloud infrastructure vendors extending certification ecosystems into enterprise hiring pipelines. Dominant competitive moves include curriculum alignment with real-time labor market signals and direct contracting with large logistics and healthcare systems for employer-sponsored tuition programs.
Within the qualification body tier, Pearson and City and Guilds of London Institute occupy positions anchored to British Commonwealth education systems and federal recognition frameworks. Udacity Inc. exemplifies the technology platform archetype through its specialization in intensive nanodegree programming. Amazon Web Services Inc. represents cloud infrastructure vendor expansion, feeding vendor-specific certifications directly into enterprise procurement conversations for distributed systems talent.
| Leading Market Players |
|---|
| Pearson |
| Coursera Inc. |
| Udacity Inc. |
| Kaplan Inc. |
| Adobe Inc. |
| City and Guilds of London Institute |
| CEGOS |
| Articulate Global LLC |
| Amazon Web Services Inc. |
| Others |
Cost & Logistics Intelligence
Sovereign-backed training networks in Germany, Brazil, and India anchor supply capacity through federal payroll tax allocations and ministry-directed funding streams, compressing price competition in employer-contracted segments while fragmenting pricing power across digital-native platforms competing for individual enrollment.
Pricing Analysis
Outcome-linked tuition models dominate employer-sponsored segments, where healthcare systems and logistics operators contract directly with community colleges for cohort-based credentialing. Price differentiation hinges on certification tier—vendor-specific cloud credentials command premiums over generic trade preparation—and delivery mode, with blended formats capturing higher fees than fully online alternatives. Cost compression in price-sensitive emerging markets stems from per-student proctoring and simulation hardware expenses. Individual borrowers exhibit highest price sensitivity, while enterprise procurement teams prioritize placement rates over per-seat cost.
Supply Chain Analysis
Qualification gating through national councils in India, Germany, and Australia concentrates accredited supply within federally supervised provider networks, restricting unaffiliated platform expansion. Curriculum development draws from industry competency frameworks, assessment protocol licensing, and simulation equipment manufacturing concentrated in the United States, Germany, and South Korea. Single-source vulnerability runs through proprietary certification ecosystems controlled by cloud infrastructure vendors. Distribution runs through ministry-affiliated training centers, employer-contracted community colleges, and direct-to-learner digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended reality simulation and AI-assisted tutoring are displacing legacy instructor-dependent models, compressing the window for incumbents to capture technology-transition premiums before standardization erodes differentiation.
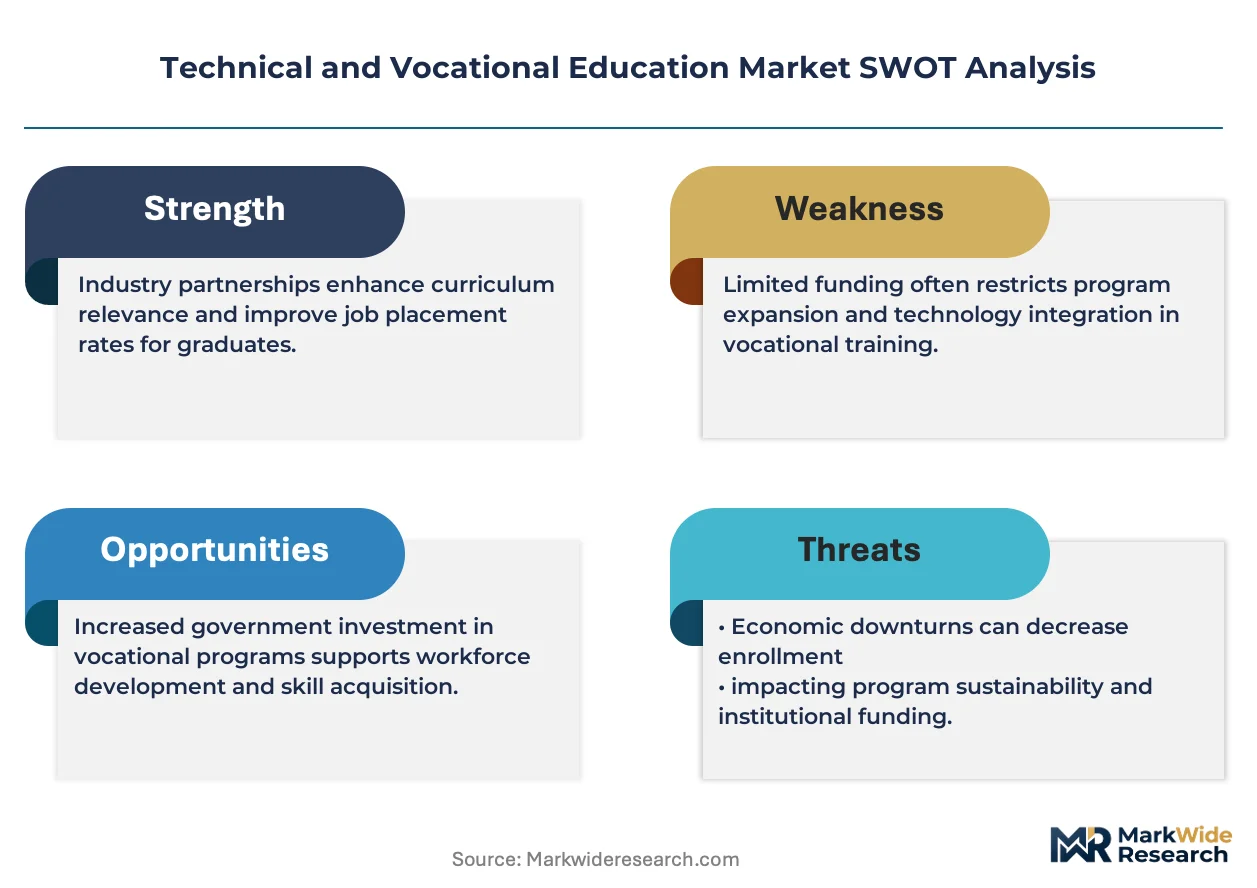
For Market Incumbents: Lock in enterprise procurement relationships through direct contracting with healthcare systems and logistics operators for off-shift cohort delivery, while securing backward integration into simulation equipment supply to defend margins against digital-native competitors. Certification investment in vendor-specific cloud and green energy credentials represents the critical defensive lever against platform-based disintermediation. For New Entrants and Emerging Players: Launch via mobile-first adaptive learning platforms targeting career switchers in India's Skill India Mission corridors and Brazil's Northeast industrial expansion zones, where federal funding reduces customer acquisition costs. White-space concentration sits with AI-assisted personalized competency pacing at scale, an application underserved by legacy qualification bodies lacking algorithmic capability. For Investors and Strategic Acquirers: Employer-sponsored tuition displacement of individual borrower financing is the leading indicator that procurement consolidation will favor providers with enterprise sales infrastructure over digital-native platforms dependent on consumer marketing spend. Acquisition targets should exhibit embedded regulatory relationships with national qualification councils and demonstrated placement rates into enterprise hiring pipelines. A model refresh is warranted upon material change in federal workforce development allocation levels.| Strategic Initiative | Industry Significance |
|---|---|
| Extended Reality Simulation Deployment | German chemical manufacturers and Texan petrochemical clusters reduce insurance liability through immersive emergency response training. |
| Enterprise Tuition Contracting | Direct procurement by Houston logistics hubs and Atlanta healthcare systems locks out competitors lacking B2B sales capability. |
| Green Skills Curriculum Development | EU Green Deal Renovation Wave mandates create certified heat pump installer gaps that training providers can fill. |
| AI-Assisted Tutoring Integration | Adaptive algorithms on mobile platforms enable personalized competency pacing previously restricted to elite coaching. |
| Cross-Border Credential Mutual Recognition | Alignment with EU European Qualifications Framework expands addressable market for providers seeking portability. |
Research Approach
Multi-period observation of enrollment patterns, federal funding allocations, and employer hiring pipeline flows anchored the trend analysis, supplemented by interviews with vocational training directors, ministry skill development officers, enterprise learning and development executives, and simulation equipment procurement managers. Secondary validation drew from EU Skills Agenda implementation reports, US Department of Education Gainful Employment disclosures, India's National Council for Vocational Training curriculum standards, and Brazilian Sistema S payroll tax distribution records. Bottom-up provider capacity modeling and top-down federal budget allocation analysis were triangulated to establish market sizing.
Input-output matrices mapped program type, delivery mode, industry application, and target audience segments across the projection horizon, with CAGRs derived from enrollment elasticity to workforce turnover rates and federal funding trajectories. Forecast inputs included healthcare workforce retirement velocity, cloud infrastructure vendor certification issuance volumes, and green energy trade mandate implementation schedules.
Regulatory framework shifts, technology platform disruption, and sovereign funding reallocation are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in EU apprenticeship directive harmonization progress or federal workforce development appropriation levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
Leadership Development Program Market
Professional Development and Training
Business Coaching Service Market
Professional Development and Training
Canada Executive Education Program Market
Professional Development and Training
Global Mechatronics and Robotics Courses Market
Professional Development and Training
Human Resource Professional Services Market
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
Personal Development Market
Professional Development and Training
Global Virtual Training and Simulation Market
Professional Development and Training
RPA Platform Training Market
Professional Development and Training
HSE Consulting Training Services Market
Professional Development and Training
Coding Bootcamp Market
Professional Development and Training
HR Professional Services Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
US Life Coaching Market