
 Equipment Maintenance Training Services Market | 2026-2036
Equipment Maintenance Training Services Market Size, Share, and Industry Trends Forecast 2026-2036
Equipment Maintenance Training Services Market Insights
Digital twin integration with live equipment telemetry is narrowing the skills gap between classroom instruction and field diagnostics. Siemens AG leverages its industrial software ecosystem to embed training modules directly within asset management platforms. Honeywell International Inc. sustains competitive positioning through proprietary simulation environments tied to process control systems. ABB Ltd. anchors its offerings in robotics-specific maintenance curricula aligned with automotive and electronics manufacturing clusters.
Equipment maintenance training services encompass structured educational programs designed to develop technical competency in diagnosing, repairing, and optimizing industrial machinery, typically incorporating hands-on modules with actual hardware, virtual reality simulations, and competency assessments against manufacturer specifications. These services reduce unplanned downtime by ensuring technicians can interpret vibration analysis, thermal imaging, and lubrication diagnostics against OEM thresholds. Virtual training within the service type dimension is expanding fastest as utilities and aviation operators seek scalable delivery without production line disruption. Instructor-led delivery still dominates high-stakes certification programs where tactile familiarity with high-voltage or pressurized systems remains non-negotiable. The manufacturing vertical absorbs the largest share of training expenditure due to continuous retooling demands driven by automation upgrades.
OSHA lockout/tagout standards and ISO 14224 reliability data collection protocols shape curriculum design across North American and European training providers, with compliance audits directly linking certification validity to insurance premium calculations. The EU Machinery Directive and CE marking requirements extend this regulatory pressure into European supplier ecosystems, forcing cross-border standardization of assessment criteria. Stakeholders must monitor how AI-generated maintenance recommendations will redefine the boundary between technician judgment and automated decision-support, reshaping competency frameworks before regulatory bodies codify new requirements.
Market Dynamics
Predictive maintenance platforms are compressing technician certification cycles as vibration analysis and thermal imaging diagnostics displace reactive repair protocols across heavy manufacturing operations.
Growth Catalysts
- OSHA Machinery Safety Mandates:Tightening compliance windows for lockout/tagout procedures force industrial facilities to accelerate technician recertification programs.
- Digital Twin Integration:Live equipment telemetry narrows the skills gap between classroom instruction and field diagnostics, enabling real-time competency validation.
- Germany's Heavy Manufacturing Expansion:Automotive and electronics clusters drive robotics-specific maintenance curriculum demand as automation upgrades accelerate.
Market Restraints
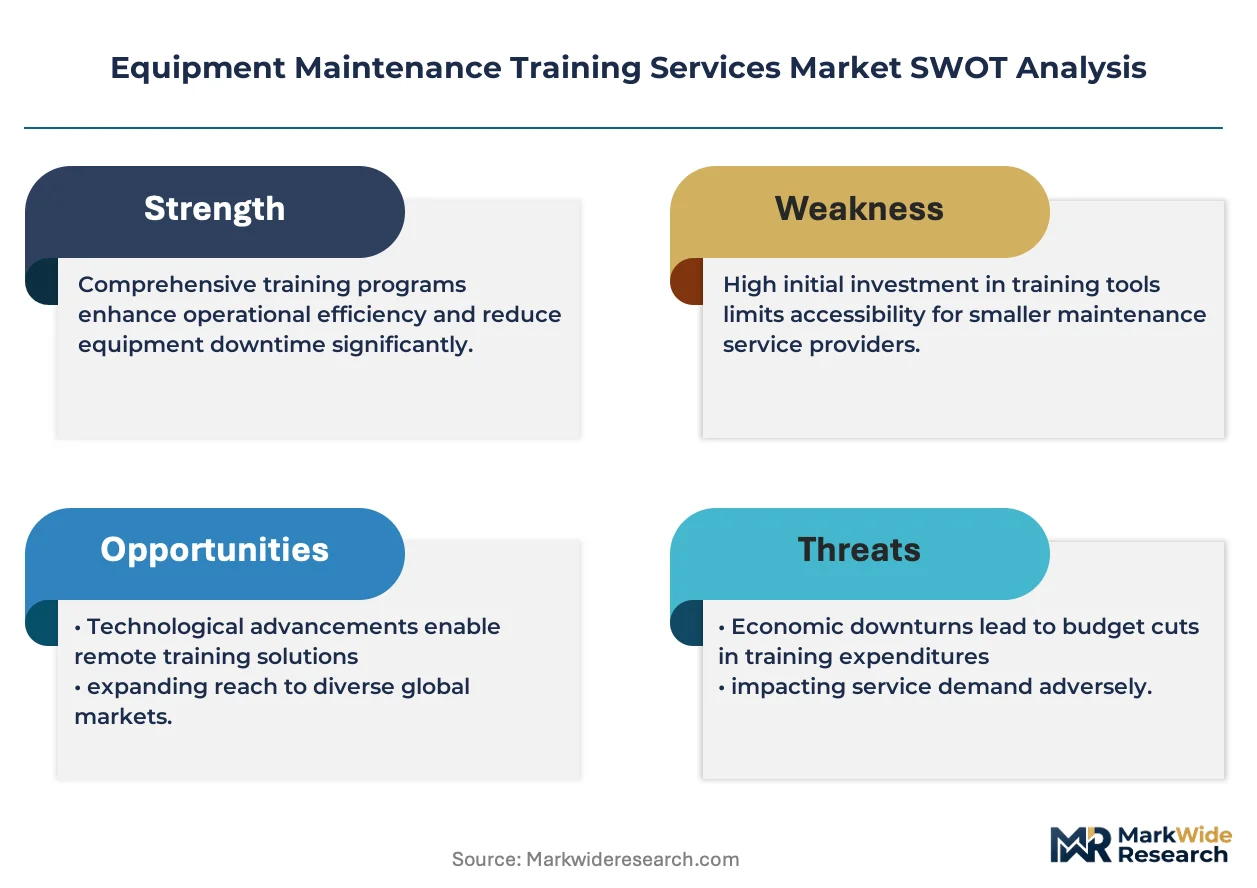
- High-Fidelity Simulator Costs:Proprietary virtual reality hardware and software licensing create capital barriers for mid-sized training providers.
- ISO 14224 Compliance Friction:Reliability data collection protocols impose documentation burdens that extend curriculum development timelines.
- Instructor-Led Delivery Dependency:Tactile certification requirements for high-voltage and pressurized systems limit scalability of purely digital training models.
Strategic Opportunities
- Utilities Distributed Generation Assets:Virtual training modules gain traction among operators managing geographically dispersed renewable infrastructure without production line disruption.
- EU Machinery Directive Harmonization:Cross-border standardization of assessment criteria creates addressable market expansion for certification providers.
- Aviation Maintenance Convergence:Augmented reality overlays combined with AI-generated maintenance recommendations reshape competency frameworks for airframe technicians.
Industry Challenges
- AI-Assisted Diagnostic Judgment:Technicians struggle to calibrate decision-making authority when automated systems generate conflicting maintenance recommendations.
- Multi-Vendor Platform Integration:Training providers face complexity harmonizing curricula across competing asset management software ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equipment Maintenance Training Services Market |
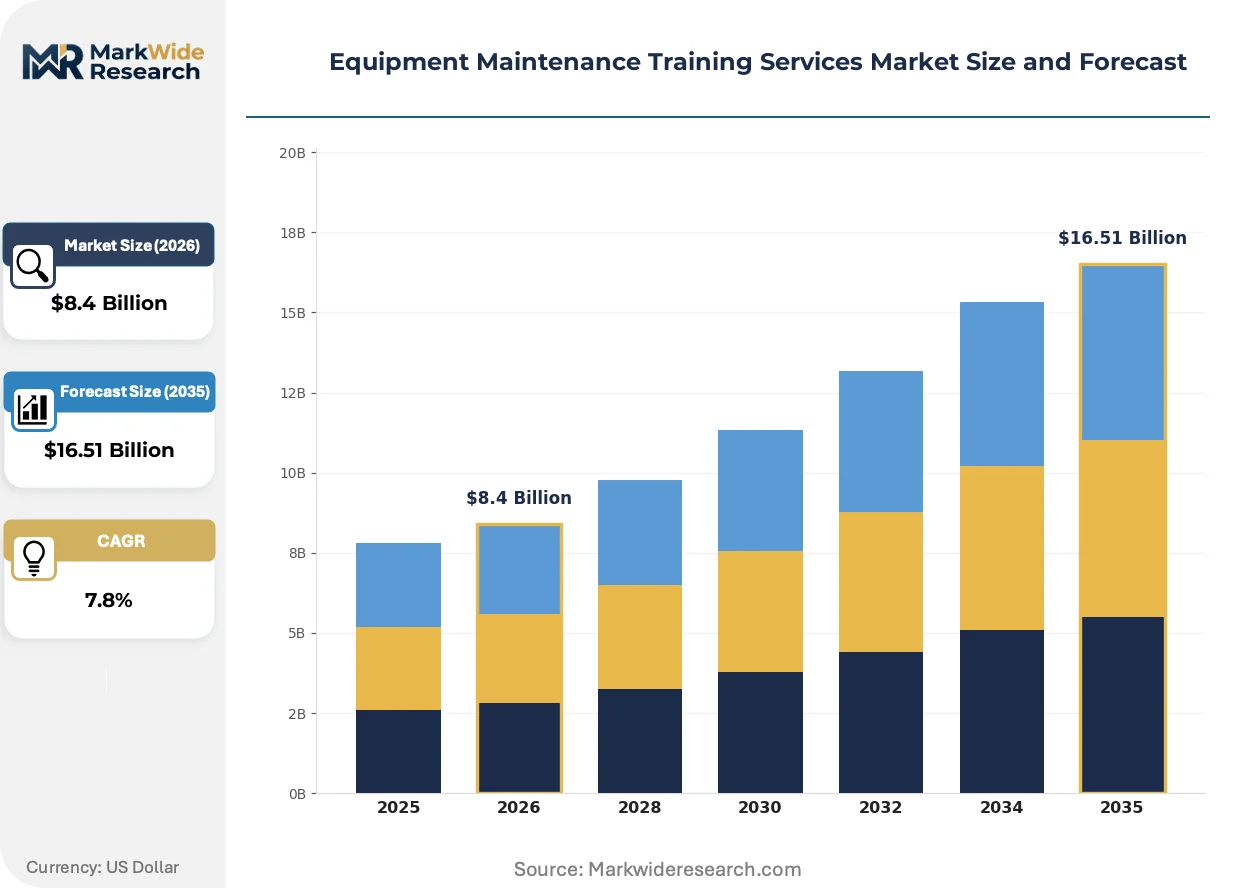
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-site Training, Virtual Training, Workshops, Certification Programs Industry Vertical: Manufacturing, Construction, Aviation, Utilities Delivery Mode: Instructor-led, Self-paced, Blended Learning, E-learning Audience Type: Technicians, Supervisors, Engineers, Management |
| Companies Covered | Siemens AG, Honeywell International Inc., ABB Ltd., Emerson Electric Co., Rockwell Automation Inc., Schneider Electric SE, Johnson Controls International plc, Baker Hughes Company, TechnipFMC plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equipment Maintenance Training Services Market Trends and Innovations
Training delivery modalities are fragmenting as immersive technologies compress the pathway from competency acquisition to field deployment.
Extended reality headsets paired with haptic feedback gloves are rendering obsolete traditional classroom-based equipment familiarization for high-risk industrial scenarios. Aviation MRO operators and nuclear facility technicians adopt these systems at accelerating pace as insurance underwriters recognize simulator-validated competency. The technology is rendering obsolete the historical trade-off between training safety and tactile authenticity.
REACH chemical safety regulations and F-Gas emission controls tighten curriculum requirements for maintenance technicians handling refrigerants and industrial solvents across European manufacturing facilities. Training providers must embed substance-specific handling protocols and disposal documentation into certification modules. Process industries in Germany and the Netherlands face the steepest compliance recalibration as auditors link certification validity to environmental liability coverage.
Certificate stacking preferences among maintenance technicians favor modular micro-credentials over comprehensive multi-year programs. Industrial employers in the United States and Germany increasingly specify vendor-neutral competency badges during hiring and promotion decisions. This behavioral shift compresses provider revenue cycles while expanding addressable learner pools among mid-career technicians seeking targeted skill augmentation.
Equipment Maintenance Training Services Market Segmentation
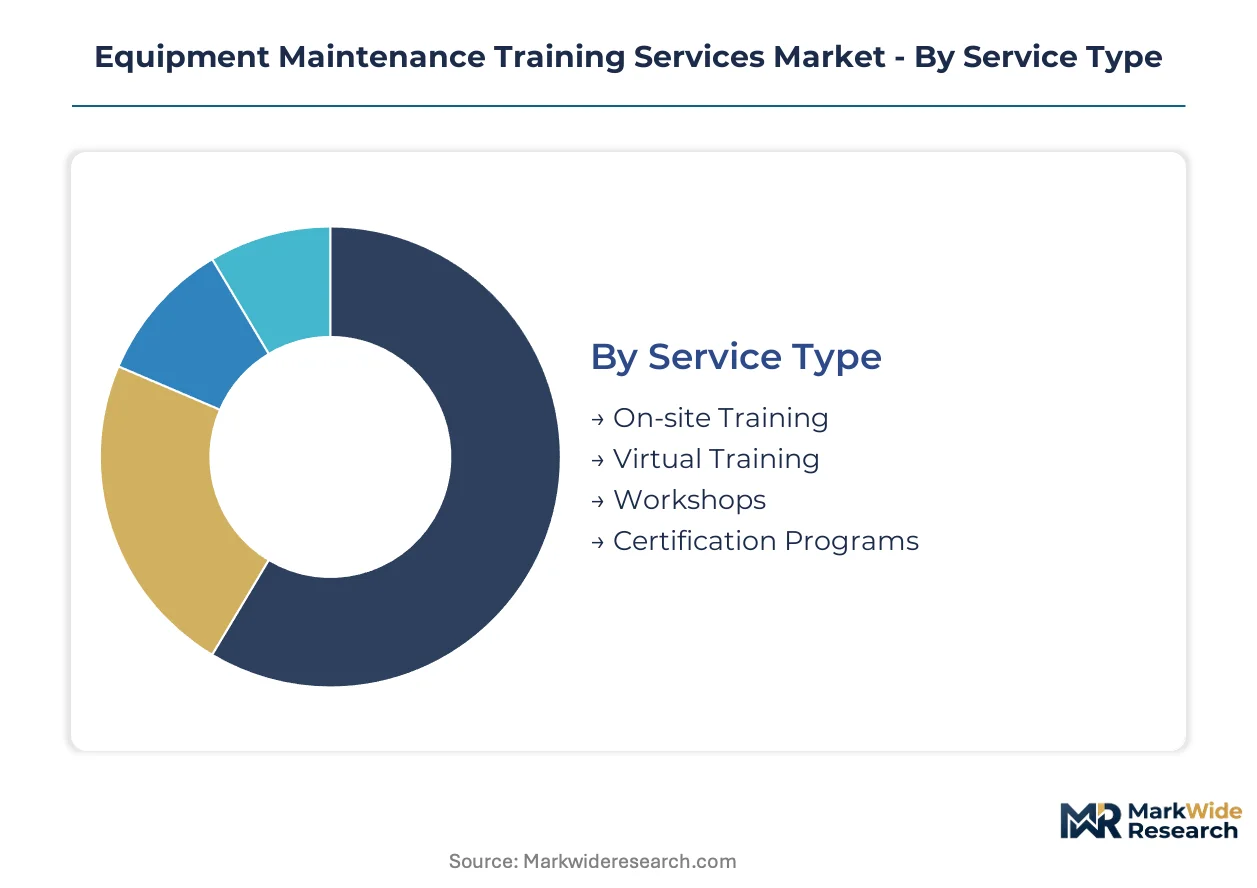
Equipment maintenance training services fragment across four structural dimensions that determine pricing power, renewal frequency, and customer lifetime value. Service type and delivery mode choices directly reflect the after-sales-service intensity of client operations, where high-asset-availability environments demand continuous competency refreshment.
Service Type:
After-sales-service intensity varies dramatically across industrial settings, with continuous-process facilities requiring embedded training partnerships rather than transactional program purchases.
- On-site Training:Technicians receive instruction at operational facilities using actual production equipment, eliminating transport costs and production line disruption. Demand concentrates among German automotive manufacturers and US petrochemical complexes where OSHA mandates require facility-specific lockout/tagout validation. Capital intensity limits provider scalability.
- Virtual Training:Scalable delivery through VR simulations and remote instructor access enables distributed workforce coverage without travel overhead. Utilities operators managing wind and solar assets across multiple states adopt this modality fastest as geographic dispersion makes centralized instruction economically unviable.
- Workshops:Condensed multi-day sessions targeting specific competency gaps such as thermal imaging interpretation or vibration analysis fundamentals. Mid-sized manufacturing facilities in industrial clusters favor this format for cross-training maintenance teams during planned shutdown windows.
- Certification Programs:Comprehensive multi-module curricula culminating in vendor-neutral or OEM-specific credentials. Aviation MRO operators and nuclear facility technicians prioritize these programs as insurance underwriters link coverage terms to documented competency verification.
By volume, On-site Training leads. By growth pace, Virtual Training is expanding most quickly.
Industry Vertical:
Cost tier differentiation separates capital-intensive process industries from project-based construction operations with intermittent training needs.
- Manufacturing:Continuous retooling demands driven by automation upgrades absorb the largest training expenditure share. Automotive and electronics clusters in Germany and the United States specify robotics-specific maintenance curricula aligned with predictive maintenance platform deployments.
- Construction:Project-based demand fluctuates with infrastructure investment cycles, favoring modular micro-credentials over comprehensive programs. Equipment rental fleets and contractor consortia drive seasonal training spikes tied to new project mobilization.
- Aviation:Regulatory stringency from FAA and EASA mandates recurrent certification with documented competency validation. Augmented reality overlays combined with AI-generated maintenance recommendations are reshaping airframe technician training frameworks.
- Utilities:Distributed generation asset proliferation creates geographically dispersed training requirements favoring virtual delivery modalities. Grid operators and renewable infrastructure managers prioritize scalable solutions that avoid production line disruption.
By revenue concentration, Manufacturing dominates. By regulatory complexity, Aviation sets the benchmark.
Delivery Mode:
Application context determines modality selection, with high-risk scenarios retaining tactile certification requirements that resist full digitization.
- Instructor-led:Dominates high-stakes certification programs where tactile familiarity with high-voltage or pressurized systems remains non-negotiable. OSHA and ISO machinery safety standards reinforce demand for documented instructor contact hours.
- Self-paced:Asynchronous module completion enables mid-career technicians to augment specific competencies without production schedule disruption. Certificate stacking preferences favor this modality for targeted skill acquisition.
- Blended Learning:Combines virtual theory modules with condensed in-person practical validation, optimizing cost and safety trade-offs. Nuclear and chemical process facilities increasingly specify this hybrid structure.
- E-learning:Fully digital delivery through web-based platforms and mobile applications serves baseline compliance training and refresher modules. Standardized content limits differentiation among competing providers.
By certification authority acceptance, Instructor-led retains primacy. By learner enrollment velocity, E-learning shows the steepest expansion trajectory.
Audience Type:
Customer type segmentation reveals distinct procurement patterns, with technical roles favoring hands-on validation and managerial roles prioritizing strategic competency frameworks.
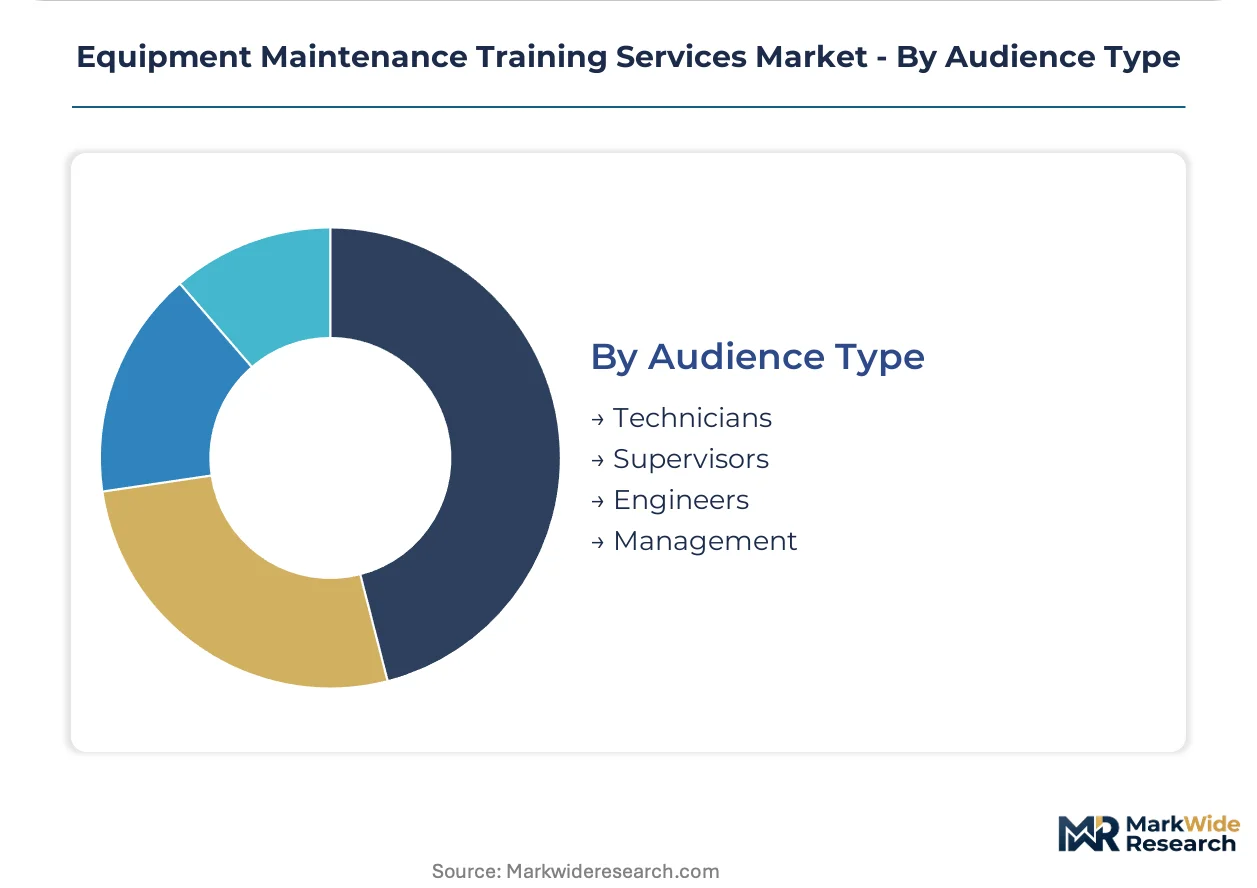
- Technicians:Frontline maintenance personnel require hands-on equipment access and diagnostic tool familiarization. Certificate stacking preferences among this cohort favor modular micro-credentials over comprehensive multi-year programs.
- Supervisors:Team leadership responsibilities demand training in competency assessment, safety protocol enforcement, and maintenance scheduling optimization. Manufacturing facilities specify supervisor certification as a promotion prerequisite.
- Engineers:Design and reliability engineering roles require advanced training in predictive maintenance platform configuration and failure mode analysis. Digital twin integration competencies concentrate demand among this segment.
- Management:Strategic oversight roles prioritize training ROI measurement, vendor selection frameworks, and regulatory compliance architecture. Budget authority makes this segment the gatekeeper for enterprise training contracts.
By headcount scale, Technicians represent the largest addressable pool. By contract value, Management controls the largest budget allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation firms export embedded training modules to automotive manufacturers in the United States, establishing a transatlantic knowledge corridor that shapes curriculum standardization across both markets.
United States
Petrochemical complexes along the Gulf Coast and automotive assembly plants in the Midwest drive sustained demand for OSHA-compliant lockout/tagout certification. OSHA machinery safety mandates tighten compliance windows for industrial facilities, accelerating technician recertification programs. Houston and Detroit industrial clusters anchor facility-specific training partnerships that eliminate production line disruption.
Germany
Automotive and electronics manufacturing clusters require robotics-specific maintenance curricula as predictive maintenance platforms displace reactive protocols. The EU Machinery Directive and CE marking requirements extend regulatory pressure into supplier ecosystems, forcing cross-border assessment standardization. Bavaria's automotive belt and Baden-Württemberg's precision engineering regions concentrate demand for Siemens-integrated training delivery.
China
Heavy manufacturing expansion in Yangtze River Delta and Pearl River Delta industrial zones creates demand for competency validation at scale. GB standards and MIIT industrial policy shape certification requirements for domestic equipment operators. Shanghai and Shenzhen manufacturing hubs prioritize virtual training modalities to cover geographically dispersed production assets.
Japan
Precision machinery and robotics manufacturers in Kanto and Chubu regions require advanced digital twin integration competencies. METI industrial standards and JIS certification protocols govern maintenance technician qualification frameworks. Nagoya's automotive corridor and Tokyo's electronics manufacturing belt concentrate demand for blended learning delivery.
India
Automotive and pharmaceutical manufacturing clusters in Maharashtra and Gujarat drive demand for modular micro-credentials over comprehensive programs. BIS standards and PLI scheme incentives accelerate automation adoption, compressing technician upskilling cycles. Pune and Ahmedabad industrial corridors favor certificate stacking for mid-career technician advancement.
Equipment Maintenance Training Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base concentrates among industrial automation conglomerates with captive training ecosystems and independent certification providers serving mid-sized facilities. Three archetypes dominate: integrated platform vendors embedding training within asset management software, simulation technology specialists licensing proprietary hardware environments, and compliance-focused providers targeting regulated verticals. Competitive moves center on digital twin integration partnerships and geographic expansion through localized curriculum adaptation.
Among integrated platform vendors, Siemens AG and Honeywell International Inc. exemplify the channel-control archetype, each leveraging industrial software ecosystems to embed training delivery within existing customer relationships. ABB Ltd. occupies a specialist position, anchoring competitive differentiation in robotics-specific curricula aligned with automotive manufacturing clusters. These three firms collectively represent the convergence of equipment supply and competency development, a structural pattern that raises barriers for standalone training providers lacking captive hardware installed bases.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| ABB Ltd. |
| Emerson Electric Co. |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| Johnson Controls International plc |
| Baker Hughes Company |
| TechnipFMC plc |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on proprietary VR hardware manufacturers from Taiwan and South Korea compresses pricing tier spreads while forcing training providers into long-term licensing commitments that reshape procurement flexibility across the value chain.
Pricing Analysis
Current-generation immersive simulator suites command premium positioning against prior-generation desktop-based modules and emerging next-generation AI-augmented reality platforms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling intensity. Cost compression in economy-tier e-learning subscriptions is intensifying because mid-sized manufacturing facilities prioritize scalable compliance coverage over tactile validation. Small industrial clusters exhibit highest price sensitivity, while aviation MRO operators demonstrate lowest sensitivity due to insurance-mandated competency thresholds.
Supply Chain Analysis
Upstream feedstock for haptic feedback gloves and extended reality headsets draws from precision sensor manufacturers concentrated in Taiwan, South Korea, and Japan. Rare earth magnet dependencies for motion tracking systems and specialized optical components for high-resolution displays anchor procurement risk. Single-source vulnerability around proprietary software licensing from industrial automation conglomerates creates supplier lock-in exposure. Distribution runs through OEM-embedded training ecosystems and independent certification networks serving facility-specific compliance mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment maintenance training services are approaching a platform-economics inflection as Siemens, Honeywell, and ABB embed competency modules within captive asset management ecosystems, rendering standalone providers dependent on interoperability negotiations.
For Market Incumbents: Build certification-data moats by integrating completion records directly into insurance underwriting workflows and OEM warranty validation systems. Siemens AG and Honeywell International Inc. already embed training telemetry within predictive maintenance platforms, raising switching costs for industrial customers. Incumbents should accelerate digital twin partnership depth with automotive and aviation clusters before emerging simulation specialists achieve API parity.
For New Entrants and Emerging Players: India's pharmaceutical and automotive manufacturing corridors offer underpenetrated demand for modular micro-credentials as PLI scheme incentives accelerate automation adoption. Certificate-stacking preferences among mid-career technicians in Pune and Ahmedabad favor targeted competency augmentation over comprehensive OEM programs. New entrants should pursue white-label virtual training partnerships with regional industrial associations to bypass direct competition with integrated platform vendors.
For Investors and Strategic Acquirers: EU Machinery Directive harmonization reshapes the acquisition landscape by creating cross-border certification validity that scales addressable market reach for compliant providers. Long-term viability centers on providers with demonstrated interoperability across competing asset management ecosystems rather than captive hardware dependencies. Watch for FAA and EASA regulatory convergence on AI-assisted maintenance competency frameworks as the signal for valuation inflection toward augmented-reality training specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration Partnership | Siemens AG embeds training modules within Teamcenter PLM workflows for German automotive OEMs. |
| Virtual Reality Hardware Licensing | Proprietary simulator environments from Honeywell International Inc. lock in petrochemical facility customers. |
| Cross-Border Certification Harmonization | EU Machinery Directive alignment enables ABB Ltd. to scale robotics curricula across European automotive clusters. |
| Insurance Underwriter Data Integration | Aviation MRO operators link training completion records to liability coverage terms through FAA-mandated validation. |
| Modular Micro-Credential Stack | Certificate-stacking preferences among US technicians compress provider revenue cycles while expanding learner pools. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at German automotive manufacturers, plant engineers at US petrochemical complexes, aftermarket service heads at industrial automation conglomerates, and training procurement leads at aviation MRO operators. Secondary validation drew from OSHA compliance enforcement databases, EU Machinery Directive implementation reports, FAA certification bulletins, and SEC 10-K disclosures from listed industrial automation firms. Bottom-up technician demand estimates were triangulated against top-down training expenditure allocations reported across manufacturing verticals.
Calibration across the analysis window employed service type, delivery mode, industry vertical, and audience type segmentation with geographic regulatory cluster overlays. CAGRs were derived from installed base expansion rates for predictive maintenance platforms and recertification cycle compression trends. Forecast inputs incorporated OSHA mandate tightening schedules, EU Machinery Directive harmonization timelines, and aviation regulatory convergence on AI-assisted competency frameworks.
Practitioners should monitor OSHA enforcement intensity, EU Machinery Directive audit outcomes, and FAA/EASA AI-competency rulemaking for early signals of forecast revision. Cross-checking against IHS Markit industrial automation capex data and Cefic chemical industry training expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Cognitive Assessment and Training Market
Professional Development and Training
North America IT Training Market
Professional Development and Training
Global Virtual Training and Simulation Market
Professional Development and Training
Technical and Vocational Education Market
Professional Development and Training
RPA Platform Training Market
Professional Development and Training
Business Coaching Service Market
Professional Development and Training
Personal Development Market
Professional Development and Training
Global Social and Emotional Learning (SEL) Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
US Life Coaching Market
Professional Development and Training
Global Mechatronics and Robotics Courses Market
Professional Development and Training
Europe Leadership Development Program Market
Professional Development and Training
GCC Soft Skills Training Market
Professional Development and Training
HR Professional Services Market