
 Global Blockchain in Supply Chain Finance Market | 2026-2036
Global Blockchain in Supply Chain Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain in Supply Chain Finance Market Foresight
The gap between enterprise-grade blockchain infrastructure and open-source protocol layers is broadening in supply chain finance. IBM leverages its Hyperledger Fabric deployments to anchor institutional trust in multi-party trade networks. SAP SE competes through embedded blockchain modules within its existing ERP customer base, while R3 specializes in Corda-based solutions that dominate letter-of-credit digitization among major banks.
Blockchain in supply chain finance deploys cryptographically linked distributed ledgers with immutable transaction hashes and programmable smart contracts to automate payment triggers against verified delivery events. The primary purpose is eliminating document fraud and settlement delays in cross-border trade. Smart Contracts and IoT Integration represent the fastest-expanding technology pair, as sensor-verified shipment data auto-executes payment terms without manual reconciliation. Consortium Blockchain deployments capture the deepest margin pools, since competing banks and logistics operators require permissioned governance to share sensitive counterparty risk data.
The EU DLT Pilot Regime and the Monetary Authority of Singapore's Project Guardian framework are reshaping how tokenized trade assets gain regulatory legitimacy and institutional liquidity access. The US SEC maintains enforcement scrutiny over unregistered token offerings, pushing platforms toward compliant security token architectures. Stakeholders must monitor which jurisdictions first harmonize bankruptcy-remote treatment of on-chain receivables, as this legal clarity will determine where capital commits to blockchain-native supply chain finance infrastructure.
Market Dynamics
Consortium blockchain architectures are consolidating control over working capital flows as competing financial institutions demand permissioned governance structures that protect counterparty risk data while enabling multi-party automation.
Growth Catalysts
- EU DLT Pilot Regime:Tokenized securities settlement frameworks unlock institutional liquidity pools for trade finance instruments, accelerating regulatory legitimacy for on-chain receivables.
- IoT-Verified Shipment Data:Sensor-automated delivery confirmation triggers smart contract payment execution, eliminating manual reconciliation delays in cross-border transactions.
- Singapore:The Monetary Authority of Singapore's Project Guardian actively promotes blockchain-native supply chain solutions, concentrating capital commitment in Asia-Pacific trade finance infrastructure.
Market Restraints
- Interoperability Limitations:Fragmented protocol standards between Hyperledger Fabric, Corda, and Ethereum-compatible layers prevent seamless data exchange across bank consortia.
- US SEC Scrutiny:Enforcement actions against unregistered token offerings push platforms toward costly security token compliance architectures, extending deployment timelines.
- Specialized Talent Scarcity:Shortage of developers proficient in both cryptographic systems and trade finance operations inflates implementation costs for enterprise deployments.
Strategic Opportunities
- India:RBI's digital rupee pilot and PLI scheme for fintech create regulatory tailwinds for blockchain-based invoice financing platforms targeting SME working capital gaps.
- AI-Blockchain Convergence:Machine learning models analyzing on-chain transaction patterns enable predictive credit scoring for previously unbanked supply chain participants.
- Embedded Finance Channels:ERP-integrated blockchain modules within existing enterprise software distribution networks bypass standalone platform adoption friction.
Industry Challenges
- Legacy System Integration Complexity:SWIFT messaging infrastructure and paper-based trade documentation workflows resist API-level connectivity with distributed ledger platforms.
- Cross-Border Legal Recognition:Absence of harmonized bankruptcy-remote treatment for tokenized receivables across jurisdictions creates enforceability uncertainty for secured lending positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain in Supply Chain Finance Market |
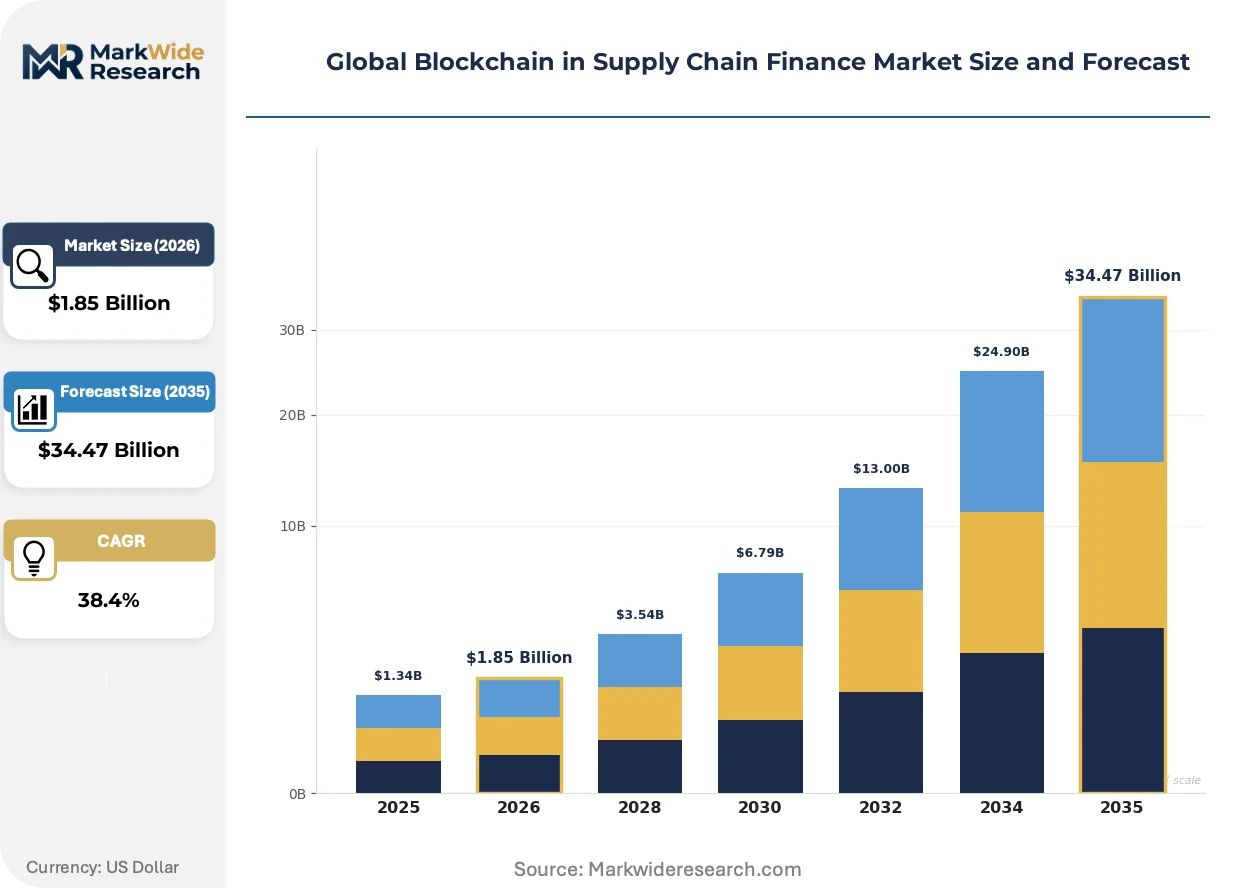
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $34.47 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Distributed Ledger, Smart Contracts, Tokenization, Cryptographic Security, IoT Integration Application: Trade Finance, Invoice Financing, Payment Reconciliation, Supplier Financing, Risk Management Deployment: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Client Type: Financial Institutions, Freight Forwarders, Manufacturers, Exporters, Importers |
| Companies Covered | IBM, Microsoft, Amazon Web Services, SAP SE, R3, ConsenSys, Oracle, Accenture, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain in Supply Chain Finance Market Shifts & Advancements
Programmable settlement infrastructure is absorbing operational layers previously managed by correspondent banking networks, compressing execution timelines from days to minutes.
Zero-knowledge proof implementations are absorbing identity verification and compliance screening functions without exposing sensitive counterparty data to all network participants. Major commodity traders and logistics operators are adopting these privacy-preserving architectures at accelerating pace. This absorption is compressing the traditional trade finance technology stack into unified execution layers.
The EU DLT Pilot Regime establishes sandbox permissions for market infrastructure providers to operate tokenized settlement systems outside standard MiFID II requirements. Industrial consequence includes accelerated pilot deployments of security token platforms for invoice securitization. German and French banking consortia are most affected, redirecting R&D budgets toward compliant token architectures.
Corporate treasury departments now demand real-time visibility into multi-tier supplier payment status, displacing quarterly reconciliation cycles. This behavioral shift disrupts traditional factoring broker channels, with direct platform access replacing intermediary-dependent procurement. The transformation is most visible in Singapore and Dubai trade finance hubs where integrated supply chain visibility commands premium pricing.
Global Blockchain in Supply Chain Finance Market Segmentation
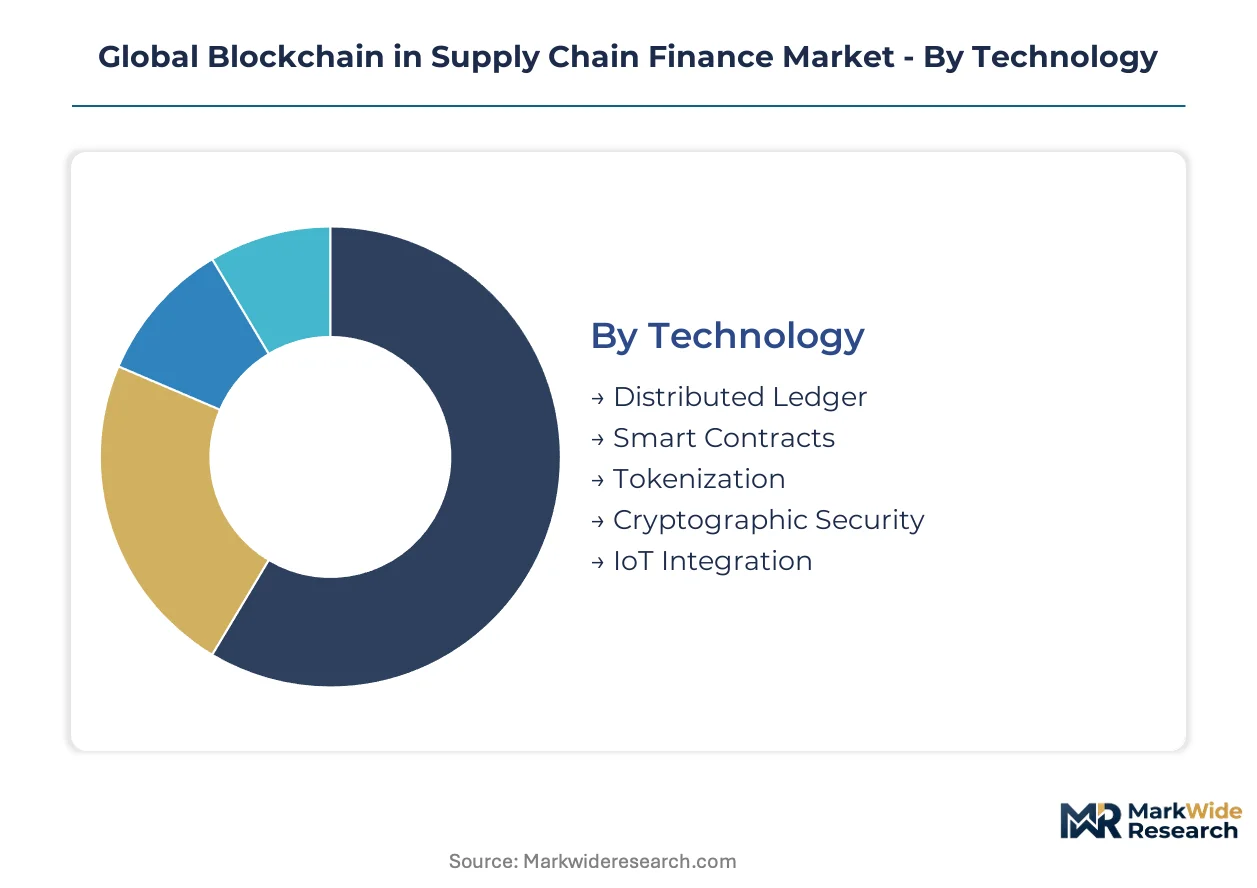
Blockchain supply chain finance segments reflect divergent technical maturity, regulatory exposure, and counterparty risk tolerance across institutional buyers. Technology choice determines automation depth; deployment architecture governs data sovereignty; application focus shapes working capital velocity.
Technology:
Buyer differentiation hinges on automation sophistication versus legacy integration burden.
- Smart Contracts:Self-executing code triggers payment upon IoT-verified delivery events, eliminating manual reconciliation. Singapore's Project Guardian pilots dominate demand concentration as MAS-validated frameworks reduce legal uncertainty for automated settlement.
- IoT Integration:Sensor networks feed real-time shipment data into distributed ledgers, enabling condition-based financing triggers. German automotive supply chains and Dubai logistics hubs concentrate procurement, driven by precision tracking requirements for high-value cargo.
- Distributed Ledger:Immutable transaction hashing creates audit trails for multi-party trade networks.
- Tokenization:On-chain representation of receivables enables fractional ownership and secondary market liquidity.
- Cryptographic Security:Zero-knowledge proofs verify identity without exposing sensitive counterparty data to all network participants.
Volume sits with Distributed Ledger foundations; growth tilts toward IoT Integration as sensor costs decline and 5G coverage expands.
Application:
Revenue concentration aligns with documentation friction intensity in cross-border workflows.
- Trade Finance:Letter-of-credit digitization through Corda-based platforms compresses settlement from weeks to hours. R3 consortium deployments across London, Singapore, and Hong Kong drive demand as correspondent banking relationships migrate to programmable infrastructure.
- Invoice Financing:Tokenized receivables enable SME working capital access previously blocked by paper-based verification. India's RBI digital rupee pilot and PLI scheme for fintech accelerate platform adoption among mid-tier suppliers.
- Payment Reconciliation:Automated matching of purchase orders, delivery receipts, and invoices reduces dispute resolution overhead.
- Supplier Financing:Early payment programs embedded in procurement platforms extend credit to tier-2 and tier-3 vendors.
- Risk Management:On-chain credit scoring and real-time exposure monitoring replace quarterly counterparty reviews.
Trade Finance commands the deepest revenue pools; Invoice Financing is climbing the fastest as regulatory sandboxes validate tokenized securities frameworks.
Deployment:
Architecture choice reflects governance requirements for sensitive counterparty data sharing.
- Consortium Blockchain:Permissioned networks governed by competing banks balance automation with confidentiality. EU DLT Pilot Regime authorizations accelerate deployments among German and French banking consortia seeking MiFID II-compliant settlement infrastructure.
- Private Blockchain:Single-entity control suits captive supply chains with concentrated procurement power. Walmart's food traceability network and Maersk's TradeLens legacy demonstrate enterprise demand for internal coordination without external governance complexity.
- Public Blockchain:Open participation enables broad supplier onboarding but conflicts with bank secrecy requirements.
- Hybrid Blockchain:Selective data exposure to public layers while retaining sensitive operations on private nodes.
Consortium Blockchain anchors institutional commitment; Hybrid Blockchain is gaining share fastest as interoperability protocols mature.
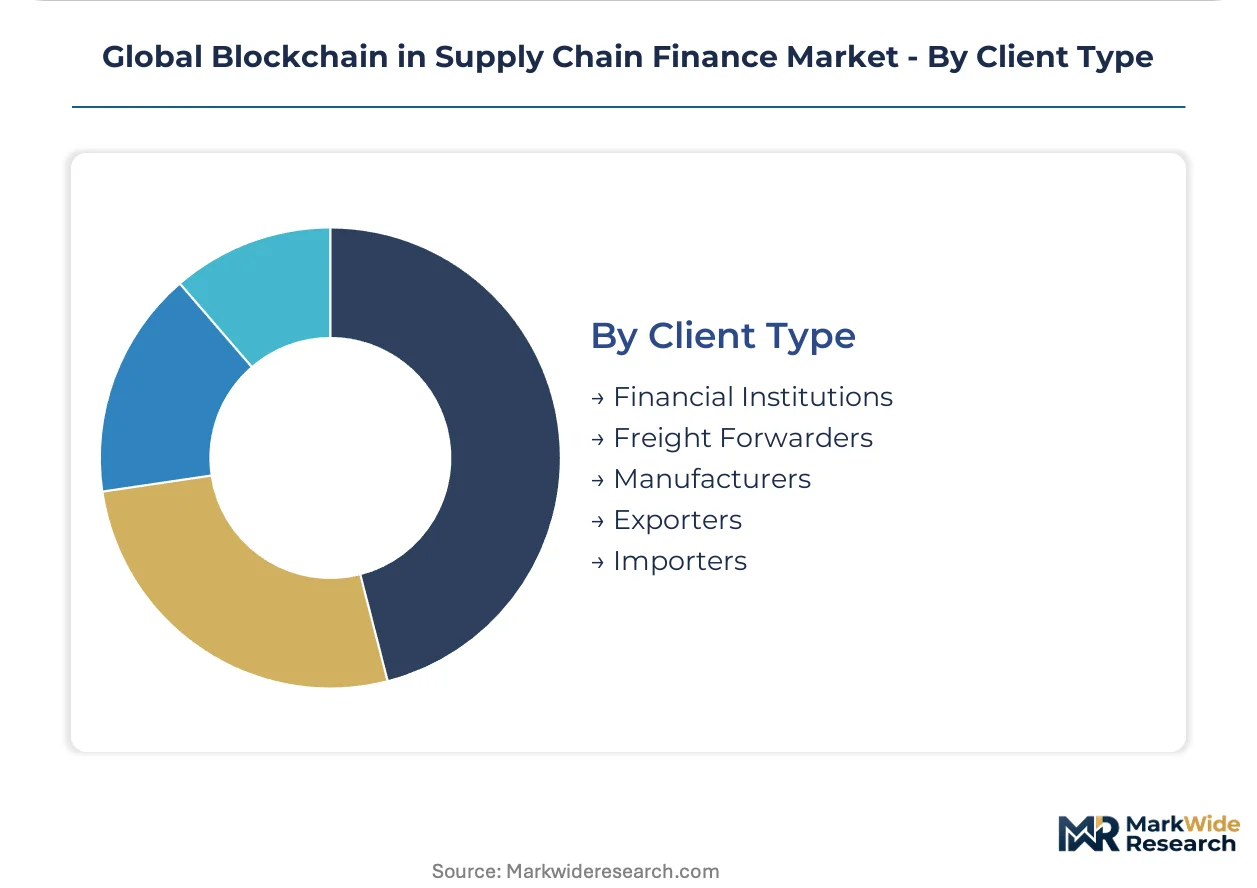
Client Type:
Procurement sophistication and balance sheet capacity determine platform engagement depth.
- Financial Institutions:Banks and non-bank lenders deploy distributed ledgers to reduce invoice fraud and accelerate working capital flows. Singapore's trade finance hub concentrates deployment as MAS actively promotes blockchain-native infrastructure.
- Manufacturers:Corporate treasury departments demand real-time multi-tier supplier visibility, displacing quarterly reconciliation cycles. Automotive and electronics producers in Germany and Japan lead adoption for complex component sourcing.
- Freight Forwarders:Logistics operators seek document digitization to accelerate customs clearance and reduce demurrage exposure.
- Exporters:SME exporters gain access to pre-shipment financing through verified order tokenization.
- Importers:Procurement platforms embed financing to extend payment terms while preserving supplier relationships.
Financial Institutions deploy the most capital; Manufacturers are expanding most quickly as ERP-integrated modules reduce standalone platform friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's trade finance hub concentrates the deepest blockchain supply chain finance deployment, with the Monetary Authority of Singapore's Project Guardian validating institutional frameworks for automated settlement.
United States
Corporate treasury departments in New York and San Francisco drive demand for real-time multi-tier supplier visibility, displacing quarterly reconciliation cycles. The SEC maintains enforcement scrutiny over unregistered token offerings, pushing platforms toward compliant security token architectures. Chicago's commodity trading houses and Los Angeles port logistics operators pilot zero-knowledge proof implementations for privacy-preserving trade documentation.
Germany
Automotive manufacturers in Stuttgart and Munich demand IoT-verified shipment data for complex component sourcing across tiered supplier networks. The EU DLT Pilot Regime authorizes sandbox permissions for tokenized securities settlement, accelerating compliant platform deployments. Frankfurt's banking consortia redirect R&D budgets toward MiFID II-compatible distributed ledger infrastructure for invoice securitization.
China
Manufacturers in Shenzhen and Shanghai seek blockchain-native working capital solutions for SME supplier financing gaps. The central bank's digital currency pilot creates regulatory tailwinds for tokenized receivables platforms. Hangzhou's fintech corridor and Beijing's Zhongguancun technology zone concentrate venture capital commitment to supply chain finance infrastructure.
India
Mid-tier exporters in Mumbai and Bengaluru gain access to pre-shipment financing through verified order tokenization. RBI's digital rupee pilot and PLI scheme for fintech accelerate platform adoption among SME suppliers. Gujarat's industrial corridors and Tamil Nadu's automotive clusters embed blockchain modules within existing ERP distribution networks.
United Arab Emirates
Logistics operators in Dubai and Abu Dhabi adopt document digitization to accelerate customs clearance and reduce demurrage exposure. The central bank's fintech licensing framework enables sandbox testing for tokenized trade finance instruments. Jebel Ali Free Zone and Dubai International Financial Centre concentrate capital commitment to blockchain-native supply chain visibility platforms.
Global Blockchain in Supply Chain Finance Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light protocol developers for control of enterprise deployment pipelines. The vendor base splits between consolidated technology conglomerates with captive cloud distribution and specialized distributed ledger firms with deep banking relationships. Three archetypes dominate: ERP-embedded platform vendors, consortium-governed network operators, and cloud-native infrastructure providers. Competitive moves concentrate on strategic partnerships with financial institutions and vertical integration into IoT sensor networks for automated delivery verification.
Within the ERP-embedded tier, SAP SE and Oracle occupy positions that leverage existing enterprise customer relationships for blockchain module distribution. IBM and Microsoft exemplify the cloud-native infrastructure archetype, anchoring institutional trust through Hyperledger Fabric and Azure-based deployments respectively. R3 represents the consortium-governance specialist, sitting within the letter-of-credit digitization segment where permissioned Corda networks dominate banking consortia in London, Singapore, and Hong Kong.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Amazon Web Services |
| SAP SE |
| R3 |
| ConsenSys |
| Oracle |
| Accenture |
| Huawei Technologies |
| Others |
Supply & Pricing Matrix
Enterprise-grade Hyperledger Fabric deployments command substantial premiums over open-source protocol alternatives, with that certification-tier divergence manifesting in both subscription pricing and vendor supply chain configurations. Banks in Singapore and Germany absorb higher costs for MAS-validated and EU DLT Pilot Regime-compliant modules, while mid-market logistics operators in India and the UAE source standardized Corda-based solutions through regional system integrators.
Pricing Analysis
Value-based pricing anchored to transaction throughput and settlement velocity dominates enterprise procurement. Three-tier pricing structure across premium consortium governance, standard SaaS modules, and economy API access reflects automation depth and counterparty data sovereignty levels. Cost compression in the standard tier intensifies because cloud-native infrastructure providers bundle blockchain modules with existing enterprise subscriptions. Financial institutions in London and Hong Kong exhibit the least price sensitivity, prioritizing regulatory validation over per-seat economics, while SME exporters in India and Southeast Asia drive hard volume discounts for invoice tokenization services.
Supply Chain Analysis
Reverse-logistics flows for obsolete hardware wallets and decommissioned validator nodes remain underdeveloped, creating stranded asset risk for early enterprise adopters. Component sourcing concentrates in Taiwan for cryptographic processors, South Korea for secure enclave manufacturing, and China for IoT sensor assembly. The ecosystem draws from specialized semiconductor foundries, cryptographic key management hardware, and enterprise software distribution networks. Single-source vulnerability in qualified security module supply creates systemic exposure for permissioned network deployments. Distribution runs through hyperscaler marketplaces, banking technology consortia, and ERP-embedded channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
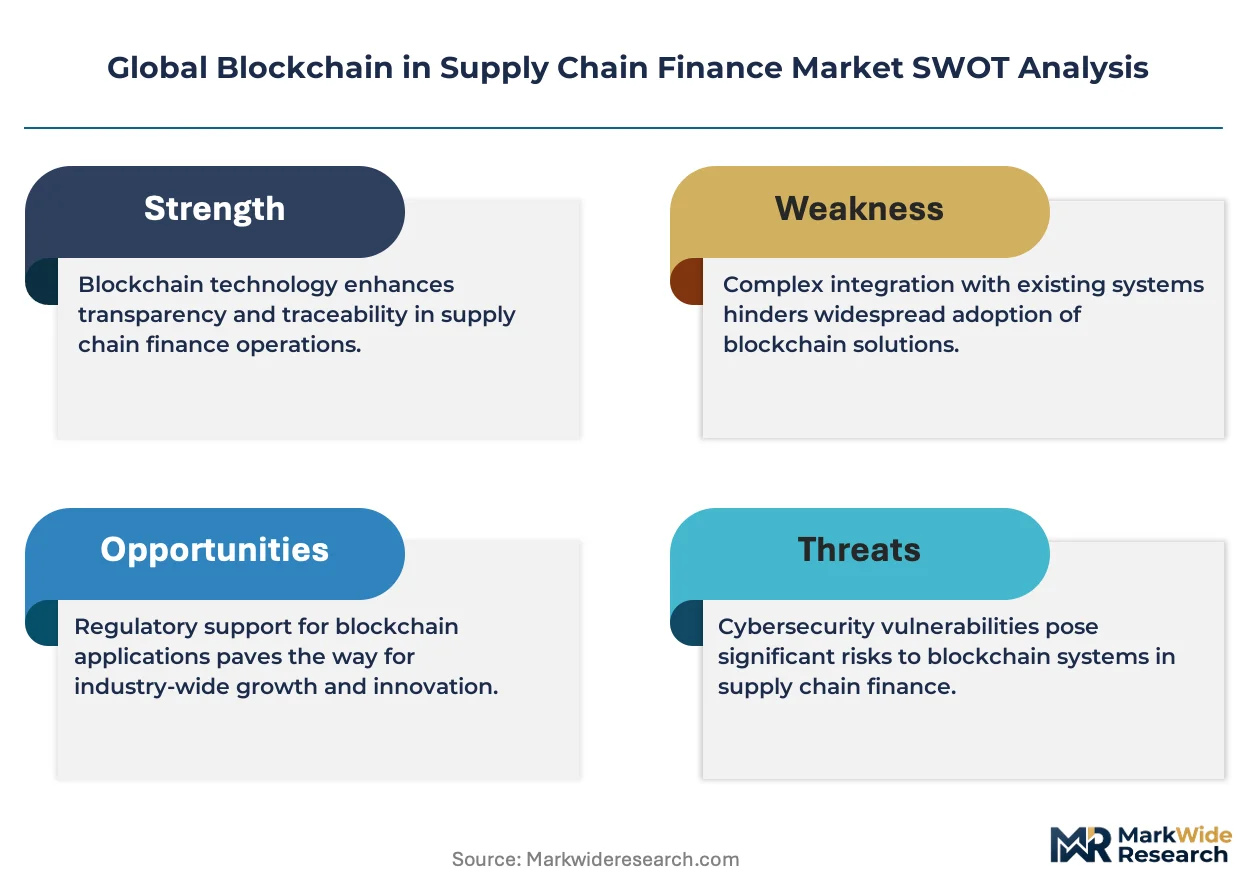
Blockchain supply chain finance sits in a technology-transition phase, with programmable settlement infrastructure displacing correspondent banking networks and SWIFT messaging workflows.
For Market Incumbents: To counter cloud-native infrastructure providers bundling blockchain modules with enterprise subscriptions, IBM and R3 must deepen banking consortium exclusivity through co-development agreements. SAP SE should accelerate ERP-embedded distribution to lock in manufacturing treasury departments before standalone platforms achieve interoperability. Certification investment in EU DLT Pilot Regime and MAS Project Guardian frameworks remains the critical defensive lever. For New Entrants and Emerging Players: Mid-tier automotive suppliers in Germany and Japan represent the most penetrable buyer archetype, with unmet demand for IoT-verified component financing across tiered sourcing networks. India's PLI scheme fintech beneficiaries offer a regulatory-sanctioned entry path for invoice tokenization platforms. Embedded finance partnerships with existing ERP distributors bypass standalone platform adoption friction. For Investors and Strategic Acquirers: Re-rating potential sits with consortium-governance specialists given accelerating EU DLT Pilot Regime authorizations and Singapore MAS validation frameworks. Long-term viability across the analysis window favors vendors with captive banking relationships and compliant token architectures. The signal to watch is harmonized bankruptcy-remote treatment for on-chain receivables in major trade finance jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Network Expansion | Deepens counterparty data sharing among competing banks under EU DLT Pilot Regime permissions. |
| IoT Sensor Integration | Enables condition-based financing triggers for German automotive and Dubai logistics supply chains. |
| Security Token Architecture | Positions platforms for US SEC compliance and institutional liquidity access. |
| ERP Module Embedding | Reduces standalone adoption friction for corporate treasury departments in manufacturing. |
| Zero-Knowledge Proof Deployment | Absorbs identity verification without exposing sensitive counterparty data to all network participants. |
Research Methodology
Multi-period observation of MAS Project Guardian pilot deployments, EU DLT Pilot Regime authorizations, and banking consortium R&D allocations anchored the trend analysis, supplemented by interviews with blockchain platform engineers, trade finance operations leads at major banks, corporate treasury directors, ERP integration specialists, and regulatory policy officers. Secondary validation drew from SEC enforcement filings, European Securities and Markets Authority sandbox disclosures, Singapore fintech licensing records, and hyperscaler enterprise blockchain service announcements. Bottom-up platform deployment tracking and top-down banking technology spending analysis provided triangulation.
Input-output matrices modeled technology adoption across smart contract automation depth, IoT sensor integration intensity, and deployment architecture governance requirements. Segmentation dimensions included settlement velocity tiers, counterparty data sovereignty levels, and regional regulatory validation status. CAGRs were derived from deployment run-rate trajectories and working capital flow acceleration metrics. Forecast inputs incorporated central bank digital currency pilot expansion and trade documentation digitization mandates.
Revisions become necessary when harmonized bankruptcy-remote treatment for tokenized receivables materializes in additional jurisdictions, or when major banking consortia abandon permissioned architectures for public blockchain alternatives. Practitioners should monitor regulatory sandbox graduation timelines and correspondent banking relationship migration patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Europe Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
Decentralized Finance Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market