
 United States Switchgear Market | 2026-2036
United States Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
United States Switchgear Market Insights
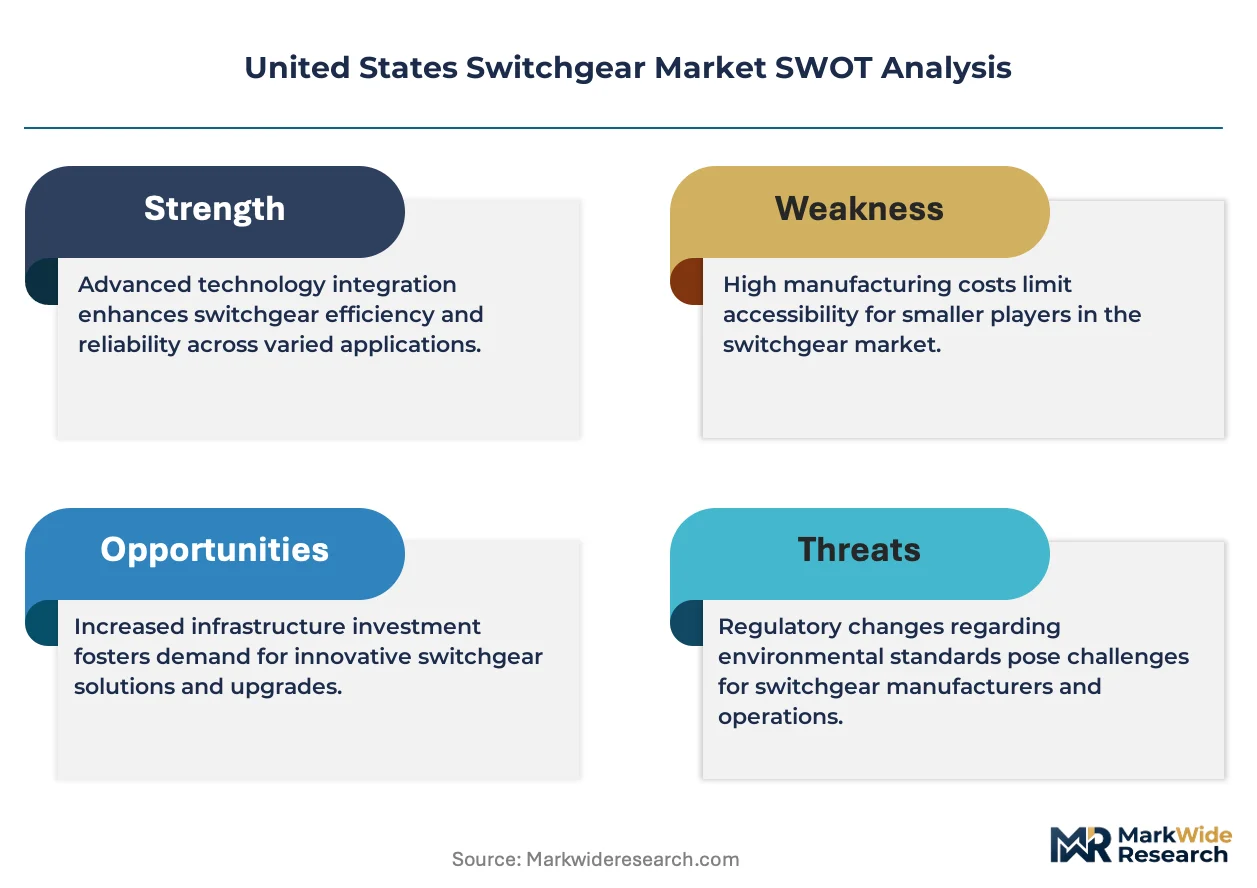
Domestic switchgear production capacity is broadening across the Ohio River Valley and Gulf Coast manufacturing corridors. Eaton Corporation plc leverages its integrated electrical platform to anchor utility and industrial channel relationships. Siemens AG competes through specialized medium voltage and digital switchgear architectures. Powell Industries Inc. sustains its position in custom-engineered outdoor and modular installations for oil, gas, and petrochemical end users.
Switchgear encompasses electrical apparatus designed to control, protect, and isolate power circuits, with medium voltage systems typically rated between 1 kV and 52 kV employing vacuum, air, or SF6 interruption technologies. These assemblies serve critical functions in power distribution networks by interrupting fault currents and enabling safe maintenance operations. Medium voltage and digital switchgear categories command attention as grid operators prioritize arc-flash mitigation and remote monitoring capabilities. Low voltage installations retain volume dominance across commercial and residential buildings, though margin pools increasingly favor IoT-enabled and smart grid connectivity segments where predictive maintenance contracts extend revenue streams.
NIST, IEEE, and OSHA standards govern switchgear design, testing, and worker safety protocols, with OSHA 1910.269 specifically addressing protective equipment in electric power generation, transmission, and distribution environments. FERC interconnection rules and state-level renewable portfolio standards compel utilities to specify switchgear with enhanced fault ride-through and bidirectional power flow capabilities. Stakeholders must monitor evolving EPA restrictions on sulfur hexafluoride emissions and corresponding IEEE revisions affecting gas-insulated system specifications.
Market Dynamics
Utility-scale grid modernization across Texas, California, and PJM territory is compressing procurement cycles for medium voltage switchgear as data center load growth and renewable interconnection backlogs strain legacy infrastructure. This structural pressure is reshaping vendor-customer relationships and technical specifications simultaneously.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation rules compel utilities to specify bidirectional-capable switchgear, expanding addressable market for digital and smart grid-ready systems.
- Data center clusters:Hyperscale facility buildouts in Northern Virginia and Dallas-Fort Worth are driving concentrated demand for high-reliability medium voltage distribution equipment with enhanced fault ride-through.
- Sulfur hexafluoride alternatives:Vacuum interruption and clean air insulation technologies are gaining specification preference as EPA emission scrutiny intensifies across gas-insulated installations.
Market Restraints
- Copper and electrical steel volatility:Raw material price swings compress margin predictability for domestic manufacturers serving price-sensitive municipal utility segments.
- Specialized fabrication concentration:Custom-engineered outdoor switchgear production clusters along the Gulf Coast create geographic supply vulnerability to hurricane disruption.
- SF6 phase-down timeline uncertainty:Incomplete IEEE revision cycles leave specification engineers without clear compliance pathways for existing gas-insulated infrastructure upgrades.
Strategic Opportunities
- Southeast utility modernization:Tennessee Valley Authority and regional cooperatives present underpenetrated demand for arc-flash-mitigated digital switchgear with remote monitoring capabilities.
- Predictive maintenance contracts:IoT-enabled condition monitoring creates recurring revenue streams beyond equipment sales, particularly for industrial end users in petrochemical corridors.
- Inflation Reduction Act manufacturing credits:Clean energy domestic content incentives accelerate Ohio River Valley production expansion for export-competitive medium voltage assemblies.
Industry Challenges
- Medium voltage engineering talent scarcity:Specialized power systems design expertise concentrates among retiring utility-sector professionals, constraining project execution velocity.
- Legacy electromechanical integration:Digital switchgear deployment requires complex retrofit coordination with existing protection relay schemes and SCADA architectures.
- OSHA 1910.269 compliance certification:Arc-flash hazard analysis and protective equipment verification extend project timelines for transmission-scale installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Switchgear Market |
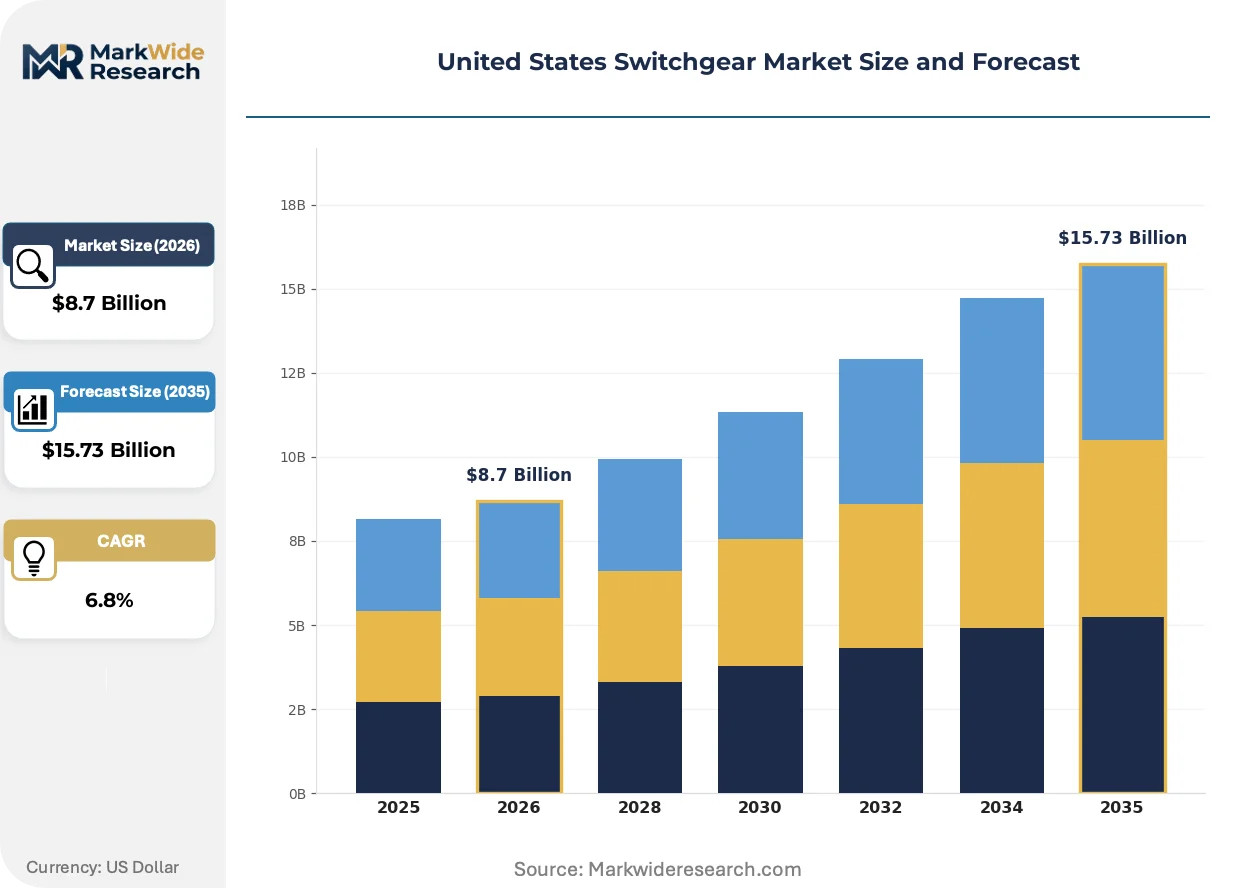
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, Low Voltage, High Voltage, Digital Switchgear End User: Industrial, Commercial, Utility, Residential Installation Type: Outdoor, Indoor, Modular, Fixed Mount Connectivity: Wired, Wireless, IoT-enabled, Smart Grid |
| Companies Covered | ABB Ltd., Schneider Electric SE, Siemens AG, Eaton Corporation plc, General Electric Company, Powell Industries Inc., Hubbell Incorporated, Mitsubishi Electric Corporation, Hitachi Energy Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Switchgear Market Trends and Innovations
Digitalization of protection and control functions is collapsing the traditional boundaries between switchgear hardware and software-defined grid management platforms. This convergence is redrawing competitive advantage around data architecture and cybersecurity credentials rather than pure manufacturing scale.
Vacuum interruption technology is overtaking sulfur hexafluoride insulation across medium voltage distribution applications due to elimination of greenhouse gas regulatory exposure. Investor-owned utilities in California and Texas are specifying vacuum breakers for new substation builds, while industrial buyers in oil and gas corridors prioritize SF6-free architectures for ESG reporting alignment. This substitution is compressing service revenue from gas handling and leak detection that previously anchored manufacturer-customer relationships.
EPA restrictions on sulfur hexafluoride emissions are compelling specification revisions across gas-insulated switchgear categories. The agency's proposed phase-down schedules force utilities to accelerate capital planning for vacuum and clean air alternatives while awaiting final IEEE C37.100.1 amendments. PJM interconnection queue participants face particular compliance pressure as renewable project developers demand SF6-free equipment to satisfy offtake contract environmental provisions.
Hyperscale data center operators are consolidating procurement authority at the corporate engineering level, bypassing traditional electrical contractor channels. This buyer concentration shifts negotiation leverage toward extended warranty and performance-guarantee terms rather than upfront equipment pricing. Northern Virginia and Phoenix markets exhibit the most pronounced channel compression as direct utility interconnection agreements become standard for campus-scale developments.
United States Switchgear Market Segmentation
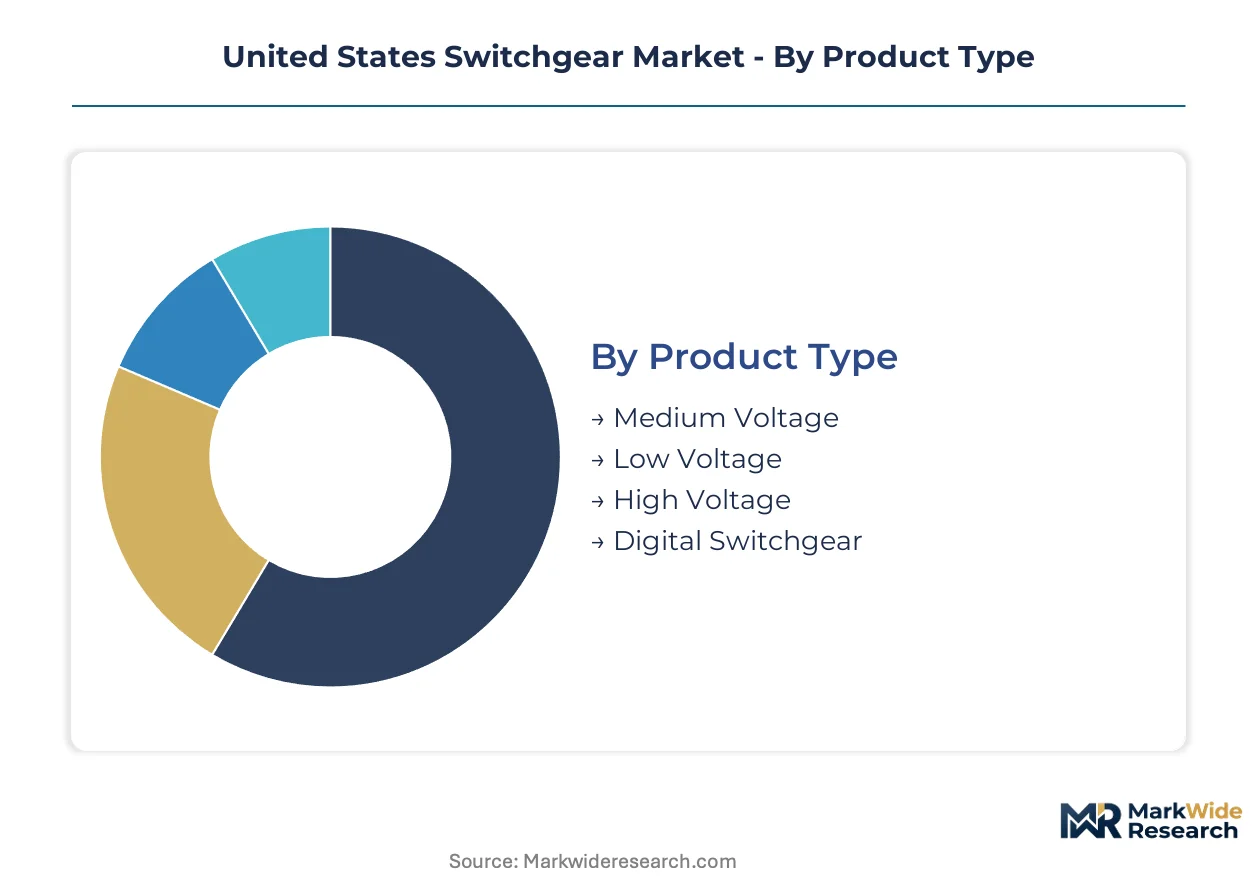
Switchgear procurement patterns diverge sharply across voltage classes and installation environments, with specification requirements varying by end-use reliability demands and interconnection complexity. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
Voltage rating and interruption technology define the core specification axis, with insulation medium and arc-quenching method driving procurement differentiation across utility and industrial channels.
- Medium Voltage:Systems rated 1 kV to 52 kV employ vacuum, air, or SF6 interruption technologies for distribution network protection. Demand concentrates in Texas and PJM territory where renewable interconnection backlogs and data center load growth strain legacy infrastructure, compressing procurement cycles for bidirectional-capable assemblies.
- Digital Switchgear:Integrated protection, control, and monitoring functions collapse hardware-software boundaries through software-defined grid management platforms. California utilities specify these architectures for arc-flash mitigation and remote diagnostics, with cybersecurity credentials now outweighing pure manufacturing scale in competitive positioning.
- Low Voltage:Commercial and residential building applications retain volume dominance despite thinner margins.
- High Voltage:Transmission-scale installations above 52 kV serve regional interconnection and bulk power transfer functions.
Low voltage leads on scale; digital switchgear leads on momentum.
End User:
Capital intensity and reliability requirements create distinct procurement behaviors across customer categories, with contract structures and specification authority varying by scale and technical sophistication.
- Utility:Investor-owned and municipal operators drive medium voltage and high voltage procurement through centralized engineering specifications. FERC Order 2222 compliance pressures and IRA clean energy incentives reshape interconnection standards across Southeast cooperatives and Texas ISO territory, expanding addressable market for smart grid-ready systems.
- Industrial:Oil, gas, and petrochemical end users prioritize custom-engineered outdoor installations with extended warranty terms. Ohio River Valley and Gulf Coast manufacturing corridors see concentrated demand for arc-flash-mitigated equipment with predictive maintenance contracts.
- Commercial:Building-scale distribution emphasizes low voltage panelboards and switchboards with IoT connectivity for energy management integration.
- Residential:Single-family and multi-family construction drives standardized low voltage load center volume.
Utility procurement leads on scale; industrial retrofit demand leads on momentum.
Installation Type:
Environmental exposure and mobility requirements determine enclosure specifications, with seismic, corrosion, and thermal cycling resilience driving engineering differentiation.
- Outdoor:NEMA-rated enclosures withstand temperature extremes, moisture, and particulate contamination for substation and industrial yard applications. Gulf Coast production clusters face hurricane disruption vulnerability, compressing delivery reliability for petrochemical corridor projects.
- Modular:Prefabricated skid-mounted assemblies accelerate deployment for data center campuses and renewable generation tie-ins. Northern Virginia and Phoenix hyperscale operators specify these for reduced on-site construction duration and factory-tested quality assurance.
- Indoor:Climate-controlled environments permit reduced enclosure ratings for commercial and light industrial facilities.
- Fixed Mount:Permanent installations dominate utility substation and heavy industrial applications with decades-long asset lifecycles.
Outdoor installations lead on scale; modular configurations lead on momentum.
Connectivity:
Communication architecture selection determines integration complexity with existing SCADA and protection relay schemes, with cybersecurity and interoperability requirements reshaping specification priorities.
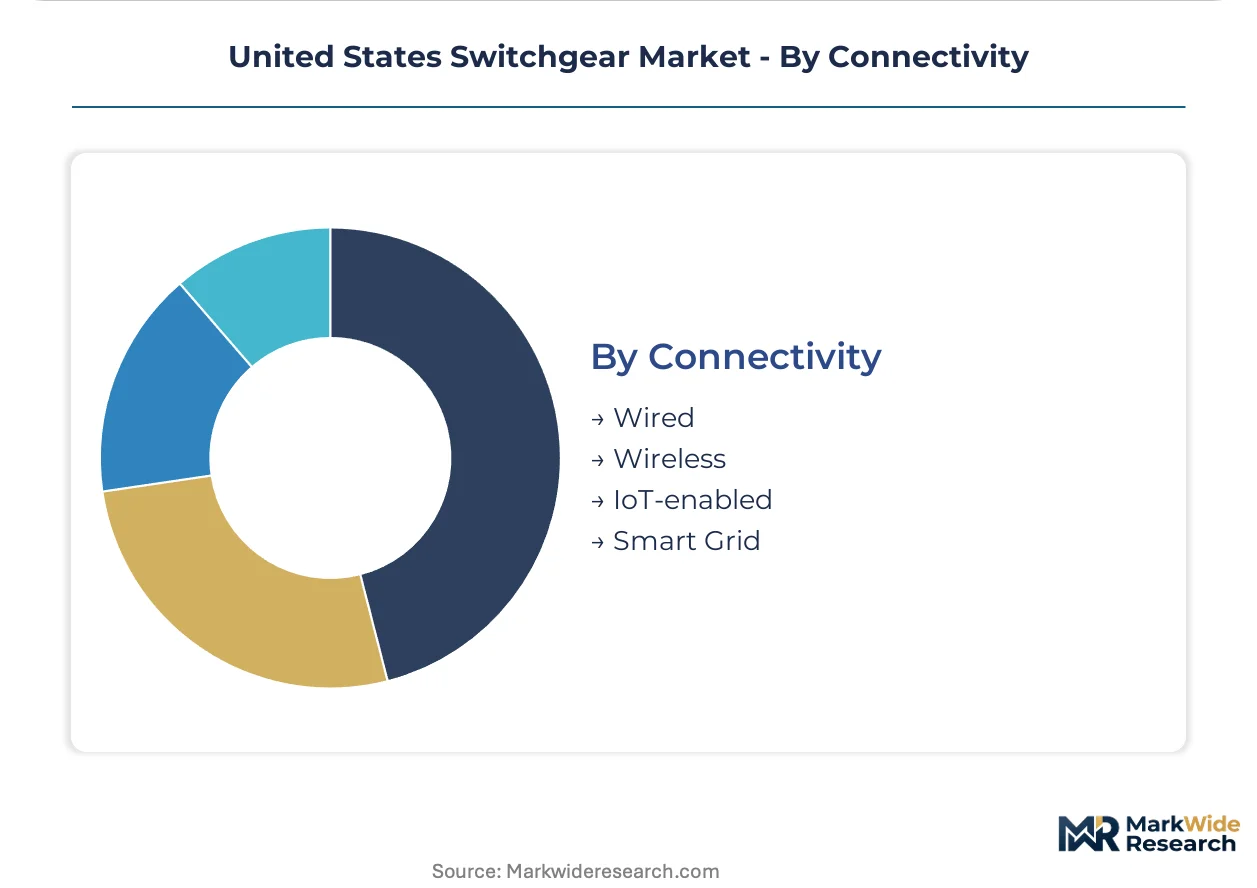
- IoT-enabled:Embedded sensors and edge computing enable predictive maintenance and condition-based monitoring. Industrial buyers in petrochemical corridors adopt these architectures to extend revenue streams beyond equipment sales through recurring service contracts.
- Smart Grid:Bidirectional power flow and distributed resource aggregation capabilities satisfy FERC Order 2222 interconnection rules. PJM queue participants face particular compliance pressure as renewable developers demand these specifications for offtake contract environmental provisions.
- Wired:Fiber and copper communication remains standard for critical utility protection circuits requiring deterministic latency.
- Wireless:Cellular and mesh radio architectures reduce cabling costs for distributed monitoring applications in remote substations.
Wired connectivity leads on scale; IoT-enabled architectures lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity is migrating toward states with favorable clean energy manufacturing credits under the Inflation Reduction Act, creating a regulatory-arbitrage advantage for Ohio River Valley and Gulf Coast fabrication corridors over higher-compliance-cost jurisdictions.
Texas
Hyperscale data center clusters in Dallas-Fort Worth and renewable interconnection backlogs across ERCOT territory are compressing procurement cycles for medium voltage switchgear with bidirectional power flow capabilities. FERC Order 2222 compliance pressures are reshaping utility specifications for distributed resource aggregation. Gulf Coast fabrication hubs face hurricane disruption vulnerability, driving inventory pre-positioning for petrochemical corridor projects.
California
Investor-owned utilities are specifying digital switchgear architectures for arc-flash mitigation and remote diagnostics as wildfire-related liability pressures intensify grid reliability mandates. EPA restrictions on sulfur hexafluoride emissions are accelerating vacuum interruption technology adoption ahead of final IEEE C37.100.1 amendments. Silicon Valley data center operators are consolidating procurement authority at corporate engineering levels, bypassing traditional electrical contractor channels.
PJM Interconnection Territory
Northern Virginia's hyperscale facility buildouts are driving concentrated demand for high-reliability medium voltage distribution equipment with enhanced fault ride-through. Interconnection queue participants face particular compliance pressure as renewable project developers demand SF6-free equipment to satisfy offtake contract environmental provisions. Pennsylvania and Ohio manufacturing corridors are expanding production capacity to capture Inflation Reduction Act domestic content incentives.
Southeast
Tennessee Valley Authority and regional electric cooperatives present underpenetrated demand for arc-flash-mitigated digital switchgear with remote monitoring capabilities. Utility-scale grid modernization programs are accelerating procurement of medium voltage systems across Florida and Georgia. Carolina manufacturing clusters are leveraging port access for export-competitive modular switchgear assemblies serving Caribbean and Latin American markets.
Midwest
Ohio River Valley production expansion is capturing Inflation Reduction Act manufacturing credits for medium voltage assemblies serving industrial end users in petrochemical corridors. Michigan and Illinois utility modernization programs are prioritizing IoT-enabled condition monitoring for predictive maintenance contracts. Chicago-area electrical distributors are consolidating inventory positions for low voltage panelboards serving commercial building retrofits.
United States Switchgear Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digitalization and SF6-free architectures as differentiation vectors. The vendor base clusters around three archetypes: integrated electrical platforms with utility channel dominance, specialized medium voltage fabricators with custom engineering capabilities, and industrial-focused outdoor installation specialists. Strategic moves concentrate on backward integration into copper and electrical steel supply chains, alongside capacity expansion along Ohio River Valley and Gulf Coast corridors.
Among diversified electrical equipment conglomerates, ABB Ltd., Schneider Electric SE, and Siemens AG exemplify the integrated platform archetype, anchoring utility and industrial channel relationships through broad product portfolios. These Switzerland-based, France-based, and Germany-based entities respectively represent global-scale competitors whose positioning reflects the market's premium-tier concentration around digital switchgear and smart grid connectivity capabilities.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric SE |
| Siemens AG |
| Eaton Corporation plc |
| General Electric Company |
| Powell Industries Inc. |
| Hubbell Incorporated |
| Mitsubishi Electric Corporation |
| Hitachi Energy Ltd. |
| Others |
Pricing and Supply Chain Analysis
Medium voltage engineering talent concentration in the Ohio River Valley and Gulf Coast corridors feeds directly into pricing-tier spreads, with labor-cost differentials between unionized utility-scale fabrication and non-union modular assembly creating a three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Distributor margin capture in the 15-25% range separates premium digital switchgear from standard electromechanical assemblies, with direct-to-utility procurement bypassing electrical contractor channels compressing markups for hyperscale data center projects. Price differentiation hinges on arc-flash certification tier and IoT-enabled condition monitoring bundling. Cost compression in municipal utility segments is intensifying because of copper and electrical steel volatility. Commercial building contractors exhibit highest price sensitivity; investor-owned utilities demonstrate lowest sensitivity due to rate-base recovery mechanisms.
Supply Chain Analysis
Regional distribution centers in Ohio, Texas, and Louisiana anchor hub-and-spoke patterns serving petrochemical corridors and utility substation projects. Geographic supply concentration draws from domestic copper mining in Arizona and Utah, electrical steel production in Indiana and Pennsylvania, and vacuum interrupter imports from Germany and Japan. Raw material dependencies rest on copper cathode, grain-oriented electrical steel, and epoxy resin systems. Single-source vulnerability in specialized vacuum interrupter supply creates procurement risk. Distribution runs through manufacturer-direct channels for utility-scale projects and electrical distributor networks for commercial and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with FERC Order 2222 compliance pressures and SF6 phase-down timelines forcing specification upgrades toward premium digital architectures with predictive maintenance capabilities.
For Market Incumbents: To counter emerging SF6-free technology specialists, anchor utility relationships through backward integration into copper and electrical steel supply chains while accelerating Ohio River Valley capacity expansion to capture Inflation Reduction Act domestic content incentives. Certification investment in IEEE C37.100.1-compliant vacuum interruption architectures serves as the priority defensive lever against regulatory displacement. For New Entrants and Emerging Players: Capture underpenetrated demand across Tennessee Valley Authority and Southeast electric cooperatives for arc-flash-mitigated digital switchgear with remote monitoring capabilities. The most penetrable segment lies in modular prefabricated assemblies for data center campus interconnections. A direct-utility sales model bypassing traditional electrical contractor channels offers the strongest go-to-market angle against established distributor relationships. For Investors and Strategic Acquirers: Industrial electrical conglomerates pursuing grid modernization portfolios are the most active acquirer in this space, with long-term viability hinging on 5-10 year utility capital expenditure cycles for renewable interconnection and data center load growth. Acquisition targets should display captive vacuum interruption technology or established predictive maintenance service contracts. The signal to watch is FERC interconnection queue processing velocity as an inflection indicator for medium voltage equipment procurement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Supply | Captive Arizona and Utah mining access insulates margin volatility from commodity spot markets. |
| Vacuum Interruption Technology Licensing | SF6-free architectures satisfy EPA emission restrictions and California utility procurement mandates. |
| Predictive Maintenance Service Contracts | IoT-enabled condition monitoring extends revenue streams beyond equipment sales for petrochemical end users. |
| Modular Prefabrication Capacity Expansion | Factory-tested skid-mounted assemblies reduce on-site construction duration for Northern Virginia data centers. |
| Direct Utility Channel Development | Bypassing electrical contractor networks captures hyperscale procurement authority consolidation at corporate engineering levels. |
Research Methodology
Coverage spans Texas, California, PJM Interconnection territory, and the Southeast, with primary inputs from each region combining structured interviews with utility planning officers, EPC contractors, industrial maintenance directors, and electrical distributor procurement leads alongside secondary validation from FERC filings, EIA power plant databases, IEEE standards documentation, and SEC 10-K equipment supplier disclosures. Bottom-up project pipeline aggregation and top-down utility capital expenditure triangulation anchor market sizing.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include voltage rating tier, interruption technology, installation environment, connectivity architecture, and end-user capital intensity category. CAGRs derive from utility interconnection queue velocity, data center power demand forecasts, and renewable buildout commitments. Industry-specific inputs incorporate EPA SF6 regulatory timeline scenarios and Inflation Reduction Act domestic content credit eligibility thresholds.
Underlying measurement precision varies by segment; utility-scale procurement carries tighter precision than commercial building retrofits due to visible interconnection queue data. Forecasts reflect documented assumptions regarding FERC rulemaking timelines, copper price trajectory, and engineering labor availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Paralleling Switchgear Market
Switches
India Reed Sensors Switches Market
Switches
Australia Switchgear Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Optical Cross Connect (OXC) Switches Market
Switches
In-Wall Smart Switch Market
Switches
Global Light Control Switches Market
Switches
Push Button Dropper Market
Switches
UK Reed Sensors Switches Market
Switches
Residual Current Circuit Breaker Market
Switches
United States Circuit Breaker Market
Switches
Pressure Switch Market
Switches
Electric Switch Market
Switches
Outdoor Boundary Vacuum Load Switch Market
Switches
North America Switchgear Market
Switches
North America Medium Voltage Switchgear Market