
 Digitalization in Bpo Market | 2026-2036
Digitalization in Bpo Market Size, Share, and Industry Trends Forecast 2026-2036
Digitalization in Bpo Market Analysis
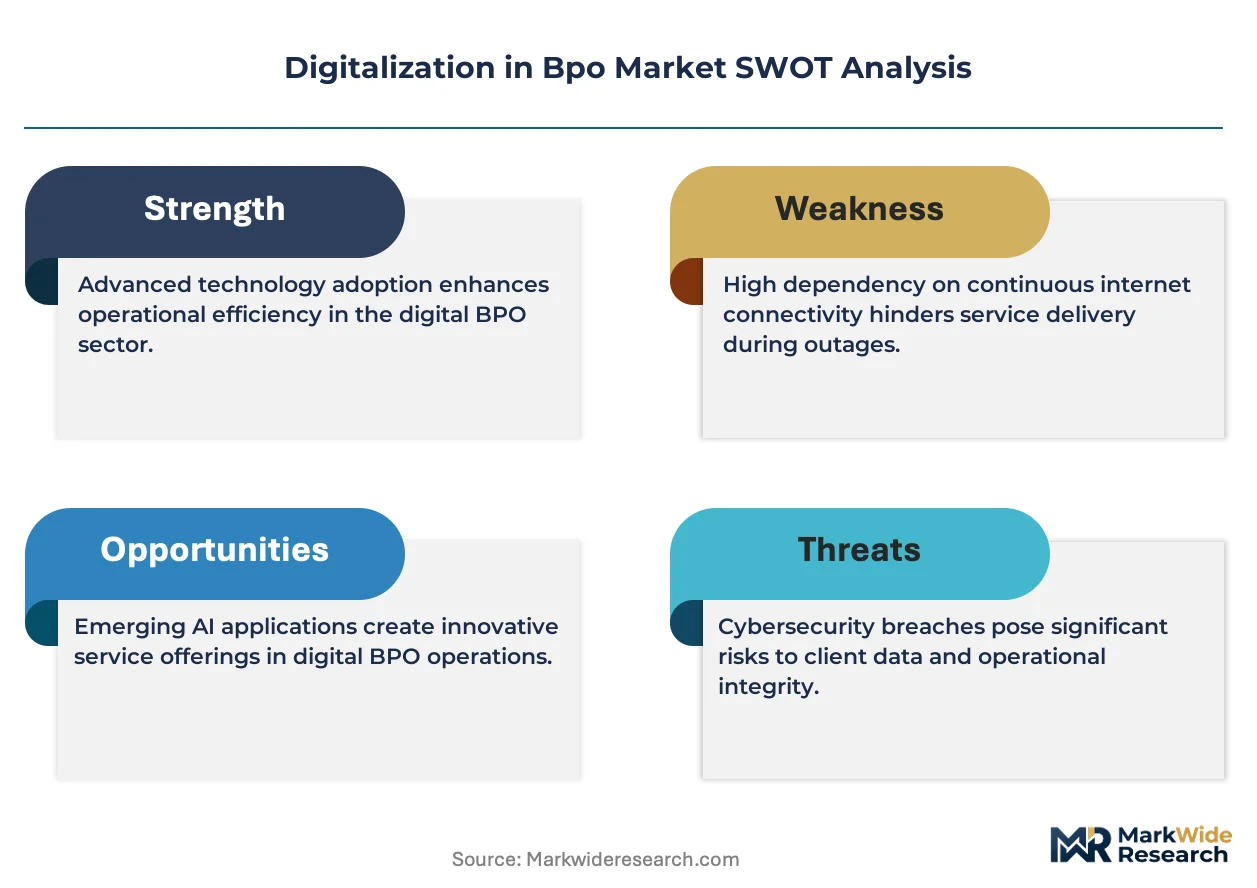
Healthcare is rebalancing the end-use mix as providers outsource patient data management and claims adjudication to specialized operators. UiPath dominates robotic process automation deployment across these workflows. Tata Consultancy Services anchors large-scale cloud migration programs for hospital networks. Cognizant differentiates through healthcare-specific compliance frameworks that reduce client audit risk.
Digitalization in BPO refers to the integration of artificial intelligence, cloud infrastructure, and automated workflow tools into outsourced business processes, typically operating through API-connected platforms that process structured and unstructured data at sub-second latency. Its primary purpose is to reduce unit processing costs while enabling real-time scalability for transactional and knowledge-intensive functions. Cloud-based deployment leads in new contract value as enterprises prioritize elastic capacity over fixed infrastructure. AI-enabled service tiers capture expanding margin pools as clients pay premiums for cognitive automation beyond basic rules-based processing. Hybrid deployment models sustain relevance in finance and healthcare where data residency requirements fragment cloud strategies.
HIPAA governs protected health information handling for US healthcare BPO contracts, while the EU AI Act imposes risk-classification obligations on automated decision systems serving European clients. India's TRAI and data localization guidelines from the Ministry of Electronics and Information Technology shape cross-border service delivery architecture. Stakeholders must monitor how divergent AI transparency requirements across jurisdictions fragment platform standardization and inflate compliance architecture costs.
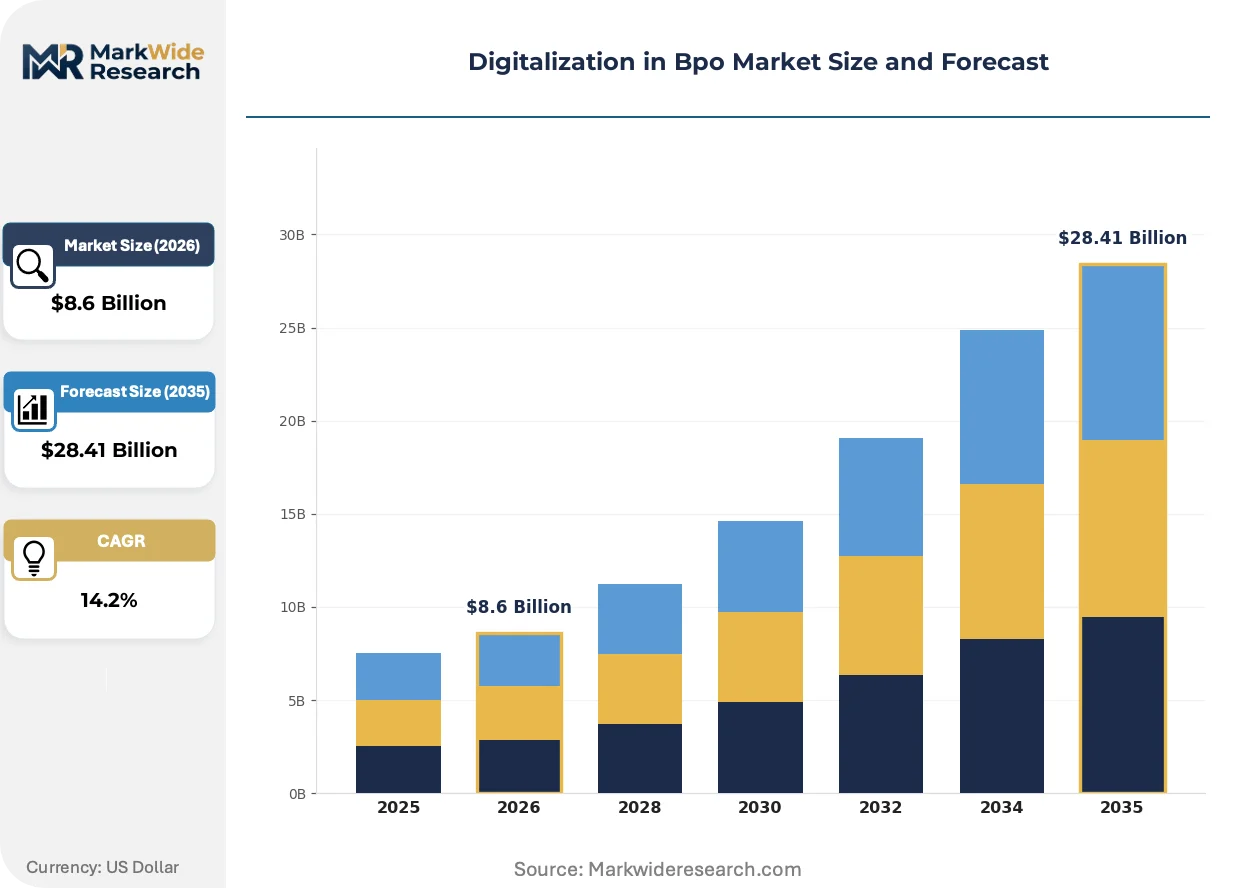
Market Dynamics
Healthcare providers are accelerating cloud migration mandates from HIPAA and the EU AI Act, forcing BPO operators to rebuild service architectures around compliance-driven automation rather than cost arbitrage alone.
Growth Catalysts
- HIPAA Cloud Mandates:US healthcare networks must migrate patient data to compliant cloud environments, creating sustained demand for specialized BPO migration services.
- India's Service Center Concentration:Bengaluru and Hyderabad anchor global delivery capacity with deep talent pools in healthcare claims processing and AI-enabled workflow automation.
- EU AI Act Risk Classification:Automated decision systems serving European clients now face binding transparency obligations, expanding the addressable market for compliance-architecture outsourcing.
Market Restraints
- Data Residency Fragmentation:Divergent localization requirements across India, the EU, and the US force BPO platforms to maintain redundant infrastructure, inflating fixed costs.
- AI Talent Scarcity:Shortage of engineers skilled in both healthcare domain knowledge and machine learning operations limits scaling velocity for cognitive automation tiers.
- Legacy System Entrenchment:Hospital networks and insurers maintain decades-old claims databases that resist API integration, extending implementation timelines.
Strategic Opportunities
- Underpenetrated European Healthcare:NHS trusts and German hospital networks lag US peers in claims automation, presenting first-mover expansion potential.
- Real-Time Payment Integrity:Convergence of AI anomaly detection with blockchain audit trails enables new service lines in pre-payment claims validation.
- India's PLI Scheme for IT:Production-linked incentives for software exports reduce effective tax burdens for BPO operators expanding domestic delivery capacity.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:Achieving concurrent HIPAA, GDPR, and ISO 27001 accreditation extends sales cycles by 8-14 months for new healthcare contracts.
- Legacy Middleware Integration:Connecting modern AI orchestration layers to mainframe-based hospital information systems demands scarce mainframe-to-cloud engineering expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digitalization in Bpo Market |
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $28.41 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Call Center, Technical Support, Data Entry, Customer Care Technology: AI, Cloud Solutions, Automation Tools, Data Analytics End User: Telecom, Retail, Healthcare, Finance Deployment Model: On-Premises, Cloud-Based, Hybrid, Outsourced |
| Companies Covered | UiPath, Blue Prism, Automation Anywhere, Accenture, Tata Consultancy Services, Wipro, Cognizant, Genpact, Teleperformance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digitalization in Bpo Market Emerging Trajectories
Agentic AI architectures are replacing rules-based automation, enabling BPO platforms to handle exception-heavy workflows without human escalation while compressing unit economics for knowledge-intensive processes.
Agentic workflow systems are decentralizing decision authority from centralized operations centers to edge-based AI nodes that handle complex claims adjudication. Mid-tier health insurers in the US Midwest are deploying these systems for pre-authorization reviews. This architecture is decentralizing the traditional hub-and-spoke delivery model that concentrated talent in India and the Philippines.
The EU AI Act's risk-tiering framework is forcing BPO providers to maintain separate model governance documentation for high-risk automated decision systems. Providers serving European healthcare clients must now implement human-in-the-loop protocols for denial-of-coverage determinations. German statutory health insurers are responding by bifurcating procurement between high-risk and limited-risk automation tiers.
Hospital procurement departments are unbundling after-sales implementation support from core BPO contracts, treating system integration as a separate competitive bid. This fragmentation is compressing margins for traditional full-service providers while creating openings for specialized healthcare IT consultancies. The pattern is most pronounced in US integrated delivery networks consolidating vendor relationships under centralized supply chain offices.
Digitalization in Bpo Market Segmentation
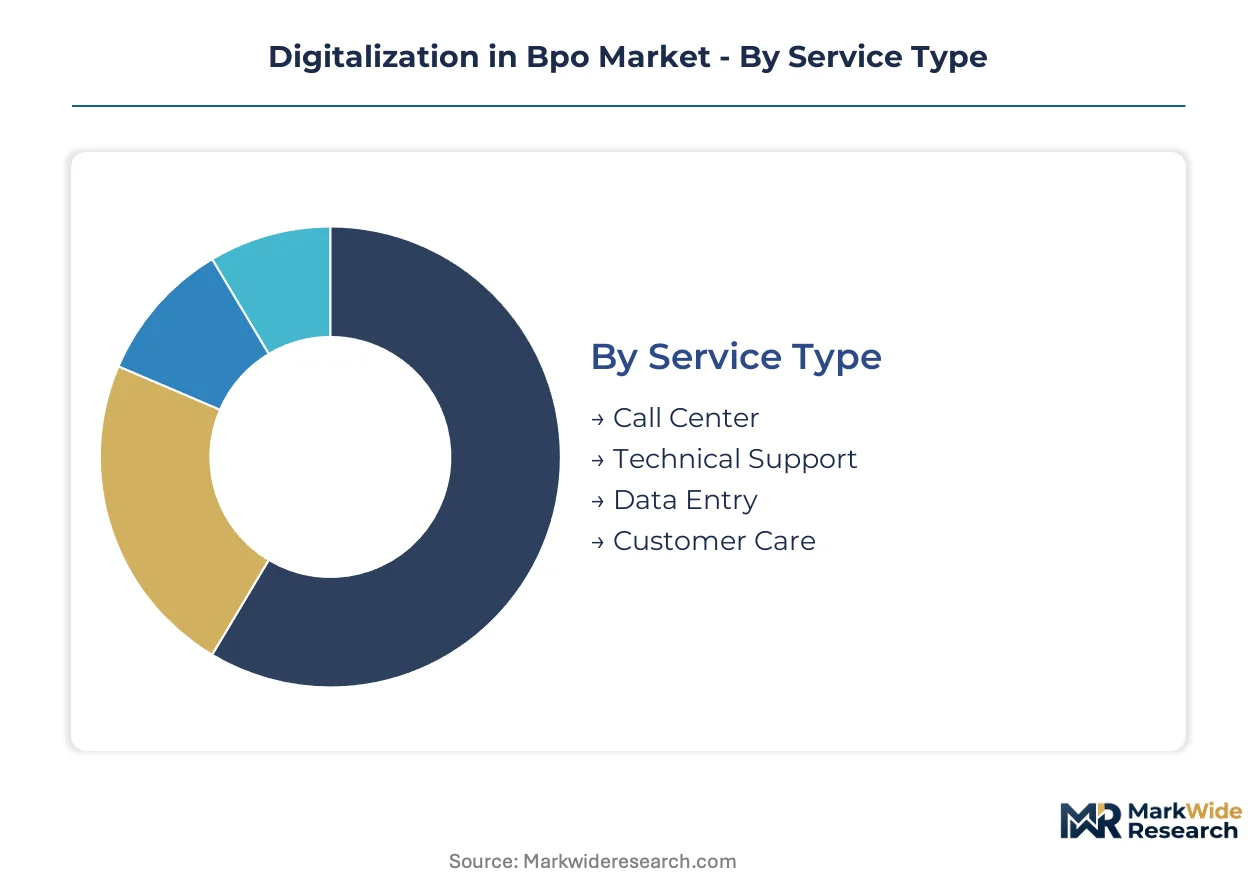
Service delivery models in digital BPO are fragmenting as legacy contracts expire and healthcare networks rebuild around HIPAA-mandated cloud architectures. Procurement officers now unbundle implementation from core processing, forcing providers to reposition across distinct capability tiers rather than geography alone.
Service Type:
Upgrade cycles for contact center infrastructure are compressing from seven-year horizons to three-year refreshes as AI-enabled voice agents displace legacy IVR systems.
- Call Center:Omnichannel platforms integrate voice, chat, and email through unified agent desktops with real-time sentiment analysis. US health insurers concentrate demand here for member enrollment surges during open periods.
- Technical Support:L1-L3 escalation hierarchies are collapsing into AI-first resolution layers with human agents handling only exception workflows. Enterprise software vendors in India deploy these tiers for SAP and Oracle ecosystem support.
- Data Entry:OCR-to-API pipelines now process structured form capture without manual keystroke verification.
- Customer Care:Retention-focused engagement models blend predictive churn scoring with proactive outreach automation.
Volume placements concentrate in Call Center; the faster expansion belongs to Technical Support.
Technology:
Cost stratification across technology tiers separates commodity automation from premium cognitive services.
- AI:Large language models power document understanding and exception handling for claims adjudication. EU AI Act risk classifications are bifurcating procurement between high-risk and limited-risk automation tiers.
- Cloud Solutions:Elastic compute architectures replace fixed-capacity data centers. HIPAA Business Associate Agreements now mandate encrypted object storage with audit logging for US healthcare contracts.
- Automation Tools:RPA bots handle repetitive data reconciliation between incompatible ERP systems.
- Data Analytics:Descriptive dashboards are yielding to predictive models for patient readmission risk scoring.
Margin capture concentrates in AI; Cloud Solutions are climbing the fastest as compliance mandates accelerate migration timelines.
End User:
Application intensity varies sharply across verticals, with healthcare procurement cycles running 18-24 months against retail's 6-9 month horizons.
- Healthcare:Claims processing and prior authorization workflows demand specialized domain models trained on ICD-10 and CPT code structures. German statutory insurers lag US peers in automation penetration.
- Finance:KYC/AML document verification combines OCR with adverse media screening. Indian banks deploy these stacks for account opening surge capacity.
- Telecom:Subscriber provisioning and billing inquiry volumes scale with 5G rollout cycles.
- Retail:Seasonal demand spikes for order management drive elastic staffing models.
Contract value concentrates in Healthcare; Finance is gaining share fastest as regulatory scrutiny intensifies.
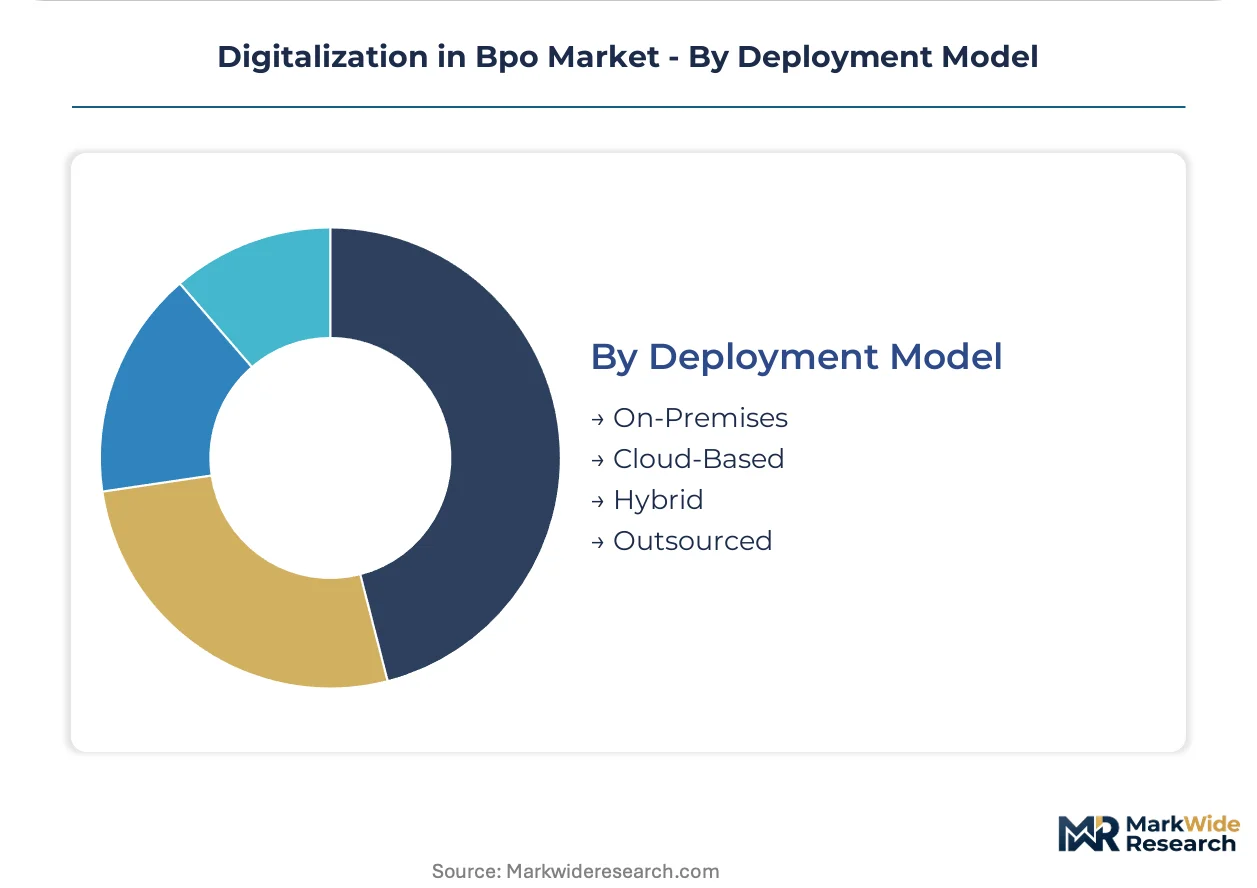
Deployment Model:
Customer type segmentation reveals divergent risk appetites: regulated industries favor control, while growth-stage firms prioritize speed.
- Cloud-Based:Multi-tenant platforms with API-first architecture enable sub-hour provisioning for claims processing spikes. India's MeitY data localization guidelines shape cross-border service delivery constraints.
- Hybrid:Sensitive data remains on-premises while compute-intensive AI inference shifts to cloud edge nodes. US hospital networks favor this architecture for patient data residency compliance.
- On-Premises:Air-gapped installations persist in defense and classified government contracts.
- Outsourced:Fully managed service delivery shifts operational risk to specialized operators.
New contract flow concentrates in Cloud-Based; Hybrid deployments show the steepest expansion trajectory as data residency requirements fragment cloud strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India (STPI) scheme and Special Economic Zones anchor global delivery capacity, concentrating talent pools for healthcare claims processing and AI-enabled workflow automation. Compliance mandates from HIPAA and the EU AI Act are redistributing contract flows toward jurisdictions with certified data infrastructure.
United States
Hospital networks and health insurers drive demand for HIPAA-compliant cloud migration and prior authorization automation. The Department of Health and Human Services enforces Business Associate Agreement requirements for outsourced patient data handling. Dallas and Phoenix service corridors expand capacity for seasonal enrollment surge processing.
India
Bengaluru and Hyderabad service centers process the majority of global healthcare claims adjudication volumes. TRAI data localization guidelines and MeitY cross-border data flow restrictions shape service delivery architecture. The PLI scheme for IT exports reduces effective tax burdens for operators expanding domestic capacity.
Germany
Statutory health insurers lag US peers in claims automation penetration, creating expansion potential for specialized BPO providers. The EU AI Act's risk-tiering framework imposes human-in-the-loop protocols for denial-of-coverage determinations. Frankfurt and Berlin clusters develop compliance-architecture expertise for high-risk automation tiers.
United Kingdom
NHS trusts accelerate procurement for patient data management outsourcing amid workforce constraints. GDPR and the EU AI Act (retained UK law) impose concurrent transparency obligations on automated decision systems. London health-tech corridors attract specialized operators for clinical documentation automation.
Philippines
Voice-centric contact center operations face margin pressure from AI-enabled voice agents displacing legacy IVR systems. The national data privacy regulator enforces alignment with GDPR-equivalent standards for European client contracts. Metro Manila and Cebu City clusters pivot toward technical support tiers for enterprise software ecosystems.
Digitalization in Bpo Market Vendor Landscape
Top-tier vendors anchor healthcare-specific compliance frameworks, while mid-tier operators compete on cost arbitrage for standardized contact center functions. The vendor base stratifies across three archetypes: global IT consultancies with vertical healthcare practices, pure-play automation software vendors, and specialized BPO operators with domain-specific talent pools. Dominant competitive moves include portfolio diversification into AI-enabled service tiers and geographic expansion into underpenetrated European healthcare markets.
Within the automation software tier, UiPath and Blue Prism exemplify platform vendors that supply robotic process automation infrastructure to BPO operators and enterprise clients directly. Tata Consultancy Services anchors the global IT consultancy archetype with large-scale cloud migration programs for hospital networks. Among specialized BPO operators, Cognizant and Genpact occupy positions that bridge compliance-architecture expertise with healthcare domain knowledge.
| Leading Market Players |
|---|
| UiPath |
| Blue Prism |
| Automation Anywhere |
| Accenture |
| Tata Consultancy Services |
| Wipro |
| Cognizant |
| Genpact |
| Teleperformance |
| Others |
Supply Flow & Price Mechanics
HIPAA-mandated cloud migration timelines from US hospital networks are compressing procurement cycles and forcing BPO providers to absorb upfront certification costs, which then recoup through premium-tier pricing for compliant service tiers. This demand-side pressure reshapes how supply capacity allocates across certified versus standard infrastructure pools.
Pricing Analysis
Lead-time-driven pricing stratification dominates contract negotiations, with premium rates attaching to sub-90-day HIPAA compliance certification and discounted spot pricing for non-healthcare transactional volumes. Three-tier pricing structure across premium compliance-certified, standard cloud-enabled, and economy onshore-reserved tiers separates buyer segments by audit risk tolerance. Cost compression in the economy tier is intensifying because AI-enabled voice agents displace legacy contact center seats in the Philippines. Price-sensitive mid-market health insurers drive hardest bargain pressure, while integrated delivery networks with centralized procurement show lowest elasticity.
Supply Chain Analysis
Certification gating through concurrent HIPAA, GDPR, and ISO 27001 accreditation requirements fragments supplier eligibility and concentrates viable capacity among tier-one operators with dedicated compliance architecture teams. Supply concentrates in India, the United States, and Germany, with Bengaluru and Hyderabad anchoring global delivery for healthcare claims processing. Talent pipelines draw from computer science institutes, healthcare administration programs, and mainframe-to-cloud engineering retraining initiatives. Single-source vulnerability runs through India's TRAI data localization enforcement, which threatens cross-border service continuity. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for legacy middleware integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digitalization in BPO Market sits in a technology-transition phase as agentic AI architectures replace rules-based automation, compressing unit economics for knowledge-intensive workflows while elevating compliance architecture to primary competitive differentiator.
For Market Incumbents: Lock in healthcare network relationships through embedded compliance teams that co-locate with hospital procurement offices, reducing competitive bid exposure. Deepen backward integration into AI model training infrastructure to capture margin pools from document understanding tiers rather than ceding them to pure-play software vendors. Defend against mid-tier automation vendors by accelerating human-in-the-loop protocol certification for EU AI Act high-risk tiers before competitors complete accreditation. For New Entrants and Emerging Players: Enter via German statutory health insurer segments where claims automation penetration lags US peers by several procurement cycles, creating first-mover expansion potential. Target NHS trusts in the United Kingdom facing workforce constraints and accelerating patient data management outsourcing timelines. Lead with specialized healthcare IT consultancy positioning that unbundles implementation support from core processing contracts, capturing margin compression from traditional full-service providers. For Investors and Strategic Acquirers: The window for entry favors specialized BPO operators with healthcare domain knowledge and concurrent multi-jurisdictional certification rather than generalist contact center platforms. Long-term viability hinges on compliance architecture depth as regulatory fragmentation intensifies across HIPAA, GDPR, and EU AI Act jurisdictions. Watch for inflection signals in hospital procurement department unbundling patterns, where separation of after-sales implementation from core contracts indicates structural margin redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Architecture Certification | Concurrent HIPAA and EU AI Act accreditation reduces sales cycles and audit risk for healthcare contracts. |
| Agentic AI Platform Development | Decentralized decision authority compresses unit economics for exception-heavy claims adjudication workflows. |
| Healthcare Domain Talent Acquisition | Deep pools in ICD-10 and CPT code structures differentiate service tiers from commodity automation vendors. |
| Hybrid Cloud Infrastructure Deployment | Edge-based AI nodes with on-premises data residency satisfy fragmented regulatory requirements across jurisdictions. |
| European Market Expansion | Underpenetrated German statutory insurers and NHS trusts present first-mover advantage for specialized operators. |
Methodological Framework
Regulatory filing databases, hospital procurement contract registries, and BPO operator disclosure documents formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with healthcare IT procurement officers, compliance architecture leads, hospital supply chain directors, and BPO service delivery executives validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled segment-level contract values with aggregate market estimates across service type, technology tier, and deployment model dimensions.
Bottom-up modeling aggregated individual contract values by segment, while top-down validation cross-checked against macro healthcare outsourcing expenditure trends across the analysis window. Segmentation dimensions included service delivery model, technology tier, end-use vertical, and deployment architecture, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from fitted growth curves calibrated to disclosed contract renewal rates and migration timeline assumptions. Forecast inputs incorporated HIPAA cloud mandate enforcement schedules and EU AI Act implementation phase transitions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated data localization enforcement or abrupt legacy system replacement mandates. Projections reflect assumptions about procurement cycle durations, certification timeline elasticity, and talent pipeline expansion rates. A model refresh is warranted upon material change in multi-jurisdictional regulatory alignment or hospital network consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
Contract Management Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market