
 Technical Support Outsourcing Market | 2026-2036
Technical Support Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
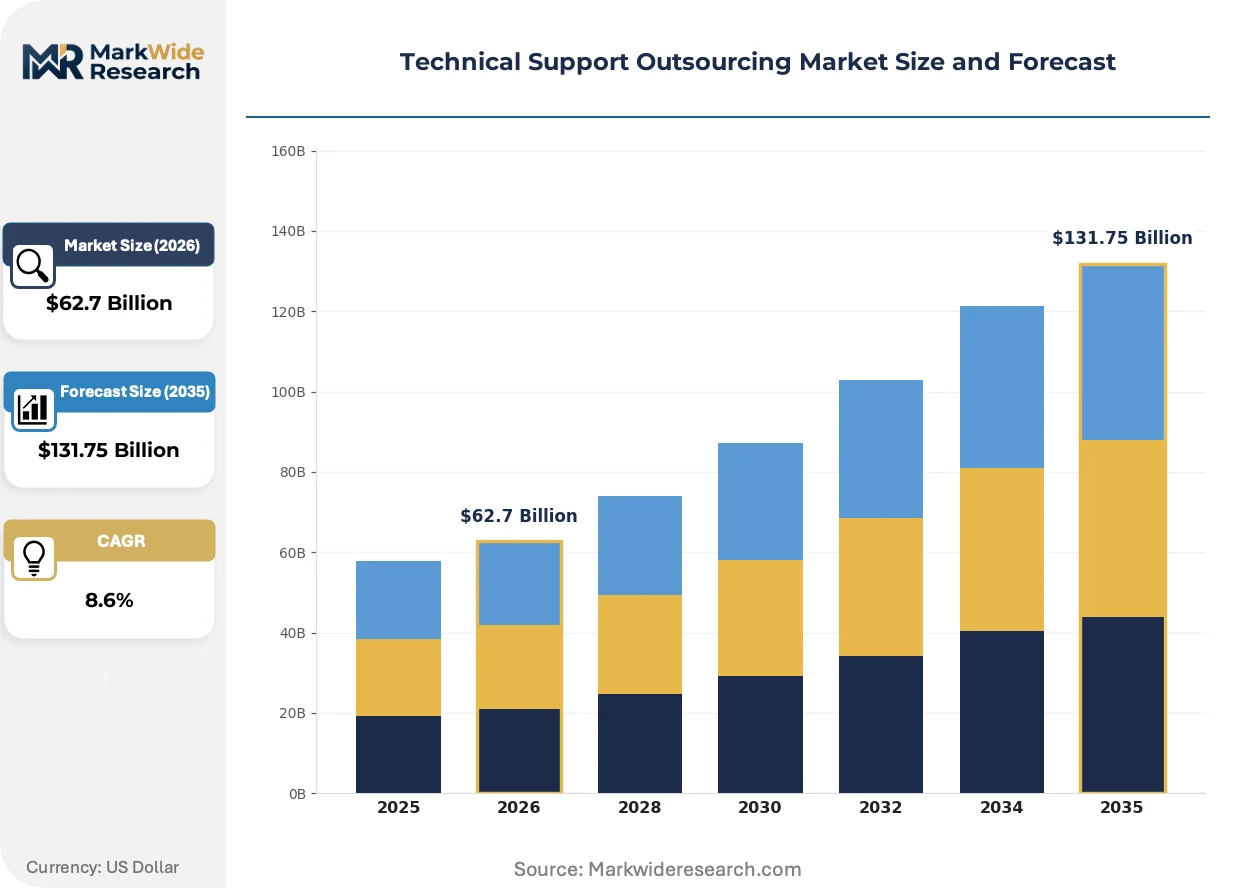
Technical Support Outsourcing Market Outlook
SaaS and cloud infrastructure vertical is shifting toward outcome-based support contracts with embedded uptime guarantees. IBM leverages its hybrid cloud consulting footprint to anchor enterprise technical support engagements across North America and Europe. Tata Consultancy Services sustains delivery scale through captive centers in Chennai and Pune that specialize in L2 and L3 technical resolution. Infosys differentiates through AI-integrated support platforms that reduce mean-time-to-resolution for software vendors.
Technical support outsourcing encompasses the delegation of end-user troubleshooting, system maintenance, and incident resolution to third-party providers operating through remote diagnostics, ticketing workflows, and field dispatch protocols. Its primary commercial purpose is to convert fixed IT labor costs into variable service expenditures while preserving service-level agreements. Help desk services occupy the largest revenue pool within service type segmentation due to universal applicability across end-user segments. AI Support and multi-channel platforms represent the fastest-expanding technology category as vendors embed predictive routing and natural language processing into standard delivery. Dedicated teams retain margin concentration in the delivery model dimension because long-term contracts enable workforce optimization and knowledge retention.
FCC guidelines on consumer protection in telecommunications shape how US-based telecom providers structure outsourced support escalation paths. GDPR and the EU AI Act constrain how European enterprises deploy automated decision-making in customer-facing technical channels, creating compliance overhead for delivery centers. India's TRAI quality-of-service mandates and data localization expectations from the central bank affect offshore support architecture for financial services clients. Stakeholders must monitor regulatory divergence between data privacy regimes and AI disclosure requirements as they select vendor geography and technology stack.
Market Dynamics
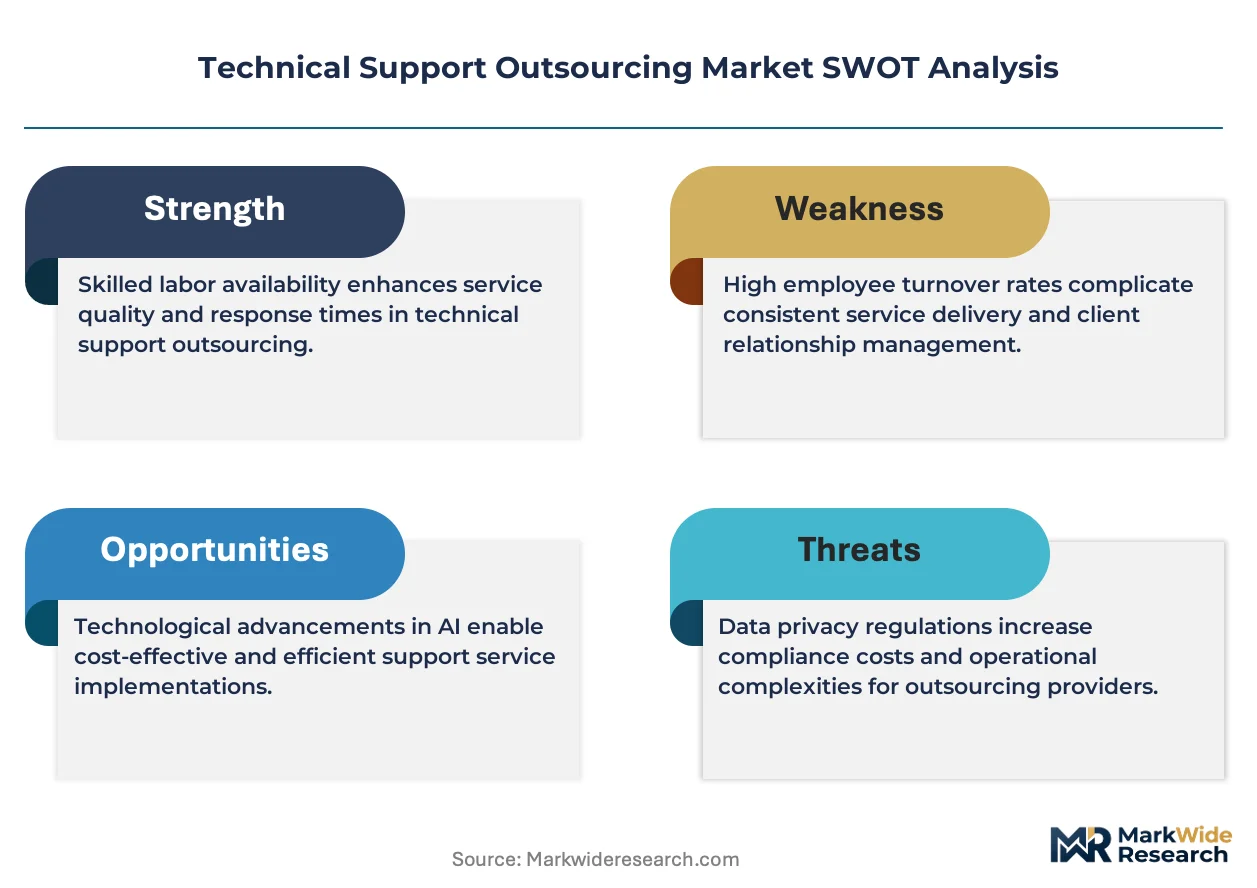
AI-enabled service tiers are compressing traditional staffing pyramids as cloud software vendors demand predictive resolution capabilities that reduce human touchpoints. This structural shift forces providers to retrain workforces toward exception handling while embedding machine learning into standard ticketing workflows.
Growth Catalysts
- India's NASSCOM certification framework:Elevated qualification standards filter low-capability vendors, concentrating demand among certified providers with proven L2/L3 resolution depth. Quality assurance mandates from this body accelerate buyer confidence in offshore delivery.
- SaaS uptime guarantee clauses:Cloud infrastructure vendors embed SLA penalties into contracts, driving procurement of dedicated technical support teams with embedded escalation protocols. This contractual structure converts variable support needs into long-term revenue commitments.
- Natural language processing integration:Predictive routing engines reduce first-response latency by classifying incident severity before human agent assignment. Vendors deploying this capability capture premium pricing from software vendors seeking competitive differentiation.
Market Restraints
- GDPR Article 22 constraints:Automated decision-making limitations in customer-facing channels create compliance overhead for European delivery centers, forcing hybrid human-AI architectures that dilute cost advantages.
- Philippine voice talent concentration:Geographic clustering of English-language support capabilities creates single-point vulnerability during climate disruptions or infrastructure failures, elevating business continuity premiums.
- Legacy system integration friction:Enterprise clients maintain decades-old ticketing platforms that resist API-based connectivity, extending deployment timelines and inflating customization costs for providers.
Strategic Opportunities
- Polish multilingual hubs:Underpenetrated relative to India and Philippines, Poland offers German-French-English trilingual capabilities for technical tiers serving EU financial services clients seeking nearshore alternatives.
- EU AI Act disclosure mandates:Regulatory requirements for transparent automated decision-making create consulting attach opportunities, positioning technical support providers as compliance implementation partners rather than pure cost arbitrageurs.
- Edge computing diagnostics convergence:Remote troubleshooting platforms integrating IoT telemetry streams enable predictive field dispatch before end-user failure reports, opening subscription revenue models beyond per-incident pricing.
Industry Challenges
- L3 engineering talent scarcity:Deep system architecture expertise required for cloud infrastructure troubleshooting concentrates in Bangalore and Hyderabad, forcing wage inflation and retention battles among captive centers.
- ISO 27001 certification timelines:Information security management system audits extend 9-14 months for new delivery centers, delaying market entry for providers targeting financial services verticals with mandatory compliance requirements.
- Knowledge retention protocols:High agent churn in voice support tiers erodes resolution accuracy for complex software products, necessitating expensive documentation systems and mentorship structures that compress margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Support Outsourcing Market |
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $131.75 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Help Desk, Remote Support, On-site Support, Technical Training Delivery Model: Dedicated Teams, Managed Services, Project-based, Time & Materials End User: SMEs, Enterprises, Telecom Providers, Software Vendors Technology: AI Support, Chatbots, CRM Integration, Multi-channel Platforms |
| Companies Covered | Accenture, IBM, Infosys, Tata Consultancy Services, HCL Technologies, Peak Support, SupportYourApp, Qualfon, 1840 & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Support Outsourcing Market Strategic Shifts
Generative AI capabilities are restructuring how technical support providers architect workforce deployment, compressing routine diagnostic layers while elevating human agents toward exception complexity. This transformation demands concurrent investment in training infrastructure and platform engineering.
Conversational AI platforms are converging with enterprise ticketing systems to enable autonomous resolution of password resets, license provisioning, and basic configuration errors. Mid-market SaaS vendors adopt these capabilities fastest, deploying them across 60-70% of tier-1 incident volumes within eighteen months of implementation. The technology is converging with workforce analytics to dynamically route exceptions based on agent specialization depth, reducing mean-time-to-resolution for software vendors by eliminating queue-bouncing.
GDPR and the EU AI Act jointly constrain automated decision-making in customer-facing technical channels, requiring human oversight loops for incident classification affecting service eligibility. European enterprises respond by bifurcating delivery architecture: AI-first triage for standard issues, mandatory human review for account-sensitive escalations. Financial services and healthcare verticals absorb the highest compliance overhead, passing costs through to end-user pricing.
Software vendors now unbundle after-sales support from license fees, shifting toward consumption-based pricing tied to actual ticket volume and resolution complexity. This procurement evolution pressures providers to offer granular service tiering—self-service portals, chatbot-assisted, and white-glove engineering—rather than flat-rate unlimited support. The shift is most visible among cloud-native application vendors in North America, where product-led growth models demand support costs scale with user acquisition rather than contract value.
Technical Support Outsourcing Market Segmentation
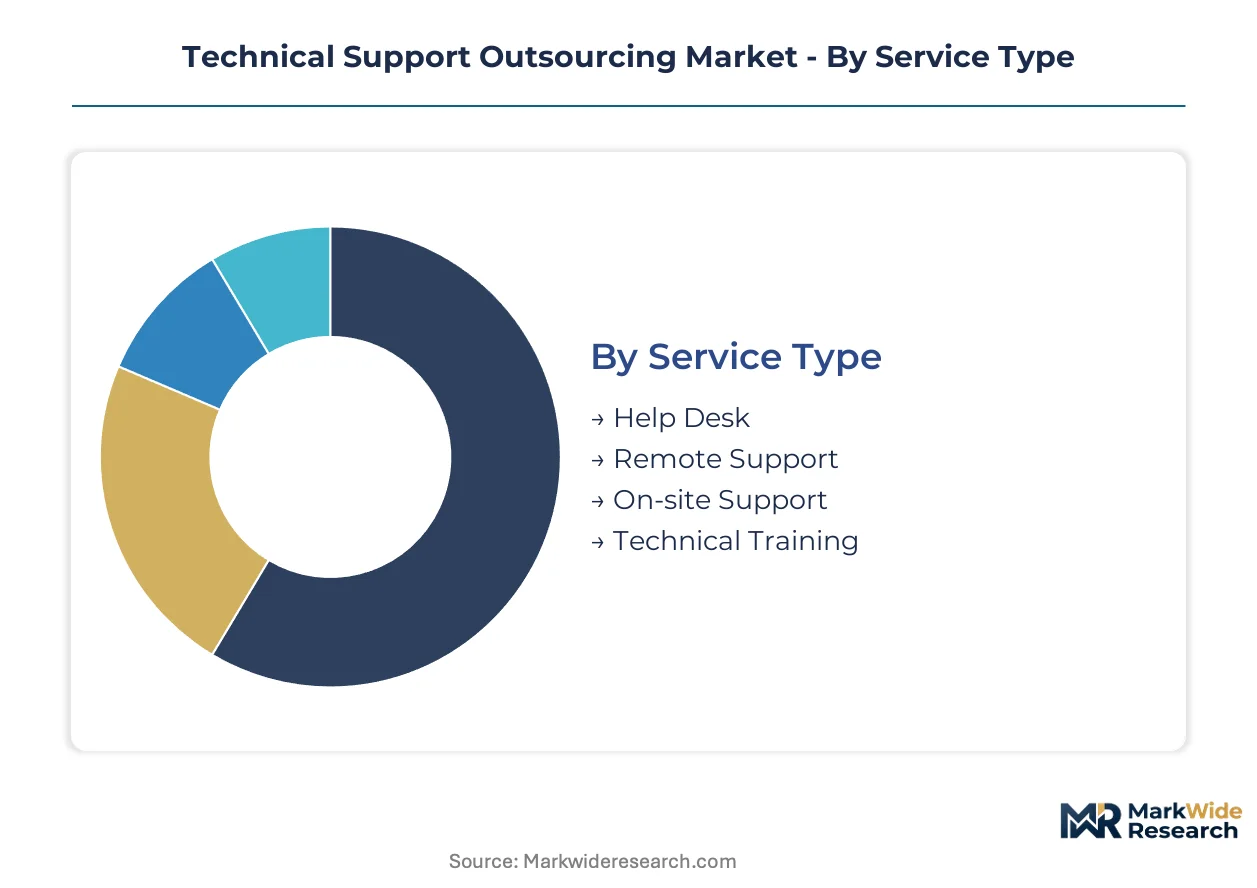
Technical support outsourcing segments reveal distinct margin architectures and capability requirements. Procurement patterns diverge sharply between standardized help desk tiers and embedded engineering support, with technology integration depth serving as the primary segmentation axis.
Service Type:
Help desk operations function as standalone service layers with minimal client system integration, while remote and on-site support embed deeper into customer infrastructure workflows.
- Help Desk:Frontline incident intake and basic troubleshooting through voice, chat, and email channels. Demand concentrates among software vendors in India and the Philippines seeking cost-optimized tier-1 coverage. NASSCOM certification requirements filter vendor pools toward providers with documented quality frameworks.
- Remote Support:Diagnostics and resolution delivered through remote desktop protocols and system administration tools. Cloud infrastructure vendors in North America drive procurement here, embedding SLA penalties that demand predictive resolution capabilities.
- On-site Support:Field dispatch for hardware failures and physical infrastructure maintenance. Enterprise manufacturing clients in Germany and Mexico utilize this tier for critical system uptime guarantees.
- Technical Training:Knowledge transfer and certification programs for end-user staff. Software vendors deploy this segment to reduce recurring ticket volumes through self-service enablement.
Volume placements concentrate in Help Desk; the faster expansion belongs to Remote Support.
Delivery Model:
Cost tier differentiation separates dedicated workforce commitments from variable expenditure structures, reshaping how buyers align support spend with revenue predictability.
- Dedicated Teams:Exclusive staffing assigned to single client accounts with embedded escalation protocols. SaaS vendors in the United States favor this model for uptime guarantee compliance, accepting premium pricing for workforce retention.
- Managed Services:Outcome-based contracts with defined SLA metrics and penalty structures. European financial services clients in Poland and Ireland adopt this tier to satisfy GDPR accountability requirements.
- Project-based:Scoped engagements for system migrations, upgrades, or product launches. Telecom providers leverage this model for 5G rollout support windows with defined endpoints.
- Time & Materials:Variable billing tied to actual agent hours and resolution complexity. Mid-market enterprises prefer this flexibility for unpredictable incident volumes.
Margin concentration favors Dedicated Teams; Managed Services are climbing the fastest as outcome-based procurement spreads.
End User:
Application context determines resolution depth requirements, with enterprise complexity demanding L3 engineering capabilities that SMEs rarely utilize.
- SMEs:Small and medium enterprises with standardized software stacks and limited customization. These buyers prioritize chatbot-first triage and self-service portals to minimize per-incident costs.
- Enterprises:Large organizations with heterogeneous legacy systems and compliance mandates. Demand concentrates in captive centers across Bangalore and Hyderabad for deep system architecture expertise.
- Telecom Providers:Network operators with FCC-regulated escalation paths and consumer protection obligations. US-based carriers structure outsourced support to satisfy mandatory disclosure timelines.
- Software Vendors:Cloud-native and on-premise application publishers unbundling support from license fees. This segment drives consumption-based pricing adoption across North American product-led growth models.
Revenue scale centers on Enterprises; the steepest expansion trajectory belongs to Software Vendors.
Technology:
Maturity gradients separate established CRM integration from emerging AI capabilities, with deployment risk tolerance varying by buyer digital sophistication.
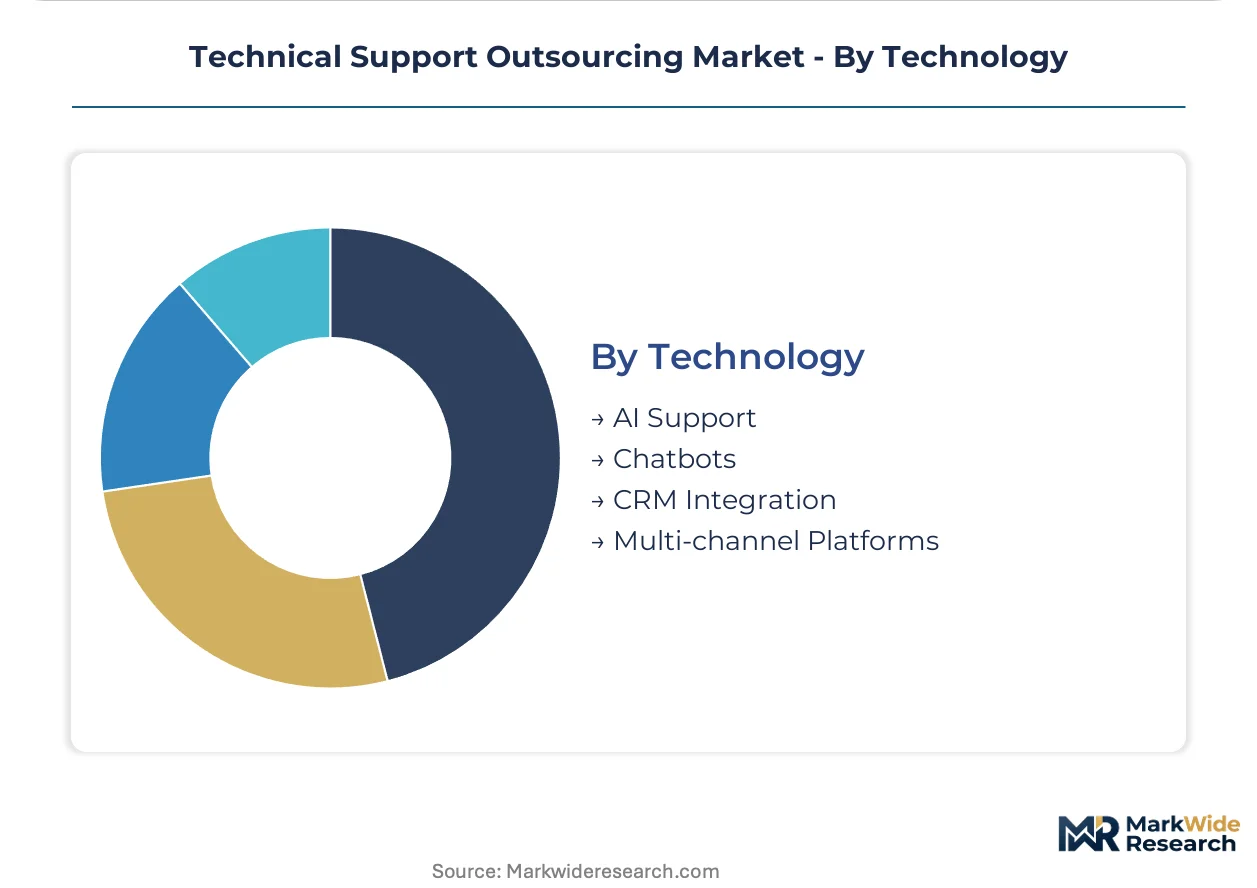
- AI Support:Predictive routing and automated classification engines reducing human touchpoints. GDPR Article 22 constraints in Europe force hybrid architectures that preserve human oversight loops.
- Chatbots:Conversational interfaces handling password resets, license provisioning, and basic configuration. Mid-market SaaS vendors achieve 60-70% tier-1 automation within eighteen months of deployment.
- CRM Integration:Ticketing system connectivity with Salesforce, ServiceNow, and proprietary platforms. Legacy system friction extends deployment timelines for enterprise clients maintaining decades-old infrastructure.
- Multi-channel Platforms:Unified voice, chat, email, and social media orchestration. These systems enable dynamic routing based on agent specialization depth, reducing mean-time-to-resolution.
Adoption velocity peaks with CRM Integration; AI Support is gaining share fastest as cloud software vendors demand predictive capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and the Philippines supply the majority of voice-centric technical support capacity, while demand concentrates among cloud software vendors in the United States, Germany, and the United Kingdom seeking L2 and L3 engineering resolution.
United States
SaaS vendors in Silicon Valley and Seattle drive procurement of dedicated technical support teams with embedded uptime guarantees. FCC guidelines on consumer protection in telecommunications shape escalation path architecture for domestic carriers. Delivery partnerships concentrate in Austin and Phoenix hubs serving enterprise clients with hybrid cloud infrastructure.
India
Captive centers in Bangalore and Hyderabad specialize in L3 system architecture troubleshooting for global cloud infrastructure vendors. TRAI quality-of-service mandates and RBI data localization expectations elevate compliance architecture for financial services delivery. Chennai and Pune house scaled operations for L2 technical resolution with NASSCOM-certified quality frameworks.
Germany
Enterprise manufacturing clients in Bavaria and Baden-Württemberg utilize on-site support tiers for critical system uptime commitments. GDPR Article 22 constraints on automated decision-making force hybrid human-AI architectures in customer-facing channels. Berlin hosts managed services providers serving EU financial services clients with outcome-based SLA structures.
Philippines
English-language voice support capabilities cluster in Metro Manila and Cebu City for tier-1 incident intake across North American software vendors. Geographic concentration creates single-point vulnerability during climate disruptions, elevating business continuity premiums. Providers maintain redundant capacity across Davao to mitigate infrastructure failure exposure.
Poland
Underpenetrated relative to Asian offshore hubs, Kraków and Warsaw offer German-French-English trilingual capabilities for technical tiers serving EU financial services. EU AI Act disclosure mandates for transparent automated decision-making create consulting attach opportunities. Nearshore positioning reduces latency for Frankfurt and Paris-based enterprise clients.
Technical Support Outsourcing Market Competitive Environment
Top-tier vendors anchor dedicated team engagements with SaaS uptime guarantees, while mid-scale specialists compete on AI-integrated platform differentiation. The market structures around three tiers: global consultancies with hybrid cloud footprints, offshore captives with NASSCOM-certified scale, and boutique providers with multilingual nearshore positioning. Strategic moves concentrate on workforce retraining for exception handling and predictive routing engine deployment.
Within the global consultancy tier, IBM leverages its hybrid cloud consulting footprint across North American and European enterprise engagements. Tata Consultancy Services sustains delivery scale through captive centers in Chennai and Pune. Infosys occupies a position exemplifying AI-integrated support platform differentiation that reduces mean-time-to-resolution metrics for software vendor clients.
| Leading Market Players |
|---|
| Accenture |
| IBM |
| Infosys |
| Tata Consultancy Services |
| HCL Technologies |
| Peak Support |
| SupportYourApp |
| Qualfon |
| 1840 & Company |
| Others |
Value Chain & Pricing Dynamics
GDPR Article 22 constraints on automated decision-making gate qualified supply for European delivery centers, forcing hybrid human-AI architectures that preserve premium-tier pricing access for compliant providers while filtering uncertified competitors from financial services procurement pools.
Pricing Analysis
Margin tightening in dedicated team engagements reflects NASSCOM certification premiums and SLA penalty embedding by SaaS vendors. Three-tier pricing structure across premium, standard, and economy levels separates uptime-guaranteed dedicated teams from variable managed services and project-based time-and-materials billing. Cost compression accelerates in voice support tiers as chatbot automation displaces tier-1 human touchpoints. SME buyers exhibit highest price sensitivity, while enterprise cloud infrastructure vendors absorb premiums for embedded L3 engineering.
Supply Chain Analysis
Workforce availability constraints in Bangalore and Hyderabad intensify wage competition for L3 system architecture talent among captive centers serving global cloud vendors. Supply concentrates in India for voice and L2 resolution, the Philippines for English-language tier-1 intake, and Poland for multilingual EU technical tiers. Delivery draws from cloud software talent pipelines, TRAI-mandated quality frameworks, and ISO 27001 certification infrastructure. Single-source vulnerability in Philippine voice clusters elevates business continuity premiums. Distribution runs through direct enterprise sales, channel partners, and platform-embedded service marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical support outsourcing sits in a technology-transition phase as generative AI displaces legacy ticketing workflows and restructures workforce deployment toward exception handling.
For Market Incumbents: Deepen captive center investments in Chennai and Pune to lock in NASSCOM-certified scale against emerging AI-native competitors. Anchor enterprise relationships through hybrid cloud consulting attach rates that embed uptime guarantees. Prioritize ISO 27001 certification maintenance to defend financial services vertical access against compliance-focused challengers.
For New Entrants and Emerging Players: Mid-market SaaS vendors with product-led growth models represent the most penetrable buyer archetype for AI-integrated support platforms. Poland-based trilingual hubs offer white-space positioning for EU financial services nearshore demand. Lead with consumption-based pricing tied to actual ticket volume rather than flat-rate unlimited support.
For Investors and Strategic Acquirers: NASSCOM certification attainment by mid-scale providers is the leading indicator that quality-filtered vendor consolidation is accelerating. Long-term viability centers on workforce retraining infrastructure and predictive routing engine ownership. Target acquisition profiles emphasize AI-integrated platform differentiation over pure cost arbitrage. Monitor EU AI Act disclosure mandate compliance costs as margin inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Routing Engine Deployment | Reduces mean-time-to-resolution for software vendors through AI-powered incident classification. |
| NASSCOM Certification Investment | Filters vendor pools toward quality-assured providers with documented L2/L3 resolution depth. |
| Hybrid Human-AI Architecture | Satisfies GDPR Article 22 constraints while preserving cost advantages in European delivery. |
| Polish Multilingual Hub Expansion | Captures EU financial services nearshore demand with German-French-English technical capabilities. |
| Consumption-Based Pricing Unbundling | Aligns support costs with product-led growth models through ticket-volume-linked contracts. |
Study Parameters
Document review covered SEC filings from publicly traded outsourcing providers, NASSCOM industry reports, and EU regulatory guidance documents, complemented by interviews with CTOs at North American SaaS vendors, IT procurement officers at European financial services firms, platform engineers at cloud infrastructure providers, and delivery center operations directors in India and the Philippines. Secondary validation drew from TRAI quality-of-service mandates, RBI data localization circulars, and GDPR implementation guidance. Bottom-up service tier sizing and top-down market aggregation were cross-referenced for triangulation.
Historical revenue trajectories were cross-referenced against panel input from delivery center operators and enterprise buyers to construct projection frameworks across the analysis window. Segmentation dimensions modeled include service type, delivery model, end-user category, technology integration depth, and geographic delivery cluster. CAGRs were derived from weighted average growth assumptions applied to segment-level baseline values. Forecast inputs incorporated AI adoption curves for tier-1 automation and NASSCOM certification penetration rates.
Revisions become necessary when regulatory divergence between data privacy regimes accelerates, AI disclosure mandates expand beyond EU jurisdictions, or Philippine infrastructure vulnerability triggers geographic supply reallocation. Forecasts reflect documented assumptions about workforce retraining timelines and platform integration friction. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
North America Business Process-As-A-Service (Bpaas) Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Global Document Outsourcing Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market