
 Desktop Outsourcing Market | 2026-2036
Desktop Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Desktop Outsourcing Market Analysis
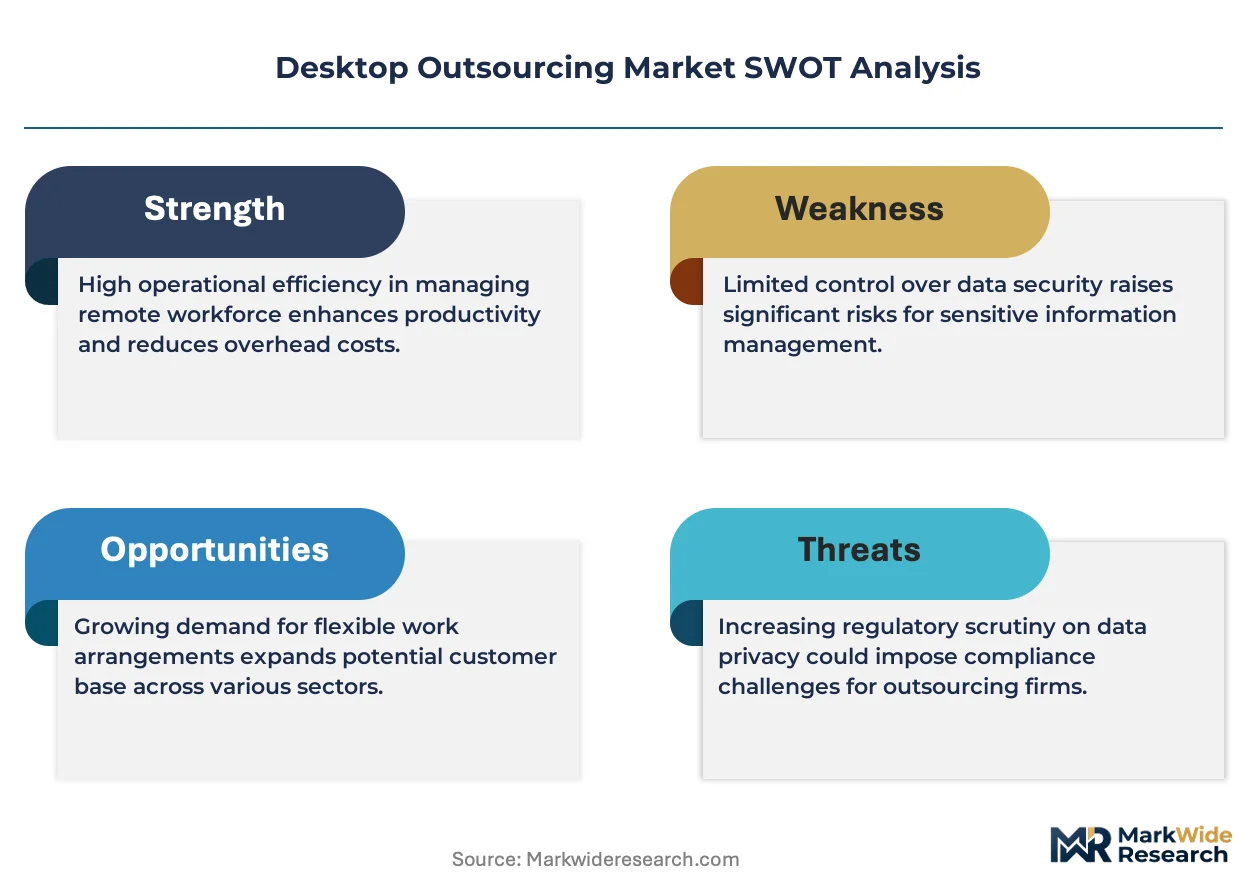
GDPR enforcement is rebalancing liability between European enterprises and their desktop outsourcing vendors, forcing contract renegotiations around data residency and breach accountability. IBM leverages its hybrid cloud infrastructure to anchor multi-year government desktop management contracts across Germany and France. Accenture sustains competitive positioning through AI-driven service desk automation that reduces mean-time-to-resolution for enterprise clients.
Desktop outsourcing encompasses the transfer of end-user computing operations—including device provisioning, patch management, security monitoring, and application support—to third-party specialists operating under defined service-level agreements with uptime thresholds typically exceeding 99.5%. The primary commercial purpose is converting capital-intensive IT asset ownership into predictable operational expenditure while accessing specialized technical talent. Help Desk Support and Remote Monitoring together dominate current revenue pools, though Desktop Virtualization is expanding fastest as enterprises consolidate physical hardware footprints. Cloud-Based deployment is displacing On-Premises arrangements among SMEs seeking elastic capacity, while Large Enterprises retain Hybrid configurations to satisfy legacy application constraints.
The EU AI Act, GDPR, and ISO 27001 collectively shape vendor selection criteria across European markets, with compliance certification now a mandatory gate for public sector RFP participation. India's BIS standards and SEZ regulations govern the export-oriented delivery centers where Wipro and Infosys process tickets for North American and European accounts. Stakeholders must weigh automation-driven labor displacement against the regulatory complexity of governing AI-augmented service desks before committing to long-term outsourcing architectures.
Market Dynamics
Financial services firms are converting fixed IT infrastructure costs into variable operational expenditure through multi-year desktop outsourcing contracts, accelerating vendor consolidation around providers with certified AI-augmented service desk capabilities.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises are renegotiating vendor contracts to embed algorithmic accountability clauses, expanding the addressable market for governance-certified providers.
- India's SEZ regulatory framework:Export-oriented delivery centers in Bangalore and Hyderabad process tickets for North American accounts under favorable tax treatment and BIS-aligned data security protocols.
- Desktop virtualization technology:Enterprises consolidate physical hardware footprints through centralized virtual desktop infrastructure, reducing endpoint management complexity and security exposure.
Market Restraints
- GDPR liability rebalancing:Data residency requirements and breach accountability clauses force European enterprises to absorb higher compliance costs or pay vendor premiums for localized infrastructure.
- Delivery concentration in Indian metros:Talent scarcity in Bangalore and Chennai drives wage inflation for L1-L2 support engineers, compressing margins for fixed-price contracts.
- Legacy application dependencies:Large enterprises retain hybrid configurations to satisfy mainframe and client-server constraints, slowing full cloud migration timelines.
Strategic Opportunities
- German public sector digitalization:Federal and state governments issue multi-year desktop management RFPs requiring ISO 27001 certification, creating a protected procurement channel.
- AI-driven predictive maintenance:Machine learning models analyzing endpoint telemetry enable shift from break-fix to preemptive intervention, improving SLA attainment and contract renewals.
- SME cloud-native adoption:Small and mid-sized enterprises bypass on-premises infrastructure entirely, accepting elastic capacity models previously unavailable to non-enterprise buyers.
Industry Challenges
- AI-augmented service desk governance:Enterprises must establish oversight frameworks for automated ticket classification and resolution without degrading end-user experience or accountability.
- Cross-border data routing complexity:Indian delivery centers processing European account data face operational friction from divergent GDPR and BIS implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desktop Outsourcing Market |
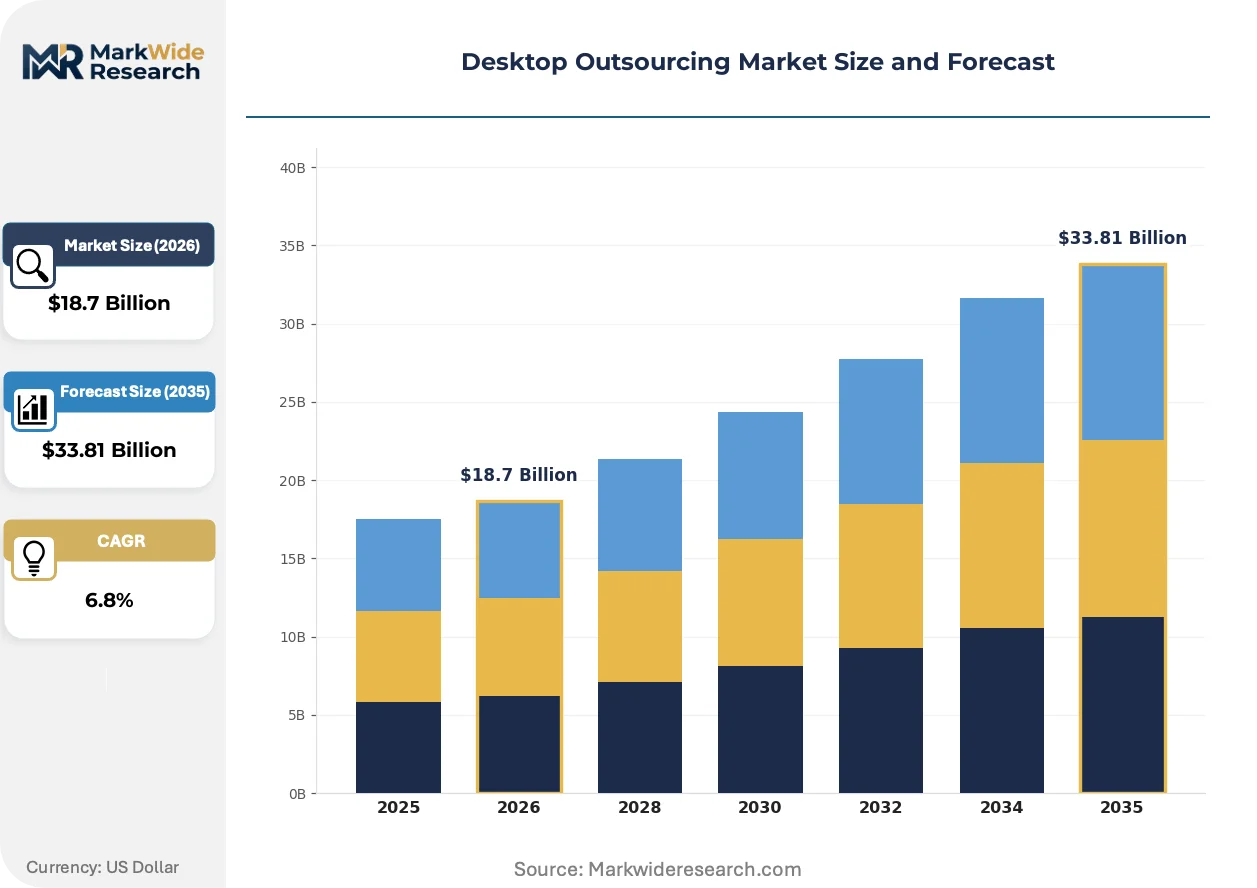
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Help Desk Support, Remote Monitoring, Desktop Virtualization, Application Management Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Technology: Remote Desktop Protocol, VPN, SaaS, AI-Driven Solutions |
| Companies Covered | IBM, HP Inc., Accenture, Cognizant, Wipro, Capgemini, Infosys, DXC Technology, TCS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desktop Outsourcing Market Emerging Trajectories
Automation is compressing mean-time-to-resolution while regulatory pressure is fragmenting vendor governance requirements across jurisdictions, forcing providers to architect modular compliance stacks.
Desktop virtualization is converging with zero-trust security architectures to enable secure remote access without VPN dependency. Financial services and healthcare buyers are deploying these stacks at enterprise scale. This convergence is collapsing the traditional boundary between endpoint management and network security procurement decisions.
The EU AI Act's risk classification framework is reclassifying automated service desk tools as high-risk when they influence access to essential services. Vendors must now maintain technical documentation and human oversight protocols for algorithmic decision systems. German and French public sector contracts now embed these requirements as mandatory evaluation criteria.
Enterprise buyers are unbundling after-sales support from hardware procurement, negotiating standalone desktop outsourcing agreements with specialized providers rather than OEM-anchored service contracts. This pattern is most pronounced among mid-market manufacturers in the Netherlands and Belgium seeking predictable opex structures. Channel partners are responding by repositioning as managed service aggregators rather than equipment resellers.
Desktop Outsourcing Market Segmentation
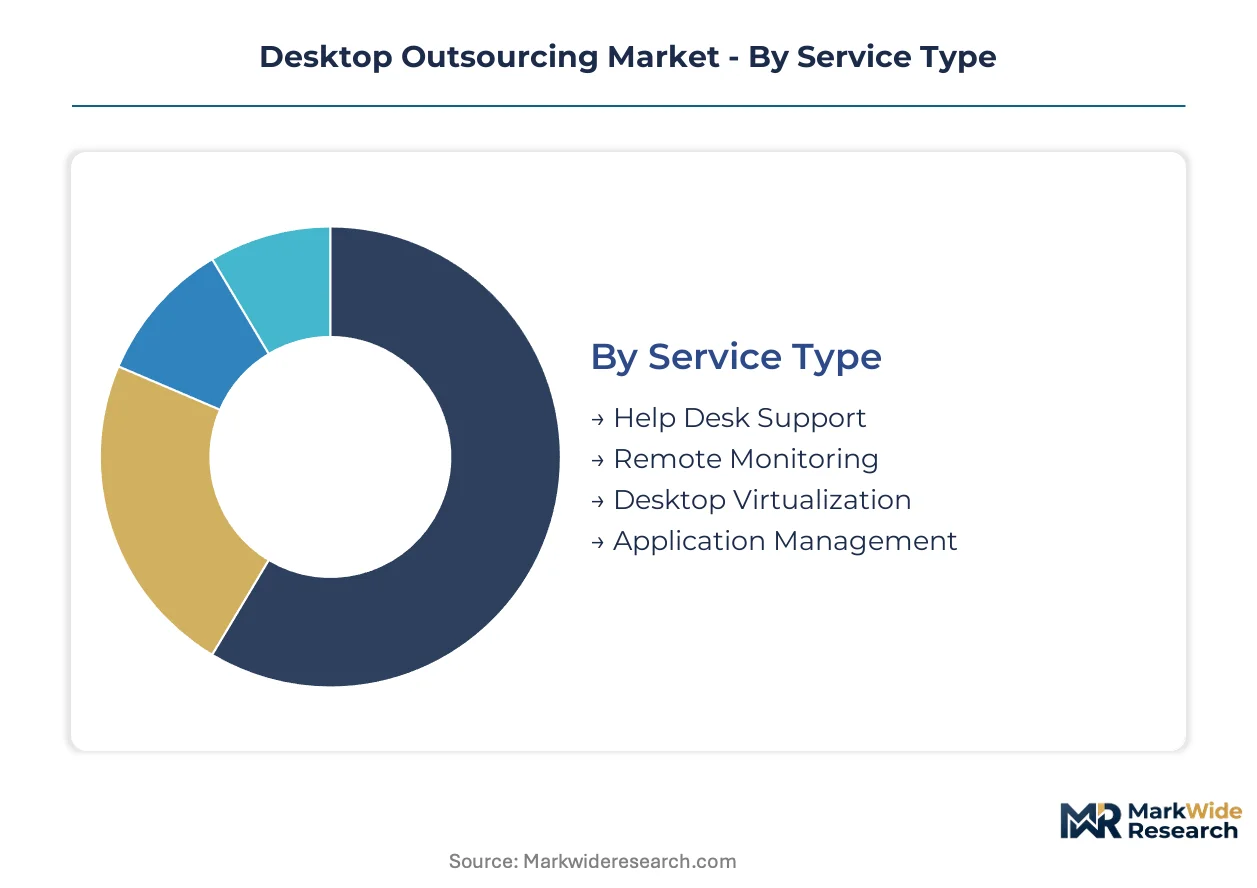
Desktop outsourcing procurement decisions hinge on matching service architecture to internal IT maturity, legacy constraints, and compliance exposure. Buyers segment opportunities across four dimensions that determine contract structure, pricing models, and vendor qualification thresholds.
Service Type:
Enterprises prioritize service mix based on internal headcount constraints and the criticality of endpoint uptime to revenue operations.
- Help Desk Support:Tiered incident resolution covering password resets, software troubleshooting, and hardware triage via phone, chat, or ticketing portals. Financial services firms in Frankfurt and Paris anchor multi-year contracts here, driven by trader workstation uptime requirements and GDPR-mandated breach response timelines.
- Remote Monitoring:Continuous endpoint telemetry collection enabling proactive patch deployment, security alert triage, and performance baseline enforcement. Manufacturing clusters in Stuttgart and Turin concentrate demand as shop-floor digitization multiplies managed device counts beyond internal IT capacity.
- Desktop Virtualization:Centralized VDI or DaaS delivery collapsing physical hardware footprints into thin-client or browser-based access.
- Application Management:Lifecycle support for productivity suites, line-of-business software, and custom enterprise applications.
Volume sits with Help Desk Support; growth tilts toward Desktop Virtualization.
Deployment:
Cost tier and data sovereignty requirements shape infrastructure location decisions across buyer segments.
- On-Premises:Dedicated infrastructure within client-controlled facilities satisfying air-gapped security mandates. Defense contractors and classified research facilities in Germany and France retain this model, constrained by national security regulations prohibiting cross-border data transit.
- Cloud-Based:Multi-tenant or dedicated cloud instances delivering elastic capacity without capital expenditure. Dutch and Belgian mid-market manufacturers bypass on-premises entirely, accepting opex models that align IT spend with production cycles.
- Hybrid:Split architecture preserving legacy mainframe or client-server dependencies while cloud-enabling modern workloads. Large German automotive suppliers deploy hybrid stacks to satisfy just-in-time production system constraints.
- Managed Services:Fully outsourced responsibility spanning infrastructure, operations, and service desk under outcome-based SLAs.
Revenue concentrates in Hybrid deployments; Cloud-Based configurations expand most quickly among SME entrants.
End User:
Organizational scale determines contract granularity, customization depth, and governance complexity.
- SMEs:Standardized service catalogs with limited customization and per-seat pricing. Benelux manufacturing SMEs drive uptake here, seeking predictable monthly expenditures without internal IT specialization.
- Large Enterprises:Bespoke multi-tower contracts integrating desktop outsourcing with broader infrastructure transformation. German automotive and chemical conglomerates anchor this segment with thousand-seat minimums and ISO 27001 certification requirements.
- Government Agencies:Public procurement frameworks mandating data residency, audit rights, and citizen service continuity guarantees.
- Educational Institutions:Semester-cyclical demand patterns with peak provisioning around enrollment periods and research grant cycles.
Large Enterprises command contract value; Government Agencies represent the steepest expansion trajectory as federal digitalization programs accelerate.
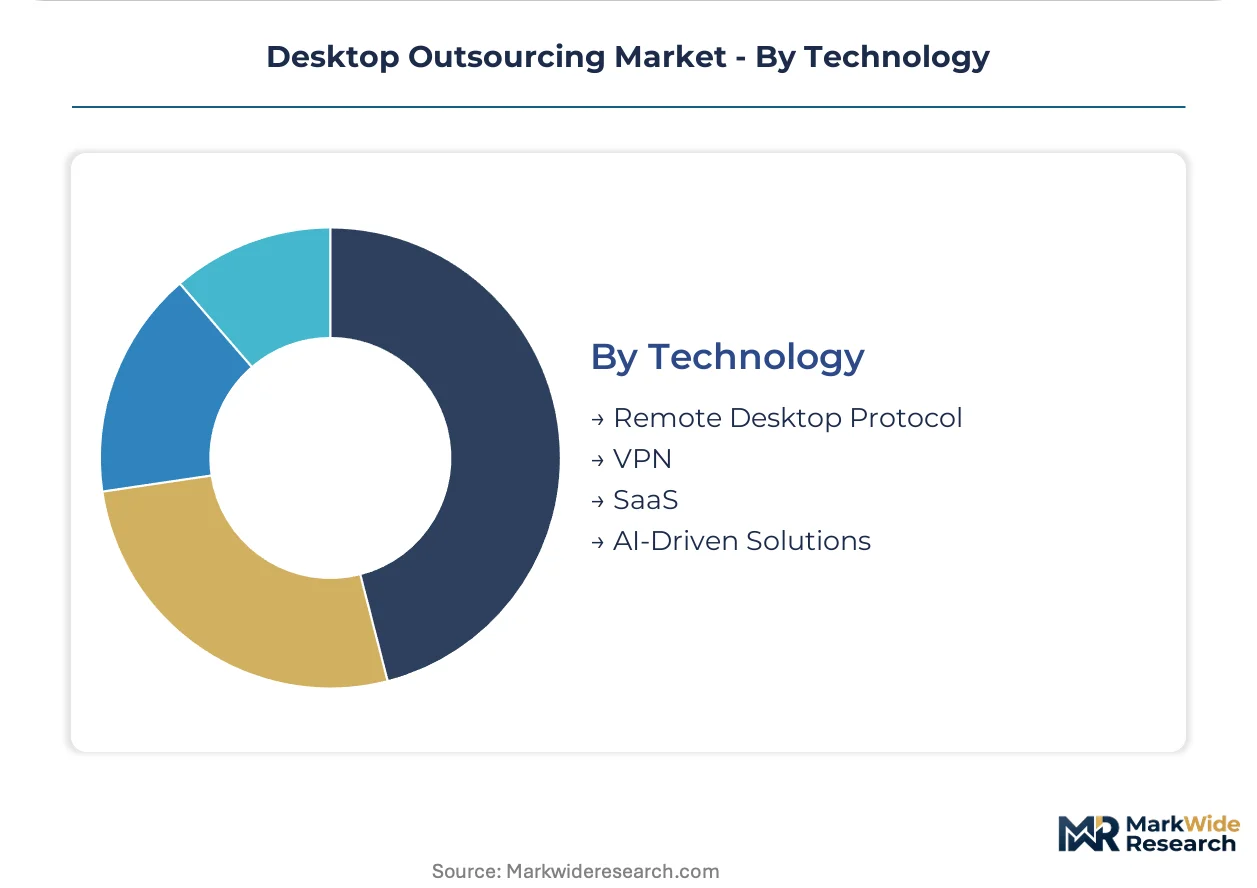
Technology:
Access protocol selection reflects security posture, legacy application dependencies, and workforce mobility requirements.
- Remote Desktop Protocol:Native Windows remote session technology delivering full desktop replication with low bandwidth requirements. Healthcare networks in France and Germany standardize on RDP for clinical workstation access, constrained by patient data encryption mandates under GDPR and national health regulations.
- VPN:Encrypted tunnel architectures extending corporate network perimeter to remote endpoints. Professional services firms maintain VPN dependency for legacy client-server applications resistant to cloud migration.
- SaaS:Browser-delivered application access eliminating endpoint installation and patch management overhead.
- AI-Driven Solutions:Automated ticket classification, predictive failure detection, and conversational service desk interfaces.
VPN retains installed base; AI-Driven Solutions gain share fastest as EU AI Act compliance frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for desktop outsourcing concentrates in financial services clusters across Germany, India, and the United States, where enterprises convert fixed IT infrastructure into operational expenditure. European regulatory pressure and India's SEZ incentives are redrawing vendor delivery footprints.
Germany
Frankfurt's banking sector and Stuttgart's automotive suppliers anchor contract volumes, driven by trader workstation uptime requirements and just-in-time production system constraints. The Federal Office for Information Security (BSI) mandates ISO 27001 certification for public sector RFPs, creating protected procurement channels. Bavaria and North Rhine-Westphalia host the densest concentration of multi-year government desktop management contracts.
India
Bangalore and Hyderabad process tickets for North American and European accounts under SEZ tax frameworks and BIS-aligned data security protocols. The Bureau of Indian Standards (BIS) governs export-oriented delivery centers where talent scarcity drives wage inflation for L1-L2 support engineers. Maharashtra and Tamil Nadu delivery hubs face margin compression on fixed-price contracts.
United States
Healthcare networks and financial services firms in New York and Chicago deploy hybrid configurations to satisfy legacy mainframe dependencies while cloud-enabling modern workloads. HIPAA and state-level data breach notification laws shape vendor accountability frameworks. The Pacific Northwest and Southeast regions show fastest SME cloud-native adoption.
United Kingdom
London's professional services firms maintain VPN dependency for legacy client-server applications resistant to cloud migration. The Information Commissioner's Office enforces GDPR breach response timelines that renegotiate vendor liability clauses. The Midlands and North England manufacturing clusters drive standardized per-seat pricing demand.
France
Paris-based healthcare networks standardize on Remote Desktop Protocol for clinical workstation access under patient data encryption mandates from CNIL and national health regulations. The EU AI Act prompts re-evaluation of automated service desk governance. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur concentrate aerospace and pharmaceutical outsourcing demand.
Desktop Outsourcing Market Vendor Landscape
Indian providers anchor the scale-driven tier; European and North American specialists hold differentiated positions in compliance-intensive segments. The vendor base organizes around three strategic archetypes: diversified technology conglomerates with hybrid cloud infrastructure, pure-play IT services firms with AI-augmented service desk capabilities, and regionally focused consultancies with public sector certification depth. Competitive moves concentrate on M&A to acquire niche compliance expertise and strategic partnerships to embed zero-trust security architectures.
Among diversified technology conglomerates, IBM and HP Inc. exemplify the infrastructure-anchored archetype, leveraging established delivery footprints to secure multi-year government contracts. Accenture occupies a position within the AI-augmented services tier, representing the shift toward predictive maintenance and automated ticket resolution. Indian pure-plays TCS and Infosys anchor the scale-driven export segment, processing high-volume tickets for North American and European accounts under favorable SEZ treatment.
| Leading Market Players |
|---|
| IBM |
| HP Inc. |
| Accenture |
| Cognizant |
| Wipro |
| Capgemini |
| Infosys |
| DXC Technology |
| TCS |
| Others |
Supply Flow & Price Mechanics
Labor cost indices in Indian metro centers cascade through desktop outsourcing contract tiers, compressing margins on fixed-price engagements while elevating premiums for GDPR-compliant European delivery. Buyers face widening spreads between standardized SEZ-based support and certified onshore alternatives.
Pricing Analysis
Volume concentrates in per-seat managed service contracts while margins accrue to AI-augmented predictive maintenance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 27001 certification grade and data residency guarantees. Cost compression in L1-L2 support intensifies because Bangalore wage inflation outpaces contract escalation clauses. SMEs exhibit highest price sensitivity; German public sector buyers prioritize compliance over unit cost.
Supply Chain Analysis
Talent scarcity in Bangalore, Chennai, and Hyderabad constrains delivery capacity for European and North American accounts. Service delivery draws from L1-L2 support engineer pools, SEZ-certified infrastructure, and BIS-aligned security protocols. Single-source vulnerability concentrates in Indian metro hubs facing wage inflation and attrition. Distribution runs through direct enterprise contracts, channel partner aggregators, and public procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Desktop outsourcing functions as a consolidation play where EU AI Act compliance costs force sub-scale vendors toward exit or acquisition. Margin compression in Indian delivery centers accelerates this attrition.
For Market Incumbents: Hedge against talent cost escalation by embedding automation layers that reduce L1-L2 headcount dependency in Bangalore and Hyderabad delivery centers. Acquire niche compliance consultancies in Germany and France to secure BSI-mandated certification depth for public sector RFPs. ISO 27001 certification investment anchors multi-year government contracts against price-only competition.
For New Entrants and Emerging Players: Capture cloud-native SME segments in Benelux manufacturing clusters where standardized per-seat pricing bypasses legacy hybrid complexity. White-space exists in AI-driven predictive maintenance for mid-market healthcare networks in France seeking CNIL-aligned automation. Channel partner aggregation offers lowest-friction go-to-market entry.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 27001-certified mid-tier providers in Bavaria and North Rhine-Westphalia facing succession or capital constraints. Long-term viability hinges on automation-to-human ratio improvement sustaining margin structure through wage inflation cycles. Watch EU AI Act enforcement intensity as inflection signal for compliance-premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Service Desk Deployment | Accenture and IBM leverage machine learning to compress mean-time-to-resolution below 15 minutes for financial services clients. |
| Zero-Trust Security Architecture Integration | VDI convergence with VPN-independent access collapses endpoint and network security procurement decisions for healthcare buyers. |
| SEZ Delivery Center Expansion | TCS and Infosys anchor export-oriented capacity under BIS protocols serving North American accounts with favorable tax treatment. |
| Public Sector Certification Acquisition | Capgemini and DXC Technology secure BSI-mandated ISO 27001 depth to access protected German federal and state RFP channels. |
| Cloud-Native SME Platform Launch | Wipro and Cognizant target Benelux manufacturers with elastic opex models bypassing on-premises infrastructure entirely. |
Methodological Framework
Document review covered vendor RFP filings, EU regulatory guidance documents, and SEZ operational reports, complemented by interviews with IT procurement directors at German automotive suppliers, service desk operations managers at Indian delivery centers, compliance officers at French healthcare networks, and channel partners in the Benelux region. Secondary validation drew from BSI certification databases, CNIL enforcement actions, Bureau of Indian Standards circulars, and hyperscaler partnership disclosures. Bottom-up contract value estimates triangulated against top-down market size assessments across the analysis window.
Model outputs generated segment-level value trajectories and deployment-mode splits across service type, infrastructure location, and end-user scale dimensions. CAGRs derived from weighted regression of historical contract renewal rates, automation adoption curves, and regulatory implementation timelines. Forecast inputs incorporated SEZ wage indices, GDPR fine case volumes, and EU AI Act risk classification guidance.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement calibration and Indian metro talent availability. Projections reflect assumptions around sustained SEZ regulatory treatment and stable cross-border data routing frameworks. Material deviation in automation substitution rates or BIS-versus-GDPR compliance friction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market