
 United States Digital OOH Advertising Market | 2026-2036
United States Digital OOH Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
United States Digital OOH Advertising Market Intelligence
FCC equipment authorization under Part 15 rules is bifurcating the competitive landscape between qualified deployers and excluded entrants. Clear Channel Outdoor Holdings Inc. leverages its nationwide billboard portfolio to sustain programmatic inventory scale. Lamar Advertising Company anchors rural and interstate coverage through owned real estate and local permit relationships. OUTFRONT Media Inc. competes in transit-centric environments where municipal contracts govern access.
Digital out-of-home advertising encompasses electronically illuminated displays that deliver dynamic content via networked content management systems, typically employing LED or LCD panels with brightness calibration between 5,000 and 10,000 nits for daylight visibility. Video screens command premium CPM rates in high-dwell locations such as airport concourses, while interactive kiosks integrate touch and gesture sensors to capture engagement metrics for attribution modeling. Static displays retain cost efficiency in retail deployment models where promotional ads rotate on fixed intervals without real-time data feeds.
The FCC governs electromagnetic emissions from digital display hardware, while local zoning boards enforce sightline and safety setbacks that directly determine permissible installation sites. Municipal transit authorities increasingly mandate accessibility compliance under ADA guidelines for interactive kiosk interfaces. Stakeholders must monitor evolving privacy frameworks around facial detection and mobile device proximity sensing as these technologies expand in measurement protocols.
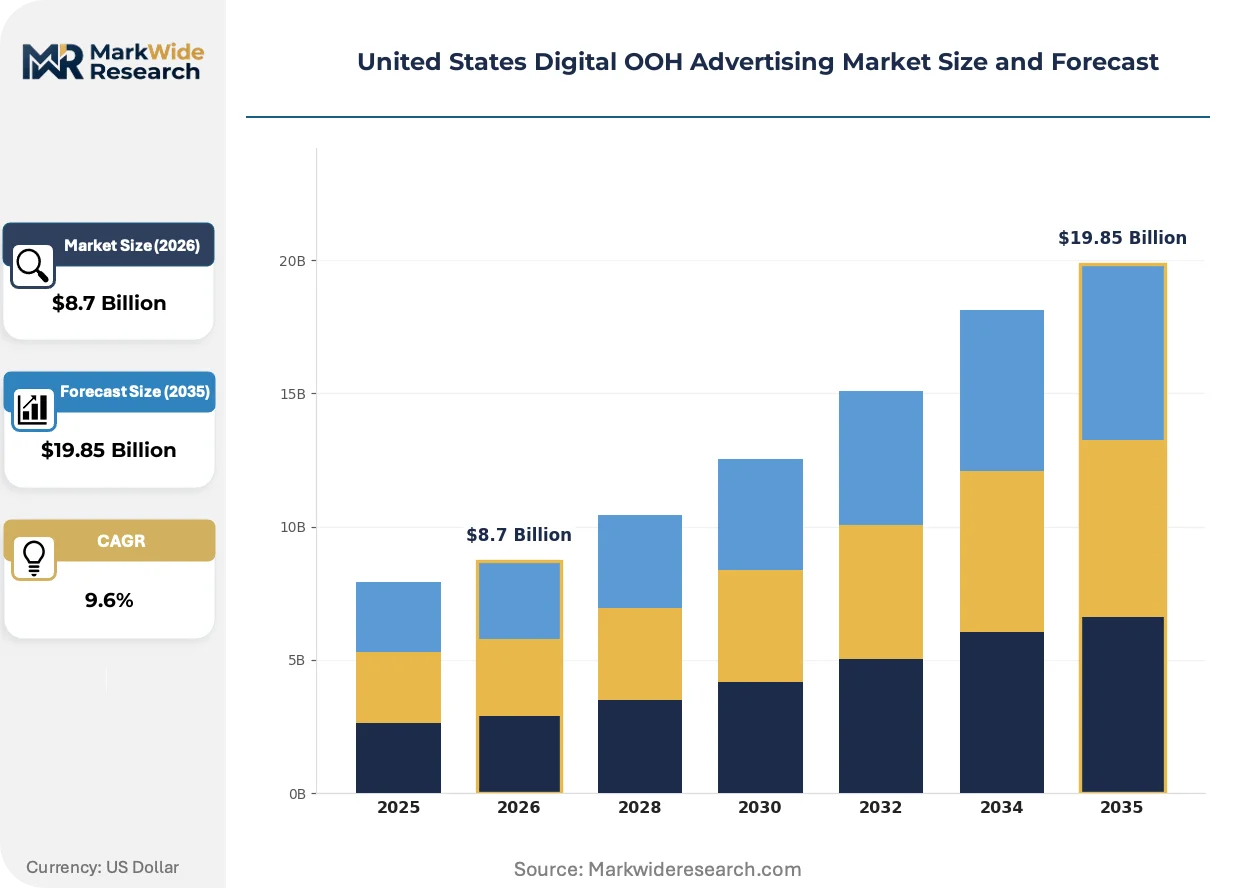
Market Dynamics
The US digital OOH advertising market is undergoing a structural transformation driven by the collision between FCC Part 15 equipment authorization requirements and municipal zoning fragmentation, which is concentrating deployment permissions among qualified infrastructure operators while excluding capital-constrained entrants.
Growth Catalysts
- Transit Authority Screen Expansion:Municipal agencies in high-density corridors are awarding exclusive digital display contracts to operators with proven ADA compliance records, locking in long-term revenue streams.
- FCC Part 15 Rules:The Commission's electromagnetic emission standards for LED hardware create a compliance moat that filters out undercapitalized competitors and consolidates inventory control among authorized deployers.
- Programmatic Trading Platforms:Real-time bidding integration is enabling impression-level audience targeting across networked inventory, attracting demand from performance-focused advertisers.
Market Restraints
- Real Estate Access Concentration:Prime billboard and transit shelter locations in the New York City metropolitan area are controlled by a handful of leaseholders with multi-decade municipal contracts, blocking new market entry.
- Local Zoning Variance Costs:Sightline and safety setback requirements vary across 3,000+ US jurisdictions, forcing operators to maintain localized legal teams and extending deployment timelines.
- Mobile Advertising Substitution:Location-targeted smartphone ad inventory competes directly for the same geofenced campaign budgets, compressing OOH rate premiums in secondary markets.
Strategic Opportunities
- Mid-Tier City Transit Modernization:Austin, Nashville, and Denver are replacing static bus shelter panels with networked digital displays, creating first-mover advantages for operators with FCC-certified hardware.
- Retail Media Network Convergence:Grocery and pharmacy chains are deploying in-aisle digital screens with proximity sensing, enabling closed-loop attribution between exposure and purchase.
- IRA Green Infrastructure Incentives:Energy-efficient LED retrofit projects qualify for federal tax credits, offsetting capital costs for municipal transit agencies upgrading legacy lighting systems.
Industry Challenges
- Facial Detection Compliance Fragmentation:No federal standard governs biometric measurement in public spaces, forcing operators to navigate Illinois BIPA, California CCPA, and emerging state privacy laws simultaneously.
- Legacy CMS Integration:Decades-old content management infrastructure in transit authorities requires costly API bridging to connect with modern programmatic platforms.
- Specialized Technician Scarcity:Installation and maintenance of 10,000-nit outdoor-rated LED panels demands certified electricians with RF shielding expertise, creating wage pressure in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Digital OOH Advertising Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.85 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Video Screens, Static Displays, Interactive Kiosks, Digital Billboards Industry Use: Retail, Transportation, Entertainment, Sports Deployment Model: In-mall, Transit Stations, Airports, Outdoor Venues Content Type: Promotional Ads, Branding Campaigns, Event Announcements, Real-time Updates |
| Companies Covered | Clear Channel Outdoor Holdings Inc., OUTFRONT Media Inc., Lamar Advertising Company, JCDecaux North America Inc., Intersection, Vistar Media, Daktronics Inc., Volta Charging LLC, GSTV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Digital OOH Advertising Market Strategic Shifts & Innovations
Programmatic infrastructure is rewiring how digital OOH inventory is bought and sold, collapsing the traditional insertion-order model while introducing real-time audience measurement and automated creative optimization across previously siloed display networks.
Edge-computing content delivery systems are bifurcating the technical architecture of digital signage networks. These distributed nodes process audience detection and creative selection locally rather than routing through centralized cloud servers. Transit operators with privacy-sensitive deployments are adopting edge-based processing to minimize biometric data transmission. The technology is bifurcating vendor capabilities between those with embedded hardware engineering teams and pure software providers dependent on third-party integration.
Local zoning boards are tightening sightline setback requirements for roadside digital billboards under pressure from state departments of transportation. The industrial consequence is a geographic redistribution of deployable inventory toward interstate corridors and away from urban arterial roads. Rural and exurban operators with grandfathered permits in Texas and Florida are consolidating these scarce assets as municipal moratoriums expand.
Advertisers are unbundling media buying from creative production, demanding self-serve platforms that enable real-time creative versioning without agency intermediation. Direct brand relationships are displacing traditional OOH specialist agencies for mid-market campaigns. This pattern is most pronounced in retail and quick-service restaurant verticals, where marketing teams prioritize speed-to-market over creative customization.
United States Digital OOH Advertising Market Segmentation
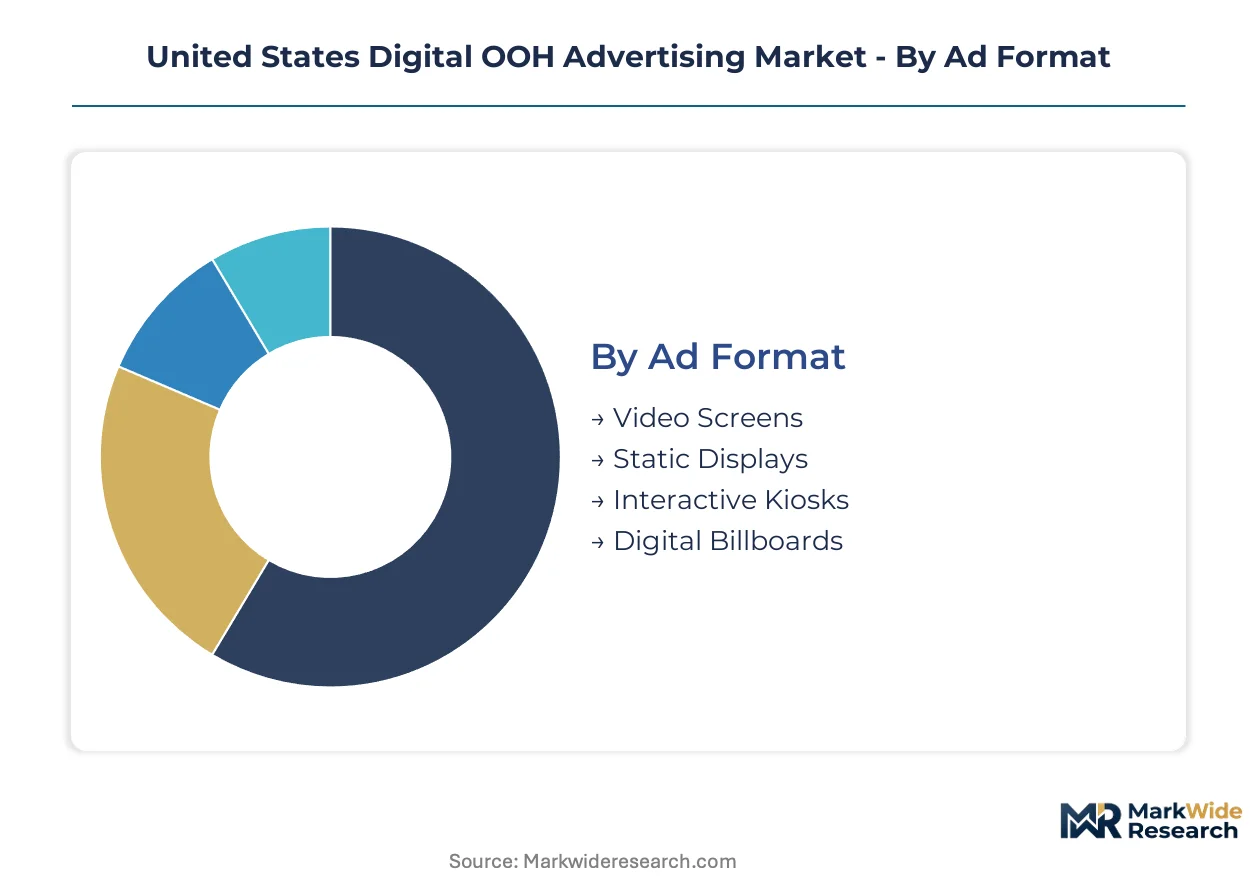
Digital OOH inventory commands divergent rate cards based on dwell time, audience measurability, and real-time adaptability. Understanding format and deployment distinctions reveals where operators invest capital and where advertisers shift budget.
Ad Format:
Margin pools concentrate in motion-enabled formats that justify premium CPMs through engagement metrics and programmatic trading compatibility.
- Video Screens:LED and LCD panels delivering full-motion content at 5,000-10,000 nits brightness for daylight visibility. Demand clusters in airport concourses and subway corridors where extended dwell times support 15-30 second spot rotations, with FCC Part 15 certification filtering out undercapitalized deployers.
- Interactive Kiosks:Touch and gesture-enabled displays capturing engagement metrics for closed-loop attribution. New York City transit authorities mandate ADA-compliant interfaces, locking in long-term contracts with operators possessing certified hardware and accessibility engineering capabilities.
- Static Displays:Electronically illuminated panels with fixed-interval content rotation lacking real-time data feeds. Retail deployment models favor this cost-efficient format for promotional cycles.
- Digital Billboards:Large-format roadside LED installations governed by local zoning sightline setbacks. Grandfathered permits in Texas and Florida corridors command scarcity premiums as municipal moratoriums expand.
The dominant share belongs to Video Screens, while Interactive Kiosks is closing the gap fastest.
Industry Use:
Application-specific deployment patterns reflect divergent procurement timelines and creative refresh frequencies across verticals.
- Retail:In-aisle and storefront displays with proximity sensing for closed-loop attribution between exposure and purchase. Grocery and pharmacy chains are unbundling media buying from creative production through self-serve platforms.
- Transportation:Transit authority contracts governing subway, bus shelter, and rail station inventory. Municipal agencies in Austin, Nashville, and Denver are replacing static panels with networked digital displays, creating first-mover advantages for FCC-certified operators.
- Entertainment:Venue-owned screens in theaters, arenas, and hospitality destinations with event-triggered content synchronization.
- Sports:Stadium concourse and exterior displays with real-time score integration and sponsor rotation flexibility.
Transportation captures the largest contract value, with Retail expanding most quickly through retail media network convergence.
Deployment Model:
Real estate access concentration determines competitive moats, with transit and aviation environments presenting the steepest barriers to new entry.
- In-mall:Property owner-managed networks with footfall-indexed rate cards. Mall operators are integrating programmatic pipes to attract performance advertisers.
- Transit Stations:Municipal agency contracts with multi-decade terms and ADA compliance mandates. New York City metropolitan area density sustains premium inventory pricing unavailable elsewhere.
- Airports:Port authority concessions with security-cleared installation protocols and passenger dwell-time premiums. Video screens here command the highest CPM rates in the entire US market.
- Outdoor Venues:Highway, arterial road, and entertainment district installations subject to local zoning variance costs across 3,000-plus jurisdictions.
Airports maintains rate leadership, while Transit Stations is gaining share fastest through agency modernization programs.
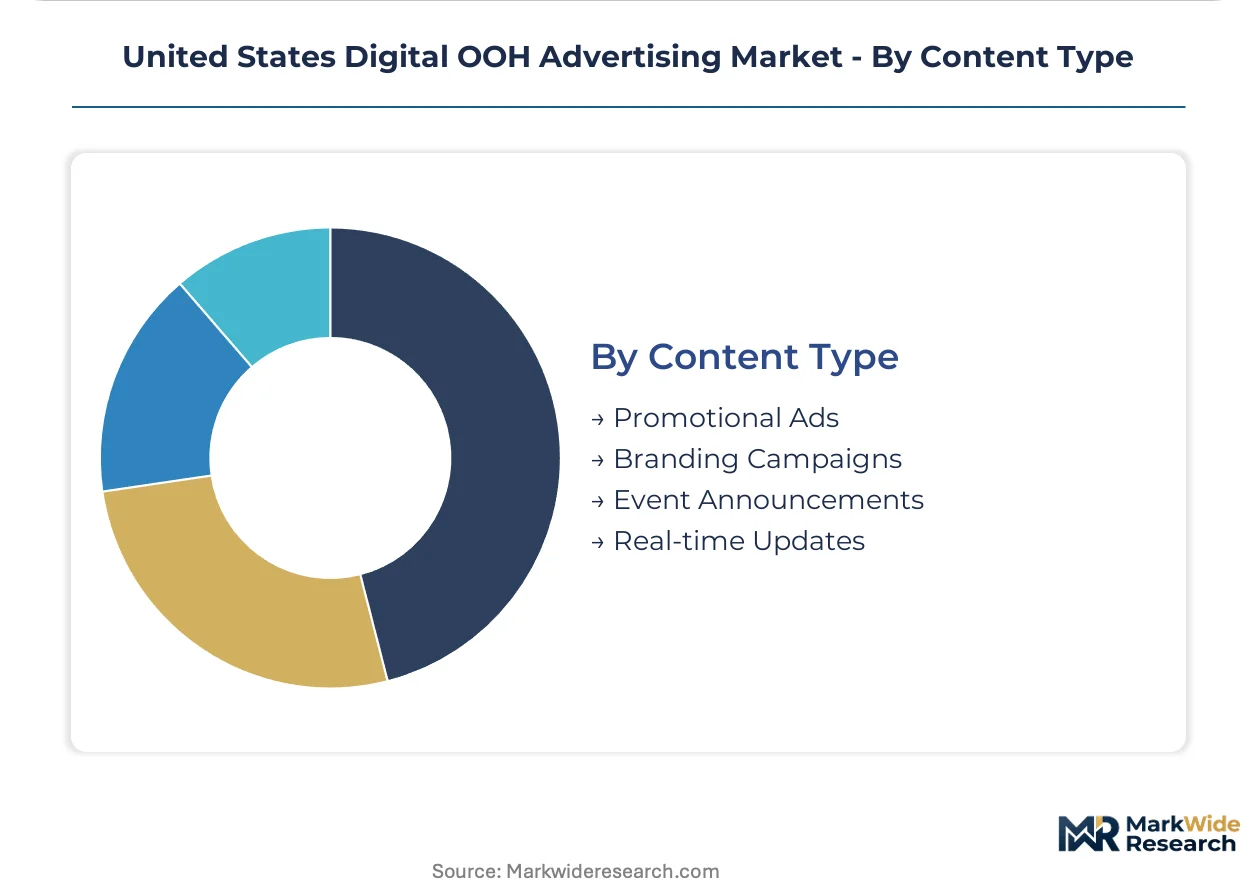
Content Type:
Creative flexibility and production velocity separate high-margin campaigns from commoditized display rentals.
- Promotional Ads:Time-limited offers with dynamic pricing and inventory triggers. Quick-service restaurant verticals prioritize speed-to-market over creative customization.
- Branding Campaigns:Long-form narrative content with cross-screen sequencing. Advertisers are demanding real-time creative versioning without agency intermediation.
- Event Announcements:Date-specific activations with geofenced audience targeting. Edge-computing nodes enable local processing for privacy-sensitive biometric detection.
- Real-time Updates:News, weather, and transit information with API-driven content feeds. Legacy CMS infrastructure in transit authorities requires costly bridging to modern programmatic platforms.
Branding Campaigns holds the largest volume commitment, with Real-time Updates climbing the fastest as edge-computing adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertiser procurement concentrates in dense metropolitan corridors where transit authority contracts and premium real estate access determine inventory availability. Municipal zoning variance costs and FCC equipment authorization requirements filter deployer participation, concentrating operational scale among qualified infrastructure operators.
New York Metropolitan Area
Subway corridor screen networks and bus shelter digital displays sustain the nation's highest CPM rates through commuter volume density. The Metropolitan Transportation Authority awards exclusive municipal contracts requiring ADA-compliant interactive kiosk interfaces. Manhattan and Brooklyn transit hubs anchor premium inventory pricing unavailable in secondary markets.
California
Los Angeles and San Francisco Bay Area transit agencies are replacing static panels with networked LED displays, creating deployment opportunities for FCC-certified operators. The California Consumer Privacy Act imposes biometric data handling requirements on facial detection measurement protocols. Interstate corridor billboards in the Central Valley face tightening municipal sightline setback restrictions.
Texas
Dallas-Fort Worth and Houston metro areas present grandfathered billboard permits commanding scarcity premiums as urban moratoriums expand. The Texas Department of Transportation enforces roadside safety setback standards that redistribute deployable inventory toward exurban corridors. Austin transit modernization programs are converting bus shelter infrastructure to digital networks.
Florida
Miami and Orlando airport concourse video screens command premium dwell-time rates among domestic aviation environments. The Florida Department of Transportation coordinates with local zoning boards on digital billboard sightline compliance. Tampa and Jacksonville municipal transit authorities are evaluating screen network expansion proposals.
Illinois
Chicago Transit Authority corridor contracts govern access to subway and rail station digital inventory. The Illinois Biometric Information Privacy Act creates compliance complexity for facial detection measurement deployments. O'Hare International Airport maintains security-cleared installation protocols for passenger-facing display networks.
United States Digital OOH Advertising Market Key Industry Players
Player mix skews toward diversified outdoor advertising incumbents with municipal real estate portfolios and transit authority relationships. The competitive structure concentrates around three strategic archetypes: nationwide billboard portfolio operators, transit-centric municipal contract holders, and programmatic technology enablers. Dominant competitive moves include exclusive municipal contract renewals and edge-computing content delivery system deployment.
Within the diversified portfolio tier, Clear Channel Outdoor Holdings Inc., OUTFRONT Media Inc., and Lamar Advertising Company exemplify competing archetypes. Clear Channel Outdoor Holdings Inc. represents the nationwide billboard and street furniture coverage model. OUTFRONT Media Inc. occupies a position emphasizing transit authority relationships and municipal contract density. Lamar Advertising Company anchors rural and interstate corridor presence through localized permit relationships.
| Leading Market Players |
|---|
| Clear Channel Outdoor Holdings Inc. |
| OUTFRONT Media Inc. |
| Lamar Advertising Company |
| JCDecaux North America Inc. |
| Intersection |
| Vistar Media |
| Daktronics Inc. |
| Volta Charging LLC |
| GSTV |
| Others |
Cost & Logistics Intelligence
Municipal transit authority contracts with 10-15 year exclusive terms lock in both supply access and rate visibility for qualified operators, insulating incumbent deployers from spot-market volatility while excluding capital-constrained entrants from premium inventory.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate transit shelter and subway corridor deployments, anchoring rate stability for operators with FCC Part 15 certification. Three-tier pricing structure across premium airport concourse, standard urban transit, and economy secondary-market tiers reflects dwell-time differentials. Pricing pressure stems from mobile advertising substitution in geofenced campaign budgets, compressing OOH rate premiums outside dense metropolitan corridors. Quick-service restaurant verticals exhibit highest price sensitivity, prioritizing speed-to-market over creative customization, while luxury brands accept premium airport CPMs for extended passenger dwell.
Supply Chain Analysis
Inventory lead times for 10,000-nit outdoor-rated LED panels extend 12-16 weeks, constraining rapid deployment for transit modernization programs. Hardware sourcing concentrates in China, South Korea, and Taiwan, with specialized driver ICs and RF shielding components drawing from concentrated semiconductor foundries. Single-source vulnerability runs through advanced LED chip suppliers, exacerbated by FCC equipment authorization bottlenecks. Distribution runs through certified installation contractors with municipal security clearances, creating localized capability scarcity in high-demand corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified RF shielding technicians and ADA-certified accessibility engineers represent the scarcest capabilities, determining which operators capture municipal transit contracts versus those locked out of premium deployment zones.
For Market Incumbents: Secure exclusive municipal contract renewals in Austin, Nashville, and Denver transit modernization programs before FCC-certified hardware shortages peak. Reinforce edge-computing content delivery capabilities to meet privacy-sensitive biometric detection requirements under Illinois BIPA and California CCPA. Vertical integration into in-house LED panel maintenance reduces wage pressure from certified electrician scarcity. For New Entrants and Emerging Players: Differentiate on retail media network convergence, deploying in-aisle digital screens with proximity sensing for grocery and pharmacy chains seeking closed-loop attribution. Target mid-tier city transit authorities in Tampa and Jacksonville evaluating screen network expansion, where incumbent concentration remains lower than New York or Chicago. Pursue self-serve platform partnerships with quick-service restaurant marketing teams prioritizing creative versioning speed. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified portfolio operators with grandfathered billboard permits and municipal contract density. Long-term viability hinges on regulatory compliance capabilities spanning FCC Part 15, ADA guidelines, and fragmented state biometric privacy laws. Acquisition target archetype: regional operators with Texas and Florida grandfathered permits plus nascent programmatic trading infrastructure. Watch for Illinois BIPA enforcement actions as inflection indicator for facial detection measurement liability exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Municipal Contract Renewal | Locks in decade-long revenue streams with MTA, CTA, and emerging transit agencies. |
| Edge-Computing Deployment | Enables local biometric processing to satisfy Illinois BIPA and California CCPA requirements. |
| Retail Media Network Partnership | Captures grocery and pharmacy in-aisle inventory with closed-loop purchase attribution. |
| Programmatic Platform Integration | Connects legacy transit CMS infrastructure to real-time bidding for performance advertisers. |
| FCC Part 15 Certification Investment | Creates compliance moat filtering undercapitalized competitors from LED hardware deployment. |
Research Approach
Desk research of FCC equipment authorization databases, municipal transit authority procurement records, and state biometric privacy legislation preceded structured interviews with transit agency procurement officers, outdoor advertising operations executives, LED hardware engineering directors, and programmatic platform product managers. Primary fieldwork combined with secondary validation against SEC 10-K filings, customs import records for display hardware, and zoning variance tracking across 3,000-plus jurisdictions. Bottom-up deployment inventory counts triangulated against top-down advertising spend estimates.
Variance decomposition across the projection horizon isolates growth contributions from transit screen expansion, retail media network adoption, and programmatic trading penetration. Segmentation modeling incorporates ad format, deployment environment, content type, and municipal contract structure. CAGRs derive from logistic adoption curves for digital substitution of static displays, with inputs including commuter volume projections, IRA green infrastructure incentive uptake, and mobile advertising CPM trends.
Decision-makers should treat outputs as directional under assumptions of sustained FCC Part 15 enforcement continuity and stable municipal transit funding; material deviation in biometric privacy litigation or federal infrastructure appropriations would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media and Entertainment Technologies
VR Content Creation Services Market
Digital Media and Entertainment Technologies
Global Virtual Event Platform Market
Digital Media and Entertainment Technologies
Digital Scent Technology Market
Digital Media and Entertainment Technologies
Video Switchers Market
Digital Media and Entertainment Technologies
Europe Digital Scent Technology Market
Digital Media and Entertainment Technologies
Healthcare Gamification Market
Digital Media and Entertainment Technologies
North America Digital Scent Technology Market
Digital Media and Entertainment Technologies
Digital Media Adapters Market
Digital Media and Entertainment Technologies
Digital OOH Market