
 Global Virtual Event Platform Market | 2026-2036
Global Virtual Event Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Event Platform Market Foresight
A shortage of cloud-native event engineers is reorganizing how platform vendors allocate technical talent between product development and customer success functions. Cvent leverages its established enterprise relationships to sustain dominance in large-scale virtual conference deployments. Zoom Video Communications anchors the mid-market segment through integrated video infrastructure that reduces third-party dependency. Hubilo differentiates through immersive networking lounge features that command premium pricing from experiential-focused buyers.
A virtual event platform is a software system that delivers real-time digital event experiences through streaming media, interactive audience tools, and data analytics dashboards, typically requiring sub-200ms latency for synchronous participation. The technology serves commercial and institutional organizers seeking scalable alternatives to physical venue dependency. Cloud-based deployment leads solution offering adoption as enterprises prioritize elastic capacity for unpredictable attendance spikes. Webinars and virtual conferences represent the most mature application categories with established pricing benchmarks, while networking lounges capture expanding margin pools as buyers demand engagement depth over broadcast reach. Corporate training and investor relations applications are gaining structural weight as compliance documentation requirements intensify.
The EU AI Act and GDPR impose algorithmic transparency and data residency obligations that constrain platform architecture choices for European deployments. The FCC in the United States enforces net neutrality principles that affect streaming quality guarantees for bandwidth-intensive virtual events. ISO 27001 certification has become a baseline procurement filter for enterprise and government agency buyers evaluating vendor security posture. Stakeholders must monitor how generative AI integration into virtual event platforms triggers fresh regulatory scrutiny on automated content moderation and attendee data processing.
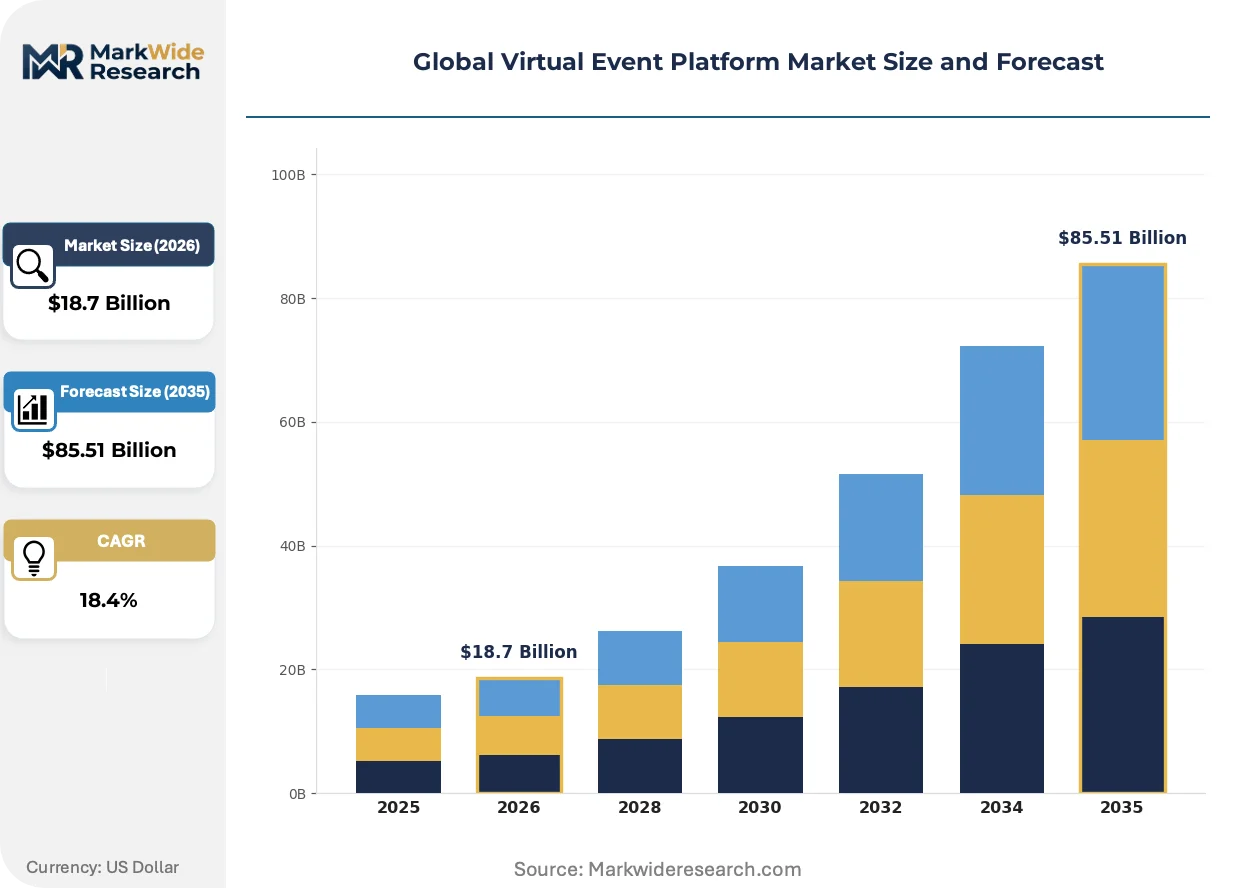
Market Dynamics
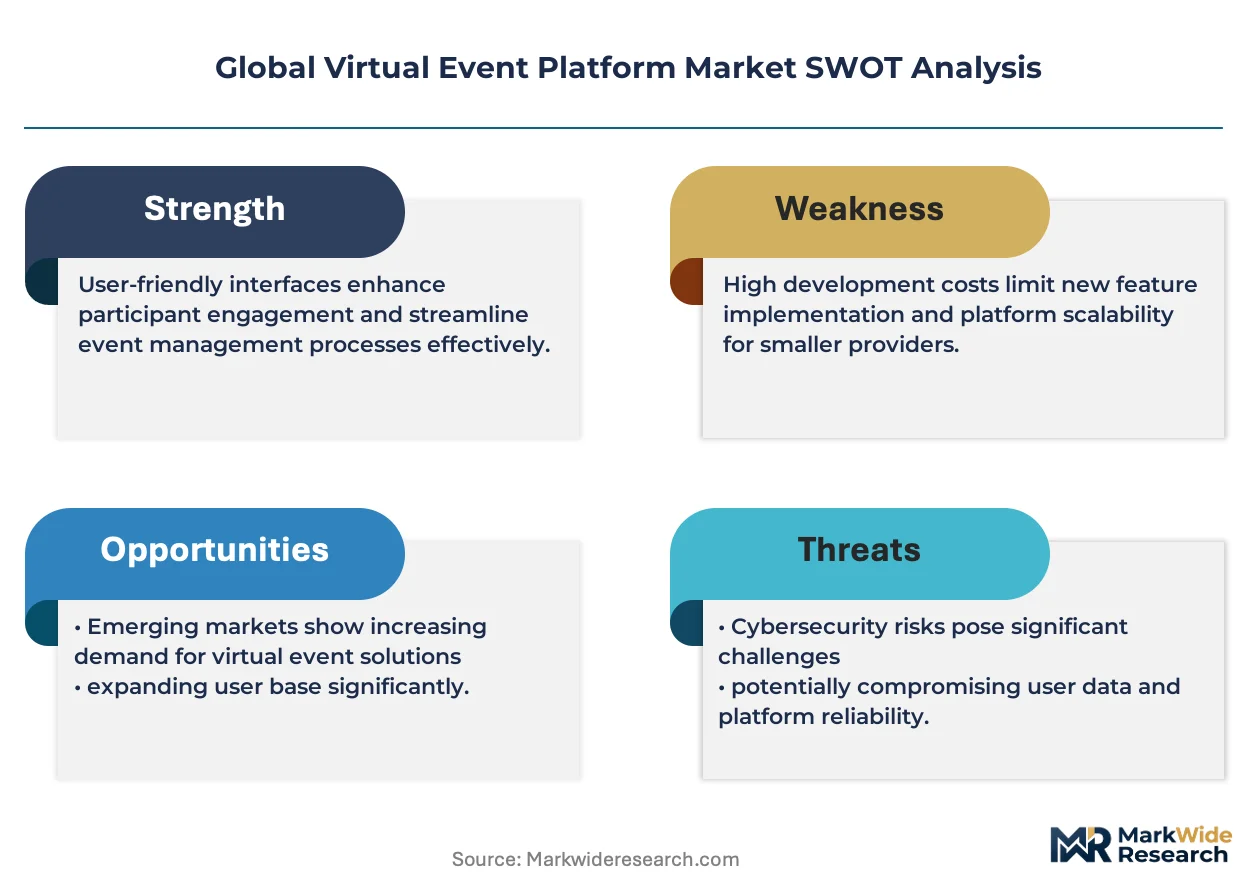
The hybrid work permanence is fragmenting event budgets across physical and digital channels, forcing platform vendors to engineer elastic infrastructure that collapses cost per attendee as volume scales unpredictably.
Growth Catalysts
- GDPR Article 17 data erasure mandates:European enterprises are procuring EU-hosted virtual event platforms to satisfy residency requirements without on-premise hardware investments.
- Cloud-native event engineering:Kubernetes-orchestrated streaming stacks are reducing latency below 150ms for synchronous networking applications.
- Fortune 500 procurement:Distributed workforce engagement budgets are consolidating into single-vendor virtual collaboration contracts with multi-year terms.
Market Restraints
- AWS-Google Cloud-Azure triopoly:Infrastructure-as-a-Service concentration creates single-point-of-failure risk for streaming capacity during peak loads.
- ISO 27001 certification timelines:Sixteen-month audit cycles delay vendor entry into government and financial services procurement pipelines.
- WebRTC technical ceiling:Browser-based real-time communication protocols struggle beyond 500 concurrent video streams without server-side relay augmentation.
Strategic Opportunities
- India PLI scheme for digital infrastructure:Local data center construction incentives are enabling India-hosted platform deployments for price-sensitive APAC buyers.
- Generative AI content moderation:Automated transcription and sentiment analysis tools are opening premium pricing tiers for compliance-heavy investor relations events.
- Immersive networking lounges:Spatial audio and avatar-based interaction layers are capturing margin pools from experiential marketing agencies seeking depth over broadcast reach.
Industry Challenges
- Cloud-native event engineer scarcity:Platform vendors are reallocating technical talent from product development to customer success functions.
- EU AI Act algorithmic transparency:Automated recommendation engines in networking matchmaking require explainability documentation that extends development cycles.
- Legacy video infrastructure integration:Enterprise buyers demand seamless handoff between existing Zoom or Teams deployments and specialized event platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Event Platform Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Managed Services Solution Offering: Webinars, Hybrid Events, Virtual Conferences, Networking Lounges, Trade Shows Application: Corporate Training, Product Launches, Investor Relations, Internal Communication End User: Enterprises, Educational Institutions, Nonprofit Organizations, Government Agencies |
| Companies Covered | 6Connex, Cvent, Hubilo, BigMarker, Zoom Video Communications, vFairs, Remo, Livestorm, EventMobi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Event Platform Market Shifts & Advancements
Real-time engagement technologies are compressing the feature gap between broadcast-quality production and self-service deployment, enabling mid-market buyers to execute previously enterprise-grade event experiences.
Edge-computing streaming nodes are decomposing centralized cloud architecture into geographically distributed processing layers. Regional enterprises in Brazil and Southeast Asia are adopting these nodes to bypass transcontinental latency penalties. This topology is decomposing the vendor-customer relationship from pure SaaS toward hybrid infrastructure partnerships with local telecom operators.
The EU AI Act's risk-based classification system is imposing documentation burdens on platforms deploying automated content moderation. Vendors must now maintain technical files proving human oversight of algorithmic decision-making. Large-scale virtual conference deployments in Germany and France are experiencing procurement delays as legal teams validate compliance attestations.
Buyer committees are consolidating vendor evaluation authority into procurement departments previously excluded from technology selection. Marketing and HR functions are losing autonomy to centralized IT governance frameworks that prioritize security certification over feature breadth. This concentration is most pronounced in United States healthcare and financial services verticals where HIPAA and SEC record-keeping requirements intersect with event technology decisions.
Global Virtual Event Platform Market Segmentation
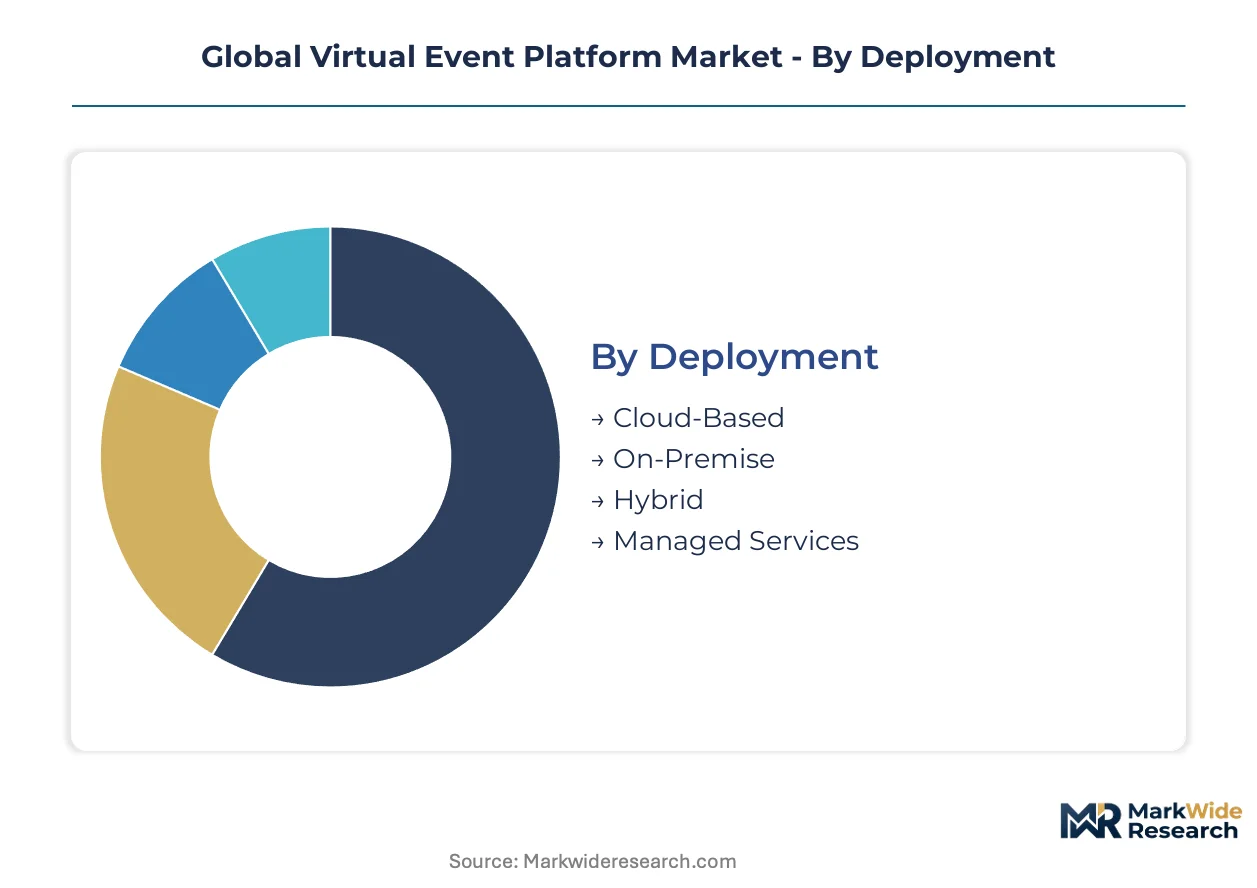
Virtual event platform segmentation reveals how deployment architecture, solution configuration, and end-user procurement authority reshape competitive positioning. Buyers prioritize elastic capacity for unpredictable attendance spikes while compliance requirements constrain vendor selection across regulated verticals.
Deployment:
Cloud-based deployment faces the strongest substitution pressure from hybrid configurations as enterprises balance elastic scaling against data sovereignty mandates.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for attendance spikes exceeding 10,000 concurrent users. Fortune 500 procurement teams in the United States consolidate multi-year contracts with vendors offering sub-150ms latency guarantees through AWS, Google Cloud, and Azure infrastructure.
- Hybrid:Split-stack deployments combine public cloud streaming with on-premise identity management for GDPR Article 17 compliance. German and French enterprises favor this model to satisfy CNIL and BfDI data residency audits without sacrificing global reach.
- On-Premise:Self-hosted infrastructure serves defense contractors and classified government agencies requiring air-gapped environments.
- Managed Services:White-glove implementation and 24/7 operational support command premium pricing from experiential marketing agencies lacking internal cloud engineering capacity.
Cloud-Based deployment anchors the volume base while Hybrid configurations gain share at the steepest rate as European compliance requirements intensify.
Solution Offering:
Pricing power concentrates in experiential formats where engagement depth displaces broadcast reach as the primary buyer metric.
- Virtual Conferences:Multi-track programming with simultaneous sessions demands orchestrated CDN distribution and real-time analytics dashboards. Enterprise technology vendors in the United States deploy these for annual user conferences with 50,000+ registered attendees.
- Networking Lounges:Spatial audio and avatar-based interaction layers enable serendipitous connection discovery previously exclusive to physical venues. Experiential marketing agencies in London and New York pay 40-60% premiums for these capabilities over standard webinar formats.
- Webinars:Single-presenter broadcast formats with Q&A and polling represent the most mature, price-commoditized category.
- Hybrid Events:Synchronized physical-digital experiences require redundant streaming infrastructure and on-site production crews.
- Trade Shows:Virtual booth configurations with lead retrieval and appointment scheduling replicate exhibition hall economics.
Webinars anchor the volume base while Networking Lounges expand most quickly as buyers prioritize engagement depth over audience scale.
Application:
Compliance documentation intensity determines procurement authority migration from marketing functions to centralized IT governance.
- Investor Relations:SEC record-keeping requirements and MiFID II transaction reporting mandate immutable audit trails and real-time transcription. Financial services firms in New York and Frankfurt procure platforms with ISO 27001 certification and automated sentiment analysis for regulatory disclosure.
- Corporate Training:SCORM-compliant content delivery with completion tracking serves distributed workforce reskilling initiatives. Healthcare systems across the United States demand HIPAA-aligned data handling for clinical education programs.
- Product Launches:Broadcast-quality production values with simultaneous interpretation support multinational go-to-market synchronization.
- Internal Communication:All-hands meetings and town halls prioritize cost efficiency over feature depth for high-frequency deployment.
Internal Communication anchors the volume base while Investor Relations climbs the fastest as compliance automation commands premium pricing tiers.
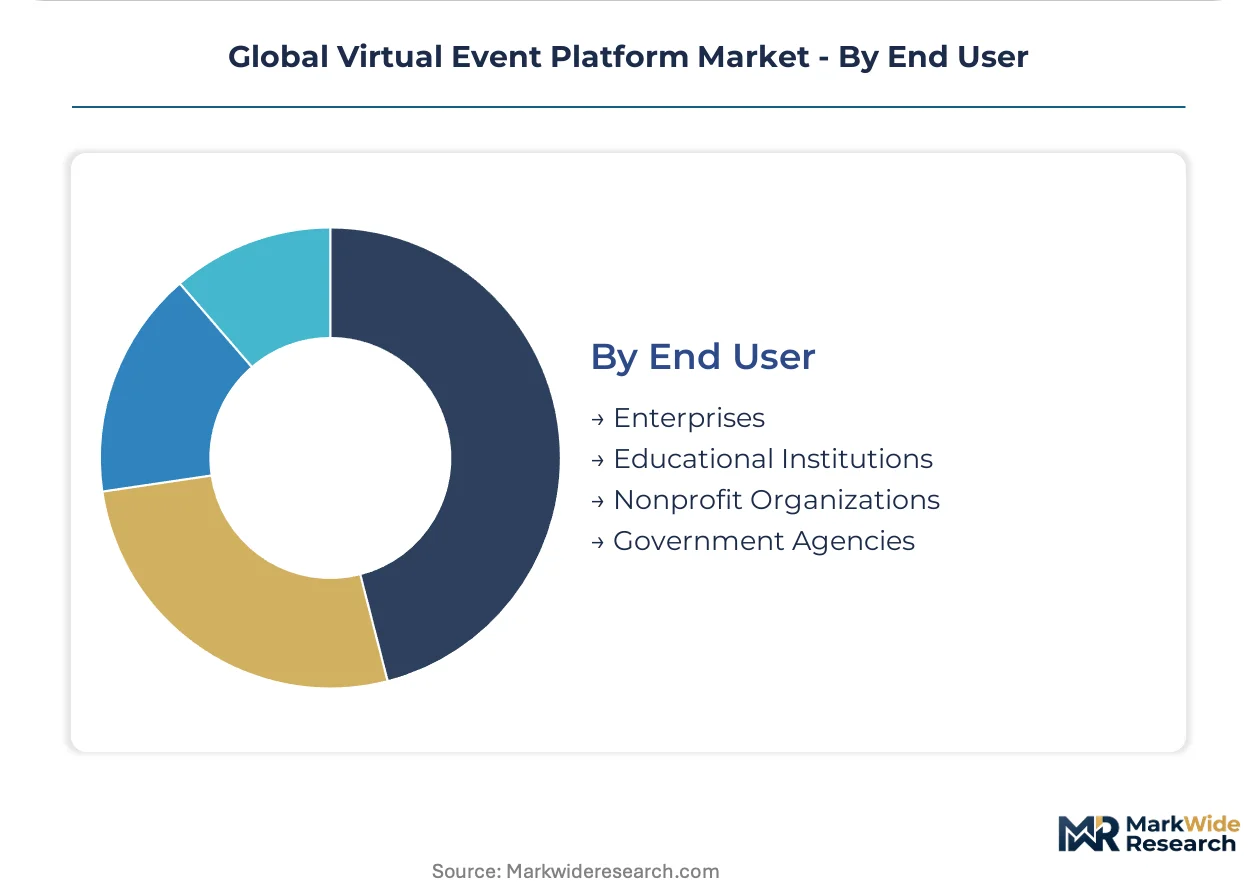
End User:
Procurement centralization into IT governance frameworks fragments vendor relationships previously managed by departmental buyers.
- Enterprises:Multi-divisional deployments with unified identity management and spend consolidation under single-vendor contracts. Technology and financial services verticals in the United States and United Kingdom lead procurement volume.
- Government Agencies:FedRAMP and ISO 27001 certification requirements exclude uncertified vendors from federal and state procurement pipelines. Defense and civilian agencies prioritize on-premise or hybrid deployment for classified communications.
- Educational Institutions:Learning management system integration and accessibility compliance (WCAG 2.1) drive platform selection for universities and K-12 districts.
- Nonprofit Organizations:Cost-sensitive procurement with donor-funded budgets favors self-service deployment over managed services.
Enterprises anchor the volume base while Government Agencies gain share at the steepest rate as certification requirements extend sales cycles and deepen vendor moats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises consume virtual event platforms as unified workforce collaboration infrastructure, while European buyers fragment procurement across compliance-segmented deployments and Indian adopters prioritize cost-elastic solutions for price-sensitive APAC expansion.
United States
Fortune 500 technology and financial services firms consolidate multi-year vendor contracts for distributed workforce engagement. FCC net neutrality enforcement shapes streaming quality guarantees for bandwidth-intensive deployments. New York and San Francisco Bay Area procurement teams anchor national volume concentration.
Germany
Industrial conglomerates and automotive OEMs demand hybrid deployment models balancing global reach with data sovereignty. BfDI audits and GDPR Article 17 mandates drive split-stack architecture preferences. Frankfurt and Munich enterprise clusters lead compliance-heavy procurement cycles.
United Kingdom
Financial services and professional services sectors prioritize ISO 27001-certified platforms for investor relations applications. FCA record-keeping requirements intersect with SEC disclosure obligations for dual-listed firms. London's experiential marketing agencies command premium networking lounge capabilities.
India
IT services exporters and domestic conglomerates adopt cloud-native platforms for APAC workforce training at scale. PLI scheme incentives for digital infrastructure enable local data center construction. Bengaluru and Hyderabad technology corridors drive regional adoption velocity.
France
Luxury goods houses and pharmaceutical groups deploy platforms for synchronized multinational product launches. CNIL algorithmic transparency requirements extend development cycles for AI-powered networking matchmaking. Paris marketing clusters anchor experiential format demand.
Global Virtual Event Platform Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with enterprise-grade infrastructure vendors commanding procurement consolidation while niche players capture premium segments through experiential differentiation. The vendor landscape organizes around three archetypes: unified collaboration platforms extending into events, pure-play virtual event specialists, and video infrastructure providers layering event-specific capabilities. Competitive motion centers on strategic partnerships with cloud infrastructure providers and vertical integration into managed production services.
Among established enterprise software vendors, Cvent exemplifies the integrated leader archetype through sustained dominance in large-scale conference deployments. Hubilo occupies a position within the specialist tier, commanding premium pricing through immersive networking differentiation. Zoom Video Communications anchors the mid-market vector, leveraging embedded video infrastructure to reduce third-party dependency for integrated buyers.
| Leading Market Players |
|---|
| 6Connex |
| Cvent |
| Hubilo |
| BigMarker |
| Zoom Video Communications |
| vFairs |
| Remo |
| Livestorm |
| EventMobi |
| Others |
Supply & Pricing Matrix
Sixteen-month ISO 27001 certification timelines compress vendor pricing power in the enterprise tier while amplifying margin capture for pre-certified incumbents, a dynamic that concentrates procurement authority among buyers with pre-existing compliance infrastructure. Cloud-native event engineering talent scarcity extends implementation lead times, forcing platform vendors to absorb premium labor costs or sacrifice deployment velocity.
Pricing Analysis
Long-term multi-year SaaS contracts dominate enterprise procurement in the United States, with Fortune 500 buyers consolidating spend under single-vendor agreements that embed sub-150ms latency service level guarantees. Price differentiation rests on ISO 27001 certification tier and managed services bundling, with experiential marketing agencies in London and New York paying 40-60% premiums for immersive networking lounge capabilities. Cost compression in the mid-market webinar tier intensifies as Zoom Video Communications anchors integrated video infrastructure pricing. Nonprofit organizations exhibit highest price sensitivity, while financial services firms in Frankfurt and New York demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Just-in-time capacity provisioning through Kubernetes-orchestrated streaming stacks has displaced strategic infrastructure stockpiling as the dominant vendor posture, though European GDPR Article 17 compliance requirements force hybrid identity management reserves. Cloud infrastructure supply concentrates in the United States through AWS-Google Cloud-Azure triopoly dominance, with India PLI scheme incentives enabling emerging local data center construction. Raw material dependencies center on GPU compute capacity, CDN edge node distribution, and real-time transcription API licensing. Single-point-of-failure risk during peak concurrent load events constitutes the primary structural vulnerability. Distribution runs through direct enterprise sales teams for large deployments and self-service web portals for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Fortune 500 procurement teams consolidate multi-year virtual collaboration contracts, fragmenting previously departmental vendor relationships into centralized IT governance frameworks. Marketing and HR functions are losing autonomy to compliance-driven technology selection committees.
For Market Incumbents: Secure ISO 27001 certification moats through accelerated audit completion timelines to exclude emerging competitors from government and financial services pipelines. Invest in backward integration into managed production services to capture premium pricing from experiential marketing agencies lacking internal cloud engineering capacity. The threat of WebRTC technical ceilings beyond 500 concurrent video streams demands server-side relay infrastructure investment. For New Entrants and Emerging Players: Lead with India-hosted platform deployments targeting price-sensitive APAC buyers leveraging PLI scheme infrastructure incentives. White-space concentration sits in immersive networking lounges for experiential marketing agencies in London and New York, where 40-60% pricing premiums persist over commoditized webinar formats. A channel partnership go-to-market model with local telecom operators bypasses direct competition with established SaaS vendors. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-automation play because EU AI Act algorithmic transparency requirements and GDPR data residency mandates deepen vendor moats through extended sales cycles and certification barriers. Acquisition targets should exhibit hybrid deployment architecture capabilities and pre-existing CNIL or BfDI audit relationships. The signal to watch is procurement department consolidation velocity in United States healthcare and financial services verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamless handoff between existing Zoom or Teams deployments reduces buyer switching friction. |
| Geographic Expansion | India PLI scheme incentives enable local data center construction for APAC price-sensitive buyers. |
| Strategic Partnership | Hybrid infrastructure partnerships with local telecom operators bypass transcontinental latency penalties. |
| Product Launch | Generative AI content moderation tools open premium pricing tiers for SEC-compliant investor relations events. |
| Acquisition of Specialist Firm | Immersive networking lounge capabilities capture 40-60% pricing premiums from experiential marketing agencies. |
Research Methodology
A standing panel of CTOs, IT procurement officers, platform engineers, and channel partners provided ongoing calibration against secondary validation from SEC filings, hyperscaler capex disclosures, and enterprise software vendor 10-K segment disclosures. Primary interviews with Fortune 500 technology and financial services firms in the United States, German industrial conglomerates, and London experiential marketing agencies combined with bottom-up deployment volume estimates and top-down addressable market sizing through triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment architecture, solution offering, application vertical, and end-user procurement authority dimensions. CAGRs derived from elastic capacity demand curves and compliance-driven procurement cycle extensions. Industry-specific forecast inputs included WebRTC technical ceiling constraints and EU AI Act algorithmic transparency documentation burdens.
The analysis sits within stated boundaries; outcomes outside sustained hybrid work permanence or accelerated GDPR enforcement timelines would require recalibration. Forecasts reflect assumptions regarding cloud infrastructure triopoly stability and cloud-native event engineering talent availability. Revision becomes warranted when AWS-Google Cloud-Azure concentration risk materializes in peak load failures or when generative AI content moderation triggers fresh regulatory scrutiny beyond current EU AI Act classifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media and Entertainment Technologies
North America Digital Scent Technology Market
Digital Media and Entertainment Technologies
United States Digital OOH Advertising Market
Digital Media and Entertainment Technologies
Digital OOH Market
Digital Media and Entertainment Technologies
Video Switchers Market
Digital Media and Entertainment Technologies
VR Content Creation Services Market
Digital Media and Entertainment Technologies
Digital Scent Technology Market
Digital Media and Entertainment Technologies
Healthcare Gamification Market
Digital Media and Entertainment Technologies
Europe Digital Scent Technology Market
Digital Media and Entertainment Technologies
Digital Media Adapters Market