
 VR Content Creation Services Market | 2026-2036
VR Content Creation Services Market Size, Share, and Industry Trends Forecast 2026-2036
VR Content Creation Services Market Analytics
The shift from in-house production to outsourced specialist studios is broadening the addressable supplier base for enterprise clients. Felix and Paul Studios leverages its cinematic pedigree to dominate premium documentary and live-action VR. Magnopus sustains competitive positioning through deep technical integration with real-time engine pipelines. Groove Jones LLC anchors its growth in branded experiential marketing campaigns for Fortune 500 clients.
VR Content Creation Services encompass the design, production, and optimization of immersive digital environments rendered through head-mounted displays, requiring stereoscopic 3D rendering at 90 frames per second minimum to prevent motion sickness. These services convert architectural blueprints, training curricula, or entertainment scripts into navigable virtual spaces for commercial deployment. Interactive Experience services command premium pricing due to complex branching logic and haptic integration requirements. Gaming applications absorb the largest share of production hours, though Training deployments generate superior per-project margins through multi-year enterprise licensing. Unity-based workflows retain dominant share among mid-budget productions, while Unreal Engine concentrates in high-fidelity cinematic and automotive visualization segments.
The Federal Communications Commission governs wireless transmission standards for untethered VR hardware, directly affecting content distribution specifications. The European Union's GDPR and emerging AI Act impose data governance and algorithmic transparency requirements on personalized immersive experiences. China's Ministry of Industry and Information Technology administers content approval frameworks for domestically distributed virtual reality applications. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs increasingly determine viable market entry strategies.
Market Dynamics
Enterprise procurement of surgical training modules is concentrating production demand among specialist studios capable of FDA-validated haptic integration, compressing project timelines from eighteen months to under six months for repeat healthcare clients.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements for immersive content generation tools are creating compliant-first vendor selection criteria that favor established studios with legal infrastructure.
- Automotive visualization pipelines:Unreal Engine adoption for real-time vehicle configurators is pulling specialist render farms into long-term service contracts with German and Japanese manufacturers.
- Los Angeles studio density:Geographic clustering of cinematic VR talent enables rapid crew assembly for premium documentary projects, reducing pre-production overhead.
Market Restraints
- GPU supply volatility:Render farm operators face input cost instability from NVIDIA H100 allocation constraints, compressing margins on fixed-bid enterprise projects.
- 90 FPS technical floor:Stereoscopic rendering at motion-sickness-prevention thresholds demands specialized optimization labor that cannot be automated through standard game engine workflows.
- China MIIT approval timelines:Content authorization frameworks for domestically distributed VR applications extend commercialization cycles by eight to fourteen months.
Strategic Opportunities
- India medical training penetration:CDSCO-recognized surgical simulation modules remain underdeployed in tier-two hospital networks, creating whitespace for localized content adaptation.
- Generative AI texture synthesis:Convergence of diffusion models with photogrammetry pipelines is collapsing environment production costs for mid-budget architectural visualization.
- Fortune 500 experiential marketing:Branded immersive activations at retail and trade events are shifting from pilot budgets to annual recurring commitments.
Industry Challenges
- Stereoscopic compositor scarcity:Post-production specialists capable of 360-degree spatial audio-video synchronization command premium rates that inflate project overhead.
- ISO 13485 certification timelines:Medical device content validation for haptic surgical trainers requires eighteen-month quality system implementation before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Content Creation Services Market |
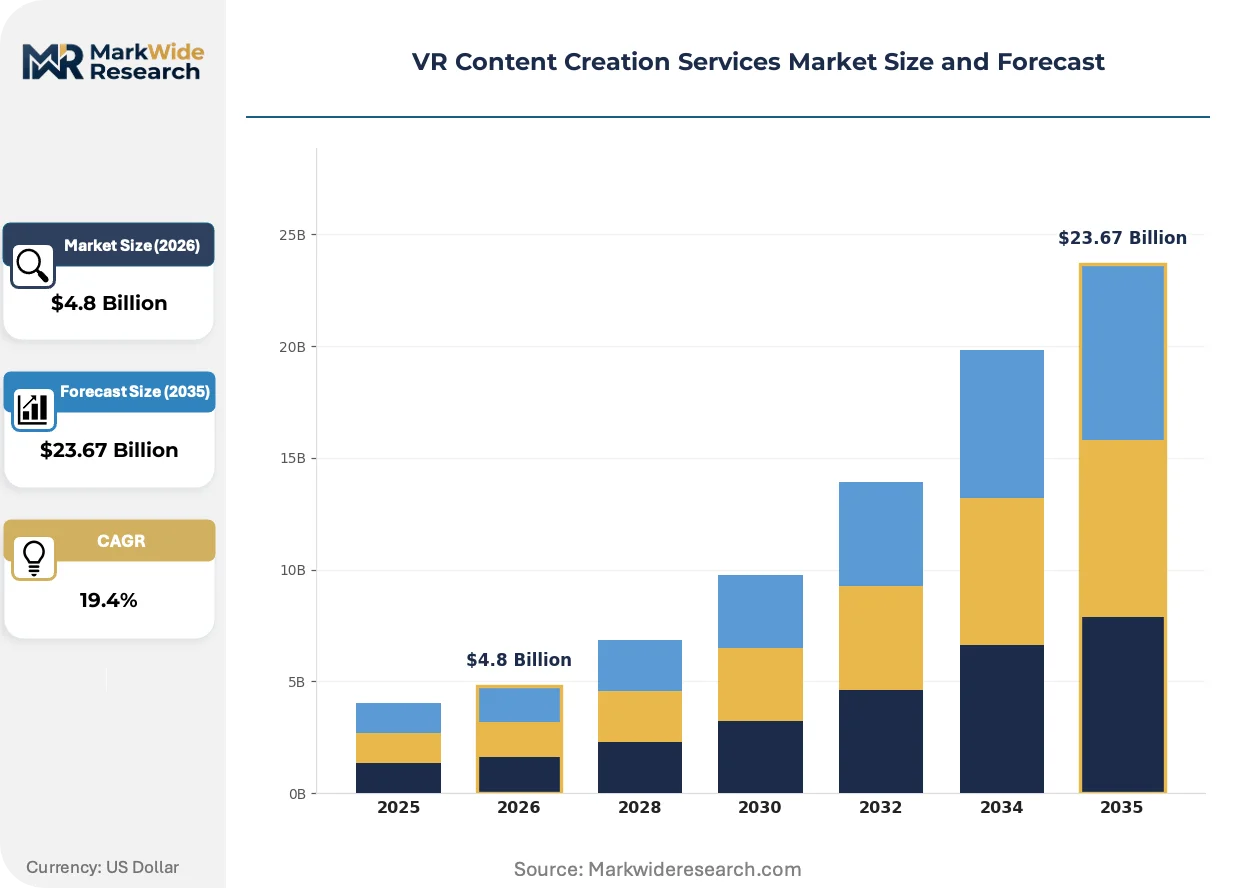
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $23.67 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 3D Animation, Live Action, Interactive Experience, Virtual Simulation End User: Entertainment, Education, Real Estate, Healthcare Technology: Unity, Unreal Engine, WebXR, Oculus Application: Gaming, Training, Marketing, Tourism |
| Companies Covered | Felix and Paul Studios, Magnopus, Voxel Digital Studios Inc., Groove Jones LLC, Innoactive GmbH, Wevr Inc., Trigger XR Inc., Framestore, Subvrsive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Content Creation Services Market Evolving Landscape
Real-time engine pipelines are displacing offline render farms as the dominant production infrastructure, compressing iteration cycles and enabling live client review sessions that reshape project economics.
Neural radiance fields (NeRFs) are converging with traditional photogrammetry workflows to enable volumetric capture of human performers without green screen infrastructure. Healthcare training divisions at major hospital networks are adopting this technology for patient interaction simulations. The compression of capture-to-deployment timelines is converging with enterprise demand for rapid curriculum updates.
The EU AI Act's algorithmic transparency obligations are forcing studios to document training data provenance and generation parameters for personalized immersive experiences. Industrial consequence includes mandatory audit trails that increase pre-production legal overhead. Healthcare and automotive visualization segments are responding by segregating EU-bound content into dedicated compliance workflows.
Enterprise buyers are consolidating vendor relationships around studios offering end-to-end service bundles spanning capture, optimization, and hardware deployment. The spot-contract model for individual VR experiences is yielding to multi-year framework agreements with volume commitments. This concentration is most visible in United States Fortune 500 procurement, where marketing and training divisions now maintain approved supplier lists of three to five specialist studios.
VR Content Creation Services Market Segmentation
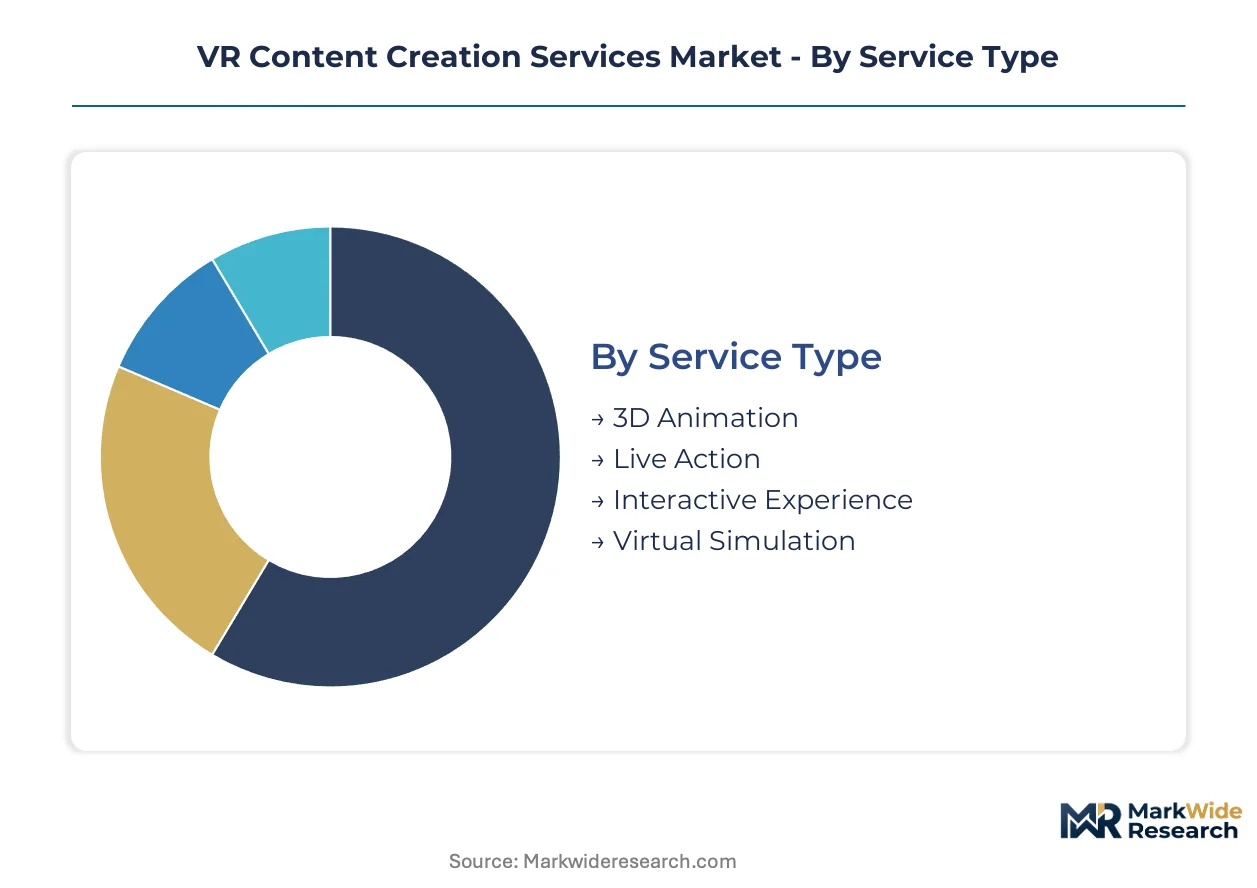
VR content creation services fragment across technical, sectoral, and platform dimensions, each carrying distinct regulatory burdens and margin profiles. Certification requirements for healthcare and automotive deployments create tiered vendor qualification barriers that reshape competitive access across segments.
Service Type:
ISO 13485 certification governs medical-grade Virtual Simulation and Interactive Experience segments, while 3D Animation and Live Action operate under lighter creative industry standards. FDA validation timelines extend eighteen months for haptic-integrated surgical trainers.
- 3D Animation:Stereoscopic asset pipelines generate navigable environments from architectural blueprints and product CAD files. Demand concentrates in automotive visualization studios serving German and Japanese manufacturers, where real-time configurators require photoreal material shaders.
- Interactive Experience:Branching narrative logic with haptic feedback integration commands premium pricing through multi-year enterprise licensing. Healthcare procurement of FDA-validated surgical modules compresses production timelines from eighteen months to under six months for repeat clients.
- Live Action:Cinematic VR capture employs volumetric stages and spatial audio arrays for documentary and branded content production.
- Virtual Simulation:Physics-based environment replication for training scenarios requires CDSCO, FDA, or PMDA device classification depending on deployment geography.
3D Animation sits at the top of the volume ranking, with Interactive Experience climbing the fastest.
End User:
Cost tier stratification separates entertainment budgets from healthcare procurement, where ISO-certified quality systems justify 3-4x production premiums over commercial gaming projects.
- Healthcare:Surgical training modules and patient interaction simulations demand FDA, EMA, or PMDA validation with haptic hardware integration. Enterprise licensing models generate superior per-project margins through multi-year hospital network deployments.
- Entertainment:Gaming and cinematic content absorbs the largest share of production hours with shorter iteration cycles and lower compliance overhead. Los Angeles and San Francisco studio clusters enable rapid crew assembly for premium documentary projects.
- Education:Institutional procurement of curriculum-aligned immersive modules spans K-12 through vocational retraining applications.
- Real Estate:Architectural visualization and virtual property tours employ photogrammetry pipelines for pre-construction marketing.
Entertainment captures the highest absolute production hours, while Healthcare delivers the steepest margin expansion trajectory.
Technology:
Supply concentration around Unity and Unreal Engine creates platform-specific vendor expertise, with WebXR emerging for browser-distributed enterprise training.
- Unreal Engine:Nanite virtualized geometry and Lumen dynamic lighting dominate high-fidelity automotive and cinematic segments. German and Japanese manufacturers anchor long-term render farm contracts for real-time vehicle configurators.
- Unity:Cross-platform deployment and mid-budget accessibility retain dominant share among mobile VR and training applications. Fortune 500 marketing divisions favor Unity-based experiential activations for trade event scalability.
- WebXR:Browser-native immersive experiences bypass app store approval timelines for enterprise training distribution.
- Oculus:Meta's hardware-software integration targets consumer gaming and social VR applications with store-gated distribution.
Unity holds the widest deployment base, with Unreal Engine gaining share fastest in premium visualization.
Application:
Customer type divergence separates pilot-budget marketing activations from recurring training commitments with multi-year framework agreements.
- Training:Enterprise surgical, technical, and safety simulations require regulatory validation with haptic hardware bundling. FDA-validated modules command eighteen-month quality system implementation before commercial deployment.
- Gaming:Consumer entertainment applications absorb the largest absolute production hours with 90 FPS technical floors for motion sickness prevention. GPU supply volatility from NVIDIA H100 allocation constraints compresses margins on fixed-bid projects.
- Marketing:Branded immersive activations at retail and trade events are shifting from pilot budgets to annual recurring commitments among Fortune 500 procurement divisions.
- Tourism:Destination preview and cultural heritage experiences employ photogrammetry and NeRF volumetric capture for monument replication.
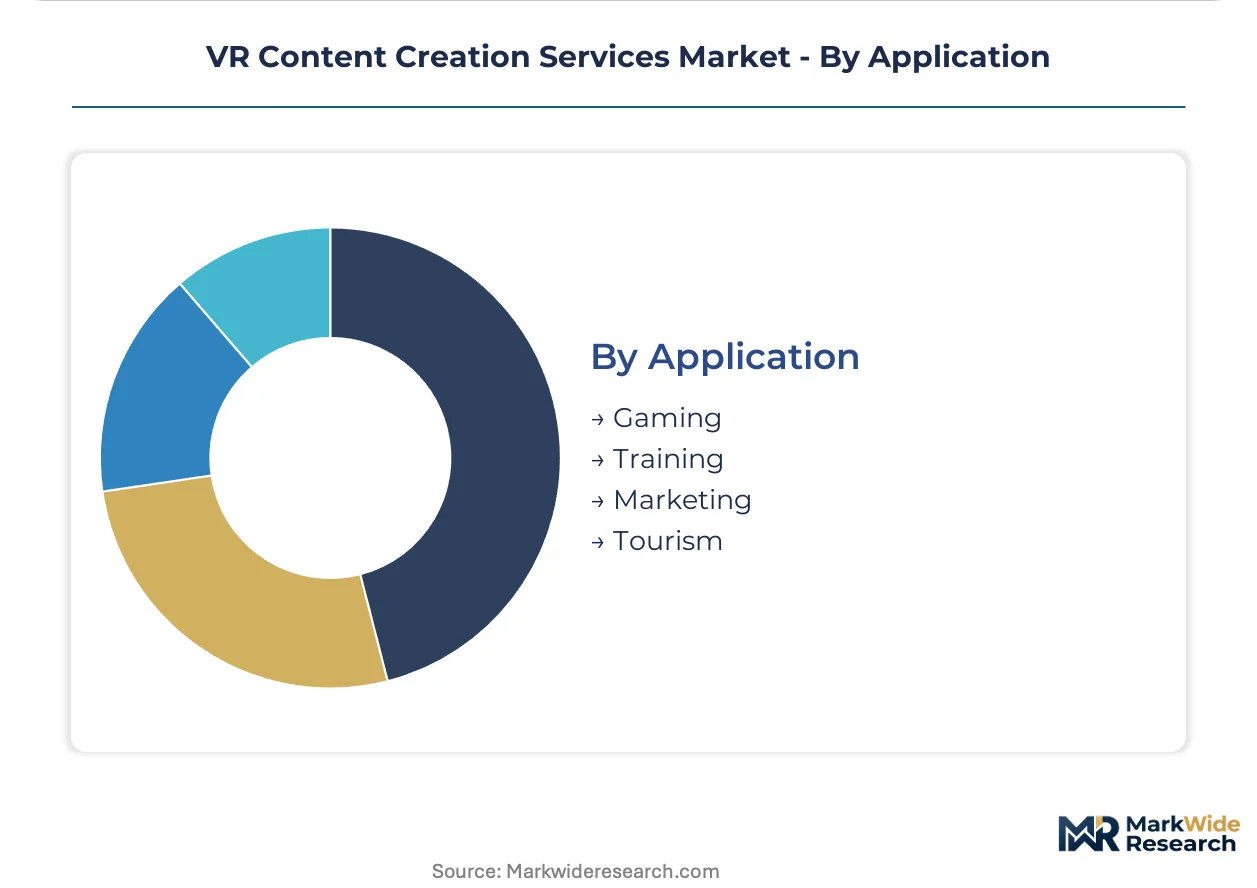
Gaming leads absolute production volume, with Training expanding most quickly through enterprise licensing conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as studios migrate toward jurisdictions with streamlined content approval frameworks. The cost-of-compliance gap between the United States and China exceeds fourteen months in commercialization timelines. This divergence concentrates premium documentary production in North American clusters while enterprise training modules shift toward European compliance-first infrastructure.
United States
FDA-validated surgical training procurement and Fortune 500 experiential marketing budgets anchor demand. FCC wireless transmission standards govern untethered hardware distribution specifications. Los Angeles and San Francisco host the densest specialist studio clusters, enabling rapid crew assembly for premium cinematic VR projects.
Germany
Automotive manufacturers commission Unreal Engine-based real-time vehicle configurators through long-term render farm contracts. KBA vehicle certification requirements extend to immersive visualization tools used in dealer networks. Bavaria and Baden-Württemberg concentrate technical integration specialists serving German and Japanese OEMs.
China
Domestic VR application distribution requires MIIT content authorization extending commercialization cycles by eight to fourteen months. National pharmaceutical regulator validation pathways for surgical simulation remain under development. Beijing and Shanghai studio clusters focus on compliance-first production for state-approved educational and cultural heritage deployments.
United Kingdom
GDPR data governance requirements and emerging EU AI Act transparency obligations filter vendor selection toward established studios with legal infrastructure. NHS procurement of patient interaction simulations creates demand for ISO-certified quality systems. London anchors post-production specialists capable of 360-degree spatial audio-video synchronization.
India
CDSCO-recognized surgical simulation modules remain underdeployed in tier-two hospital networks, creating whitespace for localized content adaptation. Central Drugs Standard Control Organization device classification governs medical-grade VR deployment. Maharashtra and Karnataka host emerging technical studios targeting medical training penetration with cost-optimized production pipelines.
VR Content Creation Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent experiential marketing and automotive visualization spaces. The vendor base stratifies across three capability tiers: cinematic documentary specialists, enterprise training integrators, and branded activation studios. Two dominant competitive moves are reshaping positioning: multi-year framework agreements replacing spot contracts, and real-time engine pipeline adoption displacing offline render infrastructure.
Within the cinematic documentary tier, Felix and Paul Studios exemplify premium live-action VR production anchored in North American talent clusters. Magnopus occupies a position among technical integration specialists with deep real-time engine capabilities. Groove Jones LLC represents the branded experiential marketing archetype, serving Fortune 500 procurement divisions with annual recurring commitments.
| Leading Market Players |
|---|
| Felix and Paul Studios |
| Magnopus |
| Voxel Digital Studios Inc. |
| Groove Jones LLC |
| Innoactive GmbH |
| Wevr Inc. |
| Trigger XR Inc. |
| Framestore |
| Subvrsive |
| Others |
Value Network & Pricing Analysis
Enterprise procurement of FDA-validated surgical training modules is compressing project timelines from eighteen months to under six months, forcing specialist studios to absorb upfront certification costs and recover margins through multi-year licensing structures that stratify pricing by compliance tier.
Pricing Analysis
Input-cost pass-through from NVIDIA H100 GPU allocation constraints is compressing margins on fixed-bid enterprise projects, particularly for render farm operators serving automotive visualization pipelines. Pricing stratifies across ISO 13485-certified medical-grade tiers, Unreal Engine premium visualization tiers, and Unity-based mid-budget production tiers. Cost compression in the mid-budget segment is intensifying because generative AI texture synthesis is collapsing environment production timelines. Fortune 500 experiential marketing divisions show lowest price sensitivity due to annual recurring commitment structures, while tier-two hospital networks in emerging markets exhibit highest sensitivity to per-module licensing fees.
Supply Chain Analysis
Reverse-logistics flows for haptic hardware refurbishment are emerging as studios recover and redeploy surgical training peripherals across multi-year hospital network deployments, creating secondary revenue streams that offset initial equipment subsidies. Hardware component sourcing concentrates in Taiwan, South Korea, and the United States for GPU and display panel supply. Raw material dependencies span photogrammetry equipment, spatial audio arrays, and motion capture sensors. Single-source vulnerability around NVIDIA GPU allocation creates supply chain risk for fixed-bid render farm contracts. Distribution runs through direct enterprise sales teams for healthcare and automotive verticals, with agency intermediaries handling branded experiential marketing activations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VR Content Creation Services Market functions as a stable compounder anchored by enterprise training procurement that converts pilot budgets into multi-year framework agreements with predictable renewal economics.
For Market Incumbents: To counter generative AI-driven cost compression in mid-budget architectural visualization, deepen ISO 13485 certification coverage across European and Asian regulatory jurisdictions, and secure exclusive multi-year render farm contracts with German and Japanese automotive manufacturers to lock in volume commitments before competitive entry. For New Entrants and Emerging Players: Launch via CDSCO-recognized surgical simulation partnerships with tier-two hospital networks in Maharashtra and Karnataka, targeting localized content adaptation whitespace that incumbent studios have deprioritized due to lower per-project margins, with cost-optimized Unity-based production pipelines as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with technical integration specialists possessing deep Unreal Engine capabilities and existing FDA validation track records. The five-to-ten year viability window favors studios with proven multi-year enterprise licensing conversion. Monitor EU AI Act compliance infrastructure buildout as the inflection signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Quality System Implementation | FDA validation for haptic-integrated surgical trainers opens multi-year hospital network licensing. |
| Unreal Engine Pipeline Integration | Real-time vehicle configurators secure long-term render farm contracts with German OEMs. |
| Generative AI Texture Synthesis Adoption | Diffusion model convergence collapses environment production costs for mid-budget visualization. |
| EU AI Act Compliance Infrastructure | Mandatory audit trails for algorithmic transparency favor established studios with legal resources. |
| Multi-Year Framework Agreement Conversion | Fortune 500 procurement shifts from spot contracts to annual recurring experiential marketing commitments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with VR studio executives, healthcare procurement officers at hospital networks, automotive visualization directors, experiential marketing leads at Fortune 500 brands, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EMA medical device registrations, FCC wireless transmission standards, EU AI Act implementation guidance, and MIIT content approval databases. Bottom-up project pipeline analysis and top-down market sizing triangulated volume estimates.
Comparable-period anchoring tied projection models to historical production hour data, enterprise licensing conversion rates, and certification timeline benchmarks across the analysis window. Segmentation dimensions spanned service type, end-user vertical, technology platform, application purpose, and geographic regulatory cluster. CAGRs derived from regression analysis of production volume trends, input cost trajectories, and procurement pattern shifts. Forecast inputs included GPU supply allocation forecasts and healthcare training budget growth assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended China MIIT approval timelines or accelerated generative AI disruption of mid-budget production tiers. Practitioners should monitor NVIDIA GPU allocation policy shifts and EU AI Act enforcement precedent for early signals of competitive margin compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media and Entertainment Technologies
Video Switchers Market
Digital Media and Entertainment Technologies
Digital Scent Technology Market
Digital Media and Entertainment Technologies
Digital Media Adapters Market
Digital Media and Entertainment Technologies
Digital OOH Market
Digital Media and Entertainment Technologies
Europe Digital Scent Technology Market
Digital Media and Entertainment Technologies
North America Digital Scent Technology Market
Digital Media and Entertainment Technologies
Global Virtual Event Platform Market
Digital Media and Entertainment Technologies
Healthcare Gamification Market
Digital Media and Entertainment Technologies
United States Digital OOH Advertising Market