
 Healthcare Gamification Market | 2026-2036
Healthcare Gamification Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Gamification Market Analysis
Hospital procurement for gamified patient engagement platforms is consolidating around integrated health system buyers with population-scale chronic disease management needs. Akili Interactive Labs anchors its position through FDA-cleared prescription game products for pediatric ADHD. Microsoft Corporation leverages its cloud infrastructure and Azure Health Data Services to compete for enterprise contracts with large provider networks. Bunchball Inc. specializes in loyalty-engine adaptations for wellness program administrators seeking measurable adherence outcomes.
Healthcare gamification applies game-design elements—point systems, progress visualization, social competition, and variable reward schedules—to clinical workflows, wellness programs, and therapeutic interventions, typically operating through software platforms that integrate with electronic health records and biometric sensors. Its primary commercial purpose is to sustain patient behavioral adherence where traditional reminder systems fail, particularly in chronic conditions requiring daily self-management. Mobile apps and wearable devices represent the most penetrated technology segments, though virtual reality applications for pain management and rehabilitation command premium pricing due to hardware bundling and specialized clinical validation requirements. Cloud-based delivery dominates implementation scale, while on-premises installations persist among pharmaceutical firms managing proprietary clinical trial participant data under strict protocol controls.
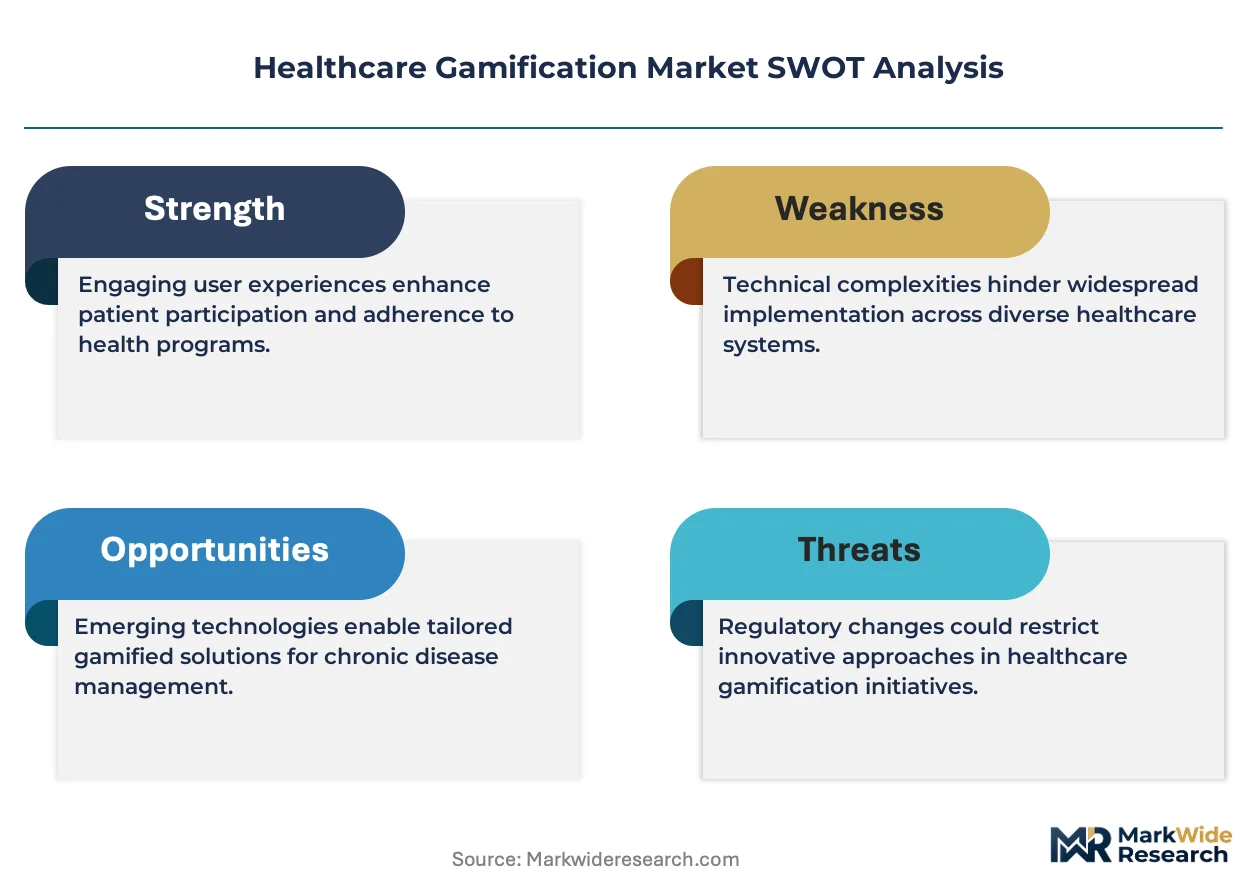
The FDA's software-as-a-medical-device framework and HIPAA privacy requirements shape product architecture decisions for any gamified platform handling protected health information in the United States. The EMA's digital therapeutics guidance and GDPR data processing constraints create parallel compliance obligations for European market entrants, while China's NMPA digital health review pathways determine access for foreign-developed platforms. Stakeholders must monitor how reimbursement policy evolution for prescription digital therapeutics in Medicare Advantage and commercial plans reshapes the business model viability of clinically validated versus wellness-oriented gamification offerings.
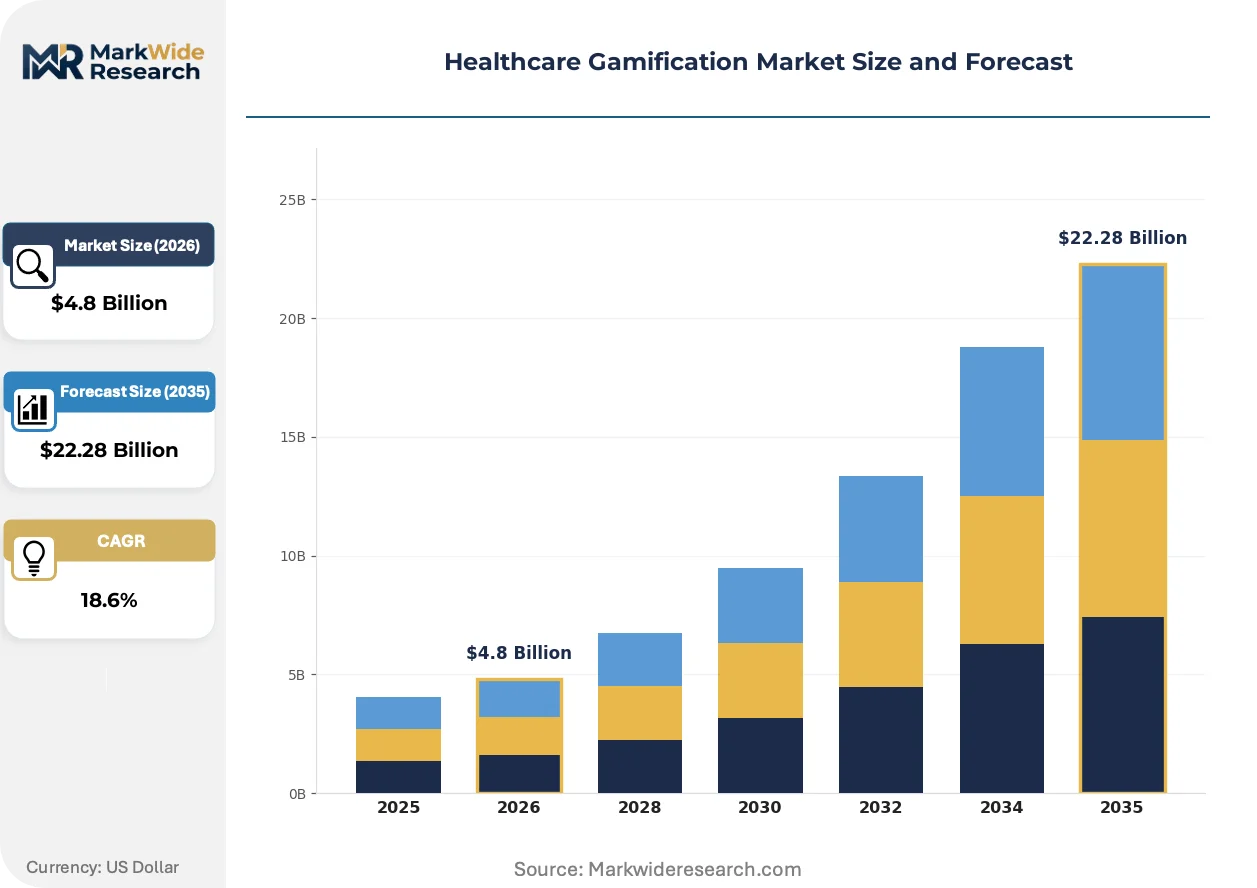
Market Dynamics
Prescription digital therapeutics reimbursement experimentation in United States Medicare Advantage and commercial plans is compressing the validation timeline for clinically validated gamified interventions versus wellness-oriented offerings.
Growth Catalysts
- FDA Software-as-a-Medical-Device Framework:The FDA's evolving digital health guidance creates clearer pathways for therapeutic game developers seeking prescription status. Pediatric ADHD applications have already secured clearance, establishing precedent for neurological condition expansion.
- Cloud Infrastructure Maturation:Microsoft Azure Health Data Services and competing platforms enable health system-scale deployment without on-premises hardware investment. Hospital procurement teams now evaluate gamification platforms through enterprise IT lens rather than point-solution procurement.
- Chronic Disease Burden Concentration:United States health systems face unsustainable costs from diabetes, cardiovascular disease, and behavioral health conditions requiring daily patient self-management. Gamified adherence interventions demonstrate measurable outcomes in populations where traditional reminder systems fail.
Market Restraints
- Clinical Validation Cost Structure:Randomized controlled trials for FDA clearance require $15-50 million investment per therapeutic indication. Wellness-oriented platforms without prescription claims face reimbursement exclusion.
- Data Localization Requirements:China's NMPA digital health review pathways mandate domestic server infrastructure for foreign-developed platforms. European GDPR constraints add compliance overhead exceeding North American deployment costs.
- Hardware Bundling Margin Pressure:Virtual reality pain management applications require specialized headset procurement. Premium pricing for bundled hardware solutions limits addressable market to well-capitalized health systems.
Strategic Opportunities
- Sub-Saharan Africa Mobile-First Penetration:Smartphone ubiquity and limited specialist physician density create conditions for gamified chronic disease management without competing legacy infrastructure. M-Pesa payment integration enables novel reimbursement models.
- EMA Digital Therapeutics Guidance Expansion:The European Medicines Agency's evolving framework for prescription digital therapeutics creates parallel market access pathway. Germany's DiGA fast-track process offers 12-month provisional reimbursement during evidence generation.
- Biometric Sensor Convergence:Continuous glucose monitors, blood pressure wearables, and sleep trackers generate real-time data streams. Gamification platforms integrating these feeds enable dynamic difficulty adjustment based on physiological state.
Industry Challenges
- Behavioral Science Talent Scarcity:Effective gamification requires expertise in variable reward scheduling, loss aversion framing, and social proof mechanics. Health technology firms compete with entertainment and fintech sectors for qualified behavioral economists and game designers.
- EHR Integration Complexity:Epic, Cerner, and Meditech systems maintain proprietary data architectures. Gamification platforms require custom API development for each health system deployment, extending implementation timelines.
- Reimbursement Code Uncertainty:CPT code assignment for prescription digital therapeutics remains contested. Payer medical policy variability across United States state lines complicates national rollout planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Gamification Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Patient Engagement, Behavioral Change, Wellness Promotion, Health Education End User: Healthcare Providers, Insurance Companies, Pharmaceutical Firms, Patients Technology: Mobile Apps, Wearable Devices, Virtual Reality, Online Platforms Delivery Mode: Cloud-Based, On-Premises, Hybrid Solutions, Self-Service |
| Companies Covered | Bunchball Inc., Nike Inc., Akili Interactive Labs Inc., Google LLC, Microsoft Corporation, Ayogo Health Inc., Fitbit Inc., Cognifit Inc., Mango Health Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Gamification Market Emerging Trajectories
Artificial intelligence inference at the edge is compressing latency for real-time adaptive gameplay in therapeutic applications. Regulatory convergence around software qualification criteria is reshaping competitive moats.
Edge AI processing in smartphones and wearables is unifying biometric signal interpretation with gameplay adaptation. Rehabilitation centers in Germany and pain management clinics in the United States deploy systems that adjust exercise difficulty within 200 milliseconds based on motion capture and heart rate variability. This architecture eliminates cloud round-trip dependency, enabling clinically validated response times for motor control applications.
The FDA's enforcement discretion policy for low-risk wellness software is narrowing as prescription digital therapeutics gain reimbursement traction. Developers previously operating in gray zone between wellness and medical device classification face reclassification pressure. United States-based platforms with FDA-cleared products now embed compliance documentation as competitive differentiator in health system RFP responses.
Hospital procurement committees are consolidating vendor evaluation under chief information officer oversight rather than departmental silos. Integrated delivery networks in Texas, California, and New York now mandate FHIR standard compliance and SOC 2 Type II attestation as table stakes. This centralization favors enterprise-scale platform providers with dedicated health system implementation teams over point-solution vendors.
Healthcare Gamification Market Segmentation
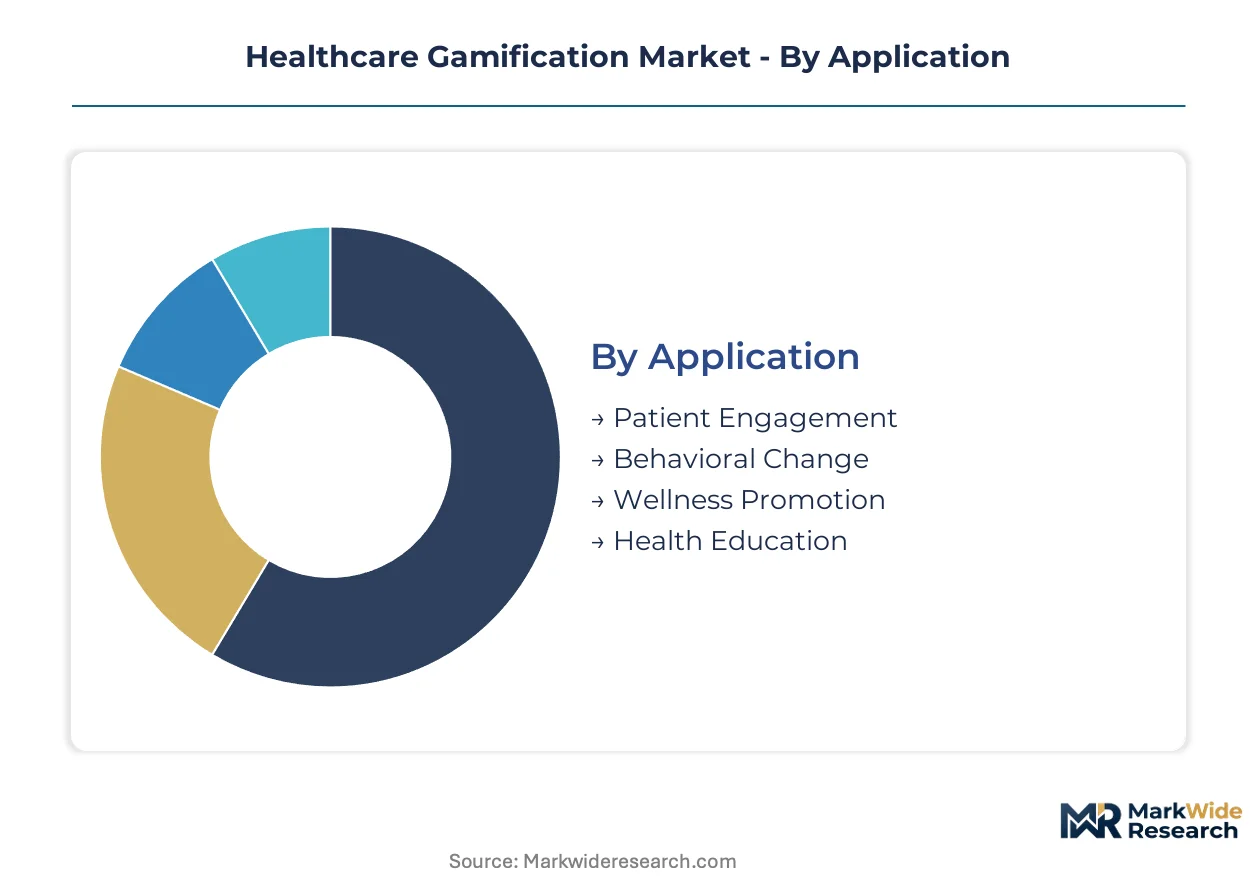
Healthcare gamification segments reflect divergent buyer economics. Hospital procurement teams evaluate platforms through enterprise IT criteria, while pharmaceutical firms prioritize data sovereignty. Reimbursement pathways for prescription digital therapeutics compress validation timelines for clinically validated applications versus wellness-oriented offerings.
Application:
Hospital chief information officers prioritize measurable adherence outcomes over engagement metrics alone. Procurement committees now mandate integration with Epic and Cerner systems as baseline requirements.
- Patient Engagement:Platforms deploy point systems, progress visualization, and variable reward schedules to sustain daily self-management in chronic conditions. Demand concentrates in United States integrated delivery networks managing diabetes and cardiovascular populations where traditional reminder systems fail. FDA-cleared products for pediatric ADHD establish precedent for neurological condition expansion.
- Behavioral Change:Therapeutic interventions apply loss aversion framing and social proof mechanics to modify health-related behaviors. Germany's DiGA fast-track process enables provisional reimbursement during evidence generation, accelerating European deployment. Behavioral science talent scarcity constrains platform effectiveness across all geographies.
- Wellness Promotion:Corporate wellness program administrators seek measurable adherence outcomes through loyalty-engine adaptations.
- Health Education:Medical schools and patient advocacy organizations deploy interactive modules for condition-specific knowledge transfer.
Volume sits with Patient Engagement; growth tilts toward Behavioral Change.
End User:
Procurement authority is migrating from departmental silos to centralized IT governance. Integrated delivery networks now consolidate vendor evaluation under chief information officer oversight.
- Healthcare Providers:Hospital systems deploy gamified platforms for population-scale chronic disease management. Texas, California, and New York integrated delivery networks mandate FHIR standard compliance and SOC 2 Type II attestation. Cloud infrastructure maturation enables health system-scale deployment without on-premises hardware investment.
- Insurance Companies:Payer organizations experiment with reimbursement for prescription digital therapeutics in Medicare Advantage and commercial plans. United States medical policy variability across state lines complicates national rollout planning for platform developers.
- Pharmaceutical Firms:Clinical trial sponsors manage proprietary participant data under strict protocol controls, favoring on-premises installations.
- Patients:Direct-to-consumer wellness applications face reimbursement exclusion without prescription claims.
Revenue concentrates with Healthcare Providers; expansion accelerates fastest among Insurance Companies.
Technology:
Hardware bundling economics determine addressable market scope. Premium pricing for specialized equipment limits deployment to well-capitalized health systems.
- Mobile Apps:Smartphone ubiquity drives penetration across all geographies. Sub-Saharan Africa's limited specialist physician density creates conditions for mobile-first chronic disease management without competing legacy infrastructure. M-Pesa payment integration enables novel reimbursement models in Kenya and Nigeria.
- Wearable Devices:Continuous glucose monitors, blood pressure trackers, and sleep sensors generate real-time data streams. Edge AI processing in smartphones and wearables unifies biometric signal interpretation with gameplay adaptation, enabling 200-millisecond response times for motor control applications.
- Virtual Reality:Pain management and rehabilitation applications command premium pricing due to hardware bundling requirements.
- Online Platforms:Browser-based delivery supports health education and wellness promotion without device-specific dependencies.
Deployment volume favors Mobile Apps; steepest expansion trajectory belongs to Wearable Devices.
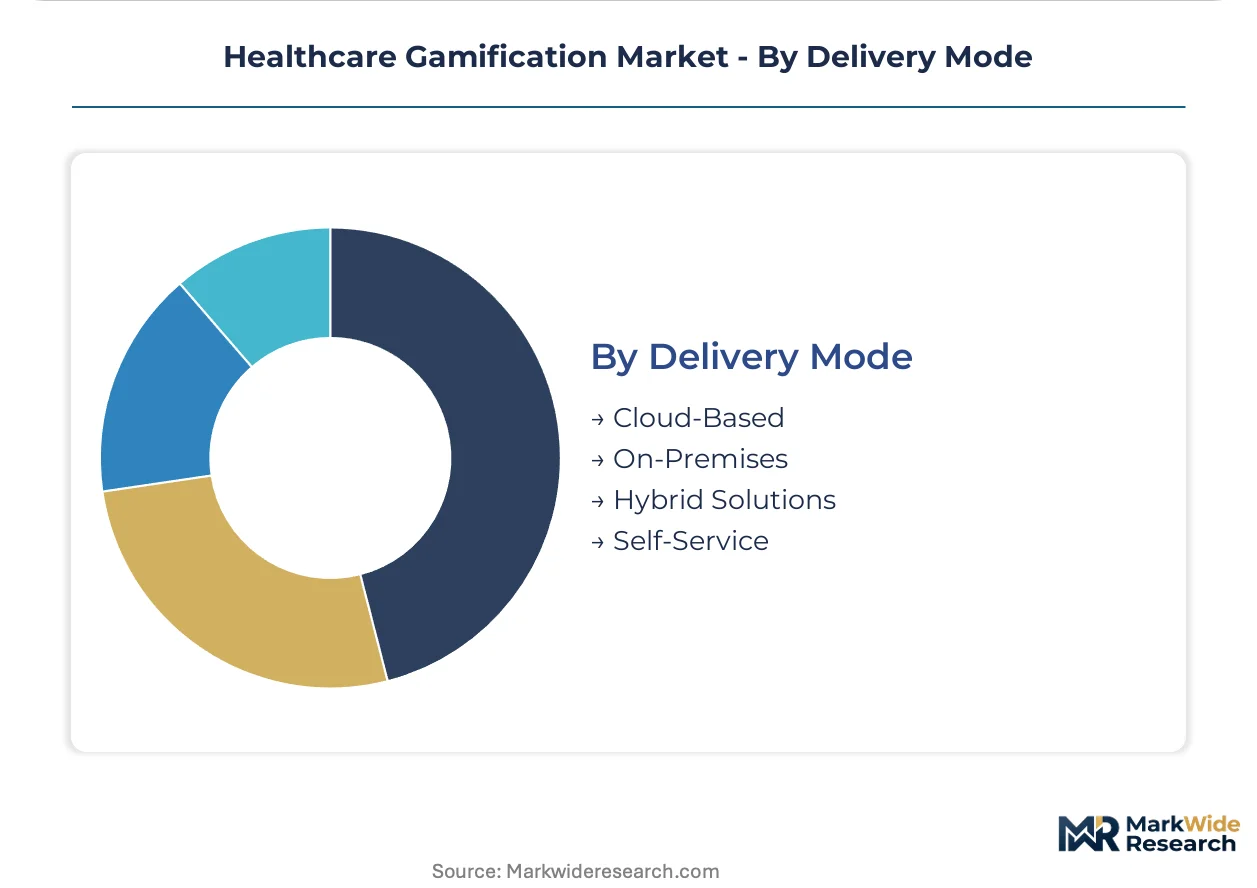
Delivery Mode:
Data localization mandates reshape architectural decisions for multinational platform developers. Compliance overhead varies dramatically across regulatory jurisdictions.
- Cloud-Based:Microsoft Azure Health Data Services and competing platforms dominate implementation scale. Hospital procurement teams evaluate gamification platforms through enterprise IT lens rather than point-solution procurement. China's NMPA digital health review pathways mandate domestic server infrastructure for foreign-developed platforms.
- On-Premises:Pharmaceutical firms managing proprietary clinical trial data under strict protocol controls maintain captive infrastructure. GDPR constraints add compliance overhead exceeding North American deployment costs for European installations.
- Hybrid Solutions:Health systems balance scalability with data sovereignty through mixed architectures.
- Self-Service:Small provider networks and direct-to-consumer applications favor low-touch deployment models.
Scale concentrates with Cloud-Based; regulatory pressure is forcing fastest adoption of Hybrid Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems concentrate procurement authority for gamified patient engagement platforms, with integrated delivery networks in Texas, California, and New York driving enterprise-scale deployment decisions. Reimbursement experimentation for prescription digital therapeutics accelerates provider willingness to integrate these interventions into standard care protocols.
United States
FDA-cleared prescription games for pediatric ADHD establish precedent for neurological condition expansion, with Medicare Advantage plans piloting reimbursement for clinically validated digital therapeutics. Texas Medical Center and Mayo Clinic anchor early adoption clusters for chronic disease management applications. Hospital procurement committees now mandate FHIR standard compliance and SOC 2 Type II attestation as baseline requirements.
Germany
DiGA fast-track process enables 12-month provisional reimbursement for digital health applications during evidence generation, accelerating European deployment timelines. EMA digital therapeutics guidance creates parallel market access pathway for prescription-grade platforms. Berlin and Munich health systems lead implementation of gamified rehabilitation programs with statutory health insurance integration.
China
NMPA digital health review pathways mandate domestic server infrastructure for foreign-developed platforms, reshaping architectural decisions for multinational developers. Chronic disease burden concentration in urban centers drives demand for mobile-first diabetes and cardiovascular management tools. Shanghai and Beijing hospital networks pilot AI-integrated therapeutic games with real-time biometric adaptation.
United Kingdom
NHS England's digital-first chronic disease management strategy creates procurement pipeline for adherence-focused platforms. MHRA software-as-a-medical-device framework shapes validation requirements for therapeutic game developers. London and Manchester integrated care systems consolidate vendor evaluation under chief information officer governance with population health management mandates.
India
CDSCO digital health guidance evolves alongside smartphone ubiquity in tier-1 and tier-2 cities, enabling chronic disease management without competing legacy infrastructure. Apollo Hospitals and Max Healthcare anchor private sector deployment for diabetes and hypertension self-management. Bengaluru and Hyderabad health-tech clusters develop localized gamification platforms with regional language adaptation.
Healthcare Gamification Market Vendor Landscape
United States technology conglomerates anchor one tier through cloud infrastructure and health data services; specialized therapeutic game developers hold differentiated positions through FDA clearance pathways. Market structure exhibits tiered concentration with enterprise-scale platform providers competing against point-solution vendors for health system contracts. Three archetypes dominate: prescription digital therapeutic specialists, cloud-native enterprise platforms, and wellness program loyalty engines. Competitive moves center on EHR integration partnerships and clinical validation investments for reimbursement eligibility.
Within the prescription therapeutic tier, Akili Interactive Labs occupies a position exemplifying FDA-cleared pediatric ADHD applications. Microsoft Corporation anchors enterprise-scale deployment through Azure Health Data Services and health system IT integration capabilities. Bunchball Inc. represents the wellness program specialization archetype, with loyalty-engine adaptations serving corporate wellness administrators seeking measurable adherence outcomes. These three companies collectively illustrate the strategic segmentation between clinically validated prescription products, infrastructure-backed enterprise platforms, and engagement-focused wellness solutions.
| Leading Market Players |
|---|
| Bunchball Inc. |
| Nike Inc. |
| Akili Interactive Labs Inc. |
| Google LLC |
| Microsoft Corporation |
| Ayogo Health Inc. |
| Fitbit Inc. |
| Cognifit Inc. |
| Mango Health Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-backed platform specialists have consolidated fragmented point-solution vendors across the United States and Germany, concentrating procurement leverage with integrated delivery networks while enforcing subscription pricing discipline through enterprise-scale contracts. This ownership pattern tightens margin pressure on standalone wellness app developers lacking FDA clearance pathways, forcing architectural choices toward cloud-native delivery that amortizes compliance costs across health system deployments.
Pricing Analysis
Volume concentrates in SaaS-tiered subscription models for hospital system deployments, while margin capture sits with prescription digital therapeutics commanding per-patient reimbursement rates. Price differentiation hinges on FDA clearance tier and EHR integration depth, with Epic-native platforms extracting premiums over API-limited competitors. Pricing pressure stems from Medicare Advantage reimbursement experimentation compressing wellness-oriented offerings toward commodity levels. Corporate wellness administrators exhibit highest price sensitivity, whereas Texas and California integrated delivery networks prioritize clinical validation over cost.
Supply Chain Analysis
Reverse-logistics flows remain minimal as cloud-based software delivery eliminates hardware refurbishment cycles, though VR pain management systems in German rehabilitation centers require headset calibration and sensor recalibration services. Supply concentration centers on United States cloud infrastructure providers, Chinese biometric sensor manufacturers, and Taiwanese semiconductor fabricators for wearable edge-AI processors. Component dependencies include continuous glucose monitor transmitters, motion capture cameras, and haptic feedback modules. Single-source vulnerability in FDA-cleared game engine licensing feeds distribution through health system procurement committees rather than direct channel sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare Gamification Market operates as a cost-of-compliance story where FDA software-as-a-medical-device framework investments create barrier-to-entry moats favoring cleared therapeutic developers over wellness-oriented competitors.
For Market Incumbents: Cement market position through exclusive EHR integration partnerships with Epic and Cerner, locking out point-solution competitors from health system RFP shortlists. Acquire behavioral science talent from entertainment and fintech sectors before compensation inflation erodes margin structures. Vertical integration into biometric sensor data streams defends against wearable-native entrants threatening platform stickiness. For New Entrants and Emerging Players: Enter via Sub-Saharan Africa mobile-first deployments where M-Pesa payment integration enables novel reimbursement models without competing legacy infrastructure. Target corporate wellness administrators in mid-market employers seeking measurable adherence outcomes below enterprise pricing tiers. White-label FDA-cleared game engines from established developers to compress validation timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor prescription digital therapeutic specialists with provisional DiGA reimbursement in Germany during evidence-generation windows. Long-term viability rests on reimbursement code consolidation eliminating payer policy variability across United States state lines. Watch Medicare Advantage medical policy harmonization as inflection signal for wellness-to-therapeutic reclassification pressure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Cleared pediatric ADHD products establish neurological expansion precedent for Akili Interactive Labs. |
| Hospital System Partnership | Texas Medical Center and Mayo Clinic deployments anchor chronic disease management adoption clusters. |
| Platform Integration | Microsoft Azure Health Data Services competes for enterprise contracts through FHIR-compliant architecture. |
| Reimbursement Strategy | Germany's DiGA fast-track enables 12-month provisional coverage during evidence generation phases. |
| Software Companion Development | Edge AI processing in wearables enables 200-millisecond gameplay adaptation for motor control applications. |
Methodological Framework
FDA 510(k) clearances, EMA digital therapeutics guidance documents, and CMS Medicare Advantage medical policy filings formed the secondary backbone, cross-referenced with primary interviews involving hospital chief information officers, behavioral health platform product managers, payer formulary directors, and GPO contracts specialists. Bottom-up sizing triangulated health system procurement database extracts against top-down cloud infrastructure spending allocations across the analysis window.
Historical trendline analysis of prescription digital therapeutic reimbursement pilots informed projection modeling across application segments, end-user archetypes, technology deployment modes, and regional regulatory clusters. CAGRs derived from segment-level growth rate convergence weighted by addressable population exposure. Forecast inputs incorporated EHR integration complexity scores and FDA enforcement discretion policy evolution.
Revisions become necessary when FDA software classification guidance shifts, Medicare Advantage medical policy harmonization accelerates, or NMPA data localization mandates expand beyond current server infrastructure requirements. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media and Entertainment Technologies
Digital Scent Technology Market
Digital Media and Entertainment Technologies
United States Digital OOH Advertising Market
Digital Media and Entertainment Technologies
Digital OOH Market
Digital Media and Entertainment Technologies
VR Content Creation Services Market
Digital Media and Entertainment Technologies
Europe Digital Scent Technology Market
Digital Media and Entertainment Technologies
Video Switchers Market
Digital Media and Entertainment Technologies
Digital Media Adapters Market
Digital Media and Entertainment Technologies
Global Virtual Event Platform Market
Digital Media and Entertainment Technologies
North America Digital Scent Technology Market