
 Europe Digital Scent Technology Market | 2026-2036
Europe Digital Scent Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Scent Technology Market Foresight
Healthcare providers is rotating toward digital scent platforms for non-invasive diagnostics and patient engagement, displacing earlier entertainment-centric deployments. Symrise AG leverages its fragrance compound library to anchor proprietary scent cartridges for medical applications. Aryballe competes through semiconductor-based olfactory sensors with solid-state architecture. Givaudan SA specializes in molecular encapsulation systems that extend scent release precision for therapeutic protocols.
Europe Digital Scent Technology encompasses electro-olfactory systems, aroma generators, and digital olfactory devices that transduce volatile organic compound signatures into machine-readable data through metal-oxide or optical sensor arrays, primarily serving diagnostic, immersive media, and ambient marketing functions. Electro-olfactory platforms lead technology investment due to their integration with portable diagnostics, while scented displays represent the fastest-expanding segment as retailers deploy them for point-of-sale differentiation. Aroma generators capture concentrated margin pools in healthcare therapy sessions where reimbursement pathways are stabilizing.
CE marking under the EU Medical Device Regulation governs clinical-grade olfactory devices, while REACH compliance constrains molecular formulations used in scent cartridges, and the EU AI Act imposes transparency requirements on diagnostic algorithms processing scent data. These frameworks elevate barriers for non-European suppliers while creating structured procurement channels for compliant domestic manufacturers. Stakeholders must monitor harmonized standards development for interoperable scent data formats across member states.
Market Dynamics
Healthcare procurement across Germany and France is displacing entertainment-centric deployments with clinical-grade olfactory diagnostics, forcing manufacturers to restructure R&D budgets toward CE marking compliance and therapeutic efficacy validation.
Growth Catalysts
- EU AI Act diagnostic transparency mandates:The regulation accelerates investment in explainable scent-data algorithms for clinical decision support, creating structured procurement channels for compliant device manufacturers.
- Automotive R&D clusters in Munich-Stuttgart corridor:Co-location with healthcare innovation hubs enables cross-pollination of sensor technologies between cabin air quality systems and portable diagnostic platforms.
- Solid-state metal-oxide sensor architectures:These semiconductor-based olfactory sensors reduce power consumption and form factor constraints, unlocking point-of-care deployment in ambulatory settings.
Market Restraints
- REACH molecular formulation constraints:The regulation restricts volatile organic compound libraries available for scent cartridges, compressing formulation flexibility and extending R&D cycles for therapeutic applications.
- Specialized polymer substrate supply concentration:German and Swiss specialty chemical suppliers dominate high-purity encapsulation materials for controlled scent release, creating input bottlenecks during demand surges.
- Optical sensor array calibration drift:Photonic olfactory platforms require frequent recalibration against reference standards, elevating total cost of ownership in distributed healthcare deployments.
Strategic Opportunities
- Underpenetrated Nordic hospital networks:Sweden and Denmark lack dedicated digital olfactory procurement frameworks, offering first-mover advantage for vendors establishing reimbursement pathways.
- Convergence with wearable continuous glucose monitors:Integration of scent-based metabolic biomarker detection with existing diabetic monitoring infrastructure creates combined diagnostic value propositions.
- EU Green Deal sustainable chemistry incentives:Bio-based molecular encapsulation systems qualify for green procurement preferences in public hospital tenders across France and the Netherlands.
Industry Challenges
- Cross-functional talent scarcity:Device manufacturers struggle to recruit chemists with simultaneous expertise in volatile organic compound synthesis and medical device quality management systems.
- CE marking timeline compression:The EU Medical Device Regulation's tightened clinical evidence requirements extend certification cycles for novel olfactory diagnostic modalities.
- Interoperable scent data format standardization delays:Absence of harmonized protocols across member states fragments health information exchange and complicates multi-site clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Scent Technology Market |
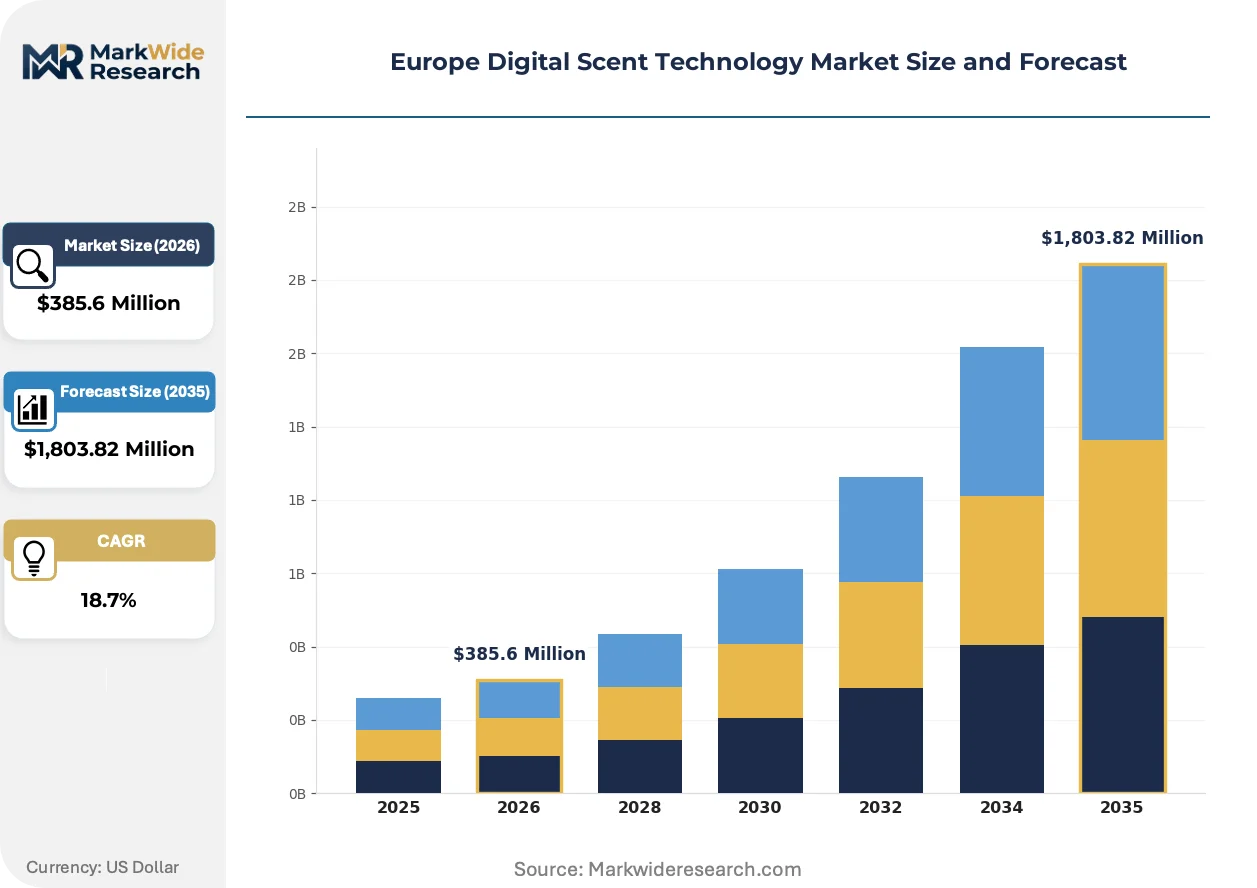
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Entertainment, Marketing, Healthcare, Virtual Reality Technology: Electro-Olfactory, Aroma Generators, Scented Displays, Digital Olfactory Devices End User: Consumers, Businesses, Healthcare Providers, Retailers Usage: Promotional Campaigns, Interactive Experiences, Therapy Sessions, Education |
| Companies Covered | Symrise AG, ams AG, Aryballe, Thermo Fisher Scientific Inc., AIRSENSE Analytics GmbH, Givaudan SA, Electronic Sensor Technology, Sensient Technologies Corporation, International Flavors & Fragrances Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Scent Technology Market Shifts & Advancements
Electro-olfactory platforms are compressing device footprints while regulatory frameworks harden algorithmic transparency requirements, reshaping competitive advantage toward integrated hardware-software compliance capabilities.
Metal-oxide semiconductor sensor arrays is miniaturizing through MEMS fabrication advances, enabling integration into smartphone-connected diagnostic accessories. French telemedicine providers are piloting these pocket-sized devices for remote respiratory infection screening. The technology is compressing the minimum viable product cost structure, opening subscription-based diagnostic service models previously uneconomical at larger form factors.
REACH authorization requirements for fragrance molecules are tightening supply chain documentation burdens, elevating compliance costs for cartridge manufacturers. The industrial consequence is accelerated backward integration into captive molecular synthesis capabilities among leading device makers. Therapeutic scent delivery systems face the most acute documentation requirements, driving consolidation of formulation expertise within vertically integrated European suppliers.
Hospital procurement departments are unbundling scent device hardware from consumable cartridge supply, forcing manufacturers to compete on separate economic terms for each revenue stream. The segment most disrupted is long-term care facilities, where volume-based cartridge contracts now dominate capital equipment tenders. This pattern is most visible in Germany's Rhineland-Palatinate region, where consortium purchasing organizations have standardized split-procurement frameworks across municipal hospital networks.
Europe Digital Scent Technology Market Segmentation
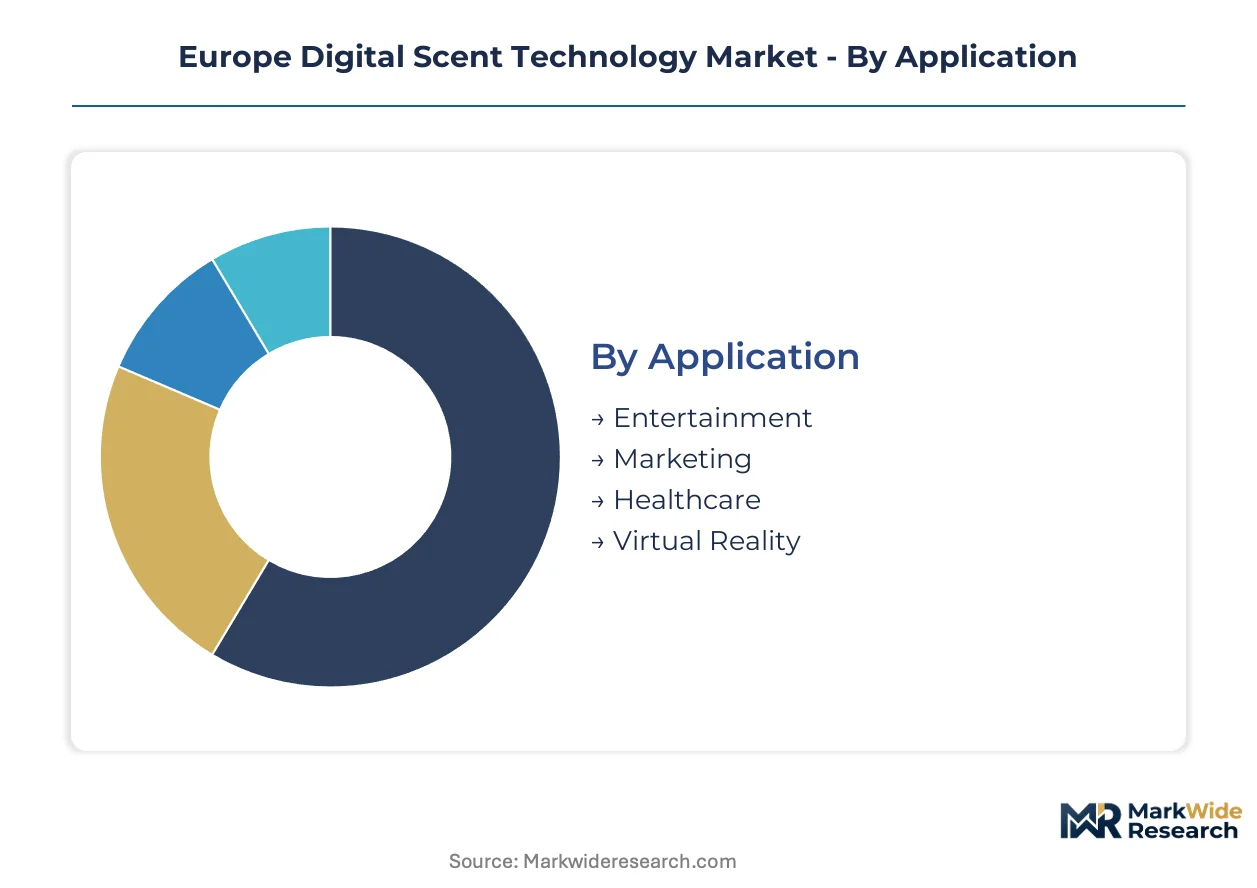
Segmentation in Europe's digital scent technology market reveals how regulatory frameworks and procurement patterns concentrate value across distinct technology-application combinations. Understanding these divisions exposes where CE marking investments and REACH compliance burdens reshape competitive positioning.
Application:
Margin pools concentrate in clinical deployments where reimbursement pathways stabilize, while entertainment applications face compressed pricing from consumer hardware commoditization.
- Healthcare:Non-invasive diagnostic protocols and therapeutic scent delivery command premium pricing through validated clinical outcomes. German hospital procurement networks in North Rhine-Westphalia and Bavaria are expanding tenders for olfactory-based respiratory screening and dementia care interventions.
- Marketing:Point-of-sale ambient scent systems generate recurring cartridge revenue streams with lower regulatory overhead than medical applications. French luxury retailers in Paris and Lyon deploy these for brand differentiation, though REACH molecular constraints limit formulation flexibility.
- Entertainment:Gaming and cinema applications face hardware margin pressure from smartphone-integrated alternatives.
- Virtual Reality:Immersive training simulations for automotive and aerospace sectors in Stuttgart and Toulouse drive specialized integration contracts.
The dominant share belongs to Healthcare, while Marketing is closing the gap fastest through retail digitization investments.
Technology:
Volume concentration follows solid-state manufacturing scalability, with semiconductor fabrication advances determining which architectures achieve smartphone-compatible form factors.
- Electro-Olfactory:Metal-oxide sensor arrays transduce volatile organic compound signatures into machine-readable data with minimal power draw. Munich-Stuttgart automotive clusters are cross-applying cabin air quality sensors for portable medical diagnostics, accelerating MEMS miniaturization roadmaps.
- Digital Olfactory Devices:Complete diagnostic platforms integrating hardware, software, and cloud analytics face extended CE marking timelines under EU Medical Device Regulation tightened clinical evidence requirements. French telemedicine providers pilot these for remote patient monitoring, creating subscription service models.
- Aroma Generators:Controlled release systems for therapeutic protocols capture concentrated margins in long-term care facilities.
- Scented Displays:Retail point-of-sale differentiation drives fastest volume expansion among consumer-facing deployments.
Electro-Olfactory platforms hold the installed base lead, though Digital Olfactory Devices are climbing the fastest through diagnostic reimbursement stabilization.
End User:
Procurement sophistication varies sharply, with healthcare providers demanding validated clinical evidence while retailers prioritize cartridge economics over hardware specifications.
- Healthcare Providers:Hospitals and clinics require CE-marked devices with documented therapeutic efficacy, creating structured tender processes that favor established European manufacturers. Germany's consortium purchasing organizations have standardized split-procurement frameworks separating capital equipment from consumable supply.
- Businesses:Corporate wellness programs and training facilities represent emerging demand with less stringent regulatory requirements than clinical settings.
- Retailers:Volume-based cartridge contracts now dominate procurement, compressing hardware margins.
- Consumers:Direct-to-market devices face pricing pressure from smartphone-integrated alternatives and limited reimbursement access.
Healthcare Providers command the technology roadmap, while Businesses are gaining share fastest through workplace wellness program expansion.
Usage:
Maturity gradients separate established promotional applications from emerging therapeutic protocols where clinical validation investments determine market access.
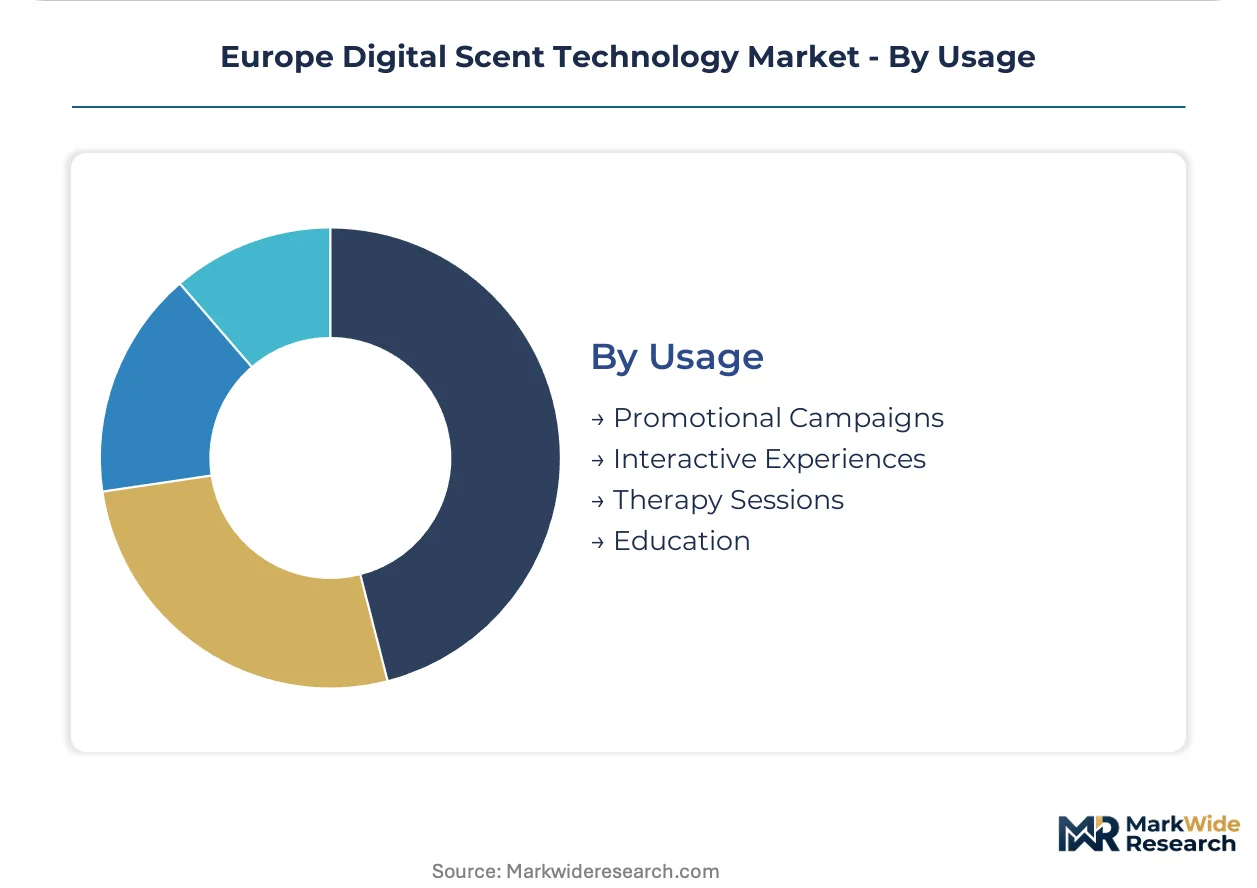
- Therapy Sessions:Scent-based interventions for anxiety, dementia, and chronic pain management require randomized controlled trial evidence for reimbursement eligibility. Dutch and Belgian long-term care networks are piloting standardized protocols, creating reference sites for broader European adoption.
- Interactive Experiences:Museum exhibitions and brand activations in London, Berlin, and Milan deploy immersive scent design with shorter sales cycles than medical applications.
- Promotional Campaigns:Seasonal retail activations face compressed planning horizons and price-sensitive procurement.
- Education:Olfactory learning tools for chemistry and medical training remain nascent with limited dedicated funding streams.
Therapy Sessions anchor premium pricing, while Interactive Experiences are expanding most quickly through experiential marketing budget growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports diagnostic-grade olfactory hardware to French hospital networks while Swiss specialty chemical suppliers feed molecular encapsulation materials downstream. This north-south trade corridor concentrates procurement sophistication in the Rhine-Rhine basin. Cross-border regulatory alignment under EU Medical Device Regulation accelerates device certification reciprocity between member states.
Germany
Hospital consortium purchasing in North Rhine-Westphalia and Bavaria drives tender volume for CE-marked diagnostic devices. The Federal Institute for Drugs and Medical Devices enforces tightened clinical evidence standards under EU MDR implementation. Munich-Stuttgart automotive clusters cross-apply cabin air quality sensors into portable medical diagnostics, compressing MEMS miniaturization timelines.
France
Telemedicine providers in Paris and Lyon pilot subscription-based scent diagnostic services for remote patient monitoring. The National Agency for Food, Environmental and Occupational Health Safety regulates volatile organic compound emissions under REACH authorization protocols. Toulouse aerospace training facilities integrate immersive scent systems into virtual reality simulators, creating specialized integration demand.
United Kingdom
London museum exhibitions and brand activations deploy interactive scent design with shorter sales cycles than medical applications. The Medicines and Healthcare products Regulatory Agency maintains parallel CE marking recognition post-Brexit, preserving market access for continental manufacturers. Greater Manchester health innovation clusters experiment with dementia care scent interventions in long-term care networks.
Netherlands
Public hospital tenders in Amsterdam-Rotterdam corridor prioritize bio-based molecular encapsulation systems qualifying for EU Green Deal procurement preferences. The National Institute for Public Health and the Environment monitors REACH compliance documentation for therapeutic scent cartridges. Eindhoven semiconductor fabrication expertise supports solid-state sensor array production for point-of-care devices.
Sweden
Underpenetrated hospital networks in Stockholm and Gothenburg lack dedicated digital olfactory procurement frameworks, offering first-mover positioning for vendors establishing reimbursement pathways. The Swedish Medical Products Agency aligns with EU MDR certification timelines while maintaining national variation in clinical evidence requirements. Uppsala life science clusters host pilot programs for scent-based metabolic biomarker detection integrated with wearable monitors.
Europe Digital Scent Technology Market Competitive Landscape
Listed leaders compete with private specialists across hardware-software integration capabilities, creating tiered competitive dynamics. The vendor base concentrates around fragrance compound archives, semiconductor sensor fabrication, and molecular encapsulation chemistry. Three archetypes dominate: diversified chemical conglomerates with captive scent libraries, precision sensor fabricators with MEMS capabilities, and therapeutic delivery specialists with clinical validation expertise. Capacity expansion in solid-state sensor foundries and backward integration into molecular synthesis represent the dominant competitive moves.
Within the diversified chemical tier, Symrise AG and Givaudan SA exemplify players leveraging proprietary fragrance archives to anchor medical-grade scent cartridges. Aryballe occupies a position among sensor specialists commercializing semiconductor-based olfactory platforms. These three represent distinct strategic positions: compound library control, solid-state hardware miniaturization, and integrated diagnostic platform development.
| Leading Market Players |
|---|
| Symrise AG |
| ams AG |
| Aryballe |
| Thermo Fisher Scientific Inc. |
| AIRSENSE Analytics GmbH |
| Givaudan SA |
| Electronic Sensor Technology |
| Sensient Technologies Corporation |
| International Flavors & Fragrances Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day cartridge inventory cycles at German hospital consortiums concentrate procurement leverage among buyers while semiconductor sensor lead times stretching to sixteen weeks anchor pricing power with Munich-Stuttgart foundries. This temporal asymmetry between consumable replenishment and capital equipment fabrication shapes margin distribution across the value chain, with therapeutic scent cartridge manufacturers facing compressed pricing from volume-based tenders while electro-olfactory hardware vendors defend premiums through MEMS miniaturization roadmaps.
Pricing Analysis
Next-generation solid-state sensor arrays command thirty to fifty percent premiums over legacy metal-oxide platforms, while prior-generation photonic systems face accelerating price erosion from calibration-intensive total cost of ownership. Three-tier pricing structure across CE-marked diagnostic, industrial-grade, and consumer-entertainment levels separates reimbursement-eligible therapeutic deployments from retail ambient marketing applications. Pricing pressure stems from REACH documentation burdens elevating molecular formulation costs, with long-term care facilities exhibiting highest price sensitivity due to fixed reimbursement ceilings while automotive R&D clusters show lowest sensitivity given integration value propositions.
Supply Chain Analysis
Strategic stockpiling of high-purity polymer substrates dominates inventory strategy among Dutch and Swiss encapsulation material suppliers, contrasting with just-in-time semiconductor wafer flows from Eindhoven foundries. German specialty chemical producers and Swiss precision polymer manufacturers anchor upstream supply concentration, while South Korean MEMS fabrication facilities feed sensor array demand. Raw material dependencies center on palladium catalysts for metal-oxide deposition, medical-grade silicone substrates, and rare-earth elements for photonic waveguides. Single-source vulnerability concentrates in Swiss molecular encapsulation expertise. Distribution runs through hospital consortium purchasing organizations in North Rhine-Westphalia and Bavaria, with direct-to-manufacturer contracts bypassing traditional device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from smartphone-integrated biosensor platforms that bypass dedicated olfactory hardware through software-defined scent inference, compressing addressable market boundaries for standalone devices.
For Market Incumbents: Consolidate backward integration into captive molecular synthesis capabilities to escape REACH documentation cost spirals, while anchoring sensor fabrication partnerships within Munich-Stuttgart automotive clusters to compress MEMS miniaturization timelines against smartphone-integrated substitute threats. Prioritize CE marking investment for therapeutic indication expansion before EU MDR clinical evidence requirements tighten further.
For New Entrants and Emerging Players: Lead with underpenetrated Nordic hospital networks in Stockholm and Gothenburg where reimbursement pathway establishment offers first-mover positioning absent entrenched vendor relationships. Target bio-based molecular encapsulation systems qualifying for EU Green Deal procurement preferences in Dutch public tenders, deploying subscription-based diagnostic service models to bypass capital equipment procurement friction.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because therapeutic scent delivery systems face extended validation timelines that favor incumbents with established clinical evidence archives, while sensor hardware commoditization pressures pure-play device manufacturers. Target acquisition archetypes combine fragrance compound libraries with semiconductor fabrication capabilities. Watch for reimbursement pathway stabilization in dementia care interventions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance opens structured procurement channels for clinical-grade olfactory diagnostics in German hospital networks. |
| Backward Integration into Molecular Synthesis | Captive formulation capabilities reduce REACH documentation burdens and compress therapeutic scent cartridge R&D cycles. |
| Hospital System Partnership | Consortium purchasing organization relationships in North Rhine-Westphalia secure volume-based cartridge contracts with embedded renewal clauses. |
| Software Companion Development | Explainable scent-data algorithms satisfy EU AI Act diagnostic transparency mandates for clinical decision support deployment. |
| Reimbursement Strategy | Randomized controlled trial evidence for anxiety and dementia interventions unlocks public payer coverage in Dutch long-term care networks. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers at German university hospitals, procurement managers at French telemedicine providers, regulatory affairs specialists navigating EU MDR implementation, and fragrance compound chemists at Swiss specialty chemical suppliers, then refined against secondary validation from EMA guidance documents, REACH authorization databases, hospital tender records in North Rhine-Westphalia and Bavaria, and automotive R&D cluster patent filings. Bottom-up demand modeling across electro-olfactory hardware installations and top-down market sizing through therapeutic application penetration rates were triangulated to constrain variance.
Variance decomposition across technology generation transitions, application maturity gradients, and geographic regulatory cluster adoption patterns structured the analytical framework over the projection horizon. Segmentation dimensions modeled include hardware architecture type, clinical versus non-clinical application, procurement channel structure, and reimbursement pathway status. CAGRs were derived from installed base growth trajectories and average revenue per unit compression curves, with MEMS miniaturization cost curves and REACH compliance cost escalations serving as primary industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside stable EU MDR implementation timelines and continued REACH authorization protocol continuity would require recalibration. Forecasts reflect assumptions regarding reimbursement pathway stabilization for therapeutic indications and semiconductor fabrication yield improvements. Revision becomes warranted when smartphone-integrated biosensor substitution rates cross clinical validation acceptance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media and Entertainment Technologies
Global Virtual Event Platform Market
Digital Media and Entertainment Technologies
North America Digital Scent Technology Market
Digital Media and Entertainment Technologies
Digital Media Adapters Market
Digital Media and Entertainment Technologies
Video Switchers Market
Digital Media and Entertainment Technologies
Healthcare Gamification Market
Digital Media and Entertainment Technologies
VR Content Creation Services Market
Digital Media and Entertainment Technologies
Digital OOH Market
Digital Media and Entertainment Technologies
Digital Scent Technology Market
Digital Media and Entertainment Technologies
United States Digital OOH Advertising Market