
 Digital OOH Market | 2026-2036
Digital OOH Market Size, Share, and Industry Trends Forecast 2026-2036
Digital OOH Market Analysis
The EU Green Deal is hardening energy-efficiency requirements for public infrastructure displays across European cities. JCDecaux leverages its street furniture concessions to deploy low-power LED networks in transit-heavy corridors. Lamar Advertising Company anchors its position through dominant billboard portfolios along US interstate corridors. Clear Channel Outdoor Holdings competes on programmatic trading platforms that connect advertisers to inventory in real time.
Digital out-of-home comprises networked electronic display systems installed in public and semi-public spaces, typically employing LED or LCD panels with brightness ratings exceeding 5,000 nits for daylight visibility, designed to deliver targeted advertising and information content to audiences in transit, retail, or urban environments. LED technology dominates new installations due to superior luminance efficiency and operational lifespan in exterior conditions. Dynamic ads represent the fastest-growing content category as advertisers shift from static creative to data-triggered messaging that responds to weather, traffic, or audience demographics. Retail displays command premium placement rates in high-dwell environments such as malls and grocery chains where purchase intent peaks.
The US Federal Communications Commission governs spectrum allocation for wireless content delivery to remote displays, while the EU F-Gas Regulation restricts refrigerants in climate-controlled outdoor enclosures, pushing manufacturers toward passive thermal designs. The EU AI Act introduces transparency obligations for algorithmic audience measurement systems that estimate viewer demographics. Stakeholders must monitor how privacy regulators in multiple jurisdictions treat biometric inference from camera-equipped screens, as compliance architecture will determine where advanced targeting capabilities remain deployable.
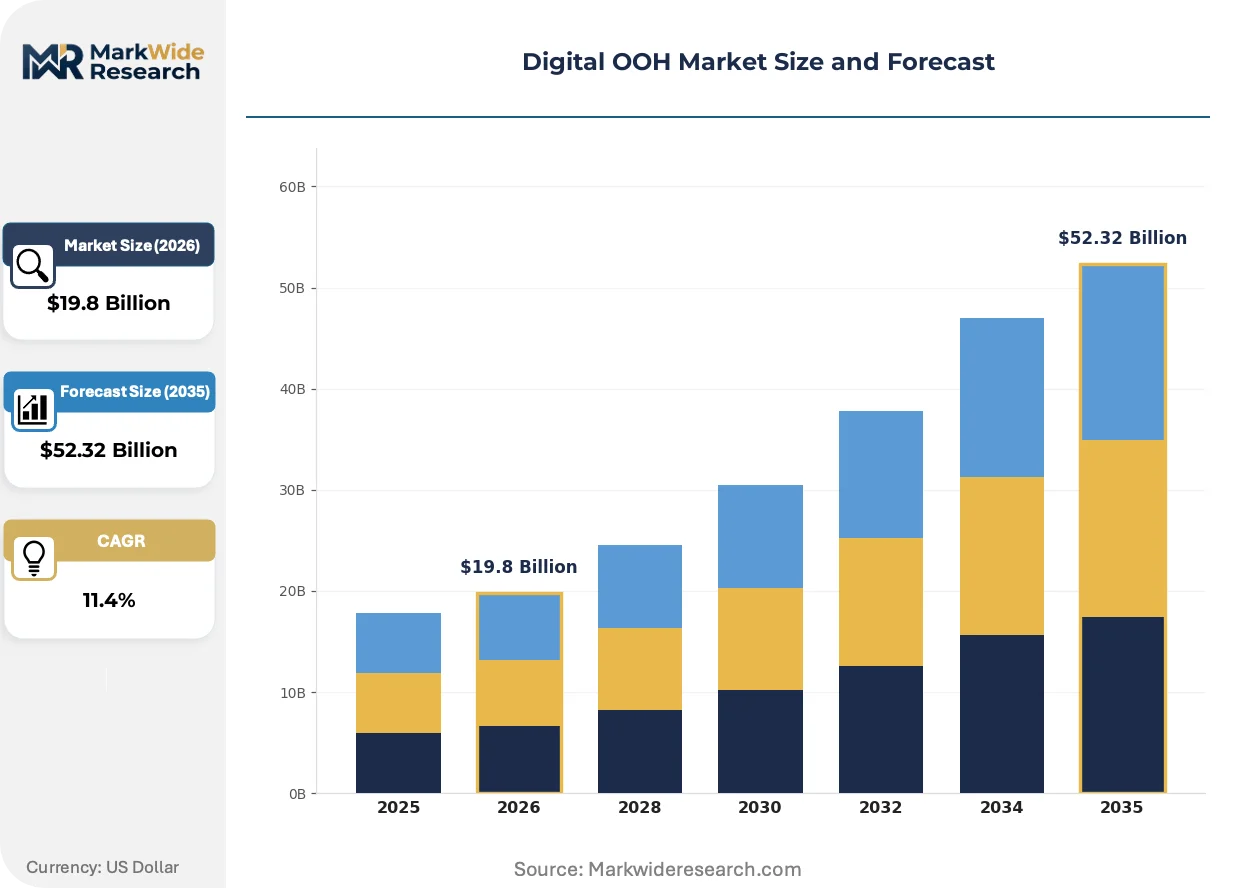
Market Dynamics
Programmatic trading platforms are compressing the gap between media buyers and digital inventory, collapsing traditional sales cycles while fragmenting audience targeting capabilities across networked screen operators.
Growth Catalysts
- EU Green Deal mandates:Energy-efficiency requirements for public infrastructure are accelerating LED retrofit programs across German transit hubs and French urban corridors.
- Transit authority screen expansion:Metropolitan rail operators in Spain, Italy, and the Netherlands are installing dense digital networks for real-time passenger communication.
- Dynamic creative technology:Data-triggered messaging systems that respond to weather and traffic conditions are displacing static billboard contracts in high-visibility locations.
Market Restraints
- LED panel supply concentration:Manufacturing of high-brightness outdoor displays clusters in East Asian component foundries, exposing operators to shipping volatility and input cost swings.
- EU F-Gas Regulation friction:Restrictions on refrigerants in climate-controlled outdoor enclosures are forcing manufacturers toward unproven passive thermal designs with shorter field histories.
- Biometric inference compliance uncertainty:Privacy regulators in France, Germany, and Italy are treating camera-equipped audience measurement systems inconsistently, freezing deployment of advanced demographic targeting.
Strategic Opportunities
- Retail pharmacy and convenience chains:High-dwell environments in suburban grocery and drugstore networks remain underpenetrated by programmatic-enabled screens.
- EU AI Act transparency obligations:Algorithmic audience measurement systems face new disclosure requirements that favor established vendors with compliance infrastructure over insurgent competitors.
- 5G private network convergence:Wireless content delivery to remote displays is expanding into mining, logistics, and agricultural applications previously unreachable by fiber.
Industry Challenges
- Technical workforce scarcity:Installation and maintenance of high-nit outdoor LED systems requires specialized electrical and thermal engineering skills concentrated among legacy signage technicians.
- Legacy CMS integration friction:Established screen networks operate on proprietary content management architectures that resist API connectivity with programmatic trading platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital OOH Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $52.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Billboards, Transit Displays, Retail Displays, Street Furniture Technology: LED, LCD, Projection, Digital Murals Content Type: Static Ads, Dynamic Ads, Interactive Content, Video Ads End User: Advertisers, Event Organizers, Brands, Media Companies |
| Companies Covered | Clear Channel Outdoor Holdings, JCDecaux, Lamar Advertising Company, Outfront Media, Ströer SE & Co. KGaA, oOh!media, APG|SGA, Broadsign International, Daktronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital OOH Market Emerging Trajectories
Three forces are compressing the traditional out-of-home value chain: wireless delivery infrastructure, algorithmic audience measurement, and automated trading platforms that bypass legacy sales intermediaries.
MicroLED modular display technology is expanding into premium transit and retail installations where maintenance access is restricted. Airport operators and rail authorities in Germany, France, and the Netherlands are specifying these panels for 24/7 operational environments. The technology is expanding into applications previously served by LCD video walls, compressing the addressable market for legacy backlighting systems.
The EU AI Act introduces transparency obligations for algorithmic systems that estimate viewer demographics from camera feeds. Operators deploying audience measurement tools must now document training data sources and inference methodologies. German and French regulators are enforcing these provisions most aggressively, pushing vendors toward simpler, non-biometric counting methods in those markets.
Media buyers are consolidating planning and execution through demand-side platforms that aggregate inventory across multiple screen networks. Brand advertisers in the United Kingdom and Spain are shifting budget from direct network contracts to programmatic guaranteed deals. This consolidation is most visible in London and Madrid, where dense screen concentration enables cross-network frequency capping and sequential messaging.
Digital OOH Market Segmentation
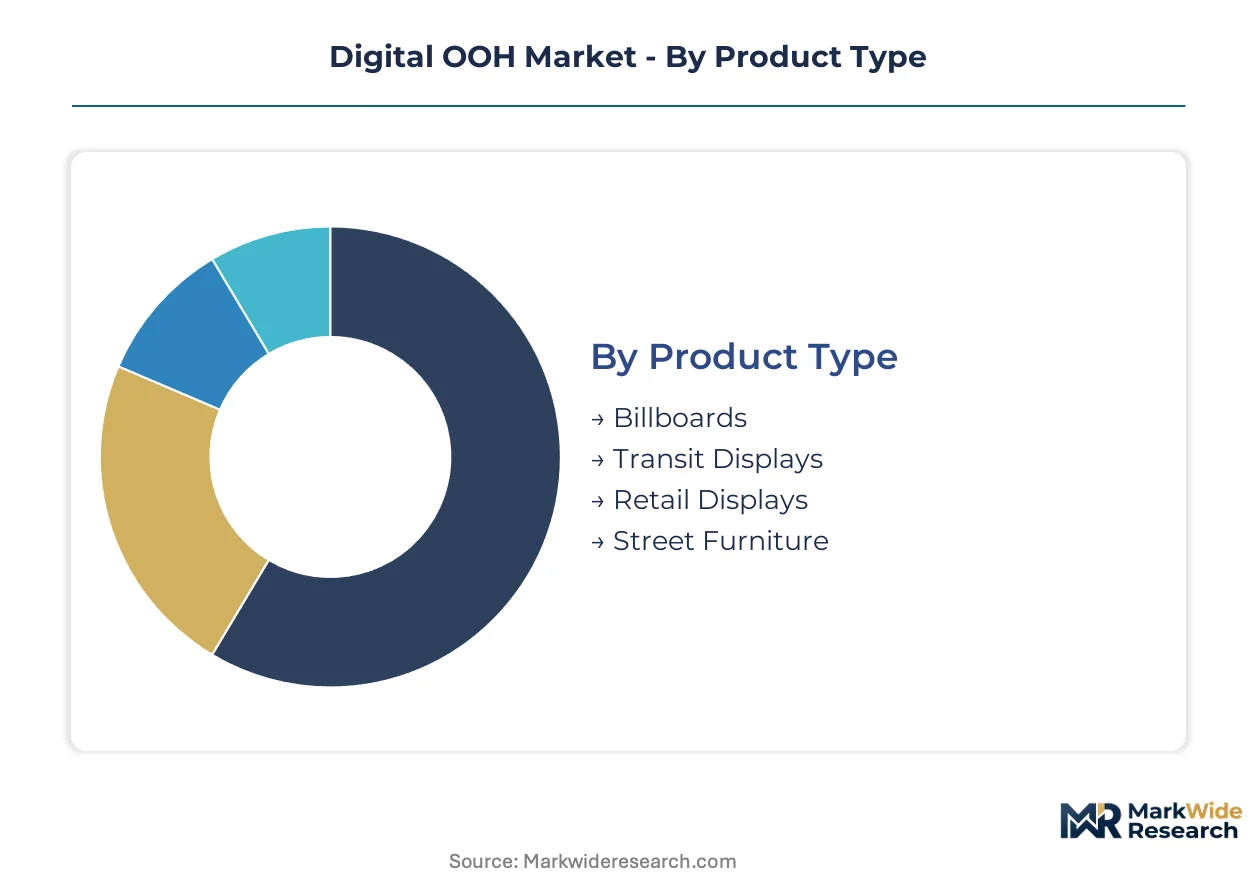
Digital OOH segmentation reveals how buyers prioritize visibility conditions, hardware durability, and audience dwell time when allocating campaign budgets across inventory types. Understanding these decision hierarchies enables operators to optimize placement density and pricing architecture.
Product Type:
Buyers select formats based on traffic velocity, viewing angle constraints, and regulatory clearance requirements for each urban environment.
- Billboards:Large-format LED installations exceeding 14 by 48 feet dominate interstate corridors and urban arterial roads. Demand concentrates along US interstate corridors where Lamar Advertising Company maintains dominant portfolios, though German autobahn networks and French périphérique routes show comparable density.
- Transit Displays:Networked screens in rail stations, bus shelters, and airport terminals deliver captive audiences during dwell periods. Metropolitan rail operators in Spain, Italy, and the Netherlands are expanding these networks for real-time passenger communication, with Ströer SE & Co. KGaA and JCDecaux operating dense configurations in German urban transit hubs.
- Retail Displays:Point-of-sale screens in malls and grocery chains capture purchase-intent moments.
- Street Furniture:Bus shelters, kiosks, and urban information panels integrate advertising with municipal services.
Billboards lead on scale; transit displays lead on momentum.
Technology:
Hardware selection hinges on luminance requirements, thermal management constraints, and maintenance access limitations.
- LED:High-brightness panels exceeding 5,000 nits enable daylight visibility in exterior conditions. New installations favor LED for superior luminance efficiency and operational lifespan, with EU Green Deal energy-efficiency mandates accelerating retrofit programs across member states.
- LCD:Backlit liquid crystal displays serve controlled indoor environments with lower ambient light interference.
- Projection:Laser and lamp-based systems enable temporary activations on building facades and irregular surfaces.
- Digital Murals:Large-scale LED mesh and flexible substrate installations conform to architectural contours.
LED commands installed base; digital murals are climbing the fastest.
Content Type:
Creative strategy determines whether campaigns prioritize brand awareness, contextual relevance, or direct response metrics.
- Dynamic Ads:Data-triggered messaging systems respond to weather, traffic, and audience demographics in real time. Advertisers in the United Kingdom and Spain are shifting budget toward these formats, displacing static billboard contracts in high-visibility locations.
- Video Ads:Full-motion creative leverages dwell time in transit and retail environments where audiences remain stationary.
- Static Ads:Fixed creative rotations persist in markets with limited programmatic infrastructure.
- Interactive Content:Touch-enabled and mobile-integrated experiences require higher engagement thresholds.
Video ads dominate revenue; dynamic ads show steepest expansion trajectory.
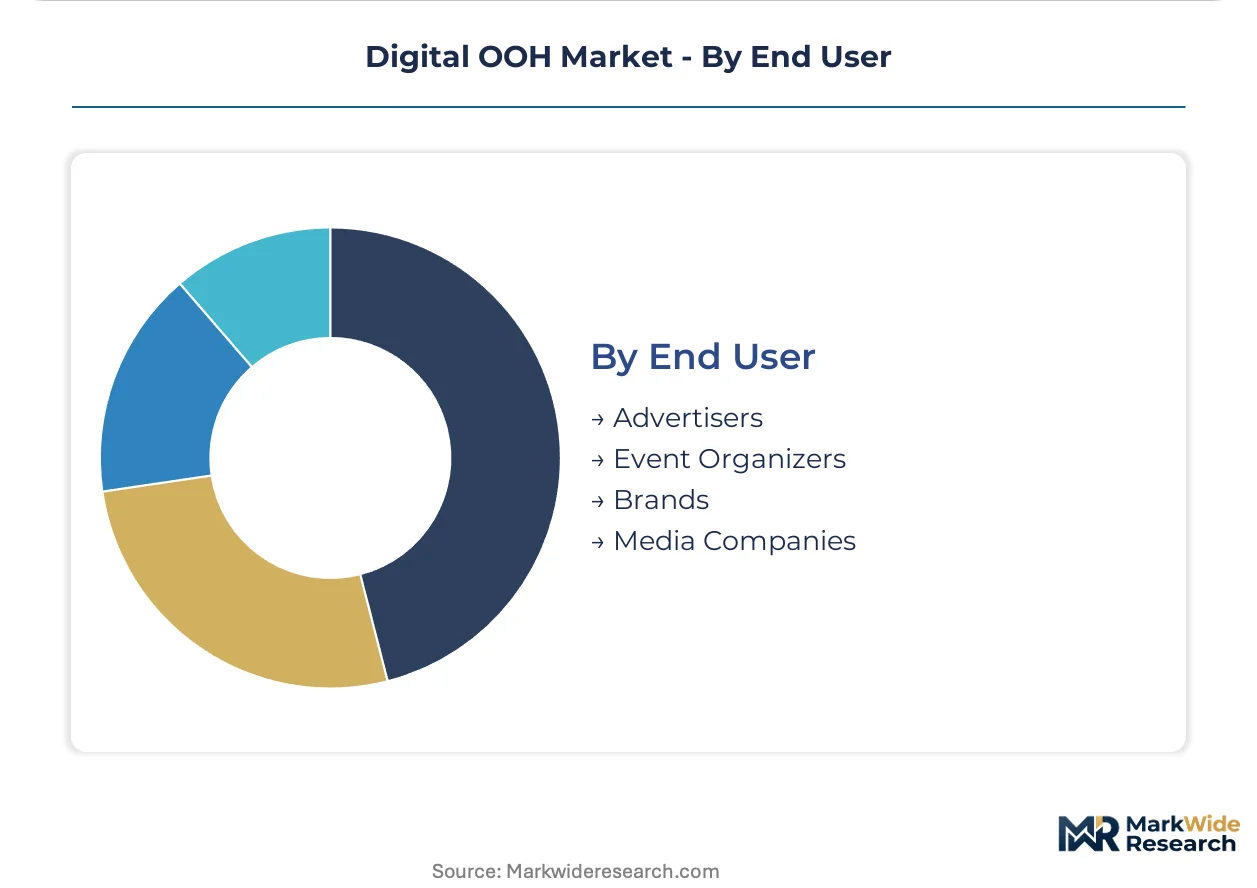
End User:
Procurement patterns diverge between centralized media buyers, decentralized brand managers, and event-specific operators.
- Brands:Consumer goods and automotive manufacturers purchase guaranteed inventory through programmatic platforms. Media buyers in London and Madrid are consolidating planning through demand-side platforms that enable cross-network frequency capping.
- Advertisers:Agencies and trading desks execute audience-based buys across multiple screen networks.
- Media Companies:Publishers extend digital inventory into physical environments to complement online reach.
- Event Organizers:Temporary installations for sports, cultural, and corporate activations require rapid deployment capabilities.
Brands anchor volume commitment; event organizers generate highest yield per screen hour.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital out-of-home infrastructure first achieved commercial scale in the United States during the 2000s, when Lamar Advertising Company and Clear Channel Outdoor Holdings converted static roadside inventories to electronic displays. European transit authorities subsequently adopted the model, with German and French operators now deploying the densest urban screen networks outside North America.
United States
Interstate corridor operators command the largest installed base of large-format LED billboards, with Lamar Advertising Company maintaining dominant positions along major highway routes. The FCC governs spectrum allocation for wireless content delivery to remote displays in rural markets. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate programmatic trading platform development, where demand-side platforms aggregate inventory across multiple screen networks.
Germany
Ströer SE & Co. KGaA operates dense digital screen networks across urban transit hubs, capturing dwell-time audiences in rail stations and bus shelters. The EU Green Deal's energy-efficiency mandates accelerate LED retrofit programs in municipal infrastructure. Berlin and Munich transit authorities specify high-brightness panels exceeding 5,000 nits for 24/7 operational environments.
France
JCDecaux leverages street furniture concessions to deploy low-power LED networks in transit-heavy corridors throughout Paris and Lyon. The EU AI Act introduces transparency obligations for algorithmic audience measurement systems, with French regulators enforcing these provisions aggressively. Île-de-France rail operators are expanding screen density for real-time passenger communication.
United Kingdom
Media buyers in London consolidate planning through demand-side platforms that enable cross-network frequency capping and sequential messaging. The country's national advertising regulator monitors privacy compliance for camera-equipped audience measurement systems. London's dense screen concentration supports programmatic guaranteed deals that displace traditional direct network contracts.
Spain
Metropolitan rail operators in Madrid and Barcelona install dense digital networks for real-time passenger communication, following the German transit authority model. Brand advertisers shift budget toward dynamic creative formats that respond to weather and traffic conditions. Madrid's urban corridor shows comparable screen density to London, enabling similar cross-network trading strategies.
Digital OOH Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the digital OOH value chain. Billboard operators owning physical real estate and concession contracts face pressure from technology vendors supplying programmatic trading infrastructure. Three archetypes dominate: integrated infrastructure owners controlling street furniture and transit concessions; pure-play technology platforms enabling automated inventory trading; and display hardware manufacturers supplying high-brightness LED panels. Competitive dynamics center on M&A activity consolidating concession portfolios and strategic partnerships linking legacy screen networks to programmatic demand-side platforms.
Among integrated infrastructure owners, JCDecaux, Lamar Advertising Company, and Ströer SE & Co. KGaA exemplify the concession-based model. JCDecaux represents the European transit-focused archetype, leveraging municipal contracts to secure dense urban screen placement. Lamar Advertising Company anchors the North American highway corridor segment through dominant billboard portfolios. Ströer SE & Co. KGaA occupies a position combining German transit authority relationships with retail network expansion. These three entities sit within the capital-intensive tier where real estate access determines competitive position more than technology differentiation.
| Leading Market Players |
|---|
| Clear Channel Outdoor Holdings |
| JCDecaux |
| Lamar Advertising Company |
| Outfront Media |
| Ströer SE & Co. KGaA |
| oOh!media |
| APG|SGA |
| Broadsign International |
| Daktronics |
| Others |
Supply Flow & Price Mechanics
Transit authority procurement concentration across German, French, and Spanish urban corridors anchors contract-based pricing for high-brightness LED installations. Municipal concession agreements favor multi-year service bundles over spot transactions, compressing price volatility while embedding maintenance obligations into headline rates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs screen procurement, with premium tiers capturing 24/7 transit authority specifications and economy tiers serving suburban retail networks. Price differentiation hinges on luminance certification grades and after-sales service bundling, where German operators demand field engineering coverage that Spanish retail chains often waive. Pricing pressure stems from LED panel oversupply in East Asian foundries, forcing European vendors toward shorter contract durations. Transit authorities exhibit lowest price sensitivity due to EU Green Deal retrofit mandates, while independent retail operators negotiate aggressively on hardware-only procurement.
Supply Chain Analysis
Refurbishment flows for failed LED modules create secondary supply channels that temper raw component demand spikes. Manufacturing concentrates in China, South Korea, and Taiwan, with high-brightness driver ICs and gallium nitride substrates drawing from semiconductor foundries concentrated in the same geographies. Supply chain risk centers on maritime logistics chokepoints between East Asian component ports and European assembly facilities. Distribution runs through specialized AV integrators holding JCDecaux and Ströer service contracts, bypassing traditional electronics wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's energy-efficiency mandates for public infrastructure function as a regulatory compounder, embedding sustained replacement demand into municipal procurement calendars across member states.
For Market Incumbents: Deepen concession portfolio density in German and French transit corridors before EU AI Act transparency obligations harden compliance barriers. Ströer and JCDecaux face emerging pressure from programmatic technology vendors disintermediating direct sales relationships; counter by captive supply of audience measurement algorithms and exclusive 5G private network partnerships with rail operators. For New Entrants and Emerging Players: Programmatic trading platforms offer a technology-first wedge into fragmented Spanish and Italian screen networks where legacy CMS architectures resist API connectivity. White-space targets include suburban pharmacy chains and convenience networks in Madrid and Barcelona corridors, where high-dwell environments remain underpenetrated. Go-to-market execution should emphasize dynamic creative capability bundled with hardware-as-a-service financing. For Investors and Strategic Acquirers: Infrastructure-focused private equity is the most active acquirer in this space, consolidating municipal concession portfolios ahead of EU regulatory harmonization. Long-term viability favors operators with embedded transit authority relationships and proprietary audience data streams. Monitor French CNIL and German KBA enforcement patterns on biometric inference systems as the critical inflection signal for deployable targeting technology.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Portfolio Consolidation | Ströer's acquisition of Berlin municipal contracts secures 15-year screen deployment rights with embedded pricing escalators. |
| Programmatic Platform Integration | Clear Channel's demand-side platform connects London media buyers to real-time inventory across 12 independent screen networks. |
| MicroLED Technology Transition | Airport operators in Frankfurt and Amsterdam specify modular panels for 24/7 operational environments with restricted maintenance access. |
| EU AI Act Compliance Infrastructure | JCDecaux's documentation of training data sources for Paris audience measurement satisfies French regulator transparency obligations. |
| 5G Private Network Deployment | German rail operators install wireless content delivery systems enabling real-time passenger information across 2,000+ remote displays. |
Methodological Framework
Bottom-up transit authority procurement modeling reconciled against top-down LED panel shipment tracking forms the analytical core. Primary interviews with network operations directors, municipal procurement officers, programmatic trading desk heads, and AV systems integrators were validated against secondary sources including EU F-Gas Regulation filings, FCC spectrum allocation records, SEC 10-K disclosures from listed operators, and customs data on high-brightness display imports. Triangulation across these channels resolves discrepancies between announced installation targets and verified hardware deliveries.
Historical trendline analysis of concession contract durations, retrofit program acceleration rates, and programmatic revenue penetration informs the projection framework. Segmentation dimensions span product type, technology node, content category, and end-user procurement pattern. CAGRs were derived from installed base growth curves adjusted for replacement cycles and EU regulatory compliance deadlines. Forecast inputs include transit authority capital expenditure plans and LED panel cost trajectories from East Asian component markets.
The model holds under sustained EU Green Deal enforcement and stable maritime logistics costs; deviation in tariff regimes or biometric privacy rulings would shift deployment timelines. Practitioners should monitor French CNIL enforcement actions and German KBA technical standards for early signals of audience measurement system viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media and Entertainment Technologies
North America Digital Scent Technology Market
Digital Media and Entertainment Technologies
United States Digital OOH Advertising Market
Digital Media and Entertainment Technologies
Healthcare Gamification Market
Digital Media and Entertainment Technologies
Europe Digital Scent Technology Market
Digital Media and Entertainment Technologies
Global Virtual Event Platform Market
Digital Media and Entertainment Technologies
Digital Media Adapters Market
Digital Media and Entertainment Technologies
Video Switchers Market
Digital Media and Entertainment Technologies
Digital Scent Technology Market
Digital Media and Entertainment Technologies
VR Content Creation Services Market