
 Video Switchers Market | 2026-2036
Video Switchers Market Size, Share, and Industry Trends Forecast 2026-2036
Video Switchers Market Analytics
The broadcast equipment distribution channel is narrowing as direct-to-broadcaster sales and specialized AV integrators consolidate procurement pathways. Blackmagic Design leverages aggressive pricing and integrated software-hardware bundles to capture independent production houses. Sony Corporation anchors premium broadcast tiers through its established service networks and 4K/8K product depth. Ross Video competes in live production workflows with modular switcher architectures that scale from mobile units to fixed installations.
A video switcher is a hardware or software system that receives multiple video input signals, processes them through internal routing matrices, and outputs a selected or composited signal to displays or transmission chains, typically handling resolutions from 1080p to 8K with latency below two frames. Its primary commercial purpose is enabling real-time video source selection, transitions, and effects layering for live broadcast, streaming, and presentation environments. IP-based switching represents the fastest-expanding technology segment as SMPTE ST 2110 adoption displaces baseband SDI infrastructure in facility builds. HDMI switchers occupy the highest volume tier in corporate and education deployments where cost sensitivity outweighs broadcast-grade reliability requirements. Live streaming applications generate accelerating demand as houses of worship, esports venues, and enterprise communications teams deploy mid-range switchers without traditional broadcast engineering staff.
The FCC governs spectrum efficiency mandates that accelerate broadcaster migration to compressed IP workflows, while the EU AI Act and GDPR shape automated content moderation features integrated into switcher software stacks. CE marking requirements under the EU's Radio Equipment Directive constrain import pathways for non-compliant hardware manufacturers. China's MIIT enforces GB standards for electromagnetic compatibility that filter which switcher models enter domestic broadcast facility tenders. Stakeholders must monitor how regional certification divergence affects product platform standardization decisions and service localization costs.
Market Dynamics
SMPTE ST 2110 standardization is compressing switching infrastructure investment cycles as broadcasters abandon SDI baseband architectures for IP-native facility builds. This protocol transition redistributes value capture from hardware manufacturers toward software-defined workflow vendors.
Growth Catalysts
- FCC Spectrum Reallocation:Mandates in the United States force broadcast stations toward compressed IP workflows, accelerating switcher refresh cycles in major metropolitan markets.
- Esports Venue Construction:Purpose-built arenas in Germany and China deploy mid-range switchers for real-time multi-camera production without traditional engineering staff.
- Live Streaming Platform Integration:Software-hardware bundles enable houses of worship and enterprise communications teams to operate broadcast-quality outputs.
Market Restraints
- Semiconductor Supply Concentration:FPGA and high-speed SerDes component fabrication concentrates in Taiwan, exposing switcher manufacturers to single-point geopolitical risk.
- Copper and Rare Earth Input Costs:Connector assemblies and shielding materials face volatile commodity pricing that compresses hardware margins.
- EU CE Marking Complexity:The Radio Equipment Directive's electromagnetic compatibility testing extends product launch timelines by four to six months for non-EU manufacturers.
Strategic Opportunities
- India Broadcast Modernization:TRAI's infrastructure mandates and rising OTT platform investment create demand for cost-optimized IP switchers in regional language production.
- Cloud-Native Production Convergence:Hybrid edge-cloud architectures enable remote switching operations that reduce facility capital requirements for tier-two broadcasters.
- EU AI Act Compliance:Automated content moderation feature integration into switcher software stacks creates premium pricing tiers for European public service broadcasters.
Industry Challenges
- IP Engineering Talent Scarcity:Broadcast facilities struggle to hire network engineers proficient in PTP timing, multicast routing, and ST 2110 stream management.
- Legacy SDI Integration Friction:Hybrid facilities require signal format conversion hardware that adds latency, complexity, and failure points to live production chains.
- Certification Timeline Compression:Regional electromagnetic compatibility standards in China, the EU, and the United States diverge, forcing redundant testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Switchers Market |
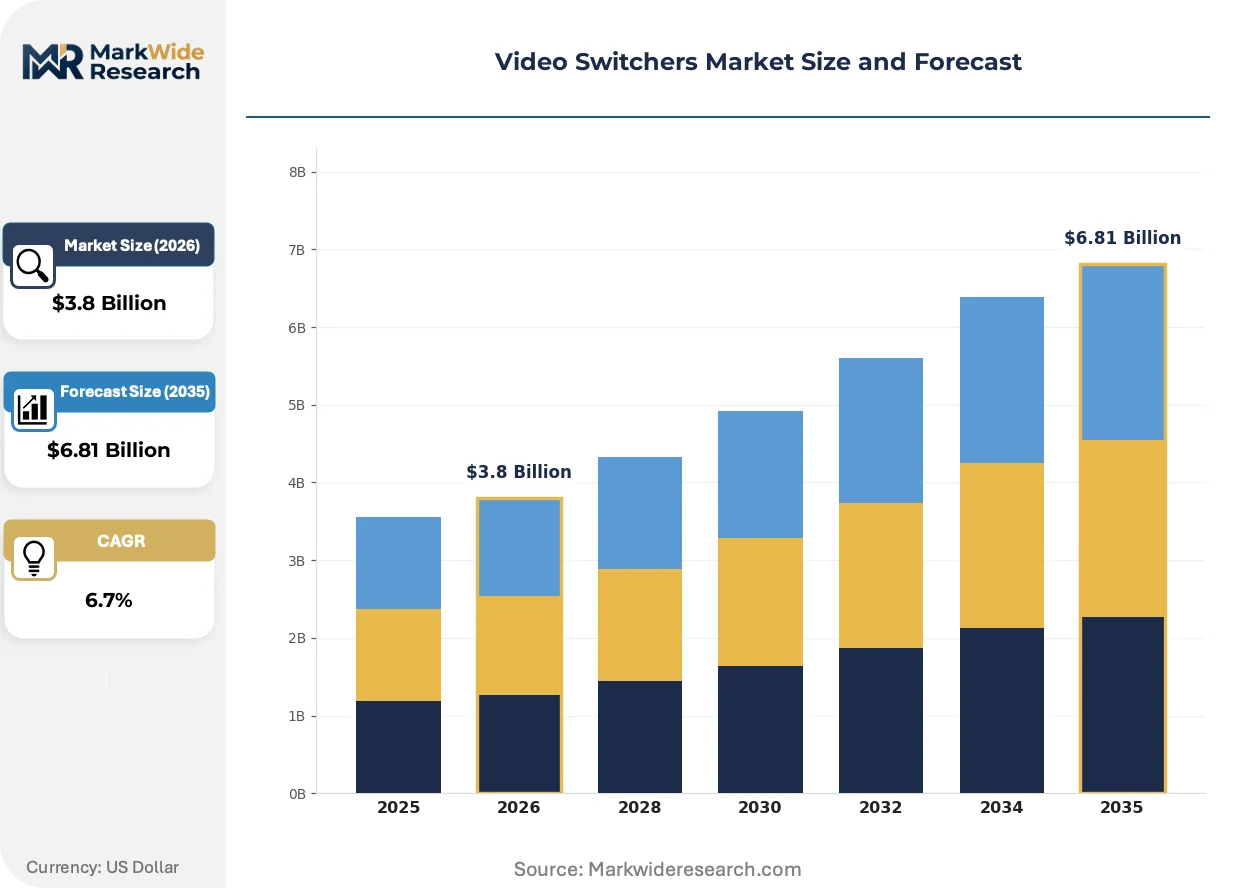
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDMI Switchers, SDI Switchers, Analog Switchers, IP Switchers Technology: Matrix Switching, IP-based Switching, SDI Switching, Instant Switching End User: Broadcast Stations, Event Venues, Education Institutions, Corporate Offices Application: Live Streaming, Video Conferencing, Sports Broadcasting, Film Production |
| Companies Covered | Blackmagic Design, Sony Corporation, Panasonic Corporation, Ross Video, Grass Valley, AJA Video Systems, NewTek, FOR-A Company, Datavideo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Switchers Market Evolving Landscape
Software-defined switching architectures are collapsing the distinction between production switchers and streaming encoders. This convergence enables single-vendor workflow stacks that displace multi-vendor integration complexity.
IP-based switching infrastructure is digitizing signal routing, processing, and distribution across broadcast facilities. Regional sports networks and university athletic departments are adopting these systems fastest. The technology is digitizing capital allocation patterns by converting fixed hardware depreciation into scalable operational expenditure models.
The EU AI Act's automated content classification requirements are mandating real-time metadata injection capabilities in switcher software. European public broadcasters must deploy systems capable of frame-accurate tagging for accessibility and content moderation. German and French facility operators are prioritizing switcher vendors with pre-certified compliance modules to accelerate deployment timelines.
Mid-market buyers are consolidating vendor relationships around integrated hardware-software-service bundles. Independent production houses and corporate AV departments now expect subscription-based feature unlocking rather than perpetual license purchases. This pattern is most visible in United States education technology procurement and United Kingdom house-of-worship technology refresh cycles.
Video Switchers Market Segmentation
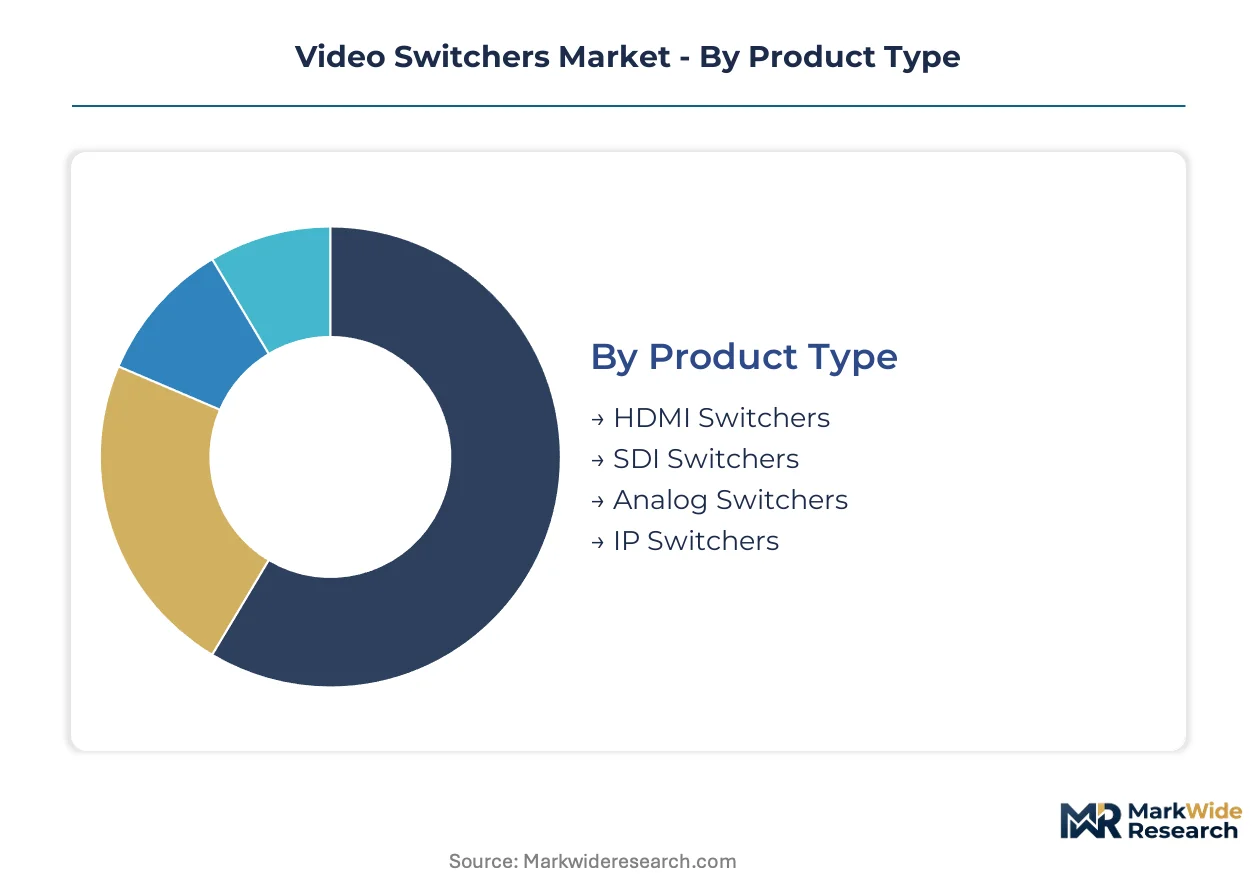
Video switcher procurement patterns diverge sharply across technical specifications and operational environments. Buyers prioritize signal format compatibility, latency tolerance, and integration complexity when matching product categories to facility requirements.
Product Type:
Use-case spectrum spans consumer-grade presentation tools to broadcast-critical infrastructure with diverging reliability thresholds.
- HDMI Switchers:Consumer-grade interfaces support 4K60p transmission over copper cabling with EDID handshake protocols. Corporate offices and education institutions in the United States and Germany dominate procurement, driven by cost-sensitive refresh cycles and plug-and-play deployment requirements without dedicated engineering staff.
- IP Switchers:Packet-based architectures implement SMPTE ST 2110 for uncompressed video over standard Ethernet, enabling facility-wide routing without dedicated coaxial infrastructure. Broadcast stations in the United States and China lead adoption as FCC spectrum mandates and MIIT infrastructure standards accelerate facility modernization timelines.
- SDI Switchers:Serial digital interface systems remain entrenched in live production chains requiring sub-frame latency guarantees.
- Analog Switchers:Legacy composite and component systems persist in retrofit scenarios and developing market budget constraints.
Established volume favors HDMI Switchers; emerging adoption favors IP Switchers.
Technology:
Cost tier stratification separates capital-intensive facility builds from operational-expense-driven cloud workflows.
- IP-based Switching:Software-defined routing through COTS network equipment converts fixed hardware depreciation into scalable subscription models. Regional sports networks and university athletic departments in the United States deploy these systems fastest, compressing traditional capital allocation cycles.
- Matrix Switching:Dedicated crosspoint hardware establishes non-blocking signal paths with deterministic latency characteristics. Event venues in Germany and China specify these systems for mission-critical live productions where packet loss tolerance approaches zero.
- SDI Switching:Baseband signal processing maintains broadcast-grade reliability in hybrid facility transitions.
- Instant Switching:Frame-buffered cut execution eliminates visible transition artifacts for presenter-controlled environments.
Matrix Switching retains premium pricing power; IP-based Switching gains share fastest in greenfield deployments.
End User:
Customer type differentiation tracks engineering sophistication and procurement authority concentration.
- Broadcast Stations:FCC-licensed facilities require redundant signal chains, frame-accurate timing, and regulatory compliance documentation. Spectrum reallocation mandates in the United States force infrastructure refresh cycles in major metropolitan markets.
- Event Venues:Purpose-built arenas and convention centers prioritize rapid reconfiguration between corporate presentations and entertainment productions. Esports venue construction in China and Germany drives mid-range switcher demand without traditional broadcast engineering staffing models.
- Education Institutions:K-12 and university AV departments prioritize intuitive control surfaces for non-technical operators.
- Corporate Offices:Enterprise communications teams demand software-hardware bundles with IT-managed deployment profiles.
Broadcast Stations command vendor attention through service contract value; Event Venues expand addressable market through volume.
Application:
Application maturity separates established production formats from emerging distribution channels.
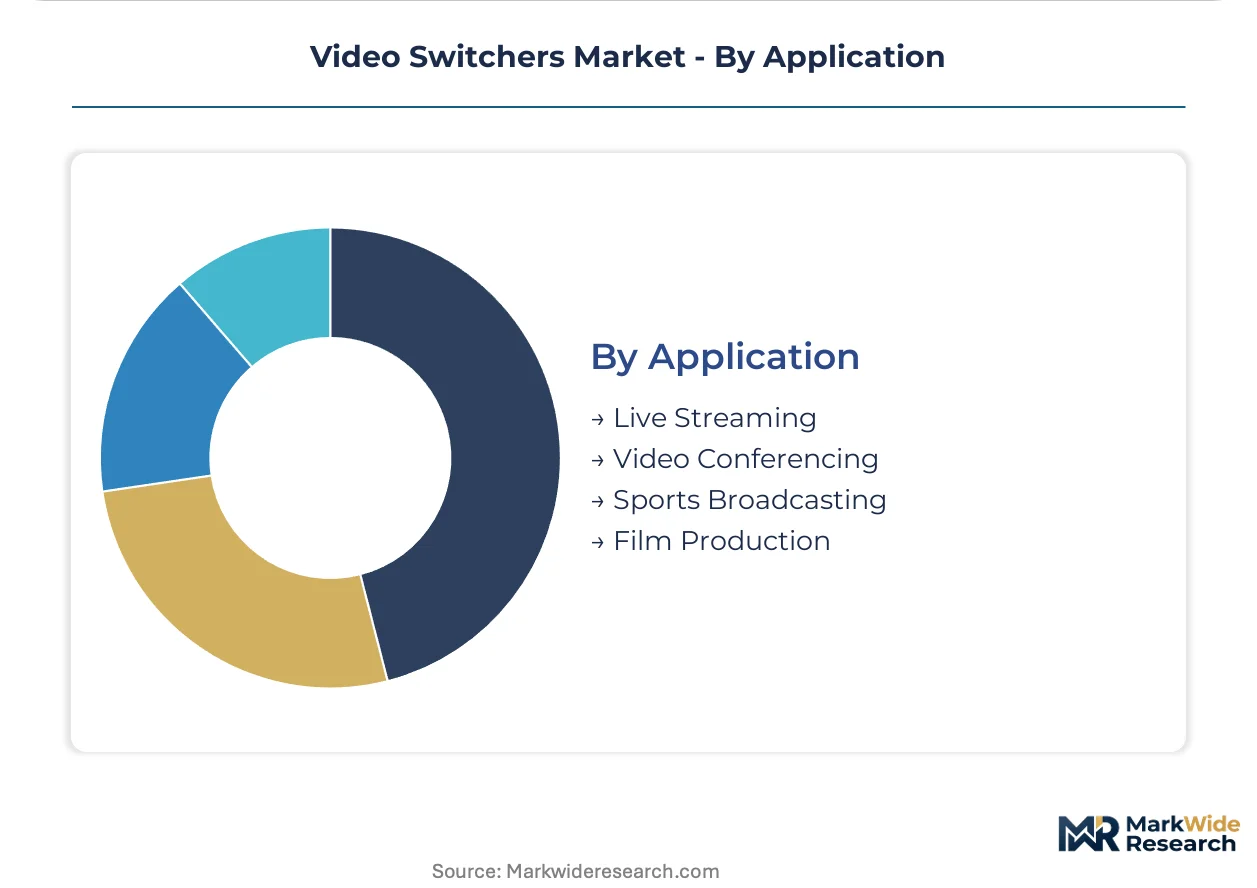
- Live Streaming:Real-time encoding integration with social platforms and OTT services collapses traditional production-distribution boundaries. Houses of worship in the United States and United Kingdom deploy mid-range switchers to reach distributed congregations, bypassing traditional broadcast engineering requirements.
- Sports Broadcasting:Multi-camera instant replay, augmented reality graphics, and slo-mo integration demand sub-frame latency and synchronous multi-channel recording. Regional networks in the United States upgrade facilities to compete with national broadcast quality standards.
- Video Conferencing:Enterprise hybrid work models require broadcast-quality camera switching for executive presentations and town halls.
- Film Production:On-set video village and livegrade monitoring drive portable switcher specifications for cinematography teams.
Sports Broadcasting anchors professional-tier pricing; Live Streaming climbs the fastest as platform integration lowers technical barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' dense fiber backbone and spectrum auction infrastructure anchors North American switcher demand, while China's 5G broadcast trials and Germany's public media investment reshape procurement patterns across three continents.
United States
FCC spectrum reallocation mandates compress broadcaster refresh cycles in New York and Los Angeles metropolitan markets. The Commission's 2020 C-band auction proceeds fund IP facility builds at major network affiliates. Atlanta's CNN Center and Burbank's studio complexes anchor live production switcher deployment for cable news and streaming originals.
Germany
ARD and ZDF infrastructure modernization drives public broadcaster switcher procurement across Munich and Cologne production hubs. The EU AI Act's automated content classification requirements accelerate software-integrated system adoption. Leipzig's media campus and Hamburg's harbor broadcast facilities concentrate esports venue technology deployment.
China
MIIT GB standards enforcement filters electromagnetic compatibility certification for domestic facility tenders in Beijing and Shanghai. The ministry's 5G broadcast pilot programs in Guangzhou and Shenzhen accelerate IP-native switching architecture deployment. Hangzhou's Alibaba Cloud integration and Chengdu's gaming arena construction expand mid-range switcher volume.
India
TRAI infrastructure mandates and regional OTT platform investment create cost-optimized IP switcher demand in Mumbai and Bengaluru. The regulator's broadcast digitization timeline compresses facility upgrade schedules for Hindi and Tamil language producers. Noida's film city cluster and Hyderabad's sports broadcast infrastructure anchor live production system procurement.
Japan
METI broadcast technology roadmaps guide NHK 8K production facility standards in Tokyo and Osaka. The ministry's spectrum efficiency targets push commercial broadcasters toward compressed IP workflows. Yokohama's international broadcast center and Fukuoka's regional network hubs concentrate next-generation switcher validation programs.
Video Switchers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream feeding signal processing modules and interface hardware into assembled workflows. The vendor base separates into three strata: broadcast-grade infrastructure providers with service networks, mid-market software-hardware bundlers, and cost-optimized volume manufacturers. Competitive positioning hardens around three archetypes: premium tier incumbents defending service contract value, agile challengers attacking with integrated subscription models, and Asian fabricators capturing education and corporate price sensitivity. Market consolidation proceeds through vertical capability acquisition and regional distribution partnership expansion rather than horizontal merger activity.
Among Australia-based design houses, Blackmagic Design exemplifies the aggressive pricing archetype that collapsed mid-market entry barriers for independent production houses. Sony Corporation anchors the premium infrastructure tier through established 4K and 8K product depth and service network density. Ross Video occupies the live production workflow specialization, with modular architectures scaling from mobile units to fixed installations. These three patterns—price disruption, premium service anchoring, and workflow modularity—capture the competitive structure reshaping procurement authority across broadcast, corporate, and education verticals.
| Leading Market Players |
|---|
| Blackmagic Design |
| Sony Corporation |
| Panasonic Corporation |
| Ross Video |
| Grass Valley |
| AJA Video Systems |
| NewTek |
| FOR-A Company |
| Datavideo |
| Others |
Value Network & Pricing Analysis
Taiwanese FPGA foundry concentration determines both the premium-to-economy pricing spread across switcher tiers and the geographic configuration of component sourcing networks. Semiconductor supply bottlenecks cascade through manufacturing lead times, forcing buyers into longer-term contracting that compresses margin flexibility at mid-market price points.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement blocks from independent production house purchases, with broadcast stations commanding 30-40% unit cost reductions at scale. Three-tier pricing stratification across premium, standard, and economy levels reflects certification grade differentiation—CE-marked and FCC-certified units carry 15-25% premiums over uncertified alternatives. Pricing pressure stems from Chinese HDMI switcher manufacturers flooding education and corporate segments with sub-$500 units. Broadcast stations exhibit lowest price sensitivity due to service contract bundling, while houses of worship and independent creators drive aggressive cost competition.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese EMS providers and Chinese ODMs in Shenzhen and Dongguan, with secondary assembly nodes in Malaysia and Vietnam. Raw material dependencies center on high-speed SerDes chips from TSMC-affiliated foundries, copper alloy connector assemblies, and rare earth shielding components. Single-source vulnerability concentrates in FPGA supply, where Xilinx and Altera alternatives face 18-month qualification cycles. Distribution runs through specialized AV integrators and direct-to-broadcaster channels, bypassing traditional electronics wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity for IP-native workflows—specifically PTP timing and multicast routing proficiency—constrains facility upgrade velocity and creates asymmetric advantage for vendors with training-embedded service models.
For Market Incumbents: Build certification moats around pre-validated SMPTE ST 2110 compliance modules to accelerate European public broadcaster sales cycles. Defend against software-defined challengers by embedding cloud-native production capabilities into existing hardware service contracts. Add FPGA buffer inventory positions in Taiwan to mitigate single-source supply disruption. For New Entrants and Emerging Players: India's regional language broadcast modernization offers the most penetrable geography, with TRAI-mandated facility upgrades outpacing qualified systems integrator supply. Target cost-optimized IP switcher bundles for Mumbai and Bengaluru OTT production houses. Pursue channel partnerships with Indian AV rental companies already embedded in wedding and cricket broadcast verticals. For Investors and Strategic Acquirers: Software-defined workflow vendors with ST 2110-native architectures represent the priority acquisition archetype, as protocol transition redistributes value capture from hardware manufacturers. Long-term viability hinges on recurring revenue attachment rates exceeding 40% of initial hardware value. Watch for inflection when tier-two U.S. broadcasters begin cloud-native production pilots without on-premise switching hardware.| Strategic Initiative | Industry Significance |
|---|---|
| ST 2110 Compliance Certification | Pre-validated modules accelerate ARD and ZDF procurement timelines by 4-6 months. |
| Cloud-Native Production Platform | Hybrid edge-cloud architectures reduce facility capital requirements for regional sports networks. |
| India Distribution Partnership | AV integrator alliances in Mumbai bypass fragmented direct sales infrastructure. |
| FPGA Supply Diversification | Secondary foundry qualifications mitigate TSMC concentration risk in SerDes components. |
| Subscription Feature Unlocking | Recurring revenue models align with U.S. education technology procurement preferences. |
Research Methodology
A standing panel of broadcast engineering directors, AV systems integrators, and live production technical managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC spectrum auction filings, MIIT GB standard publications, SMPTE technical documentation, and EMEA broadcast facility procurement databases. Bottom-up unit shipment estimates triangulated against top-down facility investment tracking across the analysis window.
Scenario-bracketing framed projections across base, accelerated, and delayed adoption paths for IP-native infrastructure. Segmentation dimensions modeled include signal format compatibility, end-user engineering sophistication, application latency requirements, and regional regulatory cluster. CAGRs derived from facility refresh cycle compression rates and greenfield deployment patterns in esports venue construction.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native production platforms would shift outcomes beyond modeled ranges. Specific risk factors include semiconductor supply disruption, electromagnetic compatibility certification divergence, and broadcast engineering talent scarcity. Quarterly review of FCC spectrum reallocation timelines, MIIT infrastructure tender awards, and European public broadcaster capital budgets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media and Entertainment Technologies
Global Virtual Event Platform Market
Digital Media and Entertainment Technologies
Digital Media Adapters Market
Digital Media and Entertainment Technologies
United States Digital OOH Advertising Market
Digital Media and Entertainment Technologies
Healthcare Gamification Market
Digital Media and Entertainment Technologies
North America Digital Scent Technology Market
Digital Media and Entertainment Technologies
Europe Digital Scent Technology Market
Digital Media and Entertainment Technologies
Digital OOH Market
Digital Media and Entertainment Technologies
VR Content Creation Services Market
Digital Media and Entertainment Technologies
Digital Scent Technology Market