
 Treadmill Motors Market | 2026-2036
Treadmill Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Treadmill Motors Market Analytics
Chinese motor manufacturing capacity is shifting toward higher-efficiency treadmill motor platforms for export markets. Brigadoon Fitness Inc leverages vertical integration across assembly and testing to sustain cost discipline. Johnson Health Tech anchors its supply chain through captive motor sourcing for its commercial treadmill lines. Rotomag Motors & Controls Pvt. Ltd. competes on customization depth for boutique fitness OEMs in South Asia and the Middle East.
Treadmill motors are electromechanical drive units, typically rated between 1 HP and 4 HP, that convert electrical energy into rotational force to move a continuous running belt at variable speeds. Brushless DC variants now dominate premium residential and commercial installations due to their superior thermal efficiency, reduced maintenance intervals, and quieter operation profiles. AC motor configurations retain structural importance in high-duty commercial gym environments where sustained load tolerance outweighs energy efficiency priorities. By end user, commercial gyms and rehabilitation centers concentrate margin pools through specification-driven procurement and extended service contracts.
Regulators in the United States enforce efficiency benchmarks through DOE appliance standards and FCC electromagnetic compatibility rules for motorized fitness equipment. China's MIIT administers GB standards for motor efficiency tiers and safety certification, while the EU applies CE marking and REACH substance restrictions on motor components and insulation materials. Stakeholders must monitor evolving efficiency mandates and material compliance deadlines across their primary export corridors.
Market Dynamics
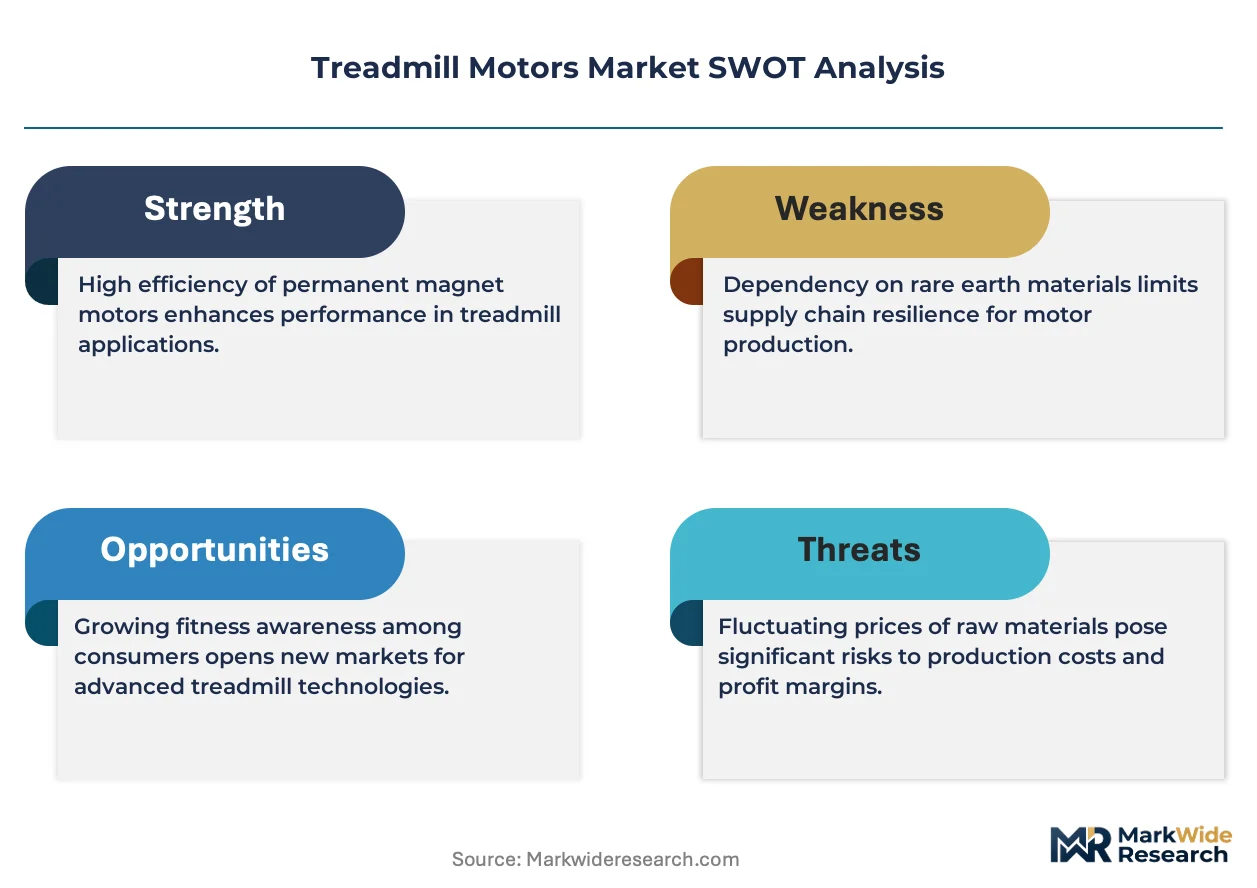
Brushless DC motor architectures are compressing thermal management costs and extending service intervals, forcing incumbent suppliers to retool winding and magnet assembly lines or cede premium residential segments to vertically integrated fitness OEMs.
Growth Catalysts
- DOE Appliance Efficiency Standards:US regulatory mandates for motorized fitness equipment are accelerating brushless motor adoption in premium residential treadmills as manufacturers pre-empt compliance costs.
- Home fitness equipment retrofit cycles:Residential users are replacing aging DC motor units with higher-efficiency drives, creating replacement demand independent of new equipment sales.
- Copper rotor die-casting:Advanced conductor geometries in induction motor variants are improving AC motor efficiency in commercial gym installations where sustained load tolerance remains critical.
Market Restraints
- Neodymium supply concentration:Rare earth magnet sourcing from Chinese processing facilities creates input cost volatility for brushless motor permanent magnet assemblies.
- GB standard compliance layering:China's MIIT efficiency tier certifications add testing overhead for export-bound motor platforms, compressing margin on mid-range residential units.
- AC motor energy penalty:Sustained-duty commercial installations face higher operating costs versus brushless alternatives, creating substitution pressure from facility energy managers.
Strategic Opportunities
- India PLI scheme for component manufacturing:Domestic motor winding and assembly incentives are enabling regional supply base development for South Asian fitness OEMs.
- Rehabilitation center specification pipelines:Medical-grade treadmill procurement with extended service contracts offers margin pools above standard commercial gym equipment.
- Silicon carbide inverter integration:Wide-bandgap power electronics convergence with brushless motor control is enabling variable-speed precision for gait-analysis treadmill systems.
Industry Challenges
- Magnet wire winding automation:Labor-intensive stator assembly processes constrain throughput scaling for brushless motor platforms amid skilled technician shortages.
- CE marking electromagnetic compatibility testing:Extended certification timelines for EU-bound equipment compress product launch windows and inventory turns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treadmill Motors Market |
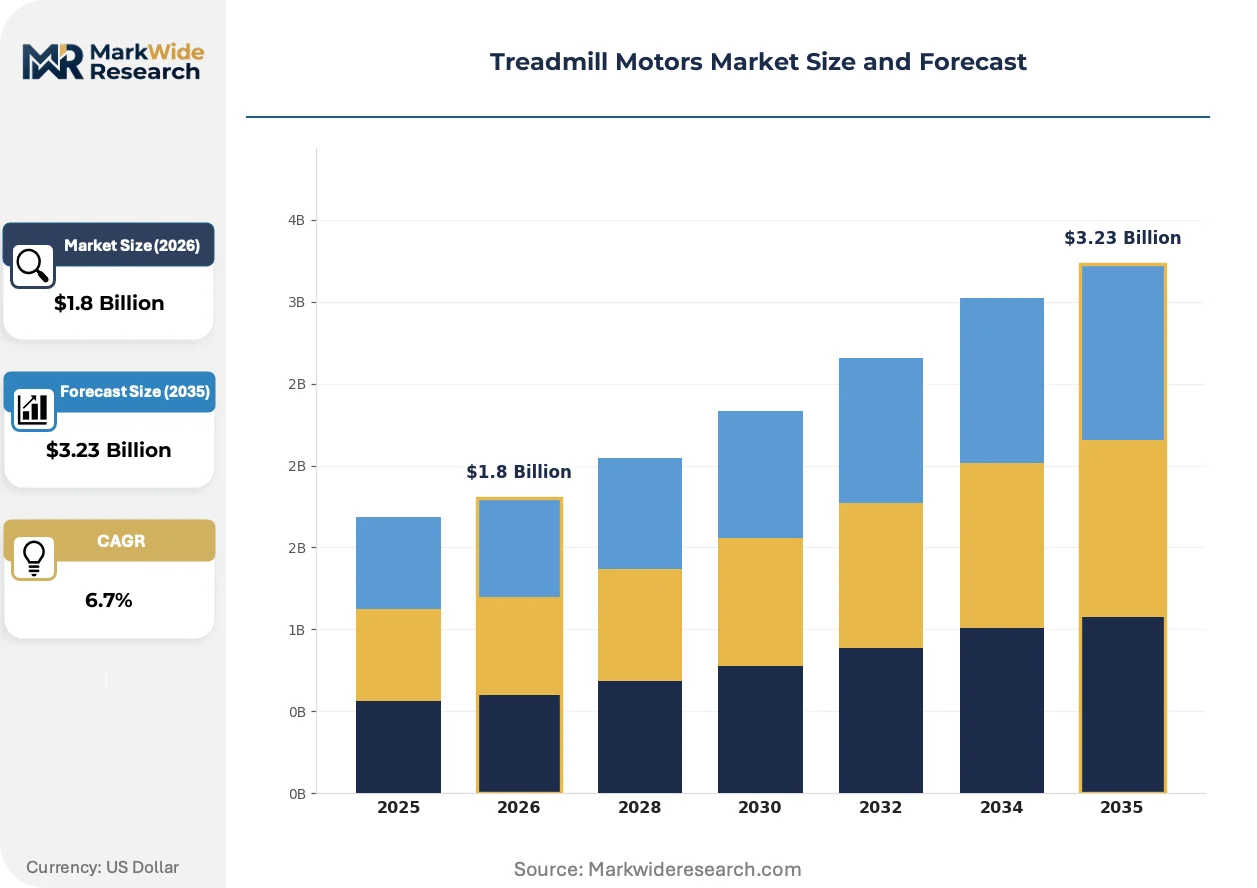
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: AC Motors, DC Motors, Brushless Motors, Synchronous Motors Power Rating: 1 HP, 2 HP, 3 HP, 4 HP End User: Residential Users, Commercial Gyms, Fitness Trainers, Rehabilitation Centers Drive Mechanism: Belt Drive, Direct Drive, Gear Drive, Chain Drive |
| Companies Covered | Brigadoon Fitness Inc, Turdan Industry Co, Rotomag Motors & Controls Pvt. Ltd., Woodway Inc, Johnson Health Tech, Life Fitness, ICON Health & Fitness, True Fitness, Impulse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treadmill Motors Market Evolving Landscape
Integrated motor-drive systems are collapsing the traditional separation between mechanical power generation and electronic control, compressing supplier tiers and shifting value capture toward firmware-capable component vendors.
Permanent magnet synchronous motor platforms with embedded field-oriented control are unifying torque generation and variable-speed regulation in single housing units. Commercial gym operators are specifying these integrated drives for noise-sensitive boutique fitness locations. The technology is unifying what were separate motor and inverter procurement decisions, reducing vendor management overhead for large facility chains.
REACH substance restrictions on motor insulation materials and stator coatings are forcing reformulation of Class H thermal protection systems. European fitness equipment assemblers are qualifying alternative polyimide-based insulation from Japanese chemical suppliers. The regulation most affects compact residential treadmills where space constraints limit thermal design margins.
Direct-to-facility spare motor distribution is shortening replacement part procurement cycles for commercial gym maintenance teams. Large fitness chains are bypassing traditional equipment OEM service networks for critical drive unit inventory. This pattern is most visible in United States metropolitan markets where facility density supports dedicated parts warehousing.
Treadmill Motors Market Segmentation
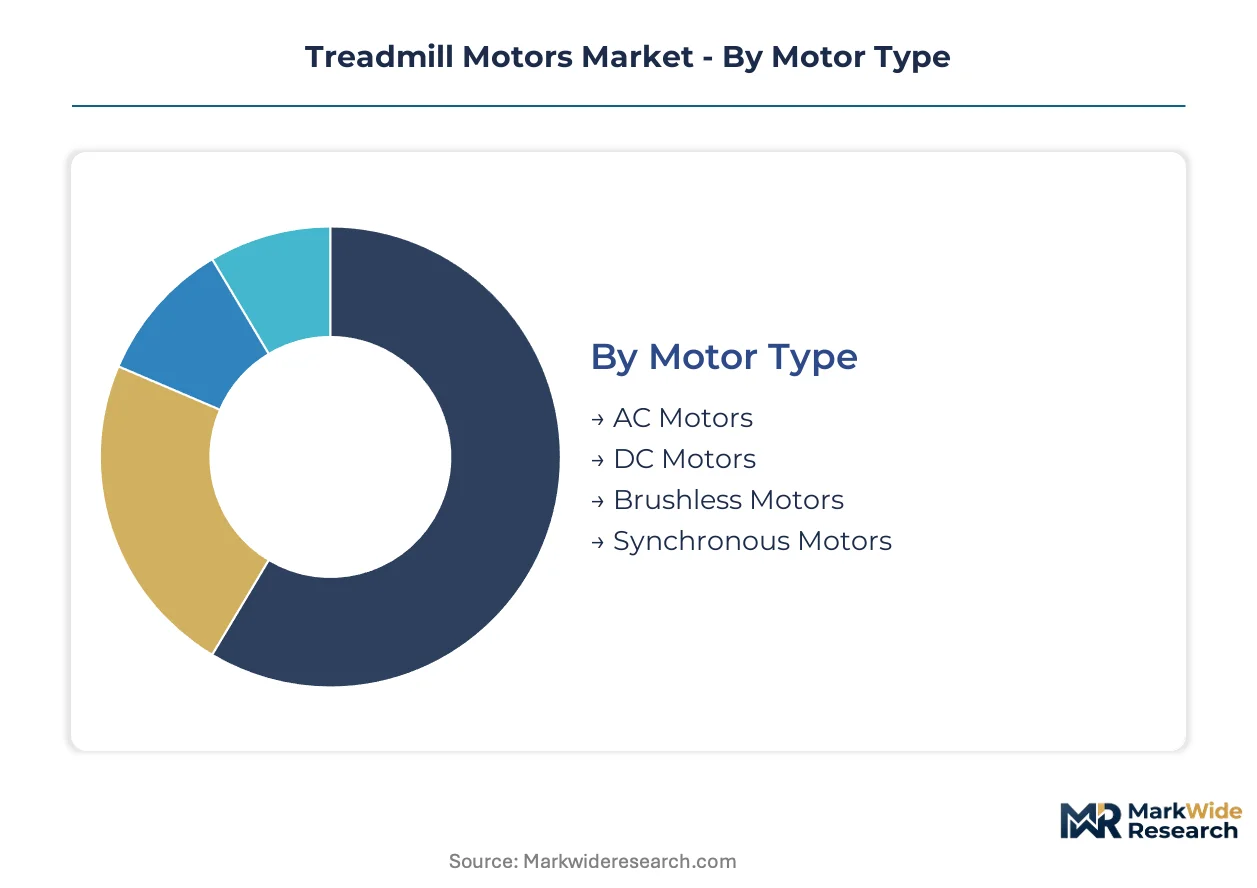
Motor architecture choices determine thermal performance ceilings and maintenance burdens across treadmill installations. Specification pipelines diverge sharply between residential retrofit demand and commercial procurement cycles. Understanding segment boundaries clarifies where technology transitions concentrate margin pressure.
Motor Type:
Supply concentration tilts toward brushless platforms as Chinese winding facilities retool magnet assembly lines for export markets.
- Brushless Motors:Permanent magnet synchronous architectures eliminate brush friction losses and reduce acoustic signatures below 60 dB. Demand concentrates in premium residential installations across the United States where DOE efficiency mandates accelerate pre-compliance procurement. Johnson Health Tech anchors captive sourcing for its commercial lines through vertically integrated motor production.
- DC Motors:Brushed commutator designs with wound rotors dominate legacy equipment replacement cycles due to controller compatibility and lower upfront capital requirements. Rehabilitation centers in Germany specify these units for budget-constrained gait analysis systems where precision speed control outweighs energy efficiency priorities.
- AC Motors:Induction architectures with copper or aluminum rotor cages sustain continuous duty cycles in high-traffic commercial gym environments. Rotomag Motors & Controls Pvt. Ltd. serves South Asian boutique fitness OEMs with customized winding configurations for 220V regional electrical standards.
- Synchronous Motors:Fixed-speed operation at line frequency limits treadmill applicability to basic institutional installations without variable-speed requirements.
Today's leader: Brushless Motors. Tomorrow's challenger: AC Motors with copper rotor die-casting advances.
Power Rating:
Cost tier stratification separates specification-driven commercial procurement from price-sensitive residential replacement demand.
- 3 HP:Continuous-duty ratings support sustained running speeds above 10 mph with thermal margins for 300+ lb user loads. Commercial gym chains in Texas and Florida specify this threshold for high-traffic locations where duty cycles exceed 16 hours daily.
- 2 HP:Intermediate ratings balance peak torque delivery with controller cost discipline for mid-market residential treadmills. Chinese export platforms concentrate production volume at this specification tier for North American big-box retail distribution.
- 4 HP:Peak overload capacity accommodates sprint intervals and incline simulation in performance training environments. Brigadoon Fitness Inc integrates these units into commercial lines targeting collegiate athletic facilities.
- 1 HP:Entry-level ratings serve walking-focused rehabilitation protocols and compact residential installations with limited mechanical envelope constraints.
Volume concentrates at 2 HP. Margin accumulates at 3 HP.
End User:
Application-specific procurement patterns fragment vendor relationships across warranty terms and service contract structures.
- Commercial Gyms:Facility operators negotiate extended service agreements covering drive unit replacement cycles. Large United States metropolitan chains bypass OEM networks for direct-to-warehouse spare motor procurement, compressing maintenance downtime.
- Rehabilitation Centers:Medical-grade specification pipelines require ISO 13485 traceability and extended calibration documentation. European procurement teams prioritize CE marking compliance and REACH substance certification for motor insulation systems.
- Residential Users:Retrofit demand for aging DC motor replacements creates aftermarket revenue independent of new equipment sales cycles. Online parts distributors capture margin through direct-to-consumer winding and controller kits.
- Fitness Trainers:Mobile and boutique studio operators prioritize acoustic performance and rapid installation compatibility over peak horsepower ratings.
Service contract value pools deepest with Rehabilitation Centers. Procurement autonomy expands fastest among Commercial Gyms.
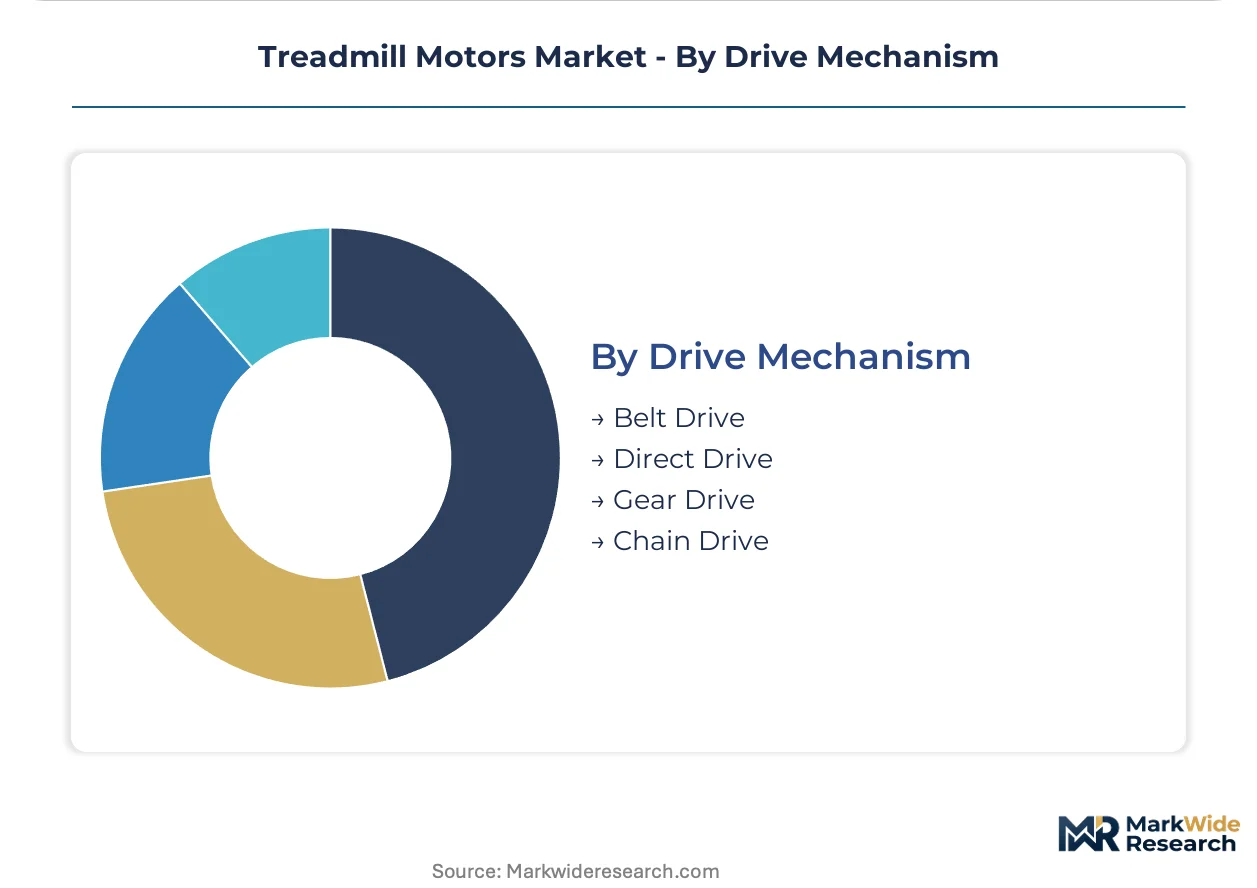
Drive Mechanism:
Maturity gradients separate established belt architectures from emerging direct-drive platforms in noise-sensitive installations.
- Belt Drive:Poly-V and timing belt configurations isolate motor vibration from deck structures through elastomeric damping. Dominant architecture across all power ratings due to maintenance accessibility and component standardization.
- Direct Drive:Motor shaft-to-roller coupling eliminates belt wear points and reduces maintenance intervals by 40-60%. Boutique fitness locations in Japan and South Korea specify these systems for premium acoustic environments.
- Gear Drive:Speed reduction stages enable high-torque, low-RPM motor selection for compact mechanical envelopes. Limited adoption due to lubrication maintenance requirements and acoustic signature penalties.
- Chain Drive:Roller chain architectures persist in budget institutional installations where initial capital cost dominates lifecycle economics.
Belt Drive commands installed base. Direct Drive gains specification share in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping treadmill motor production geography as manufacturers migrate toward jurisdictions with lower compliance-cost burdens while maintaining access to premium export markets.
United States
Residential fitness equipment retrofits and commercial gym chain expansions drive brushless motor specification. DOE appliance efficiency standards accelerate technology transitions in premium residential segments. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate distribution warehousing for direct-to-facility spare motor procurement.
China
Export-platform manufacturing for North American and European markets sustains winding facility utilization. MIIT-administered GB efficiency tier certifications add testing overhead for mid-range residential units. Ningbo and Shenzhen industrial corridors host magnet assembly line retooling for brushless motor platforms.
Germany
Medical-grade rehabilitation equipment procurement prioritizes ISO 13485 traceability and extended calibration documentation. REACH substance restrictions on motor insulation materials force reformulation of Class H thermal protection systems. Bavaria anchors specification-driven procurement for European fitness OEMs.
India
Domestic fitness OEM supply base development accelerates through PLI scheme incentives for component manufacturing. BIS efficiency certifications apply to locally assembled motor platforms. Gujarat and Maharashtra industrial zones concentrate winding and assembly capacity for South Asian regional markets.
Japan
Boutique fitness location specifications prioritize acoustic performance and rapid installation compatibility. METI energy efficiency guidelines influence premium residential equipment design. Osaka-Kobe manufacturing corridor supplies direct-drive motor systems for noise-sensitive installations.
Treadmill Motors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated drive system specialization. Market structure tilts toward consolidation as vertically integrated fitness OEMs internalize motor sourcing for captive supply security. Three archetypes dominate: vertically integrated equipment manufacturers controlling captive motor production, independent motor specialists competing on customization depth, and contract assemblers serving price-sensitive regional markets. Capacity expansion and strategic partnerships represent the dominant competitive vectors as firms secure magnet supply agreements and winding automation capabilities.
Among North American-based equipment manufacturers, Brigadoon Fitness Inc exemplifies vertical integration across assembly and testing functions. Johnson Health Tech anchors the captive sourcing archetype for commercial treadmill lines. Rotomag Motors & Controls Pvt. Ltd. occupies a position within the independent specialist tier, serving regional OEMs with customized winding configurations. These three entities represent distinct strategic postures without implying specific market share or technological superiority.
| Leading Market Players |
|---|
| Brigadoon Fitness Inc |
| Turdan Industry Co |
| Rotomag Motors & Controls Pvt. Ltd. |
| Woodway Inc |
| Johnson Health Tech |
| Life Fitness |
| ICON Health & Fitness |
| True Fitness |
| Impulse |
| Others |
Value Network & Pricing Analysis
REACH substance restrictions on motor insulation materials gate qualified supply for EU-bound equipment and premium-tier pricing access for manufacturers with certified alternative formulations. Buyers without REACH-compliant thermal protection systems face exclusion from German and broader European rehabilitation center procurement pipelines.
Pricing Analysis
Distributor margin layers compress final equipment pricing by 18-25 points between factory gate and end-user invoice. Three-tier pricing structure across premium brushless, standard DC, and economy AC motor tiers separates specification-grade rehabilitation equipment from big-box retail residential units. Pricing pressure stems from neodymium magnet cost volatility transmitted through Chinese processing facility concentration. Commercial gym chains exhibit lowest price sensitivity due to extended service contract bundling, while residential retrofit buyers prioritize controller compatibility over motor efficiency premiums.
Supply Chain Analysis
Dual-sourcing requirements from United States commercial gym chains mandate qualified backup suppliers for critical 3 HP and 4 HP drive units. Manufacturing concentrates in China, United States, and Germany for winding, final assembly, and medical-grade certification respectively. Raw material dependencies center on neodymium permanent magnets, copper magnet wire, and polyimide-based insulation systems. Single-source vulnerability runs through Chinese rare earth processing facilities for brushless motor magnet assemblies. Distribution runs through direct-to-facility spare motor warehousing in Dallas-Fort Worth and Phoenix metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by residential user demand-shift toward brushless DC premium specifications with DOE efficiency pre-compliance. Specification-driven procurement now rewards thermal efficiency and acoustic performance over upfront capital cost.
For Market Incumbents: Anchor captive magnet supply agreements through long-term offtake with Chinese processing facilities to defend against neodymium cost volatility. Invest in winding automation capabilities to offset skilled technician shortages constraining brushless motor throughput scaling. Prioritize REACH-compliant insulation formulation qualification to maintain access to German rehabilitation center procurement pipelines.
For New Entrants and Emerging Players: The mid-market price-point gap between Johnson Health Tech premium commercial lines and Chinese export-platform economy units offers white-space entry for 2 HP brushless motor specialists. Target South Asian boutique fitness OEMs through PLI scheme-enabled Gujarat winding capacity. Pursue silicon carbide inverter integration partnerships to differentiate on variable-speed precision for gait-analysis systems.
For Investors and Strategic Acquirers: Roll-up economics work for independent motor specialists with customization depth because commercial gym chain consolidation is collapsing vendor management overhead into single-source integrated drive procurement. Long-term viability favors firms with backward integration into magnet assembly and firmware-capable control systems. Watch for inflection where direct-to-facility spare motor distribution bypasses traditional OEM service networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Supply Agreement | Long-term neodymium offtake secures input cost stability for brushless motor platforms. |
| Winding Automation Investment | Robotic stator assembly addresses skilled technician throughput constraints in Ningbo facilities. |
| REACH Compliance Qualification | Alternative polyimide insulation certification unlocks German medical-grade procurement pipelines. |
| Silicon Carbide Integration | Wide-bandgap inverter convergence enables precision control for rehabilitation gait-analysis systems. |
| Direct-to-Facility Distribution | Phoenix and Dallas-Fort Worth warehousing shortens commercial gym maintenance downtime cycles. |
Research Methodology
Direct dialogue with treadmill OEM procurement directors, motor winding facility operations managers, commercial gym chain maintenance heads, and rehabilitation center biomedical engineers grounded qualitative findings. Secondary validation drew from DOE appliance standard filings, MIIT GB efficiency tier certifications, REACH substance restriction updates, and customs trade data for fitness equipment imports. Bottom-up motor unit shipment estimates triangulated against top-down fitness equipment production forecasts.
Bottom-up volume modeling aggregated across motor architecture, power rating, end-user segment, and drive mechanism dimensions. Top-down cross-checks applied equipment production ratios and replacement cycle assumptions across the projection horizon. CAGRs derived from segment-level growth rate convergence analysis. Forecast inputs incorporated brushless motor adoption curves, copper rotor die-casting penetration in commercial AC units, and PLI scheme capacity buildout timelines.
Caveats apply where neodymium supply disruptions, REACH compliance deadline acceleration, or DOE efficiency standard tightening could materially shift the outlook. Deviation in Chinese rare earth export policy or MIIT certification layering would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Military Fitness Training Equipment Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
Weight Training Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Exercise Resistance Bands Market
Fitness Equipment
Saudi Arabia Outdoor Fitness Equipment Market
Fitness Equipment
Europe E-Commerce Home Fitness Products Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Recumbent Stationary Bikes Market
Fitness Equipment
Japan Fitness Ring Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
China Outdoor Fitness Equipment Market