
 Traditional Toys and Games Market | 2026-2036
Traditional Toys and Games Market Size, Share, and Industry Trends Forecast 2026-2036
Traditional Toys and Games Market Outlook
Bundle-and-collect configurations is restructuring buyer choice in the Traditional Toys and Games sector, as manufacturers package complementary items into themed sets that raise basket sizes and repeat purchase rates. Hasbro leverages its entertainment IP portfolio to sustain cross-category bundling across action figures and board games. Mattel anchors premium positioning through in-house production of collectible doll lines with modular accessories.
Traditional toys and games encompass physical play products fabricated from wood, plastic, fabric, or metal, designed for developmental engagement, social interaction, or recreational entertainment across age-defined consumer groups. Injection-molded ABS and polypropylene remain dominant substrates for action figures and construction sets due to durability and color stability under repeated handling. Board games and puzzles occupy mature margin pools with stable replenishment cycles, while online retail distribution is capturing the fastest volume growth through direct-to-consumer fulfillment models.
EU REACH and RoHS frameworks restrict phthalate content and heavy-metal migration in plastic toys sold across European markets, compelling reformulation of PVC-based components. The US Consumer Product Safety Commission enforces ASTM F963 mechanical and flammability standards that govern product entry into American retail channels. Stakeholders must monitor evolving chemical disclosure requirements in multiple jurisdictions to maintain market access and avoid recall exposure.
Market Dynamics
East Asian manufacturing clusters now dictate cost structures and material availability for plastic-based toy production, while REACH chemical safety standards in Europe force simultaneous reformulation of legacy PVC components across supplier networks.
Growth Catalysts
- REACH material traceability mandates:European regulators now require documented polymer sourcing for phthalate-free formulations, accelerating supplier certification investments that lock in compliant manufacturers.
- Preschool tactile learning demand:German and French early-education institutions are expanding procurement of wooden manipulatives and sensory construction sets for developmental curricula.
- Injection-molding automation:Vietnam-based producers are deploying robotic assembly cells that cut per-unit labor costs for ABS action figure production.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and ABS resin prices fluctuate with crude oil benchmarks, compressing margin predictability for high-volume plastic toy lines.
- Supplier concentration risk:Three coastal provinces in China control over 70% of global injection-molding capacity for construction set components, creating single-point vulnerability.
- Substitution by digital entertainment:Tablet-based educational apps and streaming content capture hours previously allocated to physical play among school-age children.
Strategic Opportunities
- Direct-to-consumer fulfillment:Owned e-commerce channels bypass wholesale markups and capture first-party behavioral data for personalized bundling.
- EU Green Deal circularity incentives:Member states now subsidize design-for-recycling certifications that favor bio-based polymers and modular repairable toy architectures.
- Modular accessory ecosystems:Collectible doll lines with interchangeable components generate recurring revenue through planned obsolescence of individual pieces rather than full-product replacement.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for phthalate-free PVC alternatives remains concentrated among aging specialists in European compounder firms.
- Multi-jurisdiction certification timelines:ASTM F963 mechanical testing for US entry, REACH dossier preparation for Europe, and GB standard compliance for China create 14-18 month product launch cycles.
- Legacy mold asset stranding:Existing steel tooling for discontinued chemistries cannot be retrofitted for bio-based replacements without full capital write-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traditional Toys and Games Market |
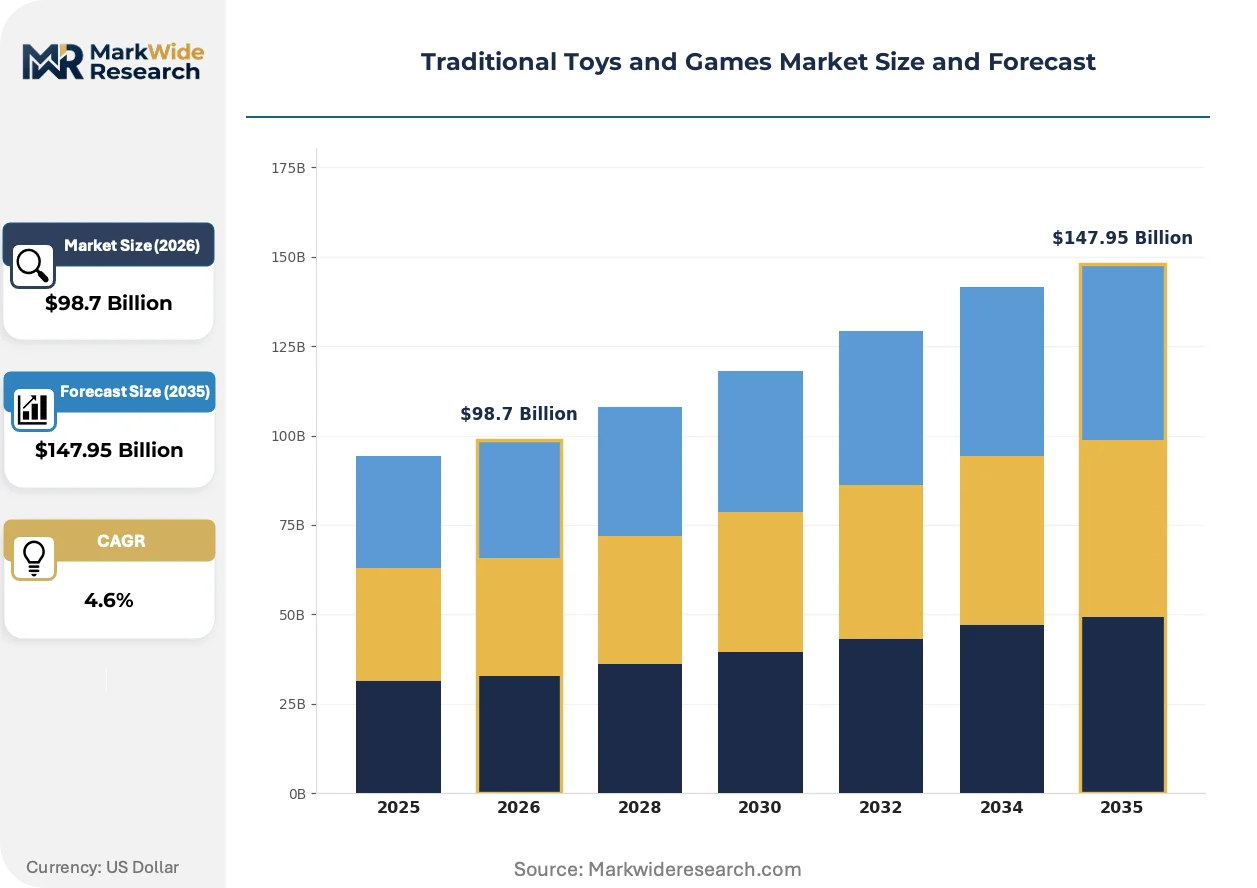
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $147.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dolls, Action Figures, Board Games, Puzzles Material: Wood, Plastic, Fabric, Metal Age Group: Infants, Toddlers, Preschoolers, Teenagers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Toy Stores |
| Companies Covered | Bandai Namco Holdings, Spin Master, Mattel, Jakks Pacific, MGA Entertainment, Hasbro, TOMY Company, Ravensburger, The LEGO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traditional Toys and Games Market Strategic Shifts
Physical-digital hybrid play formats are fragmenting traditional category boundaries, while regulatory chemistry mandates and fulfillment model experimentation reshape how value flows from factory to household.
Biodegradable PLA and starch-based polymers are absorbing capital allocation previously directed toward fossil-derived ABS in European-sourced preschool lines. German retailers now mandate compostability certifications for wooden toy coatings, pressuring suppliers to validate biodegradation timelines through third-party testing. This material transition is absorbing margin from conventional injection-molders unable to retool extrusion parameters.
REACH Annex XVII phthalate restrictions have eliminated DEHP, DBP, and BBP from teething products and bath toys sold across EU member states. Compounders serving the sector have rebuilt supply chains around citrate and adipate plasticizers with higher raw material costs but guaranteed market access. French and Italian importers now require full material safety data sheet disclosure upstream of purchase orders, shifting compliance burden onto Asian contract manufacturers.
Parental purchasing for developmental toys has migrated from seasonal big-box stocking to subscription-based curated delivery. Specialty e-commerce platforms in North America and Western Europe now offer monthly STEM kit shipments that replace one-time birthday purchases with predictable recurring revenue. This channel disintermediation is most visible in metropolitan US markets where direct brand relationships have halved traditional toy store foot traffic.
Traditional Toys and Games Market Segmentation
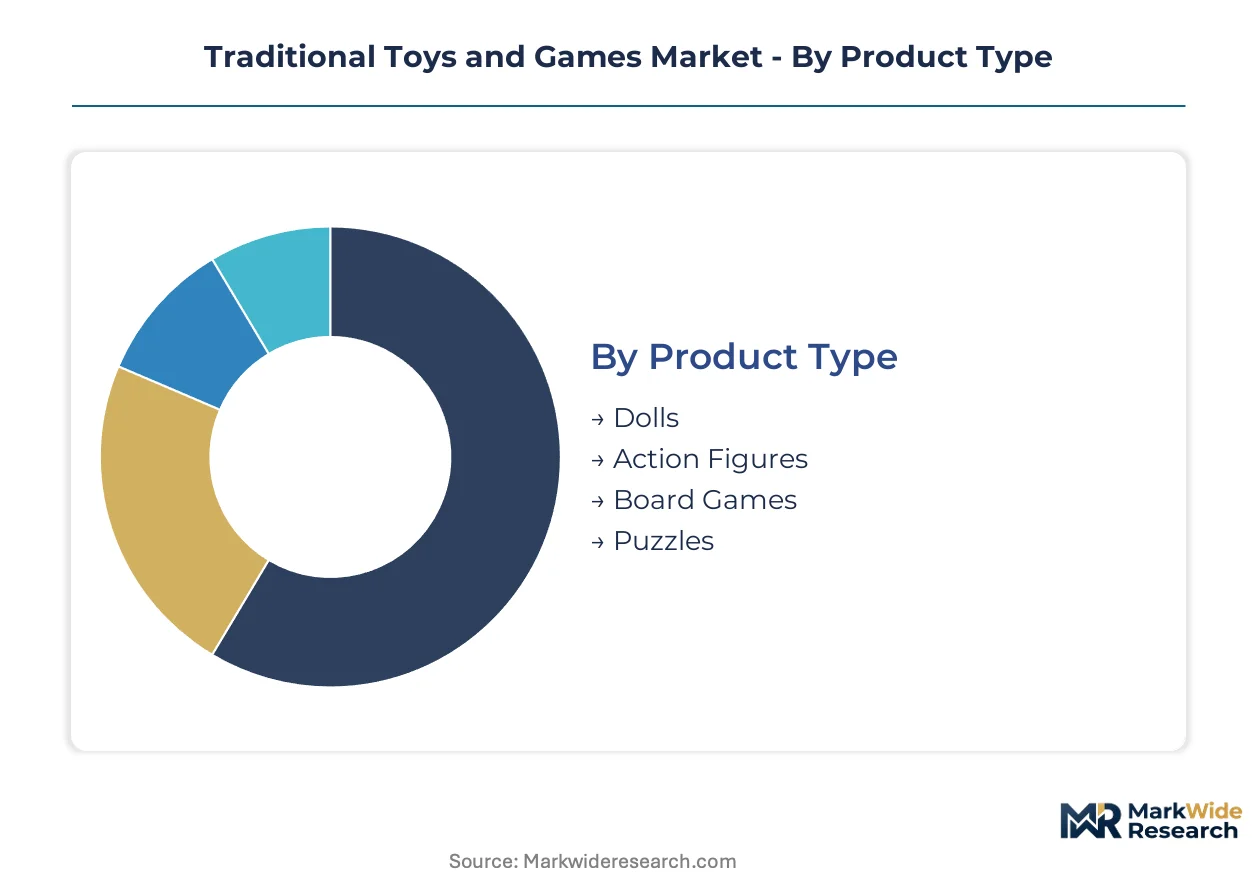
Segmentation in traditional toys and games reveals how material chemistry, developmental stage targeting, and channel economics partition margin pools. Manufacturers optimize formulation and fulfillment strategies differently across each axis.
Product Type:
Injection-molded precision and entertainment IP licensing define competitive positioning across play categories.
- Dolls:Polyvinyl chloride and ABS construction with rooted nylon hair and textile clothing assemblies. German and French specialty retailers command premium shelf placement for collectible lines with modular accessory ecosystems.
- Action Figures:Articulated ABS and polypropylene skeletons with painted detail applications. Hasbro leverages Marvel and Star Wars licensing to sustain cross-category bundling with board game tie-ins.
- Board Games:Cardboard substrate printing with thermoformed plastic insert trays. Replenishment cycles align with holiday gifting in North American mass retail channels.
- Puzzles:Die-cut paperboard or wooden piece configurations with varnish-sealed surfaces. Adult-oriented 1000+ piece formats absorb shelf space previously allocated to children's SKUs.
Mature deployment sits with Board Games. Newer deployment is concentrated in Action Figures.
Material:
Cost tier and regulatory compliance burden stratify supplier capabilities across substrate categories.
- Plastic:Injection-molded ABS, polypropylene, and phthalate-free PVC formulations dominate volume production. REACH Annex XVII mandates have forced compounders serving EU markets toward citrate plasticizer alternatives with elevated raw material costs.
- Wood:Hardwood and softwood milling with water-based coating systems for preschool manipulatives. German retailers now mandate compostability certifications for surface treatments, pressuring suppliers toward third-party biodegradation validation.
- Fabric:Polyester fill and woven textile exteriors with embroidered safety-feature detailing. Plush construction concentrates in Guangdong province contract manufacturers with integrated textile sourcing.
- Metal:Die-cast zinc alloy and stamped steel components for vehicle and construction toy durability. Die-casting capacity clusters in Zhejiang province foundries serving premium collectible segments.
Mature deployment sits with Plastic. Newer deployment is concentrated in Wood.
Age Group:
Developmental psychology research and safety testing protocols shape product architecture across life stages.
- Infants:Teething-safe silicone and untreated wood with no detachable sub-35mm components. ASTM F963 mechanical testing governs US market entry with extended certification timelines.
- Toddlers:Chunky geometric manipulatives with rounded edges and primary color schemes. French early-education institutions are expanding procurement of sensory construction sets for developmental curricula.
- Preschoolers:Wooden block systems and simple board games with 15-20 minute attention-span alignment. Tactile learning demand is intensifying across German kindergarten procurement channels.
- Teenagers:Complex strategy board games and collectible card systems with tournament-organized play. Hobby game stores in metropolitan US markets anchor community-based repeat purchase behavior.
Mature deployment sits with Preschoolers. Newer deployment is concentrated in Teenagers.
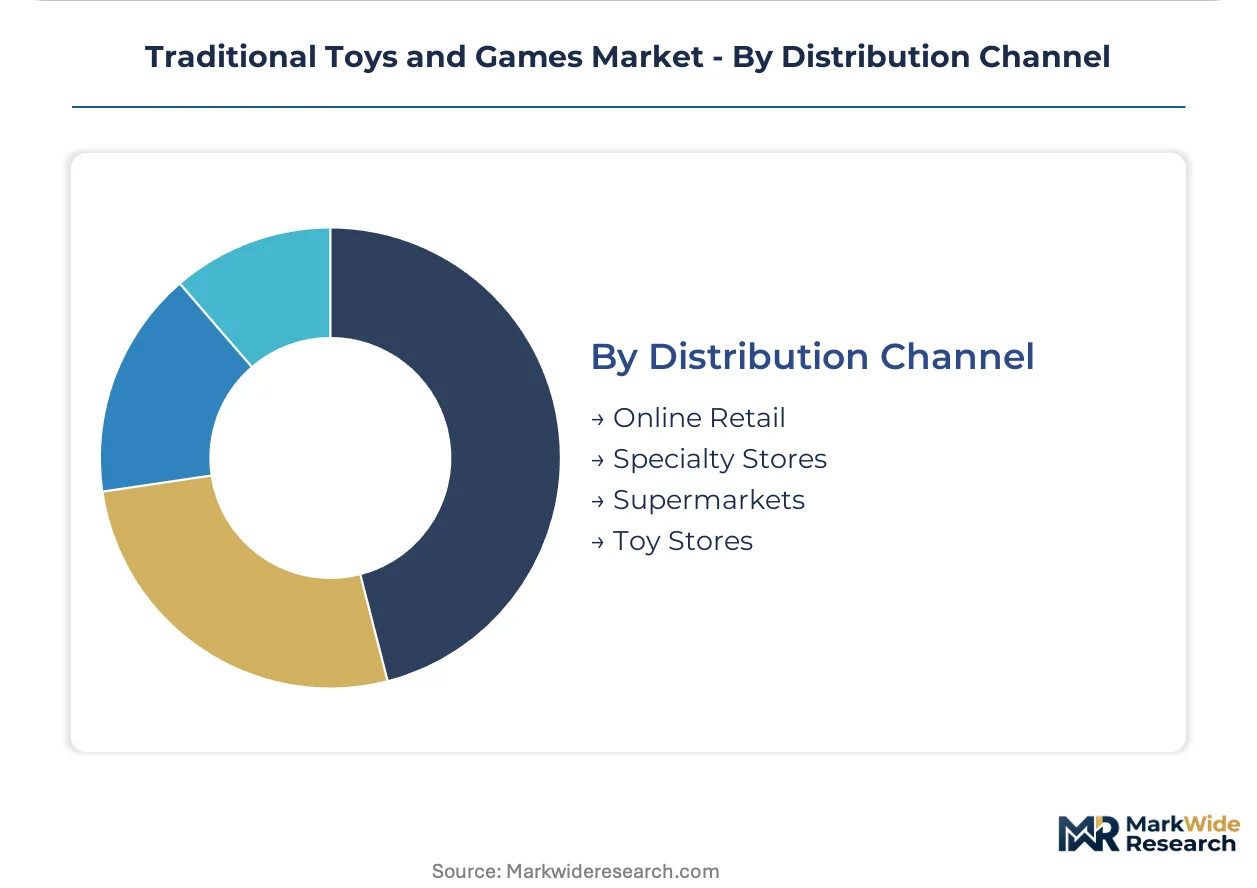
Distribution Channel:
Fulfillment model economics and customer data capture capabilities restructure value chain participation.
- Online Retail:Direct-to-consumer platforms with subscription-based curation and first-party behavioral data harvesting. STEM kit monthly deliveries in North American metropolitan markets have halved traditional toy store foot traffic.
- Specialty Stores:Hobby game and educational toy boutiques with staff expertise and in-store demonstration capacity. Board game tournament hosting generates community lock-in and inventory turns.
- Supermarkets:High-velocity seasonal stocking with impulse-placement economics and mass-market price positioning. Holiday quarter volume concentration creates working capital intensity for suppliers.
- Toy Stores:Destination retail with entertainment IP merchandising and experiential play zones. Wholesale margin compression has accelerated channel consolidation toward multi-brand big-box formats.
Mature deployment sits with Toy Stores. Newer deployment is concentrated in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters supply the bulk of plastic-based toy output, while Western European and North American markets absorb premium-priced finished goods. This production-consumption divide shapes logistics costs, regulatory compliance burdens, and margin distribution across the value chain.
China
Guangdong and Zhejiang provinces host over 70% of global injection-molding capacity for construction set components. GB standards compliance enforced by SAMR governs domestic safety testing and export certification documentation. Shenzhen and Dongguan contract manufacturers are automating ABS action figure assembly lines to offset rising labor costs.
Germany
Kindergarten procurement channels are expanding purchases of wooden manipulatives and sensory construction sets for early-education curricula. REACH Annex XVII phthalate restrictions administered by ECHA mandate full material safety data sheet disclosure from Asian suppliers. Nuremberg and Stuttgart specialty retailers command premium shelf placement for collectible doll lines with modular accessories.
United States
ASTM F963 mechanical and flammability standards enforced by the Consumer Product Safety Commission govern product entry into American retail channels. Direct-to-consumer STEM kit subscriptions in metropolitan markets have halved traditional toy store foot traffic. Los Angeles and New York distribution hubs handle last-mile fulfillment for West and East Coast e-commerce demand.
Vietnam
Robotic assembly cell deployment in northern industrial zones is cutting per-unit labor costs for ABS action figure production. Vietnamese producers are capturing contract volume previously concentrated in Chinese coastal provinces. Ho Chi Minh City and Binh Duong manufacturing parks are expanding injection-molding capacity to serve EU and US export orders.
France
Early-education institutions are expanding procurement of tactile learning products for developmental curricula. French importers now require REACH-compliant material traceability documentation upstream of purchase orders. Paris and Lyon specialty boutiques anchor community-based board game tournament hosting that generates inventory turns and repeat purchase behavior.
Traditional Toys and Games Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Traditional Toys and Games sector. The vendor base stratifies into three tiers: entertainment IP licensors with cross-category bundling capabilities, materials-led manufacturers with in-house molding and woodworking capacity, and digital-native direct-to-consumer brands with subscription fulfillment expertise. Market structure favors portfolio diversification and owned e-commerce channel development as dominant competitive moves.
Within the entertainment IP tier, Hasbro and Mattel exemplify divergent strategic positioning. Hasbro leverages Marvel and Star Wars licensing to sustain cross-category bundling across action figures and board games. Mattel anchors premium positioning through in-house production of collectible doll lines with modular accessory ecosystems. Ravensburger represents the materials-led specialist archetype with integrated puzzle and board game manufacturing.
| Leading Market Players |
|---|
| Bandai Namco Holdings |
| Spin Master |
| Mattel |
| Jakks Pacific |
| MGA Entertainment |
| Hasbro |
| TOMY Company |
| Ravensburger |
| The LEGO Group |
| Others |
Value Chain & Pricing Dynamics
Captive in-house molding operations in Guangdong and Zhejiang provinces anchor both supply security and margin capture for large-scale manufacturers, while outsourced Vietnamese assembly creates pricing flexibility for mid-tier competitors navigating petrochemical volatility.
Pricing Analysis
Margin tightening in economy-tier plastic construction sets reflects polypropylene resin volatility tied to crude benchmarks. Three-tier pricing structure across premium collectible, standard mass-market, and economy private-label tiers separates certification-grade wooden manipulatives from injection-molded commodity lines. Cost-down pressure on ABS action figures accelerates as Vietnamese robotic assembly undercuts Chinese coastal labor rates. Direct-to-consumer subscription buyers show lowest price sensitivity; supermarket seasonal purchasers exhibit highest elasticity.
Supply Chain Analysis
REACH dossier preparation and ASTM F963 mechanical certification now gate supplier qualification before volume allocation, extending procurement timelines. Guangdong, Zhejiang, and northern Vietnam host concentrated injection-molding capacity for plastic components. Raw material flows draw from Saudi and Korean petrochemical feedstock, Indonesian nickel for die-cast alloys, and European hardwood for certified preschool lines. Single-source vulnerability concentrates in three Chinese provinces controlling over seventy percent of global construction set molding. Distribution runs through Shenzhen and Ho Chi Minh City export hubs into Los Angeles and Rotterdam last-mile nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration depth, with upstream polymer compounding and downstream direct-to-consumer channels representing the critical levers separating margin leaders from price-takers.
For Market Incumbents: Hedge petrochemical exposure through backward integration into bio-based PLA formulation partnerships or long-term resin offtake contracts with Korean and Saudi suppliers. Defend shelf position in German and French kindergarten procurement by accelerating REACH-compliant material traceability documentation ahead of 2025 tender cycles. For New Entrants and Emerging Players: Subscription-curious metropolitan parents in North American coastal cities represent the most penetrable buyer archetype, with STEM kit curation and modular accessory ecosystems offering recurring revenue models absent from incumbent seasonal stocking. Bypass wholesale margin compression by launching owned e-commerce with first-party data harvesting for personalized bundling. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty e-commerce platform roll-ups and materials-led manufacturers with captive European compostability certifications. Five-to-ten year viability favors compounders with phthalate-free formulation expertise and direct-to-consumer brands with subscription retention above industry baselines. Watch for inflection when REACH Annex XVII expands restricted substance lists beyond current phthalate scope.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses wholesale markups and captures behavioral data for personalized STEM kit bundling. |
| Bio-Based Polymer Transition | Positions preschool lines for EU Green Deal subsidies and German retailer compostability mandates. |
| Modular Accessory Ecosystem Development | Generates recurring revenue through planned obsolescence of interchangeable doll components. |
| REACH Compliance Certification Investment | Locks in supplier qualification for French and Italian importer procurement requirements. |
| Robotic Assembly Automation | Vietnamese producers cut per-unit labor costs for ABS action figure manufacturing. |
Study Parameters
Trade databases, customs records, and regulatory filing repositories formed the secondary backbone, cross-referenced against primary interviews with toy brand managers, Asian contract manufacturer operations directors, European early-education procurement officers, and polymer compounder R&D leads. Bottom-up SKU-level volume aggregation and top-down category spend analysis provided triangulation checks across the analysis window.
Historical trendline analysis of segment-level volume and value trajectories informed baseline assumptions, with CAGRs derived from regression modeling across product type, material chemistry, age group, and distribution channel dimensions. Specific forecast inputs included kindergarten enrollment projections for German and French procurement demand and injection-molding capacity expansion announcements in Vietnamese industrial zones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH regulatory expansion timelines and petrochemical price volatility. Model outputs reflect documented assumptions on substitution elasticity between physical and digital play formats. A model refresh is warranted upon material change in EU chemical disclosure requirements or major Southeast Asian manufacturing cluster disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Smart Toys Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Drone for Kids Market
Toys and Games
Bath Toy Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Anime Figure Blind Box Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Global Educational Toy Market
Toys and Games
Indoor Soft Play Market
Toys and Games
Table Top Games Market
Toys and Games
Action Figures Market
Toys and Games
Bounce House Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Fabric Toys Market