
 Die-Cast Toys Market | 2026-2036
Die-Cast Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Die-Cast Toys Market Outlook
Specialty retail and direct-to-consumer digital channels is reconfiguring how die-cast toys reach end buyers. Jada Toys leverages its automotive licensing partnerships to sustain shelf presence in hobby shops and big-box retailers. Maisto anchors its competitive stance through manufacturing scale in Asian production facilities, while Tomica dominates Japan's domestic collector market with precision-engineered vehicle replicas.
Die-cast toys are metal-formed miniature replicas, typically produced through high-pressure injection of molten zinc or aluminum alloys into precision steel molds, yielding detailed, durable collectibles and play items. Zinc alloy compositions dominate mass-market production due to superior castability and surface finish for intricate detailing. Vehicles commands the largest revenue share across product types, reflecting entrenched automotive licensing partnerships and multi-generational collector loyalty. Adults represents the fastest-expanding age segment, where premium pricing for limited editions and heritage castings builds concentrated margin pools.
REACH in Europe restricts cadmium and lead content in metal alloys, compelling reformulation of traditional die-cast compositions. The Consumer Product Safety Commission in the United States enforces sharp-edge and small-parts standards that directly shape mold design and age-grading decisions. China's national standards body mandates GB toy safety certifications for domestic sale and export qualification. Stakeholders must monitor evolving chemical restrictions and traceability requirements as regulatory divergence between major markets intensifies compliance complexity.
Market Dynamics
Adult collector demand through specialty channels is concentrating purchasing power toward premium limited editions, compressing mass-market margins while elevating quality benchmarks across production tiers.
Growth Catalysts
- REACH chemical reformulation:European alloy restrictions are accelerating lead-free zinc formulations that command premium positioning in safety-conscious buyer segments.
- Digital direct-to-collector platforms:Auction sites and manufacturer portals eliminate distributor markups while capturing behavioral data for targeted heritage releases.
- China's domestic collector base:Urban middle-class expansion in tier-one cities is creating localized demand for precision-engineered vehicle replicas previously exported.
Market Restraints
- Zinc price volatility:London Metal Exchange fluctuations compress foundry margins and complicate long-term licensing contract pricing.
- Dongguan production cluster dependency:Concentrated mold-making and alloy sourcing in Pearl River Delta facilities creates single-point vulnerability for global supply continuity.
- GB 6675 certification timelines:China's toy safety testing protocols extend product launch windows by 8-14 weeks versus historical benchmarks.
Strategic Opportunities
- India's emerging collector segment:Underdeveloped specialty retail infrastructure presents first-mover positioning for direct-import partnerships with Mumbai and Delhi hobby distributors.
- CE marking convergence:Unified European compliance pathways reduce redundant testing costs for multi-market product launches.
- 3D scanning with traditional die-casting:Heritage vehicle digitization enables rapid prototype iteration for licensed classic car reproductions.
Industry Challenges
- Master mold artisan scarcity:Retiring tool-and-die specialists in German and Japanese heritage facilities constrain precision replication capabilities for limited runs.
- Multi-jurisdiction traceability systems:Divergent lot-tracking requirements between US CPSC and EU ECHA databases inflate administrative overhead for alloy composition documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die-Cast Toys Market |
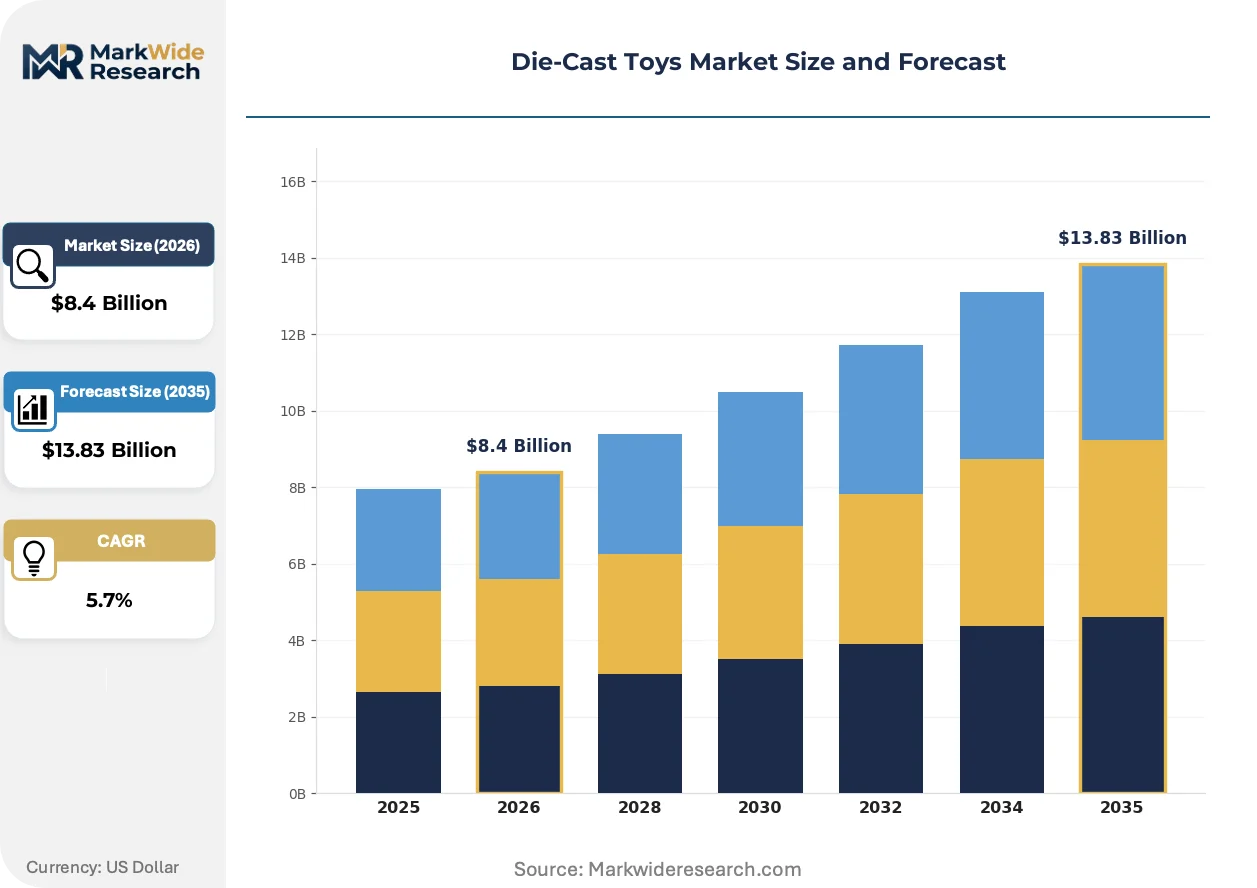
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vehicles, Action Figures, Playsets, Collectibles Material: Aluminum, Zinc, Plastic, Steel Age Group: Preschool, Children, Teenagers, Adults Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Toy Conventions |
| Companies Covered | Jada Toys, Maisto, New-Ray, Tomica, Greenlight, Welly, Bburago, Motor Max, M2 Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die-Cast Toys Market Strategic Shifts
Precision manufacturing techniques and regulatory chemistry standards are reconfiguring material specifications and collector engagement models across production tiers.
Digital light processing is migrating from prototyping to end-use mold fabrication. Heritage vehicle specialists adopt resin-based master patterns to compress tooling lead times from twelve weeks to under four. This acceleration enables smaller-batch licensed releases that match collector pre-order demand curves without inventory risk.
REACH Annex XVII cadmium restrictions are compelling alloy reformulation across European-bound production. Foundries substitute bismuth-tin stabilizers for traditional lead-bearing compositions, altering surface finish characteristics and post-cast polishing protocols. Premium segments absorb material cost premiums through limited-edition positioning, while mass-market lines face margin compression.
Collector pre-order aggregation is displacing speculative retail stocking. Manufacturer-direct crowdfunding campaigns for heritage vehicle releases capture full-margin commitments before mold cutting. This pattern concentrates in German and US enthusiast communities where automotive brand loyalty supports advance payment thresholds exceeding standard wholesale terms.
Die-Cast Toys Market Segmentation
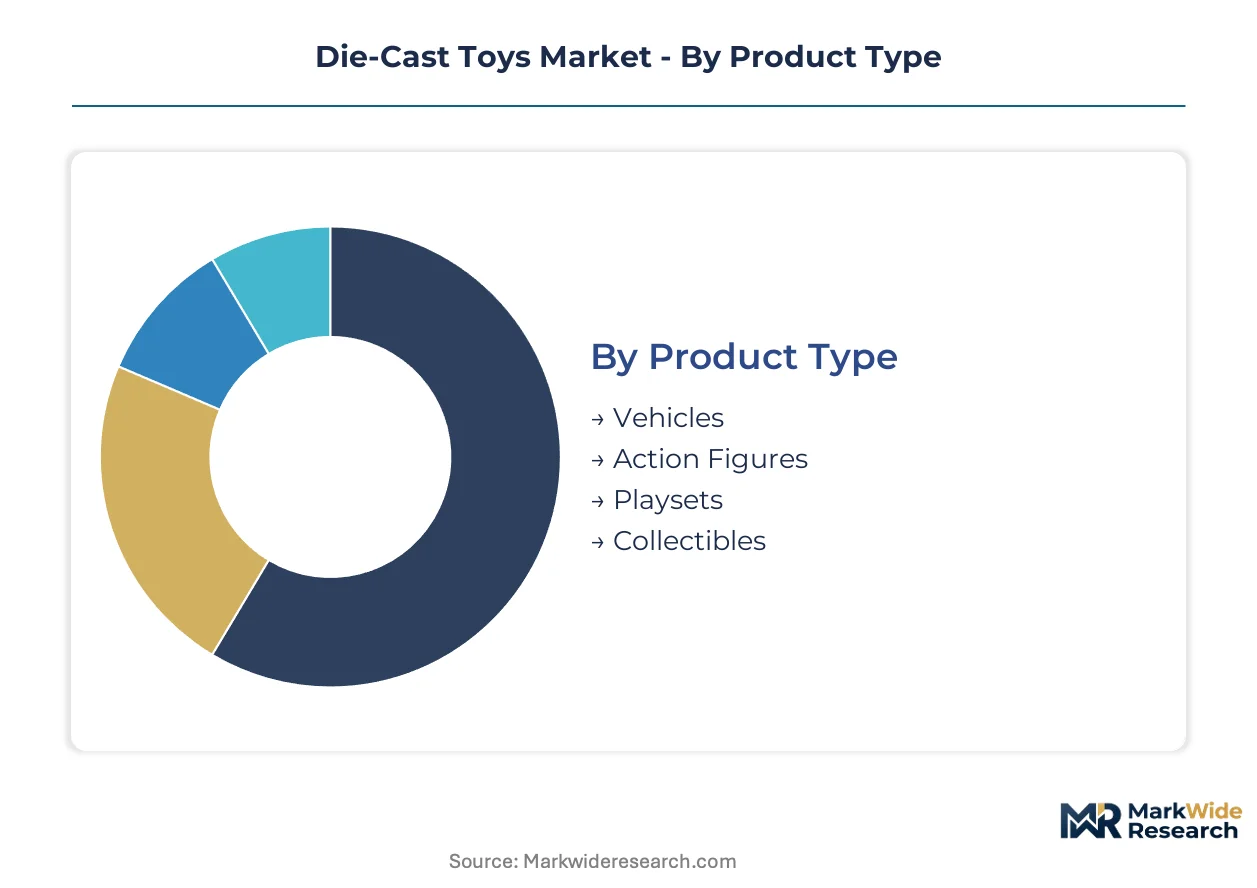
Die-cast toy segmentation reveals how manufacturing constraints, collector demographics, and channel economics partition commercial opportunity. Material chemistry and age-targeted design create distinct margin architectures that reward specialized positioning over undifferentiated scale.
Product Type:
Mature automotive licensing dominates revenue concentration while emerging collector categories reshape production batch economics.
- Vehicles:Automotive replicas command the largest revenue share through entrenched licensing partnerships with manufacturers. Collector demand concentrates in Germany, the United States, and Japan where multi-generational brand loyalty sustains premium pricing for limited heritage editions.
- Collectibles:Limited-run commemorative and anniversary editions attract adult buyers through direct-to-consumer pre-order platforms. Demand clusters in tier-one Chinese cities and North American specialty retail where advance payment thresholds exceed standard wholesale terms.
- Action Figures:Character-licensed miniatures serve entertainment franchise cross-promotions with shorter production cycles.
- Playsets:Diorama and accessory bundles extend vehicle sales through scene-building accessories with lower per-unit tooling costs.
Vehicles retains volume leadership; Collectibles holds the steepest expansion curve.
Material:
Cost tier stratification separates premium alloy formulations from commodity substitutes across safety-regulated markets.
- Zinc:Zinc alloy compositions dominate mass-market production through superior castability and surface finish for intricate detailing. REACH compliance in Europe and evolving GB standards in China are accelerating lead-free formulations that command premium positioning in safety-conscious segments.
- Aluminum:Lighter-weight aluminum alloys serve aerospace and racing vehicle replicas where reduced mass enables dynamic display features. Demand concentrates in Japanese and German precision-engineered collector lines where material differentiation justifies elevated price points.
- Plastic:Acrylonitrile butadiene styrene and resin components reduce unit costs in entry-level play segments.
- Steel:Ferrous alloys appear in structural chassis components for durability in high-wear children's products.
Zinc retains volume leadership; Aluminum holds the steepest expansion curve.
Age Group:
Customer type migration from juvenile play toward adult collecting reconfigures design specifications and margin structures.
- Adults:The fastest-expanding age segment drives premium pricing for limited editions and heritage castings through specialty channels. Urban middle-class expansion in Shanghai, Beijing, and Shenzhen creates localized demand for precision-engineered vehicle replicas previously exported exclusively.
- Children:Traditional play-oriented segments face margin compression as mass-market retail consolidates and safety certification timelines extend.
- Teenagers:Transitional buyers bridge play and collection through entertainment-licensed entry points.
- Preschool:Large-format, rounded-edge designs comply with small-parts standards and sharp-edge regulations enforced by the US Consumer Product Safety Commission.
Children retains volume leadership; Adults holds the steepest expansion curve.
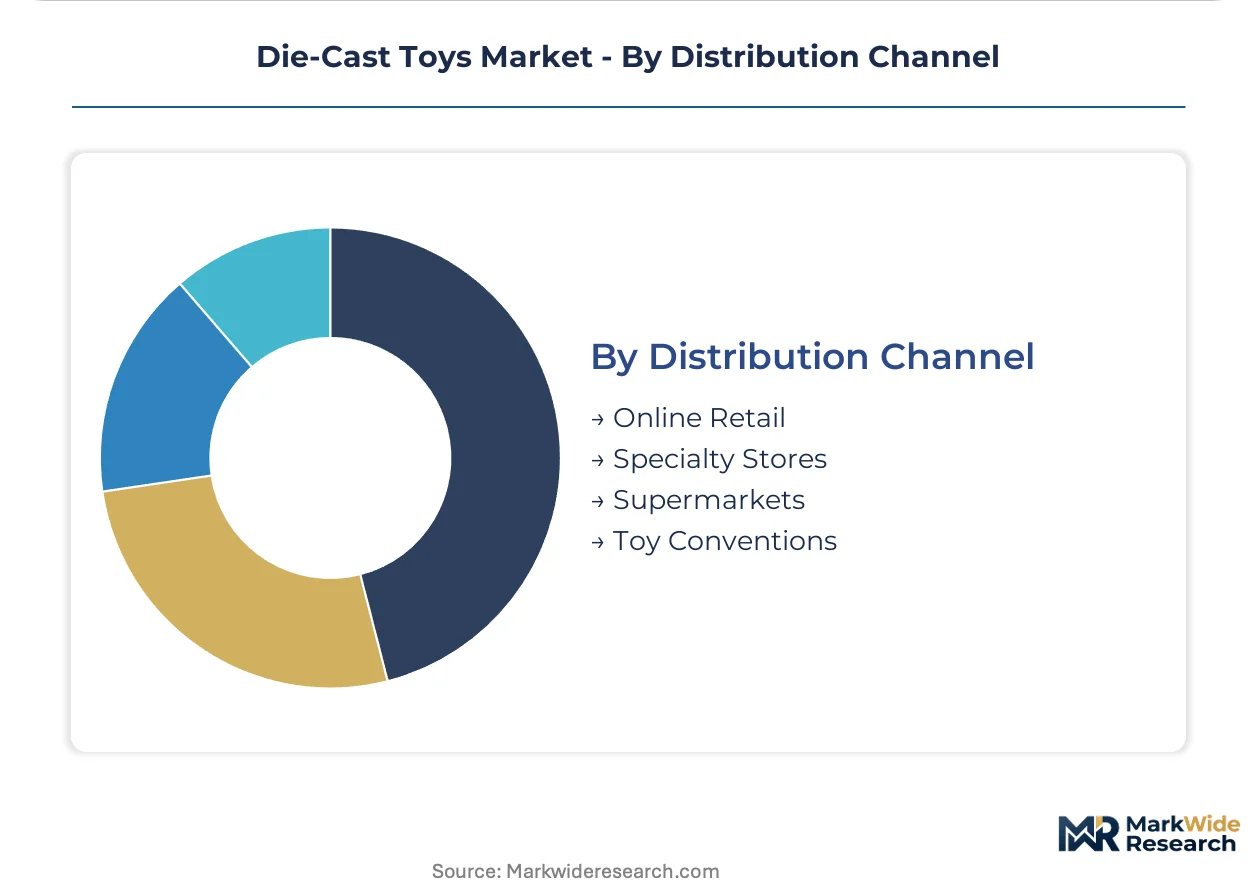
Distribution Channel:
Geography of demand concentration shapes channel investment priorities between established retail and emerging digital infrastructure.
- Online Retail:Manufacturer-direct platforms and auction sites eliminate distributor markups while capturing behavioral data for targeted heritage releases. Digital penetration concentrates in German and US enthusiast communities where automotive brand loyalty supports advance payment models.
- Specialty Stores:Hobby shops and collector boutiques sustain premium positioning through curated inventory and staff expertise. These channels anchor presence in Tokyo's Akihabara district, Los Angeles hobby corridors, and Frankfurt model railway centers.
- Supermarkets:Big-box retail maintains mass-market volume through seasonal promotional cycles and impulse placement.
- Toy Conventions:Event-based commerce enables exclusive drops and direct collector feedback for limited-run validation.
Supermarkets retains volume leadership; Online Retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for precision-engineered collector imports, while Shenzhen's Yantian container terminals handle outbound alloy shipments to specialty retailers worldwide.
China
Urban middle-class expansion in Shanghai, Beijing, and Shenzhen drives localized demand for heritage vehicle replicas previously exported exclusively. GB 6675 toy safety certifications from the national standards body extend product launch windows by 8-14 weeks versus historical benchmarks. Dongguan's Pearl River Delta production cluster concentrates mold-making and alloy sourcing, creating single-point vulnerability for global supply continuity.
United States
Automotive brand loyalty in enthusiast communities supports advance payment thresholds exceeding standard wholesale terms for limited editions. The Consumer Product Safety Commission enforces sharp-edge and small-parts standards that directly shape mold design and age-grading decisions. Los Angeles hobby corridors and Midwest collector hubs sustain specialty retail infrastructure for premium positioning.
Germany
REACH Annex XVII cadmium restrictions compel alloy reformulation across European-bound production, accelerating lead-free zinc formulations. ECHA chemical compliance databases require divergent lot-tracking protocols that inflate administrative overhead for alloy composition documentation. Frankfurt model railway centers and Stuttgart automotive heritage clusters anchor continental collector demand.
Japan
Precision-engineered vehicle replicas command elevated price points through material differentiation and multi-generational brand loyalty. METI industrial standards coordinate with JIS specifications for toy safety and alloy traceability. Tokyo's Akihabara district and Nagoya manufacturing belt sustain domestic collector market dominance through curated specialty channels.
India
Underdeveloped specialty retail infrastructure presents first-mover positioning for direct-import partnerships with Mumbai and Delhi hobby distributors. BIS certification requirements for imported toys create compliance entry barriers for new market entrants. Maharashtra and Gujarat trading hubs concentrate import logistics for alloy-based collectibles targeting emerging urban collector segments.
Die-Cast Toys Market Competitive Environment
On the supply side, the industry is bifurcated between mass-market manufacturers and precision specialists serving adult collectors. Foundry scale in Asian production facilities anchors commodity-tier output, while heritage mold-making capabilities concentrate in German and Japanese heritage facilities. Two strategic archetypes dominate: automotive licensing aggregators and manufacturing-scale operators. Competitive moves center on direct-to-collector digital platforms and REACH-compliant alloy reformulation partnerships.
Within the licensing-aggregator archetype, Jada Toys and Greenlight occupy positions defined by automotive brand partnerships and shelf presence in hobby shops. Maisto represents the manufacturing-scale tier, with production anchored in Asian facilities. These three entities exemplify how supply-side specialization—licensing leverage versus foundry efficiency—shapes competitive positioning without vertical integration into raw material sourcing.
| Leading Market Players |
|---|
| Jada Toys |
| Maisto |
| New-Ray |
| Tomica |
| Greenlight |
| Welly |
| Bburago |
| Motor Max |
| M2 Machines |
| Others |
Value Chain & Pricing Dynamics
Dongguan's Pearl River Delta production cluster concentrates mold-making capacity and alloy sourcing for die-cast toy manufacturing, translating foundry scale into downstream pricing leverage for volume buyers while compressing margins for smaller orders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates die-cast toy transactions. Premium tiers command elevated positioning through REACH-compliant lead-free zinc formulations and limited-edition heritage licensing, while economy segments face acute price sensitivity from mass-market retail consolidation. Cost compression in standard tiers intensifies because zinc price volatility on the London Metal Exchange feeds directly into foundry contract renegotiations. Mass-market children's segments exhibit highest price sensitivity, whereas adult collector specialty channels absorb material premiums for certified alloy compositions.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for die-cast toy distributors. Manufacturing gravity centers on China, Vietnam, and Thailand for alloy injection and finishing operations. Raw material flows draw from Australian zinc concentrate, Indonesian aluminum smelters, and domestic Chinese rare earth stabilizers. Single-source vulnerability concentrates in Dongguan's specialized mold-making artisan pool. Distribution runs through Shenzhen's Yantian container terminals for ocean freight consolidation to Hamburg, Los Angeles, and Yokohama port hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Die-cast toy incumbents must defend against resin-based 3D-printed collectibles and digital NFT vehicle replicas that threaten to displace physical heritage replicas in younger collector cohorts.
For Market Incumbents: Build regulatory certification moats by securing advance GB 6675 compliance for China-bound production and ECHA traceability protocols for European lots. Foundry partnerships in Vietnam and Thailand reduce Dongguan concentration risk. Direct-to-collector digital platforms capture behavioral data for targeted heritage releases, countering mass-market margin erosion.
For New Entrants and Emerging Players: Pursue India's emerging collector segment through Mumbai and Delhi hobby distributor partnerships where BIS certification barriers filter weaker competitors. Tier-one Chinese cities present secondary white-space for precision-engineered aluminum vehicle replicas. Crowdfunding pre-order aggregation offers capital-efficient market validation before mold cutting investments.
For Investors and Strategic Acquirers: Long-term, this sits as a licensing-arbitrage play because automotive brand partnerships concentrate value in intangible assets rather than manufacturing scale. Target acquisition profiles emphasize heritage mold libraries and exclusive manufacturer licensing agreements with German or Japanese automotive brands. The signal to watch is crowdfunded campaign oversubscription rates for limited heritage releases, indicating collector payment threshold elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Alloy Reformulation | Lead-free zinc compositions unlock European premium positioning and safety-conscious buyer segments. |
| Direct-to-Collector Digital Platform Launch | Manufacturer portals eliminate distributor markups while capturing behavioral data for targeted releases. |
| Heritage Mold Library Acquisition | Retiring German and Japanese tool-and-die specialists constrain precision replication capabilities for limited runs. |
| Southeast Asian Production Footprint Expansion | Vietnam and Thailand facilities reduce Dongguan single-point vulnerability for global supply continuity. |
| Automotive Licensing Partnership Extension | Exclusive manufacturer agreements with heritage vehicle brands sustain multi-generational collector loyalty. |
Study Parameters
Operator-level perspectives from foundry operations managers, specialty retail buyers, automotive licensing directors, and alloy procurement leads anchored the qualitative base for this study. Secondary validation drew from customs trade records, SEC filings of listed toy manufacturers, GB standards documentation, and ECHA chemical restriction databases. Bottom-up production volume estimates triangulated against top-down consumer expenditure tracking across the analysis window.
Scenario-bracketing framed the analytical approach across optimistic, baseline, and conservative demand trajectories over the projection horizon. Segmentation dimensions modeled include product type, material chemistry grade, age-targeted design specifications, and distribution channel economics. CAGRs derived from historical volume trajectories adjusted for regulatory compliance cost pass-through and collector demographic shifts. Zinc price volatility assumptions and automotive licensing renewal rates served as key industry-specific forecast inputs.
Sensitivities concentrate around London Metal Exchange zinc price spikes, GB 6675 certification timeline extensions, and automotive brand licensing non-renewals. Forecasts reflect documented assumptions regarding adult collector demand elasticity and REACH enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Animation Toys Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Dartboard Market
Toys and Games
US Sex Toys Market
Toys and Games
Kids Fuse Beads Market
Toys and Games
Global Stem Toys Market
Toys and Games
Plush Toy Market
Toys and Games
Table Top Games Market
Toys and Games
Robot Toys for Children Market
Toys and Games
Baby Toys Market
Toys and Games
Drone for Kids Market
Toys and Games
Inflatable Toys Market
Toys and Games
Ride-Ons Market