
 Smoking Cessation and Nicotine De Addiction Market | 2026-2036
Smoking Cessation and Nicotine De Addiction Market Size, Share, and Industry Trends Forecast 2026-2036
Smoking Cessation and Nicotine De Addiction Market Intelligence
A divergence in research and development investment for novel non-nicotine therapies is bifurcating the competitive landscape. GlaxoSmithKline plc leverages its extensive pharmaceutical R&D pipeline to develop prescription-based treatments. In contrast, Perrigo Company plc specializes in the over-the-counter segment, focusing on accessible nicotine replacement therapies like gums and patches. Pfizer Inc. competes with a portfolio of both prescription drugs and consumer health products, controlling significant pharmacy channel access.
Smoking cessation and nicotine de-addiction encompasses products and therapies designed to help individuals quit tobacco use. These solutions function by either delivering controlled, tapering doses of nicotine to manage withdrawal symptoms or by using non-nicotine pharmacological agents like varenicline to block nicotine's effects in the brain. Nicotine replacement products, such as patches and gums, constitute a mature and high-volume product category. However, digital app solutions combined with behavioral therapy represent the fastest-growing therapeutic approach, driven by accessibility.
Market access and product claims are governed by stringent pharmaceutical regulations from agencies like the US FDA and the European Medicines Agency (EMA). These bodies mandate extensive clinical trials for new pharmacological therapies and oversee the marketing of over-the-counter products. Future competitive advantage will depend on navigating the evolving regulatory pathways for digital therapeutics and demonstrating long-term clinical efficacy.
Market Dynamics
The central dynamic shaping the smoking cessation market is the tension between highly regulated pharmacological pathways and the rapid, less constrained innovation cycle of digital health solutions. This creates a dual-track market where established pharmaceutical firms navigate lengthy clinical trials while tech-centric companies focus on user engagement and behavioral modification, often with a different evidence standard.
Growth Catalysts
- Stricter Tobacco Regulations:Public health frameworks, including the WHO Framework Convention on Tobacco Control and national-level advertising bans enforced by bodies like the US FDA, diminish tobacco's appeal and push smokers toward cessation aids.
- Digital Therapeutics Adoption:The integration of app-based cognitive behavioral therapy into corporate wellness and health insurance plans provides a scalable, accessible, and low-stigma treatment modality for users seeking to quit.
- Public Health Initiatives:Government-funded programs, particularly in the United Kingdom and the United States, that provide free or subsidized access to nicotine replacement therapies and counseling services directly stimulate product demand and patient enrollment.
Market Restraints
- Substitution from Vaping Products:The consumer perception of e-cigarettes as a self-directed cessation tool, despite a lack of formal medical endorsement, diverts a significant user base away from clinically validated therapies and into an unregulated parallel market.
- Clinical Trial Hurdles:The extensive time and capital required to conduct clinical trials that satisfy regulators like the EMA and Japan's PMDA for novel non-nicotine drugs create substantial barriers to entry for smaller biopharmaceutical innovators.
- Reimbursement Gaps:In many developing nations across Latin America and Africa, the absence of robust public or private insurance coverage for cessation products limits market penetration to affluent demographics, constraining overall volume.
Strategic Opportunities
- Emerging Market Expansion:There is a significant opportunity to introduce low-cost, over-the-counter nicotine replacement therapies, such as patches and gums, into high-smoking-prevalence countries in Southeast Asia and Eastern Europe where access is currently limited.
- Digital and Pharma Convergence:Combining prescription digital therapeutics with pharmacological treatments like varenicline offers a pathway to develop synergistic, high-efficacy interventions that can command premium reimbursement from payers.
- Novel Regulatory Pathways:The formalization of approval frameworks for Software as a Medical Device (SaMD) by regulators, including Germany's DiGA system, creates a defined commercialization route for evidence-based digital cessation solutions.
Industry Challenges
- Demonstrating Long-Term Efficacy:A primary operational challenge for digital therapeutic providers is generating longitudinal data to prove sustained smoking abstinence, a key requirement for securing broader reimbursement from payers and endorsement from clinical bodies.
- Intellectual Property Protection:Safeguarding proprietary algorithms and user-data models within digital health platforms while adhering to regulatory demands for transparency, such as those under GDPR, presents a complex legal and technical hurdle.
- User Engagement and Adherence:High attrition rates for both digital apps and NRT regimens remain a persistent problem, impacting real-world clinical outcomes and complicating the ability to prove value to healthcare providers and employers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoking Cessation and Nicotine De Addiction Market |
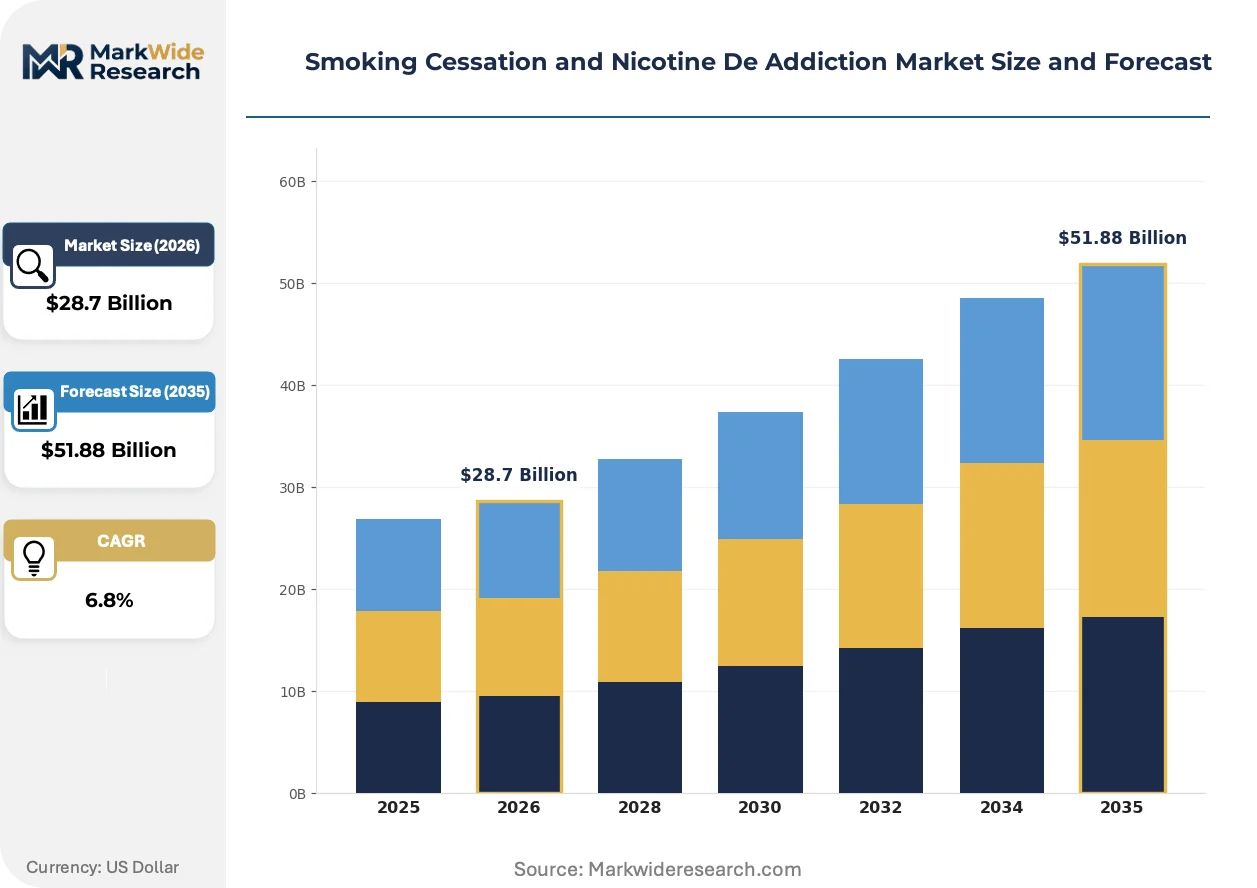
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nicotine Gum, Nicotine Patches, Inhalers, Lozenges Therapeutic Approach: Behavioral Therapy, Pharmacological Therapy, Counseling, Digital App Solutions Distribution Channel: Pharmacies, Online Retail, Health Clinics, Hospitals Target Demographic: Adults, Adolescents, Pregnant Women, Chronic Smokers |
| Companies Covered | GlaxoSmithKline plc, Pfizer Inc., Johnson & Johnson, Cipla Ltd., Perrigo Company plc, Teva Pharmaceutical Industries Ltd., Dr. Reddy’s Laboratories Ltd., British American Tobacco plc, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoking Cessation and Nicotine De Addiction Market Strategic Shifts & Innovations
The evolution of cessation strategies is defined by a deep shift toward personalization. This move away from one-size-fits-all products is driven by technological advancements in data analytics and a greater clinical understanding of addiction as a multifaceted condition requiring tailored support.
Digital therapeutic (DTx) platforms that leverage artificial intelligence to deliver personalized behavioral coaching are gaining traction. Health systems and employers are adopting these solutions to manage population health and reduce long-term costs associated with smoking-related diseases. The proliferation of these platforms is bifurcating the treatment landscape, creating a distinct, evidence-based category of prescription digital medicine that is separate from both traditional pharmaceuticals and general wellness applications.
Regulatory frameworks like the US FDA's Premarket Tobacco Product Application (PMTA) pathway are imposing rigorous scientific evidence standards on all new nicotine-containing products. This process creates a high barrier to entry and forces manufacturers to generate robust data on toxicology and user behavior. While primarily targeting e-cigarettes, this stringent oversight indirectly elevates the clinical evidence bar for next-generation nicotine replacement therapies seeking market authorization.
Demand is shifting toward integrated care models where smoking cessation is treated as a core component of managing chronic conditions like COPD or heart disease. This pivot disrupts the traditional direct-to-consumer pharmacy channel for NRTs, steering procurement toward institutional buyers like hospital networks and specialized clinics. This trend is most pronounced in healthcare systems with integrated delivery networks, particularly in the United States and the UK.
Smoking Cessation and Nicotine De Addiction Market Segmentation
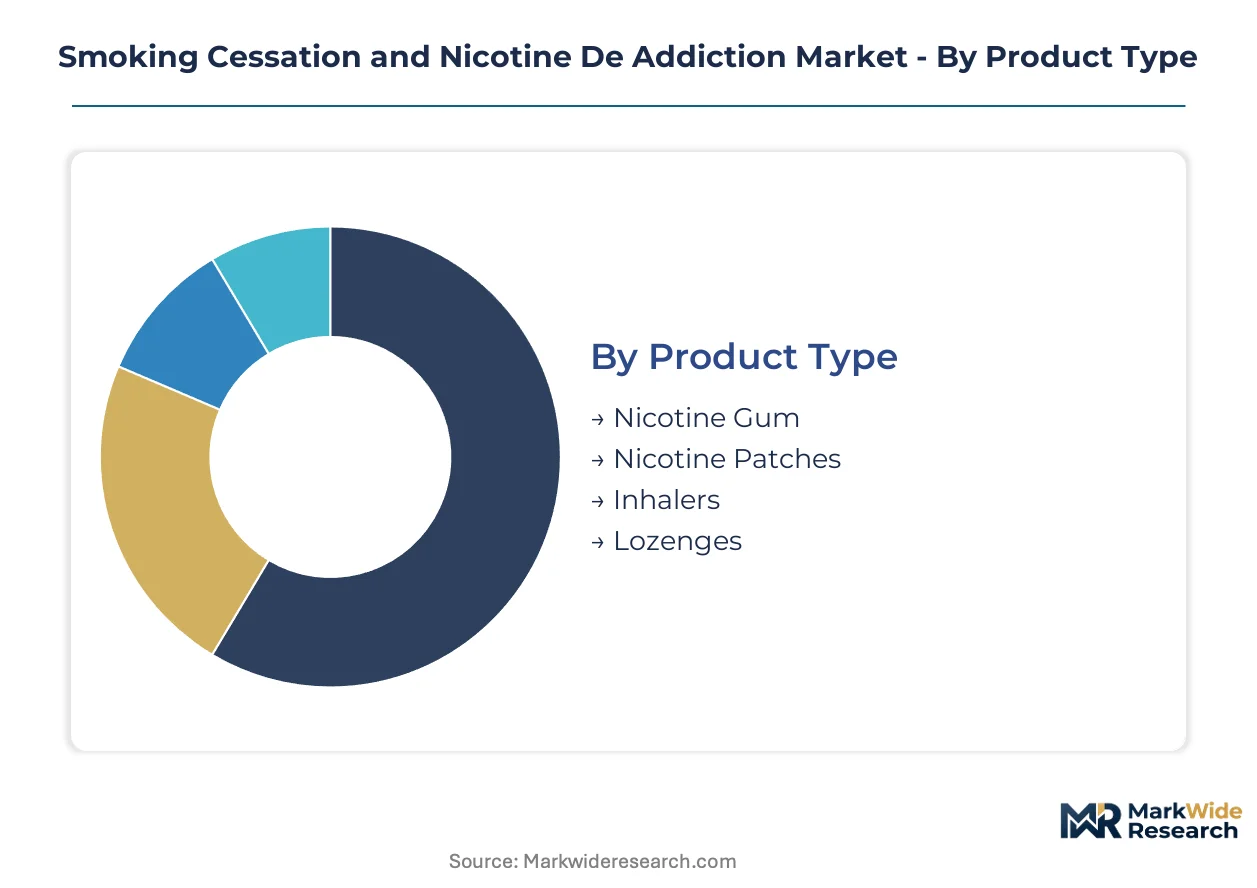
The Smoking Cessation and Nicotine De Addiction Market delineates into distinct segments, reflecting varied product functionalities, therapeutic approaches, distribution channels, and target demographics. This granular breakdown helps stakeholders understand specific demand patterns and competitive dynamics across the diverse landscape of quitting aids.
Product Type:
Product type segmentation reveals how different delivery mechanisms face varying levels of substitution pressure from alternative nicotine sources like vaping products.
- Nicotine Patches:These transdermal systems deliver a controlled dose of nicotine through the skin, managing withdrawal symptoms over a 24-hour period. Demand concentrates in regions like the United States where established healthcare systems often recommend them as a first-line therapy.
- Nicotine Gum:This oral formulation provides rapid nicotine delivery through buccal absorption, allowing users to control cravings as they arise. European markets show consistent demand, driven by accessibility in pharmacies and consumer familiarity.
- Inhalers:Nicotine inhalers mimic the hand-to-mouth action of smoking, providing both nicotine replacement and behavioral substitution.
- Lozenges:Nicotine lozenges dissolve slowly in the mouth, offering discreet nicotine delivery for craving management.
Nicotine Patches retains volume leadership; Nicotine Gum holds the steepest expansion curve.
Therapeutic Approach:
Therapeutic approaches differentiate based on their core methodology, influencing patient engagement and long-term efficacy outcomes.
- Pharmacological Therapy:This category includes prescription medications like varenicline and bupropion, which act on brain receptors to reduce cravings and withdrawal symptoms. These therapies see high adoption in clinical settings, particularly in the United Kingdom and Canada, supported by robust clinical evidence.
- Digital App Solutions:These platforms deliver cognitive behavioral therapy and personalized coaching through mobile applications, offering scalable and accessible support. Adoption is expanding most quickly within corporate wellness programs and health insurance plans in the United States.
- Behavioral Therapy:This involves counseling and psychological interventions designed to identify and modify smoking triggers and habits.
- Counseling:Professional guidance, often delivered one-on-one or in group settings, provides emotional support and practical strategies for quitting.
Pharmacological Therapy generates significant revenue; Digital App Solutions are gaining share fastest.
Distribution Channel:
Distribution channels illustrate the primary routes consumers use to access cessation products, impacting market reach and pricing strategies.
- Pharmacies:Retail pharmacies serve as a primary point of sale for over-the-counter nicotine replacement therapies, offering convenience and professional advice. This channel remains dominant across most developed markets, including Germany and France, due to established consumer habits.
- Online Retail:E-commerce platforms provide a discreet and convenient purchasing option, often with competitive pricing and a wider product selection. This channel experiences rapid growth, particularly among younger demographics and in regions with high internet penetration.
- Health Clinics:These medical facilities integrate cessation support into broader healthcare services, often prescribing pharmacological agents or referring patients to counseling.
- Hospitals:Hospitals offer cessation programs as part of inpatient and outpatient care, especially for patients with smoking-related health conditions.
Pharmacies command the largest market share; Online Retail exhibits the highest growth potential.
Target Demographic:
Target demographics highlight specific population groups with distinct needs and challenges in their cessation journey, influencing product development and marketing efforts.
- Adults:This broad demographic represents the largest segment of smokers seeking to quit, driving demand for a wide array of cessation products and therapies. Public health campaigns in countries like Australia and the Netherlands heavily target this group.
- Chronic Smokers:Individuals with long-term, heavy nicotine dependence often require more intensive and sustained interventions, including combination therapies. Specialized clinics in the United States focus on tailored programs for this demographic.
- Adolescents:Younger populations present unique challenges, requiring age-appropriate interventions and support to prevent long-term addiction.
- Pregnant Women:This sensitive demographic requires specialized, non-pharmacological or carefully selected cessation methods due to potential risks to fetal health.
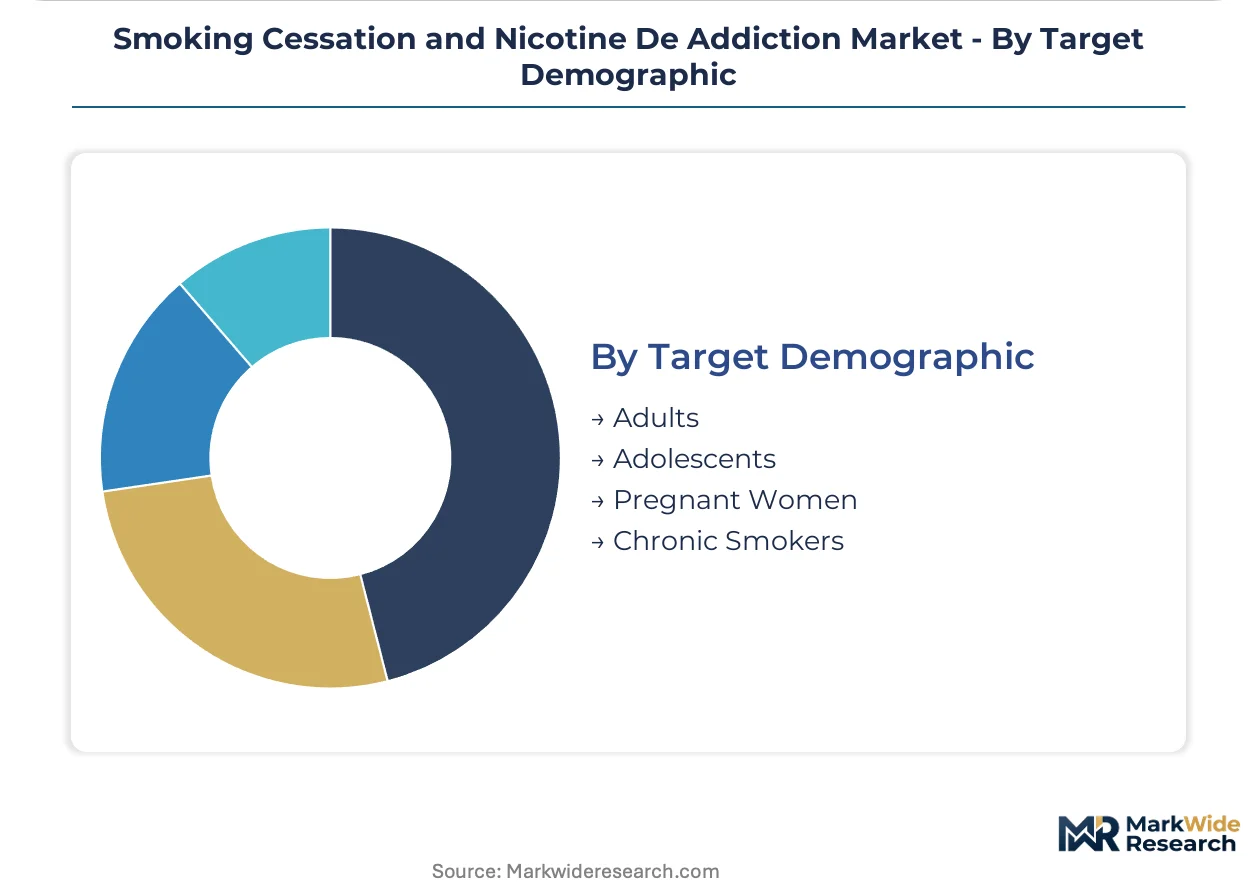
Adults drive the majority of market volume; Chronic Smokers represent a high-value patient cohort.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pricing power for smoking cessation solutions varies significantly, with premium reimbursement models prevalent in the United States contrasting sharply with the price-sensitive, low-cost product demand observed across Southeast Asia. This divergence shapes investment and market penetration strategies for cessation aid providers. Developed economies leverage robust healthcare systems for advanced therapies, while emerging markets prioritize accessible over-the-counter options.
United States
Demand for digital app solutions and pharmacological therapies drives the market in the United States. The US FDA's stringent regulations govern product approvals and claims, influencing market entry for novel treatments. Major healthcare hubs like Boston and San Francisco are centers for digital therapeutic innovation and clinical research.
United Kingdom
Public health initiatives and government-funded programs stimulate demand for nicotine replacement therapies and counseling in the United Kingdom. The National Institute for Health and Care Excellence (NICE) guidelines support evidence-based cessation interventions. London-based health tech companies are developing scalable digital solutions for behavioral support.
Germany
Pharmacies serve as a primary distribution channel for over-the-counter nicotine replacement products across Germany. The European Medicines Agency (EMA) sets high clinical trial standards for new pharmacological agents. Berlin and Munich are emerging as hubs for digital health startups focused on chronic disease management, including cessation.
Japan
Rigorous regulatory pathways, including those from Japan's PMDA, create high barriers for novel non-nicotine drugs in Japan. Consumer awareness campaigns encourage cessation, contributing to steady demand for established products. Pharmaceutical research centers in Tokyo and Osaka focus on developing next-generation pharmacological interventions.
India
Emerging market expansion opportunities for low-cost, over-the-counter nicotine replacement therapies exist in India. The absence of robust public or private insurance coverage limits market penetration for premium products. Major metropolitan areas like Mumbai and Delhi are seeing increased adoption of accessible cessation aids.
Smoking Cessation and Nicotine De Addiction Market Key Industry Players
Concentration sits with established pharmaceutical firms that possess extensive research and development pipelines for prescription-based treatments. The market exhibits a tiered structure, with a distinct bifurcation between these R&D-heavy players and over-the-counter specialists. Archetypes include global pharmaceutical giants, consumer health product manufacturers, and agile digital therapeutic providers. Dominant competitive moves involve pipeline development for novel non-nicotine therapies, strategic acquisitions to integrate digital health capabilities, and securing market access through stringent regulatory pathways.
Within the established pharmaceutical tier, GlaxoSmithKline plc represents a firm leveraging a deep R&D pipeline for prescription treatments, particularly in novel non-nicotine therapies. Pfizer Inc. exemplifies an integrated player, controlling significant pharmacy channel access with a robust portfolio spanning both prescription drugs and consumer health products. Perrigo Company plc anchors the over-the-counter segment, focusing intently on accessible nicotine replacement therapies like gums and patches, ensuring broad consumer reach through retail channels. These companies collectively influence market direction through product innovation, distribution network strength, and adherence to evolving regulatory landscapes.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Johnson & Johnson |
| Cipla Ltd. |
| Perrigo Company plc |
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy’s Laboratories Ltd. |
| British American Tobacco plc |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
The US FDA's stringent approval pathway for novel pharmacological therapies gates both supply qualification and enables premium price differentiation for manufacturers. This regulatory environment directly influences the cost structures and market entry barriers for cessation products, impacting both established pharmaceutical firms and emerging digital therapeutic providers.
Pricing Analysis
Pricing for smoking cessation solutions reflects a hybrid model, with value-based reimbursement dominating prescription drugs and transactional pricing for over-the-counter nicotine replacement therapies. Price differentiation stems from proven clinical efficacy for pharmacological agents and brand recognition for accessible consumer health products. Pricing pressure stems from the consumer perception of e-cigarettes as a lower-cost cessation alternative, particularly for nicotine replacement products. Uninsured individuals and those in developing nations exhibit the highest price sensitivity for basic cessation aids.
Supply Chain Analysis
Port congestion in major shipping lanes, particularly impacting inbound raw materials from Asia, introduces volatility into the supply chain for nicotine replacement therapies. Geographic supply concentration for active pharmaceutical ingredients (APIs) primarily rests in India and China, crucial for both generic and branded prescription cessation drugs. Raw material dependencies include pharmaceutical-grade nicotine, specialized excipients for patches and gums, and digital infrastructure components. Regulatory hurdles for new drug approvals across agencies like the EMA and Japan's PMDA represent a structural supply chain risk. Distribution runs through established pharmacy networks, increasingly supplemented by online retail platforms and institutional procurement by healthcare systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Success in the Smoking Cessation and Nicotine De Addiction Market hinges on bridging a capability gap in integrating digital behavioral science with pharmacological development, demanding specialized expertise in both domains.
For Market Incumbents: Compound investment in long-term clinical trials for combined pharmacological and digital therapeutic interventions to counter the threat of unregulated vaping products. Acquire specialized digital health platforms with established user engagement metrics to bolster behavioral support capabilities. Leverage existing pharmacy channel control to integrate new product launches and educational campaigns. Prioritize R&D into novel non-nicotine therapies to diversify away from traditional NRTs.
For New Entrants and Emerging Players: Anchor in underserved geographic markets, such as Southeast Asia, with low-cost, accessible nicotine replacement therapies. Target corporate wellness programs in developed economies like the United States with scalable digital app solutions. Partner with local healthcare providers or insurance companies to gain rapid market access and build trust among patient populations seeking cessation support. Focus on niche digital solutions addressing specific comorbidities associated with smoking.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the digital therapeutic segment due to significant R&D and regulatory compliance costs. The market shows sustained growth over the next decade, driven by persistent addiction rates and public health initiatives. Target acquisition archetypes include digital therapeutic providers with validated clinical outcomes and established Software as a Medical Device (SaMD) regulatory approvals. Formalization of digital therapeutic reimbursement codes in key markets, such as Germany's DiGA system, serves as a critical signal to watch for broader market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates development of novel non-nicotine therapies, expanding treatment options for chronic smokers. |
| Regulatory Approval Pathway | Secures market authorization for digital therapeutics, enabling broader healthcare system integration. |
| Strategic Partnership | Combines pharmaceutical expertise with digital health innovation, creating synergistic cessation solutions. |
| Distribution Channel Expansion | Increases access to cessation aids in high-smoking-prevalence emerging markets like India. |
| Pipeline Diversification | Reduces reliance on traditional NRTs, adapting to evolving consumer preferences and regulatory landscapes. |
Research Approach
Findings reconcile primary fieldwork against secondary review of US FDA filings, EMA submissions, WHO reports, and clinical trial registries. Primary interviews engaged pharmaceutical R&D executives, public health officials, digital health founders, and payer representatives to capture diverse market perspectives. This approach ensured a robust understanding of both technological advancements and regulatory complexities, triangulating insights from bottom-up market intelligence and top-down industry analysis.
The analytical framework modeled segmentation dimensions including product type, therapeutic approach, distribution channel, target demographic, and regional regulatory frameworks. Compound annual growth rates were derived through rigorous regression analysis and expert consensus, projecting market trajectory across the analysis window. Forecast inputs considered global tobacco consumption rates, evolving healthcare expenditure patterns, and anticipated regulatory changes affecting market access for cessation aids.
Decision-makers should treat outputs as directional under base assumptions of continued public health support and stable regulatory environments; material deviation would warrant model refresh. Forecasts reflect assumptions regarding the efficacy of public health campaigns and the uptake of novel digital solutions. Unforeseen shifts in e-cigarette regulation or significant changes in healthcare reimbursement policies represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
North America Hair Loss Treatment Products Market
Personal Health
Sleeping Aids Market
Personal Health
Asia Health Check-Ups Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Sexual Wellness Market
Personal Health
Patient Health Management Market
Personal Health
Biohacking Market
Personal Health
Menstrual Cup Market
Personal Health
Health Check-Up Market
Personal Health
Feminine Hygiene Market
Personal Health
Health Coaching Market
Personal Health
Menopause Wellness Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Sleep Mask Market
Personal Health
PTBCHA Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market