
 Digital Textile Printing Market | 2026-2036
Digital Textile Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Textile Printing Market Analysis
Italian ink formulation capacity is hardening as European converters demand pigment systems compatible with tighter effluent rules. Kornit Digital leverages its NeoPigment chemistry to capture share in waterless workflows. Mimaki Engineering sustains leadership in wide-format dye-sublimation through precision heads engineered for polyester sportswear. Durst Group AG anchors industrial-scale single-pass production with its P5 platform architecture.
Digital textile printing deposits colorant directly onto fabric via piezoelectric or thermal inkjet heads, eliminating rotary screens and enabling lot sizes as small as one unit with sub-millimeter registration accuracy. Inkjet technology dominates installed base volumes while dye-sublimation commands premium positioning in athletic apparel for its colorfastness under wash and UV stress. Direct-to-fabric systems are displacing transfer workflows in home décor as brands compress time-to-shelf for seasonal collections.
REACH restricts azo dyes and heavy metal carriers across European supply chains, while EPA effluent guidelines shape discharge protocols for US-based finishing operations. ECHA's candidate list expansion is forcing reformulation of reactive ink binders, and ISO 14001 certification is becoming a gatekeeping standard for supplier qualification at major apparel retailers. Stakeholders must track how OEKO-TEX and ZDHC roadmap convergence will reorder chemical supplier tiers before the next procurement cycle locks in.
Market Dynamics
On-demand production models are collapsing minimum order quantities and compressing design-to-retail cycles across fashion supply chains. REACH chemical restrictions and EU Green Deal effluent mandates are forcing simultaneous reformulation of ink chemistries and wastewater infrastructure.
Growth Catalysts
- EU Green Deal discharge limits:Tighter effluent rules are accelerating migration from reactive dyes to pigment-based systems that eliminate water-intensive washing stages.
- Polyester sportswear demand:Athletic apparel brands are expanding dye-sublimation capacity for colorfastness under UV and repeated wash cycles.
- Como silk district concentration:Italian converters are aggregating specialized ink formulation expertise to serve luxury fashion houses requiring rapid sample turnaround.
Market Restraints
- Piezoelectric head supply concentration:Precision printhead manufacturing concentrates in Japanese and German component suppliers, creating single-source vulnerability for system integrators.
- Reactive ink binder reformulation costs:ECHA candidate list expansion is forcing mid-scale converters to absorb R&D expenses for compliant chemistry without volume offsets.
- Rotary screen residual cost advantage:Long-run textile printing in South Asian export hubs retains cost efficiency where design change frequency remains low.
Strategic Opportunities
- Home décor direct-to-fabric adoption:Interior textiles are bypassing transfer paper workflows as brands compress seasonal collection lead times.
- ISO 14001 certification gatekeeping:Major apparel retailers are elevating environmental management certification to supplier qualification criteria, favoring certified converters.
- Waterless pigment workflow expansion:NeoPigment chemistry is penetrating markets beyond sportswear into technical textiles and soft signage.
Industry Challenges
- Color management specialist scarcity:Digital textile production requires operators trained in ICC profiling and substrate-specific ink limitation, creating hiring bottlenecks.
- Single-pass system capex intensity:Industrial-scale installations demand eight-figure capital commitments that strain converter balance sheets.
- OEKO-TEX and ZDHC roadmap convergence:Competing chemical compliance frameworks are creating audit duplication before standard harmonization completes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Textile Printing Market |
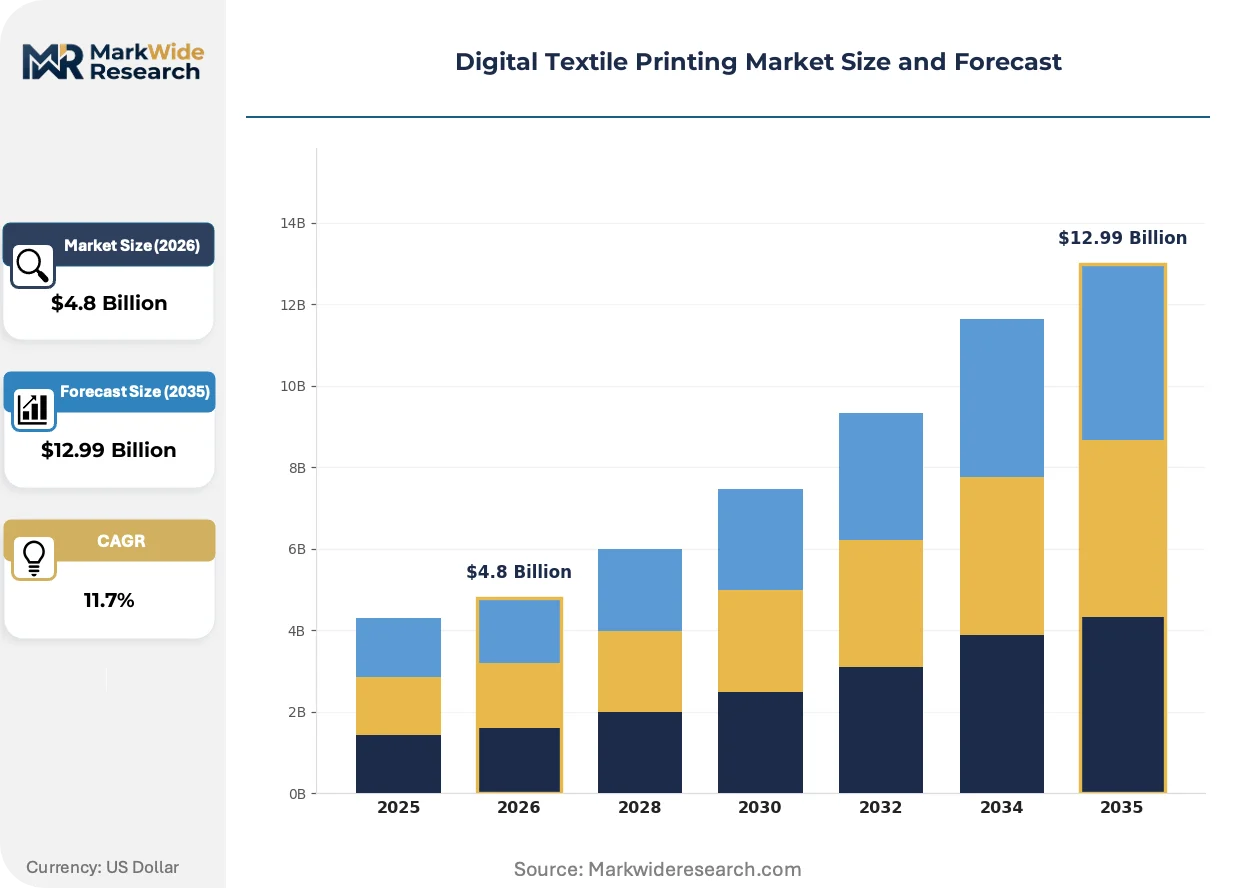
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inks, Printers, Software, Materials Technology: Inkjet, Dye-Sublimation, Direct-to-Fabric, Textile Transfer End User: Fashion, Home Décor, Technical Textiles, Automotive Application: Custom Printing, Mass Production, Sample Production, Prototype Development |
| Companies Covered | Kornit Digital, Mimaki Engineering, Seiko Epson Corporation, Durst Group AG, EFI Reggiani, Roland DG Corporation, Konica Minolta, Brother Industries, SPGPrints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Textile Printing Market Emerging Trajectories
Workflow digitization is collapsing the boundary between design software and production equipment. Three converging developments are reconfiguring how colorants reach fabric.
Single-pass inkjet architecture is unifying pre-treatment, printing, and fixation into continuous production lines. Technical textile manufacturers in Germany's industrial belt are adopting these systems to serve automotive and medical end-uses demanding lot traceability. The technology is unifying previously separate finishing stages, eliminating work-in-process inventory buffers.
REACH authorization procedures are restricting azo dye precursors and heavy metal carriers across European supply chains. Italian ink formulators are accelerating pigment dispersion R&D to maintain formulation sovereignty. Converter operations in Como and Prato are most affected, with several facilities completing effluent system retrofits ahead of enforcement deadlines.
Brand procurement departments are compressing supplier panels and mandating digital sample capabilities. Direct-to-garment workflows are displacing traditional strike-off processes for initial collection development. This concentration is most visible in Milan-based luxury houses and Berlin direct-to-consumer labels, where design iteration cycles have shortened from weeks to days.
Digital Textile Printing Market Segmentation
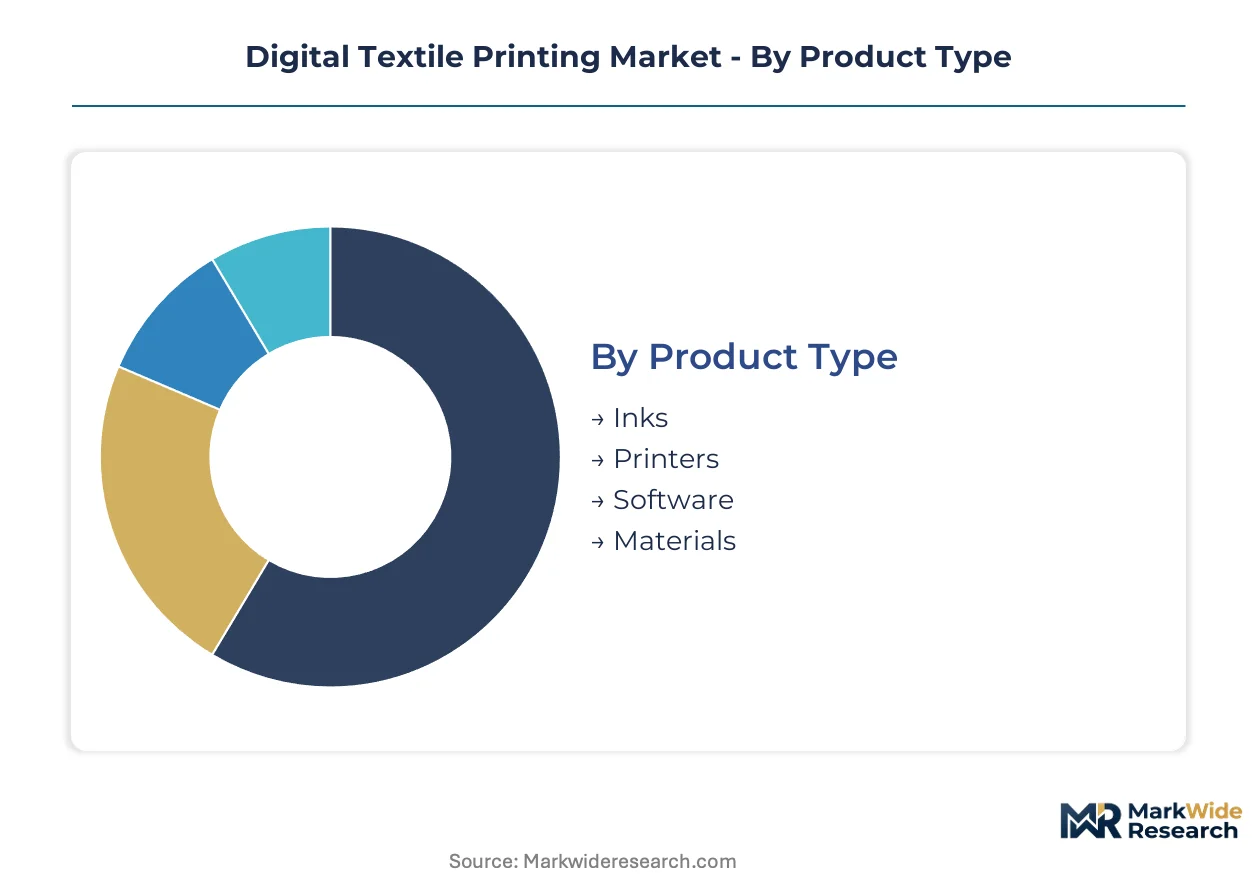
Digital textile printing segmentation reflects how buyers prioritize speed-to-market, regulatory compliance, and production flexibility. Technology choices determine chemical handling requirements, while end-use applications dictate substrate compatibility and colorfastness specifications. Understanding these segment boundaries clarifies where capital investments concentrate and which supplier tiers capture margin.
Product Type:
Buyers allocate budget across hardware, consumables, and workflow software based on their position in the supply chain and regulatory exposure.
- Inks:Pigment, reactive, acid, and disperse formulations dominate procurement spend. REACH-compliant pigment systems are displacing reactive chemistries in Como district operations as converters retrofit effluent infrastructure ahead of enforcement deadlines.
- Printers:Single-pass industrial systems and multi-pass scanning platforms anchor capital expenditure decisions. German technical textile manufacturers favor Durst P5 architecture for automotive lot traceability requirements, while Italian converters prioritize Mimaki wide-format units for silk sampling workflows.
- Software:RIP engines and color management suites bridge design platforms to production equipment. Kornit Digital integrates NeoPigment profiling into proprietary workflow stacks to lock in recurring service revenue.
- Materials:Pre-treatment chemistries, fixation agents, and substrate handling consumables complete the operational stack. ECHA candidate list expansion is forcing reformulation of binder systems without volume offsets for mid-scale converters.
Inks lead on scale; software leads on momentum.
Technology:
Process selection hinges on substrate chemistry, run length economics, and water treatment capacity.
- Inkjet:Piezoelectric and thermal deposition heads deposit colorant directly onto fabric via droplet ejection. The installed base concentrates in fashion sampling and soft signage where sub-millimeter registration accuracy justifies equipment cost.
- Dye-Sublimation:Disperse dyes transfer from paper to polyester under heat and pressure. Athletic apparel brands in Germany's Ruhr industrial belt are expanding capacity for UV-stable, wash-fast sportswear production.
- Direct-to-Fabric:Pre-treated substrates receive inkjet deposition without transfer paper intermediaries. Home décor brands in Milan are bypassing transfer workflows to compress seasonal collection lead times from weeks to days.
- Textile Transfer:Intermediate paper carries design to fabric via calendering or heat press. Rotary screen residual cost advantage persists in South Asian export hubs where design change frequency remains minimal.
Inkjet dominates installed volumes; direct-to-fabric climbs the fastest.
End User:
Industry verticals impose distinct performance standards and certification requirements that reshape supplier qualification.
- Fashion:Luxury houses and fast-fashion retailers demand rapid sample turnaround and small-lot flexibility. Berlin direct-to-consumer labels have collapsed design-to-retail cycles through digital strike-off replacement.
- Home Décor:Interior textile brands require color consistency across curtain, upholstery, and bedding applications. Direct-to-fabric adoption is accelerating as procurement departments compress supplier panels.
- Technical Textiles:Automotive and medical end-uses demand lot traceability and ISO 14001 certification. German manufacturers in Baden-Württemberg are adopting single-pass systems to unify pre-treatment, printing, and fixation stages.
- Automotive:Seat fabric and interior trim suppliers face OEM mandates for chemical compliance and durability testing. Pigment ink systems are penetrating this segment for waterless workflow advantages.
Fashion leads on volume concentration; technical textiles show the steepest expansion trajectory.
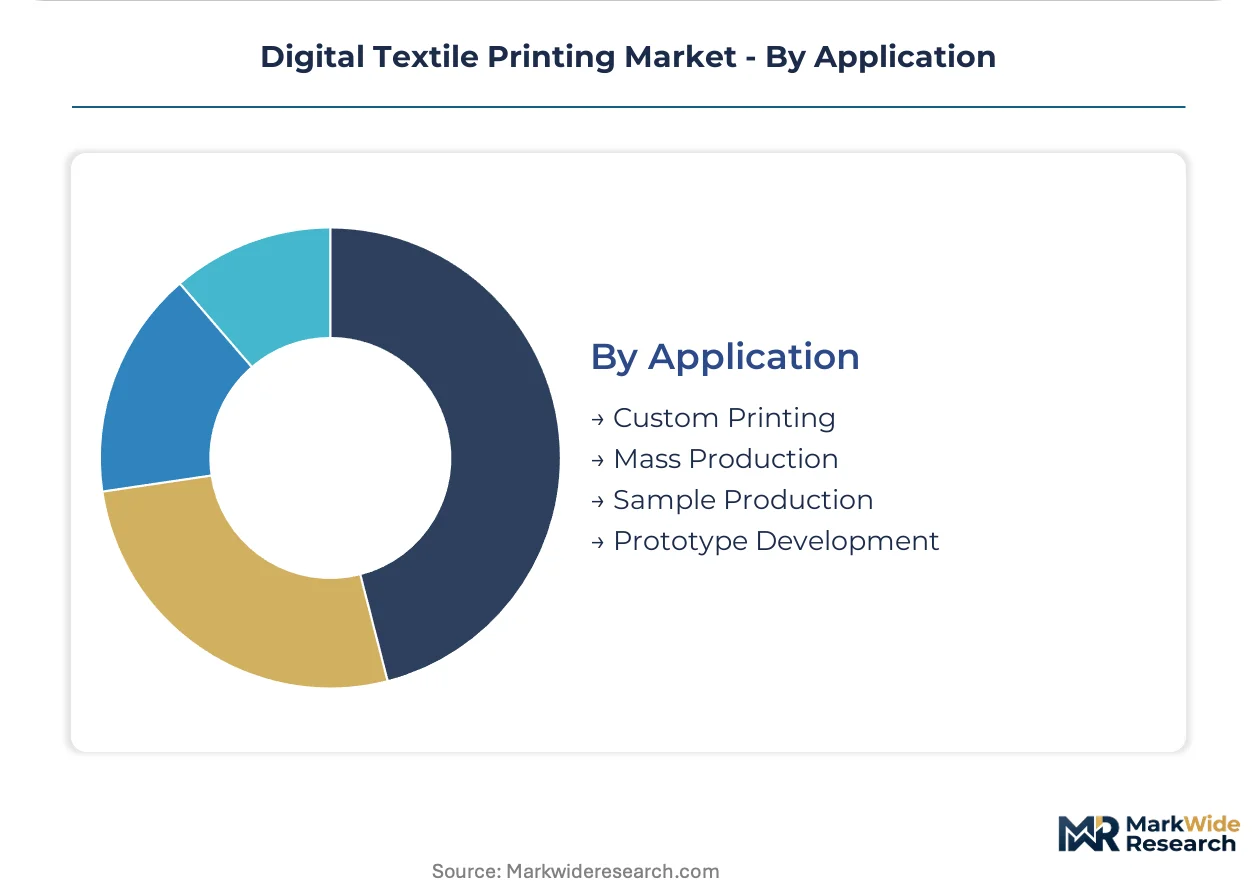
Application:
Production purpose determines equipment configuration, staffing models, and margin structure.
- Custom Printing:Lot-size-one production serves individual consumers and micro-brands. On-demand models are collapsing minimum order quantities across European supply chains.
- Mass Production:Long-run efficiency competes with rotary screen economics. South Asian export hubs retain cost advantage where design stability permits analog workflows.
- Sample Production:Rapid strike-off generation accelerates collection development. Milan-based luxury houses have shortened iteration cycles from weeks to days through digital workflows.
- Prototype Development:Pre-production validation requires color-accurate, short-run capability. Como silk district converters aggregate specialized expertise to serve this demand tier.
Mass production leads on scale; custom printing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy concentrates specialized ink formulation expertise while Germany dominates industrial-scale system manufacturing, creating complementary poles of technical leadership across European supply chains.
Italy
Luxury fashion houses in Milan demand rapid sample turnaround for silk and high-end synthetics. REACH authorization procedures restrict azo dye precursors across Italian supply chains. Como district converters aggregate pigment dispersion R&D to serve rapid prototyping workflows ahead of enforcement deadlines.
Germany
Technical textile manufacturers seek lot traceability for automotive and medical end-uses. EU Green Deal effluent mandates accelerate migration from reactive dyes to waterless pigment systems. Baden-Württemberg and North Rhine-Westphalia industrial belts adopt single-pass architecture to unify pre-treatment, printing, and fixation stages.
United States
Apparel retailers compress supplier panels and mandate digital sample capabilities for strike-off replacement. EPA effluent guidelines shape discharge protocols for finishing operations in southeastern textile corridors. Direct-to-garment workflows expand in Los Angeles and New York Metro clusters serving direct-to-consumer labels.
Japan
Piezoelectric printhead manufacturing concentrates precision component supply for system integrators worldwide. METI industrial standards influence deposition head reliability specifications across Asian export markets. Nagoya and Tokyo industrial zones anchor thermal and piezoelectric head fabrication capacity.
China
Domestic sportswear brands expand dye-sublimation capacity for polyester athletic apparel production. National dual carbon goals pressure textile finishing operations to reduce water-intensive washing stages. Yangtze River Delta and Pearl River Delta manufacturing clusters retrofit effluent infrastructure for pigment system compatibility.
Digital Textile Printing Market Vendor Landscape
Japanese and German producers anchor one tier; Israeli and Italian specialists hold differentiated positions in chemistry and sampling workflows. The vendor structure fragments across three strategic tiers: industrial-scale system integrators, wide-format sampling specialists, and ink chemistry formulators. Competitive positioning depends on M&A activity consolidating printhead supply chains and strategic partnerships bridging hardware with proprietary workflow software.
Within the chemistry-integrated tier, Kornit Digital exemplifies waterless pigment system architecture, while Mimaki Engineering occupies a position in wide-format dye-sublimation platforms. Durst Group AG anchors industrial single-pass production systems serving technical textile manufacturers. These three companies represent distinct archetypes: chemistry-proprietary workflow integration, precision sampling equipment, and continuous production line architecture.
| Leading Market Players |
|---|
| Kornit Digital |
| Mimaki Engineering |
| Seiko Epson Corporation |
| Durst Group AG |
| EFI Reggiani |
| Roland DG Corporation |
| Konica Minolta |
| Brother Industries |
| SPGPrints |
| Others |
Supply Flow & Price Mechanics
Color management specialist scarcity in Italy's Como silk district widens pricing spreads between premium certified workflows and economy-tier operations lacking ICC profiling capabilities. Labor-cost differentials between German technical textile engineers and South Asian rotary screen operators sustain three-tier pricing stratification across pigment, reactive, and transfer-based production systems.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for dye-sublimation hardware as domestic sportswear brands expand polyester printing capacity. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified German automotive suppliers from uncertified transfer-paper converters in Bangladesh and Vietnam. Price differentiation hinges on REACH compliance certification and volume scale, with mid-scale Italian converters absorbing the steepest margin compression from reactive ink binder reformulation costs. Small-lot sampling workflows in Milan command premium positioning, while mass-production tiers face persistent pricing softness from rotary screen residual economics in South Asian export hubs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for automotive seat fabric and medical technical textiles requiring lot traceability. Precision piezoelectric printhead manufacturing concentrates in Japan and Germany, while ink formulation expertise clusters in Italy and Israel. Raw material dependencies include pigment dispersions, reactive dye precursors, and polyester substrate feedstocks. Single-source vulnerability in Japanese thermal head fabrication creates supply chain risk for system integrators lacking dual-qualified component sources. Distribution runs through specialized textile machinery distributors serving converter networks across European industrial belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through waterless pigment workflow adoption, as brands absorb premium pricing for REACH-compliant chemistry that eliminates wastewater infrastructure capital. Pigment system penetration into technical textiles and soft signage creates tier-upgrading opportunities for certified converters.
For Market Incumbents: Cement formulation sovereignty by acquiring specialized dispersion R&D capabilities in Italy's Como district before enforcement deadlines lock in supplier relationships. Deepen backward integration into pre-treatment chemistry production to capture margin pools threatened by ECHA candidate list expansion. Lock in multi-year service contracts with luxury fashion houses in Milan to defend against emerging sampling specialists offering compressed turnaround times. For New Entrants and Emerging Players: Direct-to-garment platform routes offer the lowest customer acquisition friction for penetrating Berlin's direct-to-consumer label cluster. Target home décor sampling workflows in Milan where supplier panel compression creates white-space for digital strike-off specialists. Pursue ISO 14001 certification as a gating qualification for technical textile procurement departments in Germany's Baden-Württemberg industrial belt. For Investors and Strategic Acquirers: Industrial machinery conglomerates with textile sector exposure are the most active acquirer in this space, seeking chemistry-integrated workflow platforms. Long-term viability centers on waterless pigment system adoption trajectories across automotive and medical end-uses. Monitor OEKO-TEX and ZDHC roadmap convergence completion as an inflection signal for chemical supplier tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Dispersion | Italian formulators capture margin pools threatened by REACH authorization deadlines. |
| Single-Pass System Deployment | German technical textile manufacturers unify finishing stages for automotive lot traceability. |
| ISO 14001 Certification Investment | Converters qualify for major apparel retailer procurement panels elevating environmental standards. |
| Direct-to-Fabric Workflow Expansion | Home décor brands bypass transfer paper to compress seasonal collection lead times. |
| Regional Service Hub Establishment | Proximity to Como silk district converters enables rapid response sampling contracts. |
Methodological Framework
Multiple input streams — executive interviews with digital textile printer OEMs, procurement directors at Milan-based luxury houses, and plant managers at German technical textile facilities — were reconciled against customs trade data, SEC equipment supplier filings, and ECHA regulatory databases. Primary fieldwork with ink formulators in Italy's Como district and dye-sublimation converters in China's Pearl River Delta supplemented secondary validation from ISO certification registries and ZDHC compliance disclosures. Bottom-up equipment shipment analysis and top-down end-use demand estimation were triangulated to anchor volume projections.
Historical capacity installation patterns were cross-referenced against panel input from RIP software developers and color management specialists to model adoption curves across the projection horizon. Segmentation dimensions included technology type, ink chemistry class, end-use vertical, and regional regulatory cluster. CAGRs were derived from equipment replacement cycles and brand procurement policy shifts toward on-demand production models. Forecast inputs incorporated REACH enforcement timelines and EU Green Deal effluent infrastructure investment trajectories.
The model assumes a particular technology adoption path; alternative pathways for waterless pigment systems would alter the outlook if reactive dye wastewater treatment costs decline faster than projected. Forecasts reflect base-case assumptions regarding printhead reliability improvements and single-pass system capex amortization periods. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
Smart Textile Market
Textile Innovations
Quilt Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Clothes Fastener Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Textile Felt Market
Textile Innovations
GCC Textile Market
Textile Innovations
Canvas Bags Market
Textile Innovations
Global Textile Market
Textile Innovations
Waterproof Socks Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
Textile Acoustic Panel Market