
 Sanded Plywood Market | 2026-2036
Sanded Plywood Market Size, Share, and Industry Trends Forecast 2026-2036
Sanded Plywood Market Insights
Asset-light leasing models for veneer dryers and press equipment is narrowing the capital barrier for mid-scale entrants in sanded plywood manufacturing. Georgia-Pacific leverages its captive timber holdings and integrated resin production to sustain margin control across the value chain. Weyerhaeuser Company anchors its position through scale advantages in Douglas fir veneer supply. SVEZA competes in specialty birch plywood grades where Russian and Baltic raw material access differentiates product consistency.
Sanded plywood consists of thin wood veneers cross-laminated under heat and pressure, then surface-sanded to precise thickness tolerances typically ranging from 1/4 inch to 3/4 inch for finished applications. The material serves primarily as a dimensionally stable substrate for furniture, cabinetry, and interior finish systems where flatness and paint adhesion matter. Structural plywood dominates volume flows in building construction, while marine plywood commands premium positioning in moisture-exposed environments. Interior plywood grades are maturing in North American residential markets, though exterior plywood faces substitution pressure from engineered wood alternatives.
The EPA enforces TSCA Title VI formaldehyde limits that shape resin formulation choices and third-party certification requirements for U.S. producers. CARB compliance in California extends de facto national standards through supply chain spillover effects. OSHA workplace exposure rules for wood dust influence sanding line automation investments. Stakeholders must monitor evolving bio-based binder technologies and regional timber supply constraints as these forces reshape cost structures and sourcing geography.
Market Dynamics
EPA's TSCA Title VI formaldehyde emission limits are compressing resin formulation choices across U.S. plywood manufacturing, forcing capital redeployment toward low-emitting adhesive systems and third-party certification infrastructure.
Growth Catalysts
- Residential subflooring demand:North American housing starts are absorbing larger sanded plywood volumes for structural sheathing applications where dimensional stability matters.
- CARB compliance spillover:California's Air Resources Board standards extend de facto national benchmarks through supply chain integration, elevating certified product premiums.
- Softwood veneer clustering:Southeastern U.S. timber proximity to processing mills reduces logistics costs and accelerates order fulfillment cycles.
Market Restraints
- Phenol-formaldehyde cost volatility:Petrochemical feedstock price swings compress margin predictability for exterior-grade resin formulations.
- Baltic birch supply concentration:Russian and Baltic raw material access disruptions threaten specialty grade consistency for decorative plywood applications.
- OSB substitution pressure:Oriented strand board alternatives displace structural plywood in wall sheathing through lower per-unit cost positioning.
Strategic Opportunities
- Underpenetrated Canadian markets:Health Canada and PMRA compliance pathways favor low-emitting products, creating first-mover positioning for certified U.S. exporters.
- Bio-based binder convergence:Soy and lignin adhesive technologies intersect with TSCA Title VI thresholds, enabling marketing differentiation without performance trade-offs.
- Direct contractor channel:Bypassing traditional distributor layers through mill-direct procurement platforms captures margin and accelerates specification control.
Industry Challenges
- Veneer drying technician scarcity:Specialized kiln operation expertise is concentrating at legacy facilities, constraining workforce scaling for mid-scale entrants.
- Press equipment capex intensity:Multi-opening hot press installations require substantial capital commitments that asset-light leasing models only partially offset.
- CARB-EPA dual certification timelines:Parallel third-party verification processes extend product launch cycles and complicate inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanded Plywood Market |
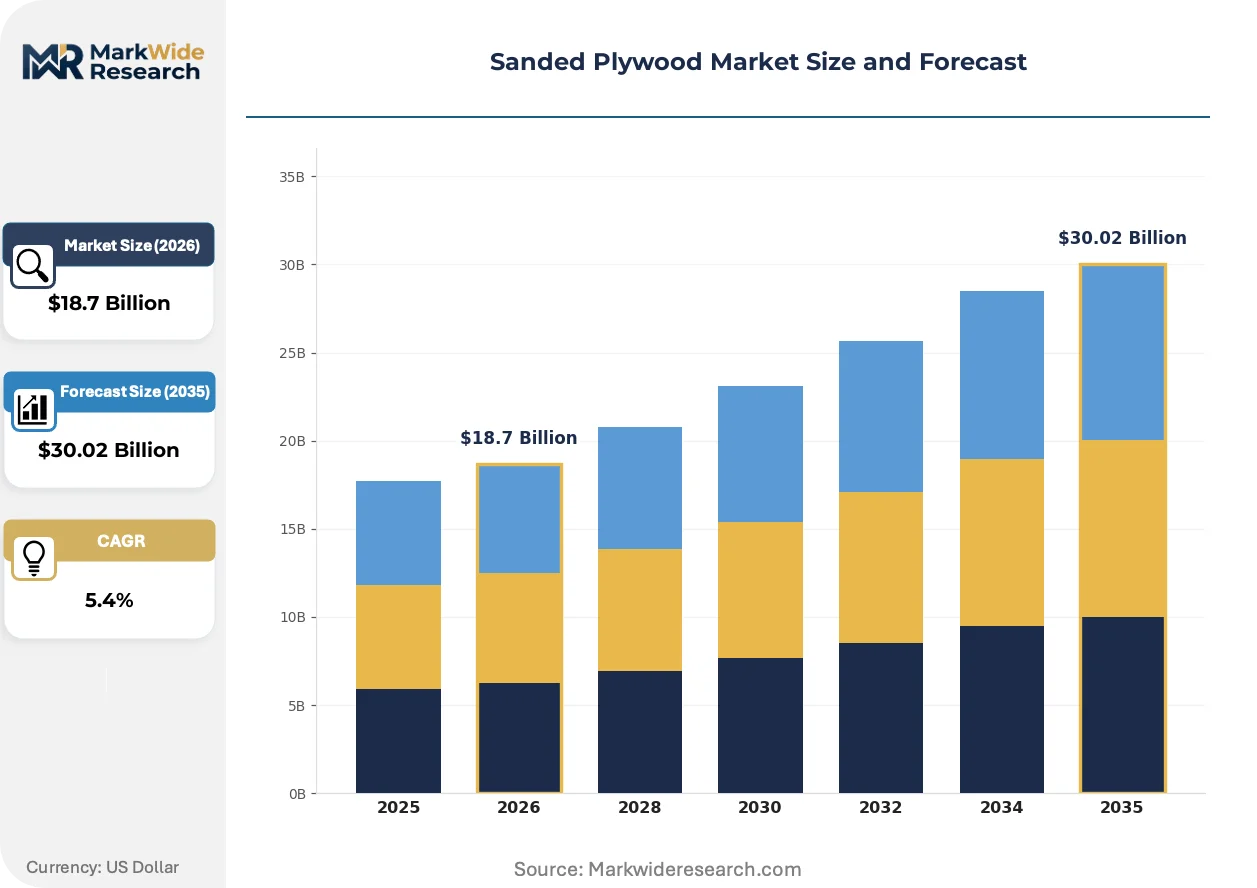
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marine Plywood, Interior Plywood, Exterior Plywood, Structural Plywood Thickness: 1/4 Inch, 1/2 Inch, 3/4 Inch, 1 Inch Application: Furniture, Flooring, Cabinetry, Building Construction Wood Species: Pine, Birch, Oak, Teak |
| Companies Covered | Boise Cascade, Georgia-Pacific, Weyerhaeuser Company, ARAUCO, Coastal Plywood Company, Eagle Plywood Specialties, Roseburg Forest Products, UPM, SVEZA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanded Plywood Market Trends and Innovations
Automated veneer grading systems are compressing quality variability in sanded plywood production. Regulatory convergence around formaldehyde limits is standardizing resin chemistry investments. Buyer procurement patterns are fragmenting across specification-driven and cost-optimized segments.
Machine vision-based veneer defect detection is digitizing quality assurance workflows. Cabinetry manufacturers and furniture OEMs are adopting these systems at accelerating rates to reduce downstream lamination failures. Real-time grading data is digitizing supplier scorecards and compressing acceptance cycle times.
REACH regulation in Europe is extending chemical disclosure requirements through imported wood product supply chains. Manufacturers serving EU markets must document resin composition and emission profiles across extended material safety data obligations. Decorative plywood grades face heightened documentation burdens compared to commodity structural products.
Specification-driven buyers are unbundling after-sales technical support from base product pricing. Large-scale contractors and millwork distributors now procure sanded plywood through separate sourcing channels for certified versus economy grades. This bifurcation is most visible in California and Pacific Northwest markets where green building codes drive premium segmentation.
Sanded Plywood Market Segmentation
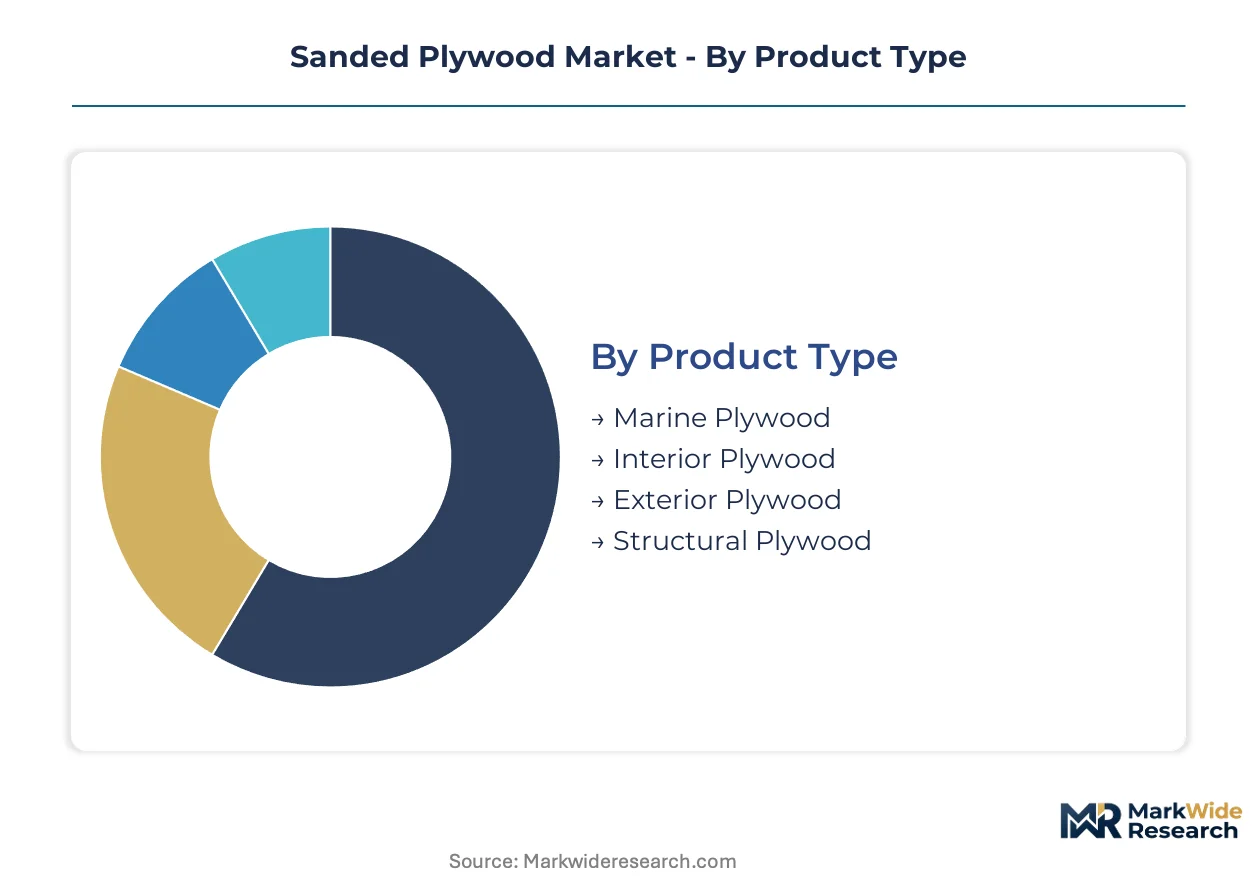
Sanded plywood segmentation reveals distinct performance requirements across moisture exposure, structural load, and finish quality dimensions. Specification buyers prioritize certified grades for visible applications while cost-optimized procurement dominates hidden structural uses.
Product Type:
Mature exterior and structural grades anchor volume flows while specialty marine formulations command technical premiums.
- Structural Plywood:Cross-laminated softwood veneers engineered for load-bearing wall sheathing, subflooring, and roof decking where building code span ratings govern specification. North American residential construction absorbs the majority of volume, with southeastern U.S. mill proximity reducing landed costs for regional builders.
- Interior Plywood:Surface-sanded panels manufactured to precise thickness tolerances for furniture substrates, cabinetry boxes, and architectural millwork where paint adhesion and flatness matter. California's CARB-compliant supply chains capture premium positioning as green building codes tighten across Pacific Coast markets.
- Exterior Plywood:Phenol-formaldehyde bonded panels rated for moisture exposure in siding and soffit applications, facing substitution pressure from engineered wood alternatives in cost-sensitive segments.
- Marine Plywood:Waterproof adhesive systems and void-free core construction for boatbuilding and dock applications, sourced primarily through specialty distributors serving coastal manufacturing clusters.
Structural plywood retains volume leadership; interior plywood holds the steepest expansion curve.
Thickness:
Cost tier stratification separates commodity construction panels from precision-finished specialty grades.
- 3/4 Inch:Dominant specification for cabinetry carcases, furniture case goods, and finished carpentry where screw-holding strength and dimensional stability intersect. Furniture OEMs in the southeastern United States specify this grade most heavily for residential and hospitality production lines.
- 1/2 Inch:Standard thickness for drawer bottoms, cabinet backs, and light-duty shelving where weight reduction offsets structural margins. Flooring underlayment applications in multi-family residential projects drive steady demand.
- 1/4 Inch:Veneer-core panels for decorative surfacing, bent laminations, and craft-scale manufacturing, concentrated in specialty woodworking supply channels.
- 1 Inch:Heavy-duty structural and industrial applications including concrete formwork and load-bearing platforms, procured through contractor-direct channels for commercial construction.
3/4 inch panels dominate revenue contribution; 1/2 inch thickness is expanding most quickly in multi-family flooring applications.
Application:
Customer type fragmentation separates specification-driven finish carpentry from commodity structural procurement.
- Building Construction:Structural sheathing, subflooring, and temporary forming panels procured through lumberyard distribution networks serving regional contractors. Code compliance and span ratings drive specification more than surface quality.
- Cabinetry:Precision-sanded panels for kitchen, bath, and commercial casework where CARB certification and face-grade consistency command price premiums. European-style frameless construction specifications favor thinner, higher-grade panels.
- Furniture:Case goods, seating frames, and display fixtures requiring paint-ready surfaces and edge-screwing integrity, with domestic manufacturers increasingly specifying low-emitting certified grades.
- Flooring:Underlayment and finished hardwood substrates where moisture resistance and dimensional stability prevent telegraphing and seasonal gapping.
Building construction retains volume leadership; cabinetry holds the steepest expansion curve as kitchen remodeling activity accelerates.
Wood Species:
Supply concentration and veneer drying characteristics differentiate regional sourcing strategies.
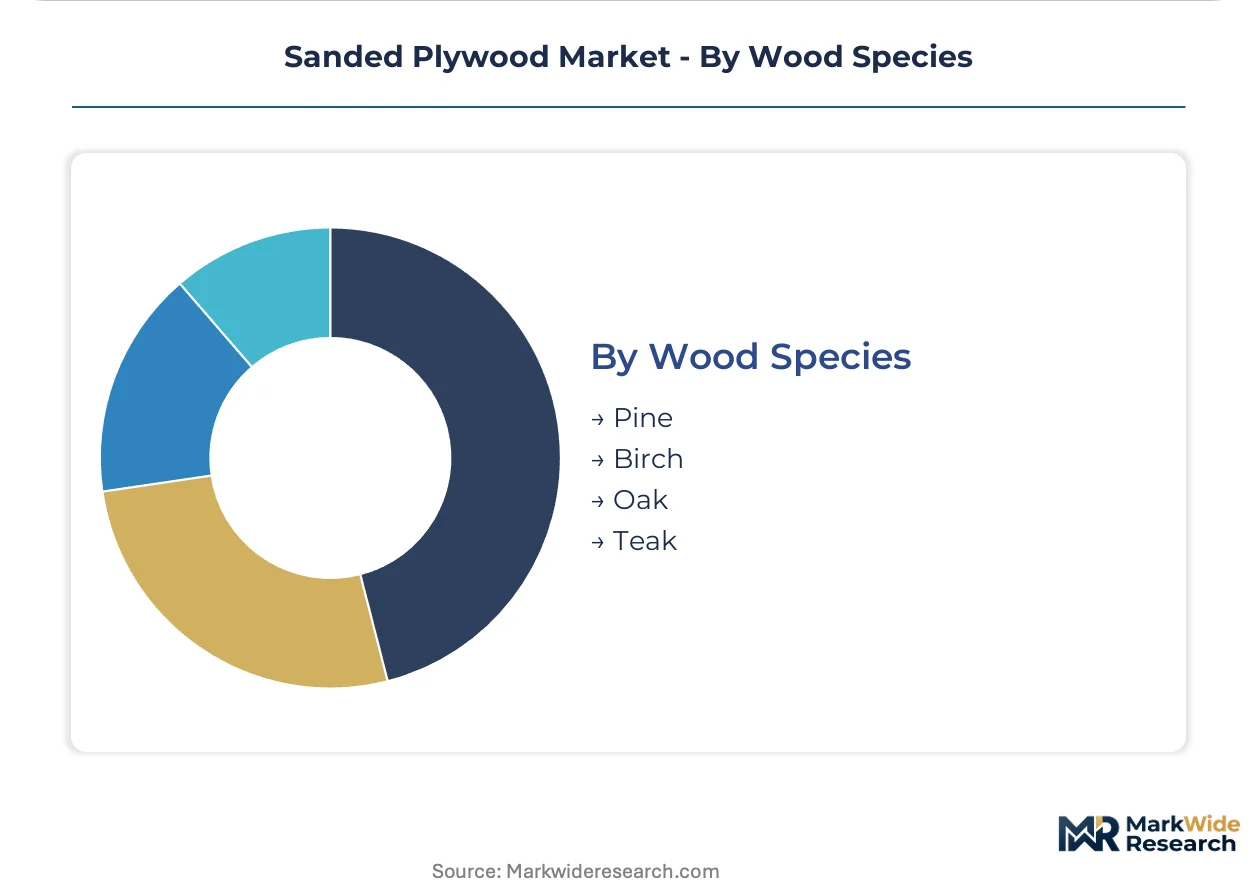
- Pine:Softwood plywood manufactured from southern yellow pine and Douglas fir feedstocks dominates North American structural and construction-grade production. Southeastern U.S. timber proximity to processing mills compresses logistics costs.
- Birch:Decorative hardwood plywood prized for uniform pale color, fine grain, and machinability in furniture and cabinetry applications. Baltic and Russian raw material access disruptions threaten specialty grade consistency.
- Oak:Hardwood veneer plywood for premium architectural millwork and visible furniture components where grain pattern and stain acceptance matter.
- Teak:Marine-grade and exterior decorative applications requiring natural oil content and dimensional stability in moisture-exposed environments.
Pine retains volume leadership; birch holds the steepest expansion curve pending supply chain reconfiguration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA formaldehyde emission standards under TSCA Title VI are reshaping procurement patterns across multiple jurisdictions. Timber access and certification infrastructure now determine competitive positioning in regional sanded plywood supply.
United States
Residential construction in the southeastern states absorbs the majority of structural sanded plywood volume for subflooring and wall sheathing applications. CARB compliance in California extends de facto national standards through supply chain spillover effects. Softwood plywood mills cluster near timber sources in Georgia and Alabama, compressing logistics costs for regional builders.
Canada
Health Canada and PMRA compliance pathways favor low-emitting certified products, creating positioning opportunities for exporters meeting dual EPA-CARB standards. Multi-family residential construction in Toronto and Vancouver drives steady demand for precision-sanded interior grades. British Columbia's timber processing infrastructure supports specialty veneer production for furniture and cabinetry applications.
Germany
REACH regulation extends chemical disclosure requirements through imported wood product supply chains, elevating documentation burdens for decorative plywood grades. The country's furniture manufacturing sector in North Rhine-Westphalia specifies precision thickness tolerances for paint-ready substrates. Bavarian distributors serve as consolidation points for Baltic birch supply reconfiguration efforts.
China
GB standards and MIIT industrial policies govern domestic plywood quality classifications and export certification requirements. Yangtze River Delta furniture OEMs specify low-emitting grades for North American and European export production. Shandong Province processing capacity concentrates on structural grades for domestic construction and regional export markets.
Brazil
Sustainable forestry certification requirements under national environmental regulations shape export market access for tropical hardwood plywood producers. São Paulo state's furniture manufacturing corridor sources specialty grades for domestic and Mercosur regional consumption. Southern pine plantations in Paraná and Santa Catarina supply veneer feedstock for structural plywood production.
Sanded Plywood Market Competitive Landscape
On the supply side, the industry is consolidating around integrated timber holders and specialized veneer processors. Mid-scale entrants face capital intensity barriers for press equipment and drying infrastructure. Three archetypes dominate: captive timber integrateds, specialty grade specialists, and regional scale fabricators. Competitive moves concentrate on backward integration into resin production and mill-direct procurement platform development.
Among North American integrated producers, Georgia-Pacific exemplifies the captive timber archetype through upstream control over fiber supply and adhesive formulation. Weyerhaeuser Company anchors the Douglas fir veneer specialist position. SVEZA occupies a position within the decorative birch plywood tier where raw material access differentiates product consistency.
| Leading Market Players |
|---|
| Boise Cascade |
| Georgia-Pacific |
| Weyerhaeuser Company |
| ARAUCO |
| Coastal Plywood Company |
| Eagle Plywood Specialties |
| Roseburg Forest Products |
| UPM |
| SVEZA |
| Others |
Pricing and Supply Chain Analysis
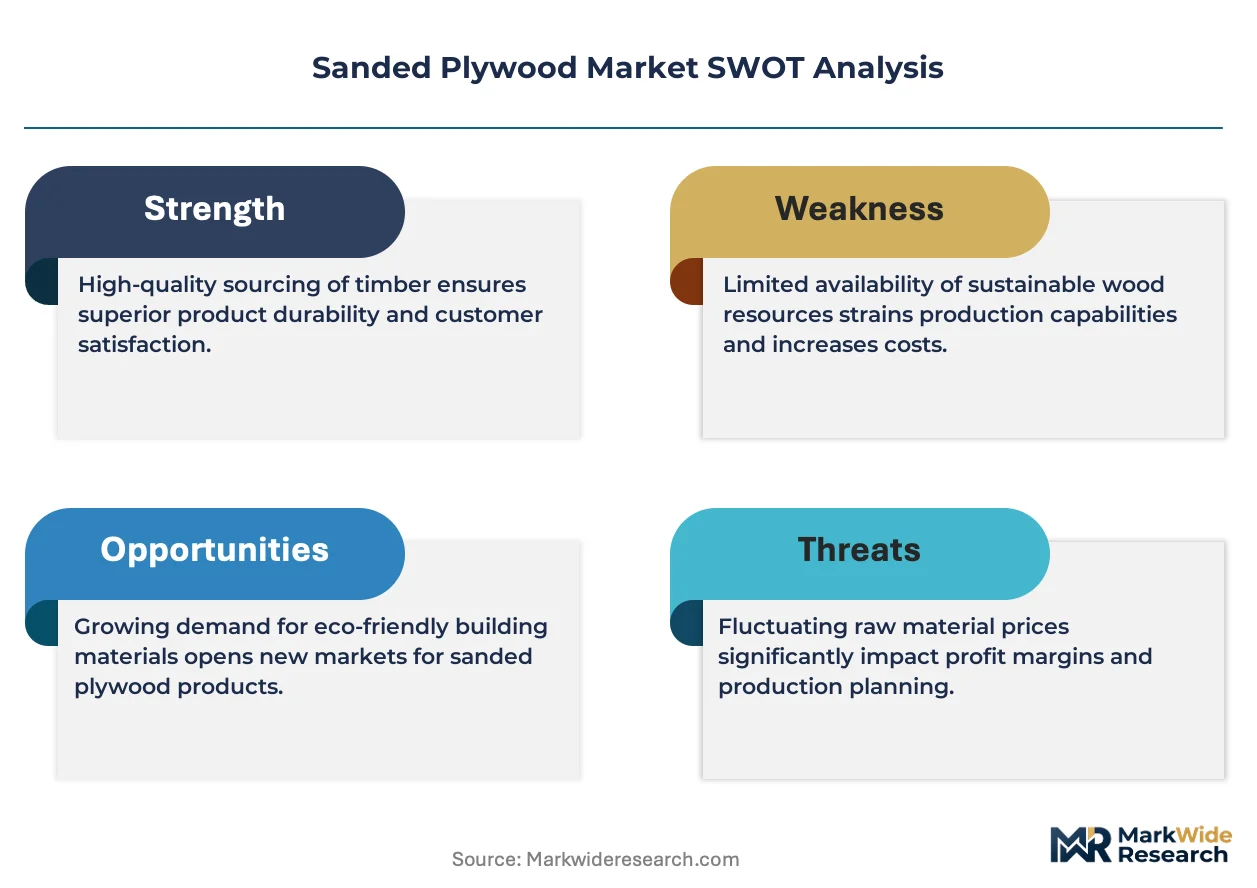
Undercapacity in southeastern U.S. softwood veneer drying capacity is compressing order fulfillment timelines and elevating spot pricing leverage for integrated producers with captive timber holdings. This utilization squeeze simultaneously rewards backward integration into resin production and pressures asset-light entrants toward leasing arrangements that sacrifice margin control.
Pricing Analysis
Certification level creates the primary spread across sanded plywood tiers, with TSCA Title VI and CARB Phase 2 compliance commanding substantial premiums over uncertified commodity grades. Three-tier pricing structure across certified premium, standard industrial, and economy construction levels reflects divergent buyer willingness-to-pay for emission documentation. Cost compression in structural grades is intensifying because OSB substitution erodes plywood's cost-position in wall sheathing applications. Large-scale contractors exhibit highest price sensitivity through mill-direct procurement platforms, while cabinetry OEMs prioritize face-grade consistency over per-unit cost.
Supply Chain Analysis
Timber feedstock availability centers on Georgia, Alabama, and Mississippi where southern yellow pine plantations cluster within haul distance of processing mills. Phenol-formaldehyde resin formulations, Douglas fir veneer from Pacific Northwest sources, and Baltic birch decorative faces constitute critical input dependencies. Single-source vulnerability in Russian and Baltic birch supply threatens specialty grade consistency for furniture and cabinetry applications. Distribution runs through lumberyard networks serving regional contractors, with mill-direct platforms gaining share in specification-driven segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sanded plywood market functions as a regulatory-moat business where TSCA Title VI certification infrastructure creates switching costs that entrench compliant incumbents. This entrenchment mechanism rewards early movers who absorbed compliance capital deployment before standards tightened.
For Market Incumbents: Entrench certification advantage through captive resin production investments that lock in low-emitting formulation capacity ahead of potential bio-based binder transitions. Consolidate southeastern timber positions through long-term stumpage agreements that constrain competitor feedstock access. OSB substitution in structural sheathing represents the primary volume threat requiring differentiation through span-rated performance documentation.
For New Entrants and Emerging Players: Build out asset-light leasing models for veneer dryers and multi-opening presses that narrow capital barriers in underpenetrated Canadian markets where Health Canada compliance pathways favor certified U.S. exporters. Direct contractor procurement platforms offer the most penetrable go-to-market angle, capturing margin through bypassed distributor layers in multi-family residential construction segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-scale sanded plywood fabrication as equipment leasing proliferates, compressing returns for pure-play producers while integrated timber holders sustain margin control. Long-term viability favors acquisition targets with captive timber positions and established TSCA Title VI certification infrastructure. The signal to watch is Baltic birch supply reconfiguration progress, as successful alternative sourcing would unlock specialty grade expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive phenol-formaldehyde capacity insulates margin from petrochemical feedstock volatility. |
| Mill-Direct Procurement Platform Development | Bypassing lumberyard distributors captures margin and accelerates specification control with large contractors. |
| Bio-Based Binder Technology Investment | Soy and lignin adhesive convergence with TSCA Title VI thresholds enables marketing differentiation. |
| Long-Term Timber Stumpage Agreements | Southeastern plantation access locks in feedstock cost position against competing veneer demand. |
| Automated Veneer Grading System Deployment | Machine vision quality assurance reduces downstream lamination failures in furniture OEM supply chains. |
Research Methodology
Cross-validation between primary interviews with plywood mill operations managers, resin formulation chemists, lumberyard procurement directors, and cabinetry OEM supply chain leads anchors the qualitative findings. Secondary validation draws from EPA TSCA Title VI certification databases, CARB-approved third-party certifier records, U.S. Forest Service timber harvest data, and SEC filings of integrated forest products companies. Bottom-up volume estimates from regional mill capacity and top-down construction spending flows were reconciled through iterative triangulation.
Calibration against historical demand elasticities and input cost pass-through patterns shaped the projection framework across the analysis window. Segmentation modeling incorporated product type, thickness specification, application end-use, wood species, and regional regulatory cluster dimensions. CAGRs were derived from trend-line extrapolation of housing starts, remodeling activity indices, and substitution rate assumptions between plywood and OSB in structural applications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by bio-based adhesive specialists or Baltic birch supply reconfigurers would shift outcomes. Cross-checking against U.S. Census Bureau construction spending data and Forest Products Laboratory demand surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Lecterns Market
Furniture
Vietnam Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
UK Sustainable Home Furniture Market
Furniture
Europe School Furniture Market
Furniture
Japan Furniture Market
Furniture
US Multifunctional Furniture Market
Furniture
Plastic Furniture Market
Furniture
Global Organic Furniture Market
Furniture
Bean Bag Chairs Market
Furniture
Indonesia Furniture Market
Furniture
Bounding Table Market
Furniture
Back Mount Frames Market
Furniture
Russia Home Furniture Market
Furniture
Piano Stools Market
Furniture
Asia-Pacific Contract Furniture Market