
 Global Aphrodisiac Powder Market | 2026-2036
Global Aphrodisiac Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aphrodisiac Powder Market Foresight
The capital-intensity divergence between integrated botanical processors and contract blenders is rotating competitive advantage toward upstream cultivation control. Himalaya Wellness Company leverages its Himalayan herb sourcing infrastructure to sustain margin resilience across volatile raw material cycles. NOW Foods anchors North American shelf presence through pharmacy and health food store networks. Dabur India Ltd. differentiates via Ayurvedic heritage positioning in South Asian and diaspora markets.
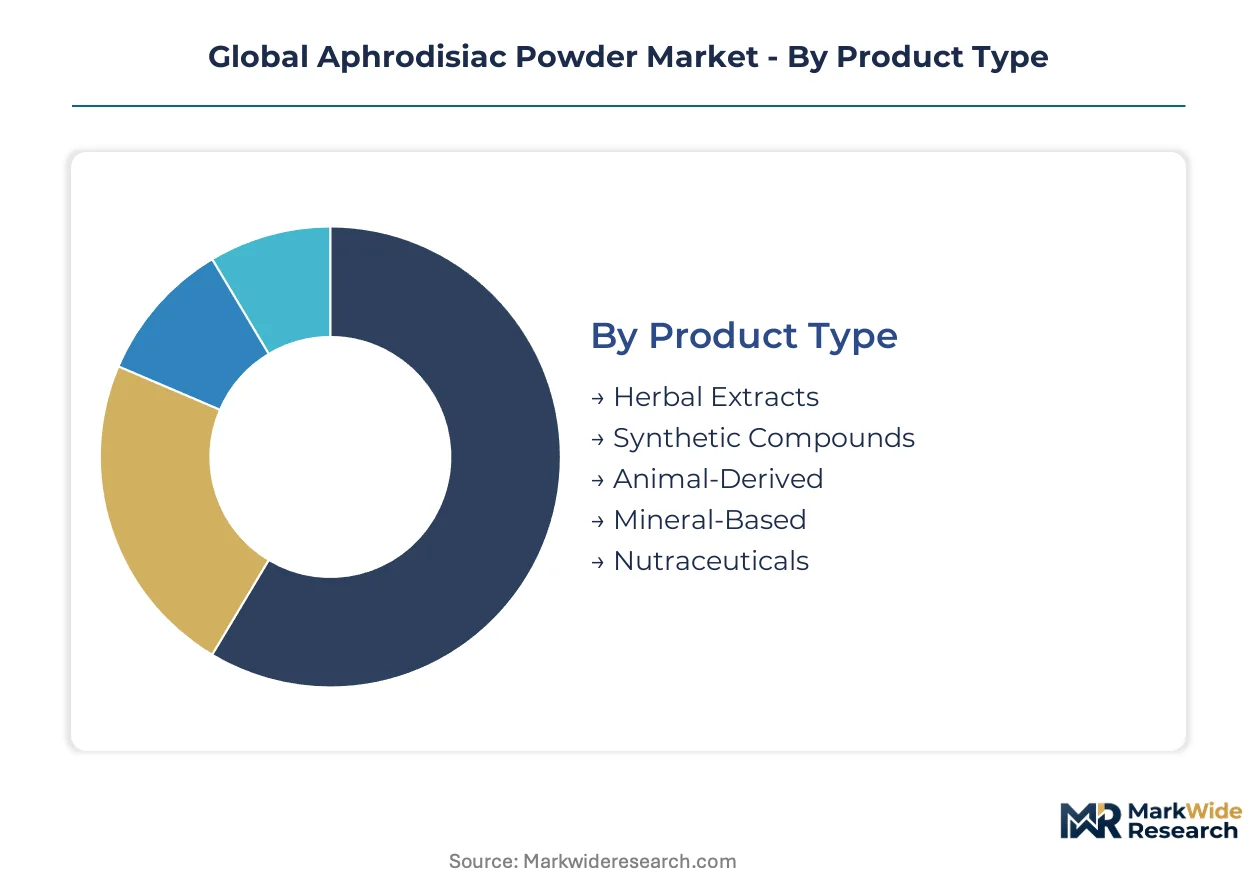
Aphrodisiac powders comprise concentrated botanical, synthetic, mineral, or animal-derived actives formulated for dissolution in beverages or encapsulation, typically standardized to marker compound thresholds such as icariin percentage in Epimedium extracts or yohimbine alkaloid content. These formulations serve pharmaceutical and wellness applications targeting vasodilation, neurotransmitter modulation, or hormonal pathway support. Herbal extracts command the dominant value share due to consumer preference for clean-label provenance and perceived safety profiles. Synthetic compounds represent the fastest-expanding segment as pharmaceutical companies pursue reproducible potency and batch consistency. Nutraceuticals capture concentrated margin pools where brands achieve dual positioning between supplement and functional food classifications.
FDA dietary supplement Current Good Manufacturing Practice requirements, EFSA novel food assessments under EU regulation, and India's FSSAI functional food standards collectively elevate compliance costs while filtering substandard entrants from distribution channels. Regulatory stringency in the European Union and United States is forcing reformulation investments and third-party certification adoption. Stakeholders must monitor evolving pharmacovigilance reporting obligations and adapt supply chain documentation to preempt market access disruptions.
Market Dynamics
Regulatory divergence between FDA dietary supplement enforcement and EFSA novel food assessments is fragmenting formulation strategies, forcing manufacturers to maintain parallel compliance architectures for the same active compounds.
Growth Catalysts
- EFSA Novel Food Pathway:Standardized safety dossier requirements for botanical extracts are accelerating market access for European wellness brands seeking cross-border distribution within the European Union.
- Direct-to-Consumer E-Commerce:Platform-native brands in India, China, and the United States are capturing margin pools previously allocated to pharmacy and health food retail intermediaries.
- Pharmaceutical-Grade Synthesis:Reproducible potency standards for yohimbine and icariin analogues are attracting institutional investment from contract development and manufacturing organizations.
Market Restraints
- Raw Material Volatility:Himalayan Epimedium and Indian Mucuna pruriens harvests face climate-induced yield compression, destabilizing cost structures for integrated botanical processors.
- FDA Import Documentation:Evolving Current Good Manufacturing Practice enforcement is creating customs clearance friction for Asian contract manufacturers without third-party NSF or USP certification.
- Clean-Label Substitution:Whole-herb capsule formats are capturing preference share from powdered extracts among risk-averse consumer segments in Germany and Japan.
Strategic Opportunities
- Brazil's ANVISA Reform Window:Pending simplification of herbal product registration is creating first-mover advantage for brands with pre-positioned toxicology dossiers.
- Functional Food Convergence:Dual positioning between supplement and beverage categories is opening shelf placement in convenience retail channels across South Korea and Thailand.
- India PLI Scheme Extension:Production-linked incentives for active pharmaceutical ingredient manufacturing are subsidizing backward integration into captive herb extraction facilities.
Industry Challenges
- Pharmacovigilance Reporting:Adverse event documentation systems remain underdeveloped at mid-scale contract blenders, exposing brands to regulatory enforcement action.
- Marker Compound Standardization:Batch-to-batch variation in icariin and yohimbine content is forcing costly HPLC verification protocols that compress margins at economy-tier positioning.
- Cross-Border E-Commerce Compliance:Platform-specific labeling requirements in China and the United States are multiplying SKU complexity for direct-to-consumer operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aphrodisiac Powder Market |
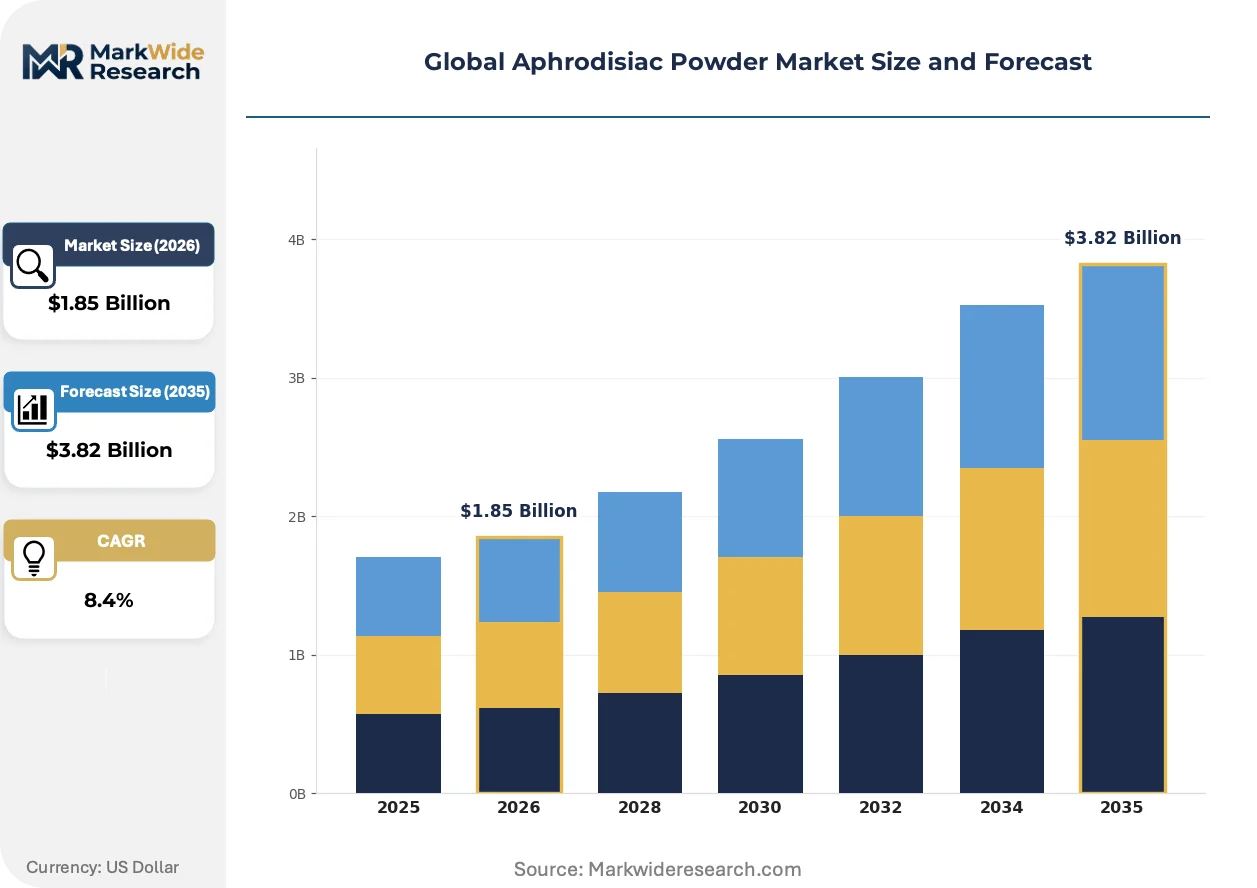
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Synthetic Compounds, Animal-Derived, Mineral-Based, Nutraceuticals Application: Enhancement of Libido, Stress Relief, Hormonal Balance, Energy Boost, Sleep Improvement End User: Pharmaceutical Companies, Wellness Centers, Online Retailers, Specialty Stores, Fitness Clinics Distribution Channel: Direct Sales, Pharmacies, E-Commerce Platforms, Health Food Stores, Beauty & Personal Care Outlets |
| Companies Covered | Cupid Labs Ltd., Biopark Cosmetics, Farfalla Essentials AG, Himalaya Wellness Company, Moon Juice, Green Healthy Living International Co., Ltd., NOW Foods, Dabur India Ltd., Patanjali Ayurved Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aphrodisiac Powder Market Shifts & Advancements
Formulation science and distribution architecture are undergoing parallel transformation as synthetic standardization confronts heritage botanical positioning, with regulatory compliance emerging as the primary competitive differentiator rather than raw efficacy claims.
Supercritical CO2 extraction is supplanting traditional solvent-based methods for Epimedium and Tribulus terrestris processing, preserving thermolabile flavonoid profiles while eliminating residual solvent concerns. European nutraceutical manufacturers are adopting this technology at accelerated capex cycles, compressing the premium positioning window for conventional extract suppliers and enabling clean-label claims that command shelf price premiums in German pharmacy channels.
REACH registration requirements for imported botanical concentrates are forcing reformulation investments among Asian contract manufacturers serving European wellness brands. The industrial consequence is a bifurcation between REACH-compliant integrated processors and non-compliant blenders now restricted to domestic or North American distribution. Small-batch artisanal brands in France and Italy are absorbing compliance costs through direct-to-consumer pricing power, while mass-market operators are consolidating supplier relationships.
Subscription-based replenishment models are displacing single-transaction e-commerce for aphrodisiac powder consumers, locking in twelve-month lifetime value metrics that justify elevated customer acquisition spend. This pattern is most visible in United States direct-to-consumer channels, where platform algorithms favor recurring revenue signals, and in South Korea, where integrated beauty-wellness apps bundle powder formulations with personalized consultation services.
Global Aphrodisiac Powder Market Segmentation
Channel architecture and end-use concentration determine margin capture in the aphrodisiac powder market. Product positioning must align with whether formulations flow through pharmacy networks, direct-to-consumer platforms, or wellness center procurement.
Product Type:
Channel mix varies sharply by product origin, with herbal extracts commanding pharmacy and health food placement while synthetic compounds concentrate in pharmaceutical direct sales.
- Herbal Extracts:Concentrated botanical actives standardized to marker compounds such as icariin or yohimbine alkaloids. Wellness centers across Germany, Japan, and Brazil are expanding procurement of these formulations for clean-label positioning.
- Synthetic Compounds:Laboratory-synthesized analogues delivering reproducible potency and batch consistency. Pharmaceutical-grade synthesis is attracting institutional investment from contract development organizations seeking regulatory predictability.
- Animal-Derived:Processed glandular or tissue extracts requiring specialized cold-chain logistics. Supply concentrates in traditional medicine channels with limited Western pharmacy penetration.
- Mineral-Based:Zinc, selenium, and magnesium formulations targeting micronutrient deficiency correlations. Shelf placement skews toward health food stores and specialty supplement retailers.
- Nutraceuticals:Dual-positioned formulations bridging supplement and functional food classifications. Convenience retail channels across South Korea and Thailand are opening to this hybrid positioning.
Herbal extracts dominate installed base. Synthetic compounds are where expansion concentrates.
Application:
Application segmentation tracks end-use concentration across clinical, wellness, and lifestyle consumer segments with divergent efficacy evidence requirements.
- Enhancement of Libido:Primary indication driving category definition and regulatory scrutiny. Direct-to-consumer e-commerce channels spanning India, China, and the United States capture concentrated demand for discreet access.
- Stress Relief:Adaptogenic positioning leveraging cortisol modulation claims. Wellness centers in Germany and Japan are absorbing premium-priced formulations with clinical consultation bundling.
- Hormonal Balance:Endocrine pathway support targeting testosterone and estrogen optimization. Pharmacy networks require prescription-adjacent documentation for this positioning.
- Energy Boost:Mitochondrial and circulatory enhancement claims. Fitness clinics and specialty stores drive volume for pre-workout and vitality applications.
- Sleep Improvement:Melatonin-potentiation and GABA-ergic mechanisms. E-commerce platforms capture recurring subscription demand for nightly-use formulations.
Libido enhancement anchors category revenue. Stress relief applications are climbing the fastest.
End User:
Customer type determines formulation complexity, with pharmaceutical companies demanding full pharmacokinetic dossiers while wellness centers prioritize experiential efficacy.
- Pharmaceutical Companies:Institutional buyers requiring GMP-compliant manufacturing and complete batch documentation. These entities drive synthetic compound volume through contract manufacturing arrangements.
- Wellness Centers:Service-integrated procurement across Germany, Japan, and Brazil seeking herbal extract formulations with consultation-based dispensing.
- Online Retailers:Platform-native brands capturing margin pools previously allocated to pharmacy intermediaries through algorithm-optimized customer acquisition.
- Specialty Stores:Curated shelf presence in health food and supplement boutiques with educated staff consultation.
- Fitness Clinics:Performance-oriented dispensing with trainer or nutritionist recommendation protocols.
Online retailers are gaining share fastest. Pharmaceutical companies retain pricing power.
Distribution Channel:
Channel selection determines compliance burden, with pharmacy placement requiring FDA or EFSA alignment while e-commerce navigates platform-specific labeling rules.
- Direct Sales:Manufacturer-to-consumer relationships bypassing retail markup. Subscription-based replenishment models are displacing single-transaction purchasing in United States channels.
- Pharmacies:Regulated shelf placement requiring third-party NSF or USP certification. German pharmacy channels absorb supercritical CO2 extracted premiums.
- E-Commerce Platforms:Algorithm-driven discovery with platform-specific labeling requirements multiplying SKU complexity for cross-border operators.
- Health Food Stores:NOW Foods anchors North American presence through established retail networks with educated consumer base.
- Beauty & Personal Care Outlets:South Korean integrated beauty-wellness apps bundle powder formulations with personalized consultation services.
E-commerce platforms are where expansion concentrates. Pharmacies dominate premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with German and Japanese buyers absorbing premium-priced supercritical extracts while Indian and Brazilian consumers drive volume through price-sensitive direct-to-consumer channels.
United States
Direct-to-consumer e-commerce platforms capture concentrated demand for discreet libido enhancement access, with subscription-based replenishment models displacing single-transaction purchasing. FDA's evolving Current Good Manufacturing Practice enforcement is reshaping import documentation requirements for Asian contract manufacturers. Wellness clusters in California and New York anchor platform-native brand headquarters.
Germany
Wellness centers across Bavaria and Baden-Württemberg expand procurement of herbal extract formulations with consultation-based dispensing. EFSA novel food assessments under EU regulation elevate compliance costs while filtering substandard entrants from pharmacy distribution. Supercritical CO2 extracted premiums concentrate in Frankfurt and Munich pharmacy channels.
India
Ayurvedic heritage positioning drives South Asian and diaspora market capture through direct-to-consumer channels. FSSAI functional food standards and PLI scheme extensions for active pharmaceutical ingredient manufacturing subsidize backward integration into captive herb extraction. Maharashtra and Karnataka host concentrated herb processing infrastructure.
Brazil
ANVISA's pending simplification of herbal product registration creates first-mover advantage for brands with pre-positioned toxicology dossiers. Wellness centers in São Paulo and Rio de Janeiro drive clean-label herbal extract procurement. Climate-induced yield compression in domestic supply chains elevates import dependence for standardized actives.
China
Platform-native brands leverage algorithm-optimized customer acquisition for aphrodisiac powder distribution through domestic e-commerce channels. NMPA and SAMR oversight of dietary supplement labeling creates cross-border compliance friction for international operators. Yangtze River Delta clusters concentrate extraction and formulation capacity.
Global Aphrodisiac Powder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated botanical processors commanding premium positioning through upstream cultivation control while contract blenders compete on volume scale. The vendor base stratifies across three tiers: heritage Ayurvedic houses with captive herb sourcing, North American nutraceutical distributors with pharmacy network anchoring, and Asian contract manufacturers with synthetic standardization capabilities. Dominant competitive moves include backward integration into captive extraction facilities and geographic expansion through platform-native e-commerce positioning.
Within the heritage wellness tier, Himalaya Wellness Company and Dabur India Ltd. exemplify upstream control strategies through Himalayan and Indian subcontinent herb sourcing infrastructure. NOW Foods anchors North American shelf presence through established pharmacy and health food store networks. Among platform-native specialists, Moon Juice occupies a position bridging supplement and functional food classifications for direct-to-consumer channels.
| Leading Market Players |
|---|
| Cupid Labs Ltd. |
| Biopark Cosmetics |
| Farfalla Essentials AG |
| Himalaya Wellness Company |
| Moon Juice |
| Green Healthy Living International Co., Ltd. |
| NOW Foods |
| Dabur India Ltd. |
| Patanjali Ayurved Limited |
| Others |
Supply & Pricing Matrix
REACH registration requirements for imported botanical concentrates gate both European market access and premium pricing tiers simultaneously, forcing Asian contract manufacturers into costly compliance investments that bifurcate the supplier base between certified premium processors and price-competitive non-compliant blenders restricted to domestic channels.
Pricing Analysis
Subscription-based replenishment contracts now drive lifetime value capture across direct-to-consumer channels, displacing single-transaction purchasing. Three-tier pricing structure across premium, standard, and economy levels separates supercritical CO2 extracted formulations from solvent-based extracts and unstandardized whole-herb powders. Cost compression in the economy tier is intensifying because contract blenders absorb HPLC verification expenses without passing through to price-sensitive buyers in India and Brazil. Wellness centers in Germany and Japan exhibit lowest price sensitivity, while platform-native consumers in South Asia drive volume through promotional discounting.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Himalayan Epimedium and Indian Mucuna pruriens shipments, compressing margins at integrated processors without captive cultivation. Supply concentrates in India, China, and Nepal for raw botanical inputs, with extraction capacity clustering in Maharashtra, Karnataka, and the Yangtze River Delta. Batch-to-batch variation in icariin and yohimbine marker compounds creates single-source vulnerability for brands dependent on specific harvest regions. Distribution runs through pharmacy networks in Germany, direct-to-consumer platforms in the United States, and wellness center procurement in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among platform-native direct-to-consumer brands and integrated wellness center chains, fragmenting the customer base away from traditional pharmacy intermediaries and forcing suppliers into volume-commitment negotiations.
For Market Incumbents: Compound defensive positioning through backward integration into captive herb extraction facilities in Maharashtra and Karnataka, securing supply continuity against climate-induced Himalayan yield compression. Invest in third-party NSF or USP certification to preempt FDA import documentation friction for Asian manufacturing. Prioritize subscription infrastructure development to lock in twelve-month lifetime value metrics against emerging platform-native competitors.
For New Entrants and Emerging Players: Subscription-based replenishment service gaps in Brazilian and Southeast Asian markets present white-space entry points where incumbents under-serve through pharmacy-centric distribution. Target Brazil's ANVISA reform window with pre-positioned toxicology dossiers for first-mover herbal product registration. Enter through direct-to-consumer platform positioning bundled with personalized consultation services, bypassing established retail intermediaries entirely.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure, favoring scaled processors over asset-light contract blenders. Long-term viability over the medium-term horizon rests on upstream cultivation control and regulatory compliance architecture rather than formulation differentiation alone. Target acquisition archetypes include integrated botanical processors with REACH-compliant European distribution and Himalayan or Indian subcontinent herb sourcing infrastructure. Monitor EFSA novel food assessment timelines as inflection indicators for cross-border market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Extraction | Maharashtra and Karnataka facilities reduce raw material volatility exposure for integrated processors. |
| Third-Party Certification Investment | NSF or USP certification preempts FDA import documentation friction for Asian contract manufacturers. |
| Subscription Infrastructure Development | Twelve-month lifetime value metrics justify elevated customer acquisition spend on platform algorithms. |
| ANVISA Pre-Positioning | Pre-submitted toxicology dossiers capture first-mover advantage in Brazil's pending regulatory simplification. |
| Supercritical CO2 Extraction Adoption | European manufacturers preserve thermolabile flavonoid profiles while eliminating residual solvent concerns. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings in documented compliance patterns. Conversations with herbal extraction facility managers, wellness center procurement directors, platform-native brand operators, and contract manufacturing executives informed supply chain and pricing dynamics. Secondary sources include FDA dietary supplement warning letters, EFSA novel food assessment decisions, FSSAI functional food notifications, and ANVISA herbal product registration databases. Bottom-up volume triangulation against top-down value estimates validates segmentation splits.
Sensitivity analysis around regulatory enforcement intensity and raw material yield variation stress-tests the analytical framework. Segmentation dimensions modeled include product type, application indication, end-user archetype, and distribution channel across the projection horizon. CAGRs derive from trend extrapolation adjusted for policy inflection points and technology adoption curves. Forecast inputs incorporate climate-induced harvest compression scenarios and e-commerce platform algorithm evolution.
Forecasts assume regulatory continuity in FDA dietary supplement enforcement, EFSA novel food assessments, and India's FSSAI functional food standards; material policy shifts would require re-modeling. Specific risk factors include pharmacovigilance reporting obligation expansion, REACH registration requirement tightening, and platform-specific labeling rule proliferation in China and the United States. Recalibration cycles align with material shifts in enforcement posture, regulatory simplification windows, and extraction technology capex cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Lemongrass Oil Market
Extracts
Labdanum Market
Extracts
Global Herbal Extract Market
Extracts
Wild Yam Powder Market
Extracts
Patchouli Oil Market
Extracts
Clary Sage Oil Market
Extracts
Myrrh Powder Market
Extracts
Bee Venom Extract Market
Extracts
Lavender Oil Market
Extracts
Pullulan Market
Extracts
Basil Extracts Market
Extracts
Herb and Spice Extracts Market
Extracts
Ovalbumin Powder Market
Extracts
Helichrysum Oil Market
Extracts
Passion Flower Extracts Market
Extracts
Nootkatone Market