
 Helichrysum Oil Market | 2026-2036
Helichrysum Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Helichrysum Oil Market Analysis
Organic and therapeutic-grade certification is bifurcating the helichrysum oil market into premium and commodity tiers. doTERRA International LLC leverages its Co-Impact Sourcing program to secure traceable supply from Corsica and Slovenia. Young Living Essential Oils sustains vertical integration through its Seed to Seal farms in Croatia and Utah. Ultra International B.V. anchors European bulk supply through long-term distiller partnerships in the Balkans.
Helichrysum oil is a steam-distilled or solvent-extracted volatile oil derived from Helichrysum italicum flowers, containing high concentrations of neryl acetate and gamma-curcumene that confer anti-inflammatory and tissue-regenerative properties for topical and inhalation applications. Essential oil commands the largest volume share due to its versatility across aromatherapy and cosmetic formulations, while absolute extracts capture concentrated margin pools in luxury perfumery. Skincare applications lead absolute consumption as clean beauty brands prioritize single-origin botanical actives, and online retail channels extend fastest as direct-to-consumer wellness brands bypass traditional distribution.
ECOCERT and USDA Organic standards govern cultivation and extraction claims, while REACH registration in the European Union mandates full toxicological disclosure for absolutes using hexane or ethanol solvents. FDA cosmetic labeling rules in the United States restrict disease claims even as the agency permits GRAS status for certain aromatherapy applications. Stakeholders must monitor evolving pesticide residue thresholds under EU Regulation 396/2005 and the emerging patchwork of state-level cosmetic safety laws in California and New York.
Market Dynamics
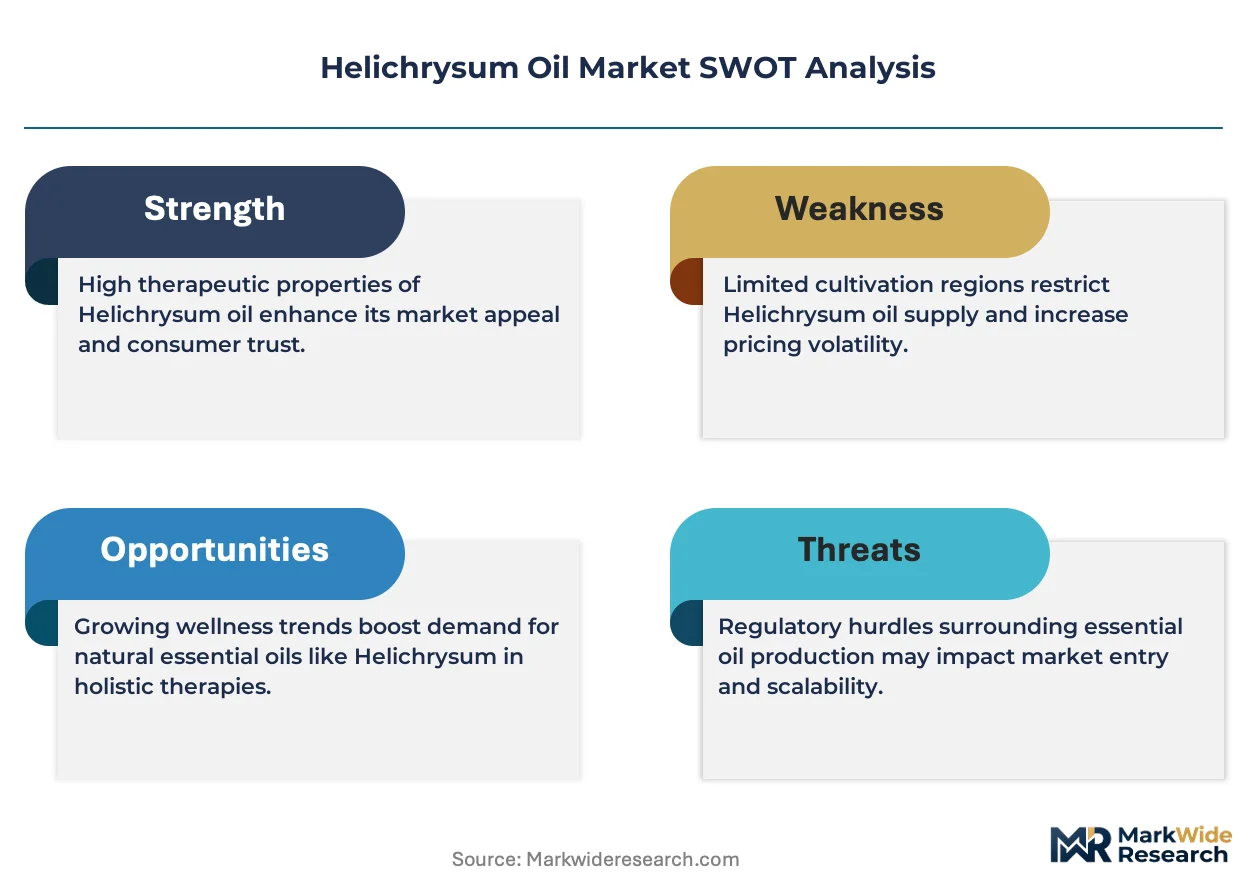
REACH compliance in the European Union is compressing residual solvent limits for helichrysum absolutes, forcing distillation infrastructure upgrades across Corsican and Balkan supply clusters while organic certification premiums widen the gap between commodity and therapeutic-grade supply tiers.
Growth Catalysts
- Clean beauty actives demand:Premium cosmetic formulators in France and Italy now mandate organic-certified helichrysum oil for anti-aging serums, pulling volume through ECOCERT-validated channels.
- Aromatherapy channel expansion:Direct-to-consumer wellness brands bypass traditional distribution through online retail, accelerating volume capture in inhalation and topical applications.
- Western Cape cultivation investment:Emerging cultivation projects in South Africa's Western Cape supplement wild harvesting, stabilizing raw material flow to global distillers.
Market Restraints
- Wild harvest concentration risk:Supply concentrates in South Africa's Western Cape and Corsican hills, exposing volume to climate volatility and land-use restrictions.
- Solvent extraction cost pressure:Hexane and ethanol solvent costs for absolute production compress margins as REACH mandates tighter residual limits and full toxicological disclosure.
- Synthetic terpene substitution:Laboratory-synthesized neryl acetate and gamma-curcumene isolates threaten natural oil demand in cost-sensitive fragrance applications.
Strategic Opportunities
- US state-level cosmetic safety laws:California and New York are enacting stricter ingredient disclosure rules, creating first-mover advantage for brands with pre-validated organic supply chains.
- GRAS aromatherapy positioning:FDA-permitted GRAS status for specific inhalation applications opens institutional wellness contracts in hospitality and corporate settings.
- Cultivation-to-distillation integration:Controlled-environment agriculture converges with small-batch steam distillation, enabling year-round production outside traditional harvest windows.
Industry Challenges
- Organic certification timeline compression:USDA Organic and ECOCERT validation cycles extend 18-36 months, delaying market entry for new cultivation projects.
- Skilled distiller scarcity:Traditional steam distillation expertise for helichrysum italicum concentrates in aging practitioner networks across Corsica and the Balkans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helichrysum Oil Market |
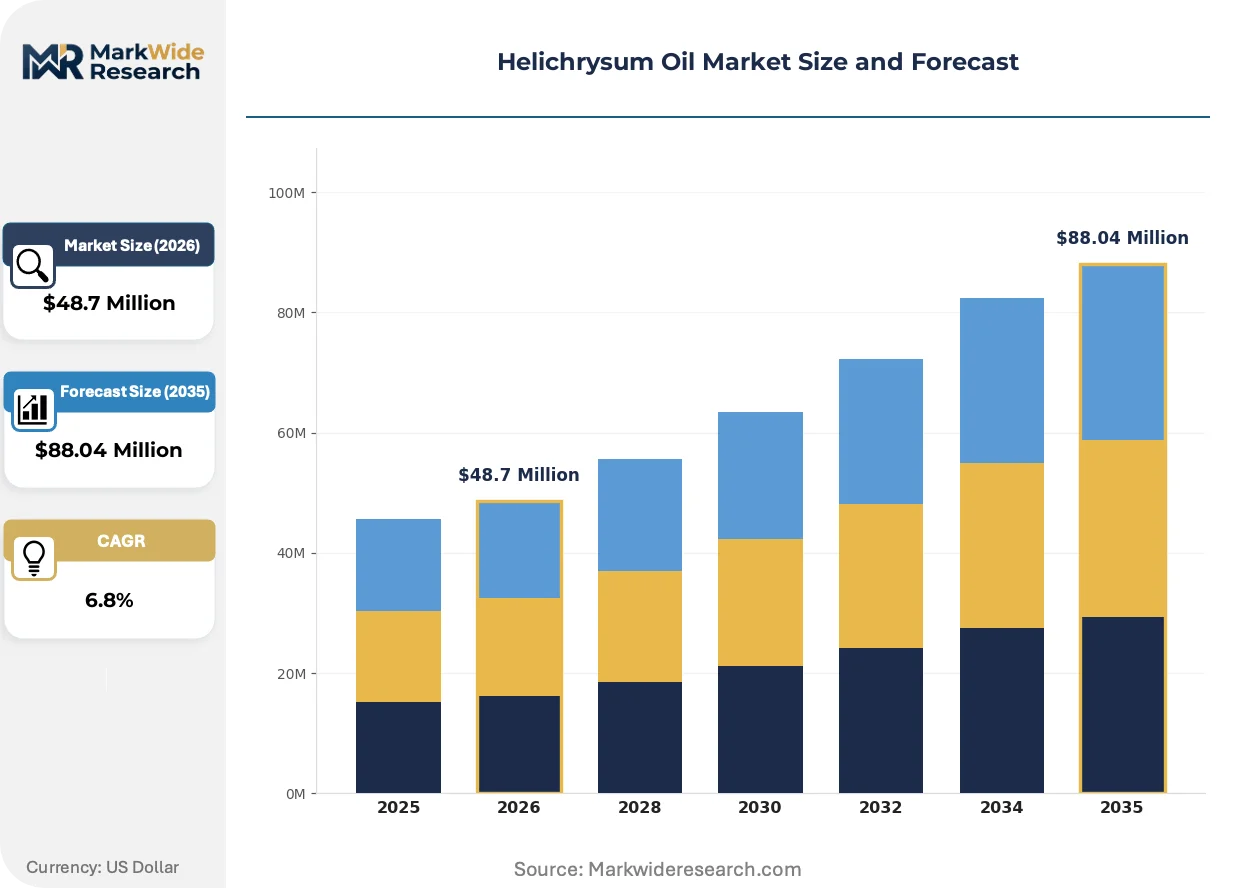
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Absolute, Hydrosol, Blends Application: Aromatherapy, Skincare, Pharmaceuticals, Household Products Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales End User: Consumers, Manufacturers, Distributors, Wellness Centers |
| Companies Covered | doTERRA International LLC, Young Living Essential Oils, Ultra International B.V., Mountain Rose Herbs, AOS Products Private Limited, Allin Exporters, Plant Therapy Essential Oils, Rocky Mountain Oils, Immortelle Therapy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helichrysum Oil Market Emerging Trajectories
Extraction technology and certification standards are reshaping how helichrysum oil moves from harvest to formulation, with implications for cost structure, supply security, and end-use access across cosmetic and therapeutic channels.
Supercritical CO2 extraction is miniaturizing from industrial-scale systems to pilot-plant configurations suitable for estate-level producers. Small distillers in Croatia and Slovenia are adopting modular units to bypass solvent-based absolute production entirely. This technology is miniaturizing capital barriers, enabling single-origin traceability claims that command premium positioning in clean beauty formulations.
EU Regulation 396/2005 is tightening pesticide residue thresholds for botanical ingredients entering cosmetic supply chains. The European Commission's 2024 guidance on cumulative exposure assessment forces reformulators to validate cultivation practices back to seed stock. Organic-certified producers in Italy and France gain competitive insulation as conventional suppliers face testing cost inflation.
Ingredient sourcing teams at mid-size cosmetic brands now require blockchain-traceable documentation from cultivation through distillation. This audit-depth expectation displaces spot-market purchasing, favoring multi-year offtake agreements with verified single-origin suppliers. The shift is most visible in French prestige skincare, where formulators publish supplier coordinates on product packaging.
Helichrysum Oil Market Segmentation
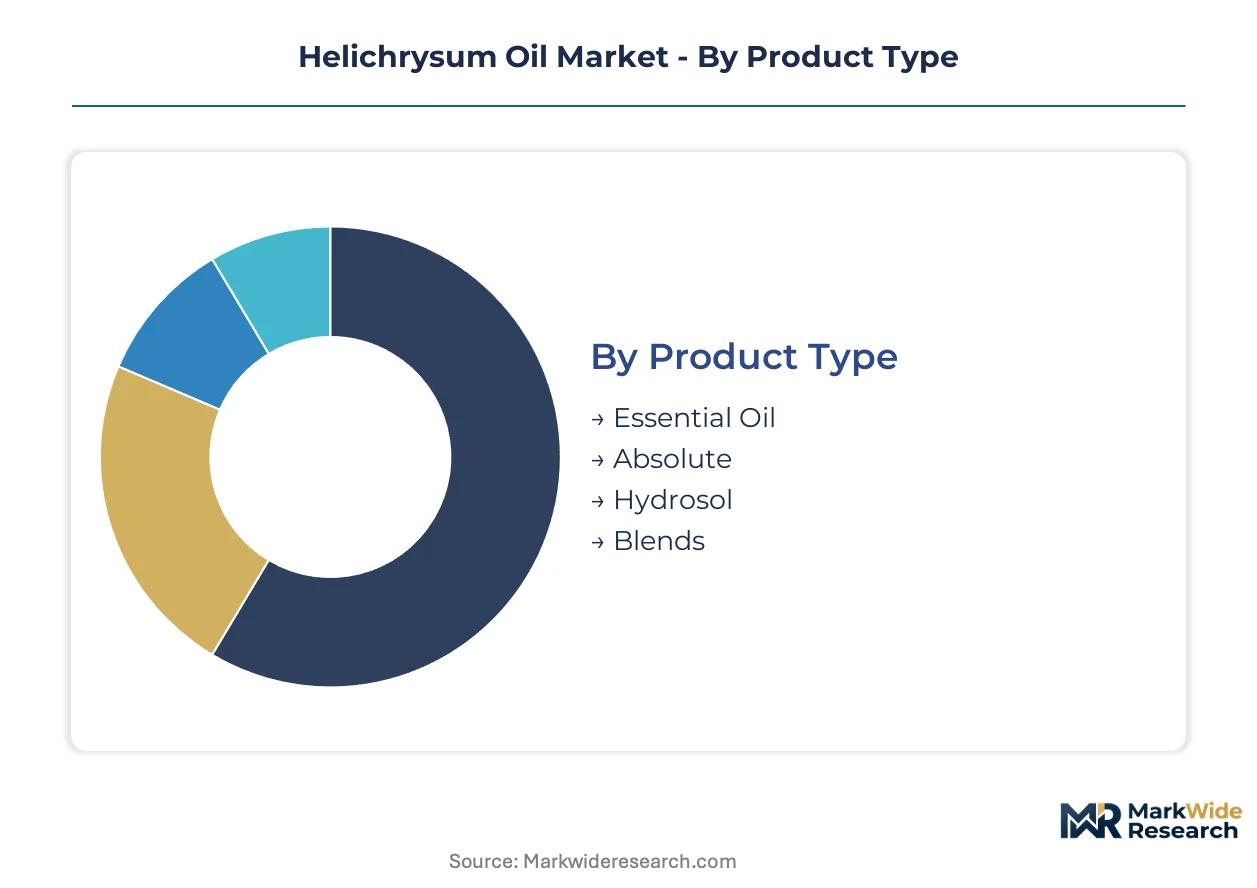
Helichrysum oil segmentation reflects divergent extraction methods, certification tiers, and channel economics that reshape procurement strategies across cosmetic and therapeutic end-uses. Regulatory frameworks in the European Union and United States enforce distinct compliance burdens by product form, compressing margins for solvent-based absolutes while rewarding steam-distilled essential oils with organic validation.
Product Type:
REACH mandates on residual solvents and USDA Organic certification timelines create divergent cost structures across extraction methods.
- Essential Oil:Steam-distilled volatile oil containing neryl acetate and gamma-curcumene at therapeutic concentrations. Demand concentrates in French and Italian anti-aging serum formulations where ECOCERT validation commands premium positioning against conventional supply.
- Absolute:Solvent-extracted concentrate using hexane or ethanol for luxury perfumery applications. REACH compliance tightens residual limits, forcing distillation infrastructure upgrades across Corsican and Balkan supply clusters while compressing margins.
- Hydrosol:Aqueous co-product of steam distillation with diluted active compounds for gentle skincare toners.
- Blends:Pre-formulated combinations with carrier oils targeting direct-to-consumer wellness markets.
Established volume favors Essential Oil; emerging adoption favors Absolute.
Application:
End-use economics range from high-margin single-origin cosmetic actives to commoditized fragrance inputs threatened by synthetic substitution.
- Aromatherapy:Inhalation and topical applications leveraging GRAS status for institutional wellness contracts in hospitality settings. Direct-to-consumer brands bypass traditional distribution through online retail, accelerating volume capture.
- Skincare:Clean beauty brands prioritize single-origin botanical actives for anti-aging serums. French prestige formulators now publish supplier coordinates on packaging, displacing spot-market purchasing with multi-year offtake agreements.
- Pharmaceuticals:Tissue-regenerative properties under investigation for wound healing formulations.
- Household Products:Fragrance applications facing cost pressure from laboratory-synthesized neryl acetate isolates.
Skincare generates the steepest expansion trajectory; Household Products face substitution headwinds.
Distribution Channel:
Channel selection determines traceability depth and margin capture, with blockchain documentation requirements reshaping procurement patterns.
- Online Retail:Direct-to-consumer wellness brands accelerate volume capture through bypassed intermediaries. Blockchain-traceable documentation from cultivation through distillation is now mandatory for mid-size cosmetic brand sourcing teams.
- Specialty Stores:Curated aromatherapy retailers emphasizing organic certification and single-origin provenance for educated consumers.
- Pharmacies:Therapeutic-grade oils with GRAS positioning for clinical and institutional buyers.
- Direct Sales:Network marketing channels leveraging cultivation-to-distillation integration claims.
Online Retail is gaining share fastest; Specialty Stores retain premium positioning.
End User:
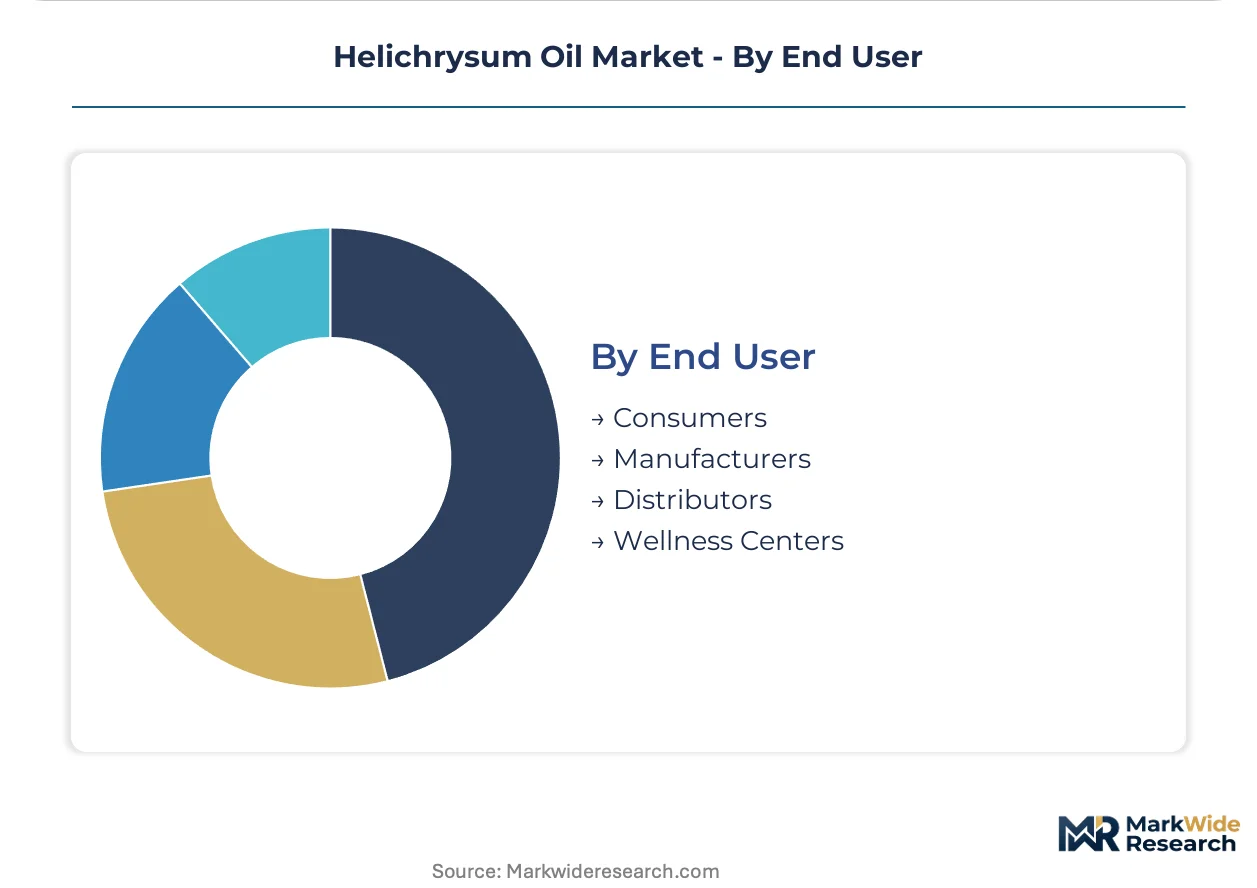
User type dictates volume scale, certification stringency, and supply chain integration depth.
- Consumers:Individual purchasers prioritizing organic certification and traceability claims for personal aromatherapy and skincare use.
- Manufacturers:Cosmetic formulators in France and Italy mandating ECOCERT-validated supply for clean beauty actives, with multi-year offtake agreements displacing spot-market purchasing.
- Distributors:Bulk handlers anchoring European supply through long-term distiller partnerships in the Balkans.
- Wellness Centers:Institutional buyers in hospitality and corporate settings leveraging FDA-permitted GRAS status for specific inhalation applications.
Manufacturers anchor volume concentration; Wellness Centers represent emerging contract opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows for helichrysum oil tilt toward European distillation clusters importing raw biomass from Mediterranean and African cultivation zones, with finished oil shipments radiating toward North American and Asian cosmetic formulators.
France
Corsican distillers supply ECOCERT-validated essential oil to Parisian prestige skincare houses. ANSM cosmetic safety guidance enforces stringent traceability documentation. The island's aging practitioner networks concentrate traditional steam distillation expertise in micro-scale facilities.
Italy
Tuscan and Sicilian formulators specify organic-certified absolutes for luxury anti-aging serums. REACH mandates through ECHA tighten residual solvent thresholds for hexane-extracted concentrates. Florence-based clean beauty brands publish supplier coordinates on product packaging.
South Africa
Western Cape wild harvesters and emerging cultivators feed global aromatherapy demand through Cape Town export channels. The country's national agricultural regulator monitors pesticide residue thresholds under EU-aligned protocols. Clanwilliam and Citrusdal sub-regions anchor distillation infrastructure serving European bulk buyers.
Croatia
Dalmatian coastal farms supply Seed to Seal-integrated channels with traceable organic biomass. ECOCERT validation cycles govern market access for new cultivation projects. Split and Zadar clusters host small-batch steam distillation operations targeting premium cosmetic offtake.
United States
Utah-based cultivation projects supplement Mediterranean supply for domestic wellness brands. FDA cosmetic labeling rules restrict disease claims while permitting GRAS positioning for specific inhalation applications. California and New York state-level disclosure laws create compliance differentiation for pre-validated organic supply chains.
Helichrysum Oil Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and geographic sourcing control, producing a bifurcated structure where scale-driven distributors anchor volume against estate-level producers commanding traceability premiums. Three archetypes dominate: multi-level marketing networks with captive cultivation programs, European bulk distributors with Balkan distiller partnerships, and specialty retailers curating single-origin portfolios. Consolidation pressure favors backward integration into controlled-environment agriculture, while blockchain documentation investments separate premium-tier suppliers from commodity handlers.
Within the network-marketing tier, doTERRA International LLC and Young Living Essential Oils exemplify vertical control strategies through Corsican, Slovenian, Croatian, and Utah cultivation assets. Ultra International B.V. anchors the European bulk distribution archetype through long-term distiller partnerships. Mountain Rose Herbs and Plant Therapy Essential Oils occupy positions in the specialty retail channel emphasizing organic certification and transparent sourcing documentation.
| Leading Market Players |
|---|
| doTERRA International LLC |
| Young Living Essential Oils |
| Ultra International B.V. |
| Mountain Rose Herbs |
| AOS Products Private Limited |
| Allin Exporters |
| Plant Therapy Essential Oils |
| Rocky Mountain Oils |
| Immortelle Therapy |
| Others |
Supply Flow & Price Mechanics
REACH registration through ECHA gates both supply qualification and price differentiation in helichrysum oil, compressing margins for solvent-based absolutes while amplifying premiums for ECOCERT-validated essential oils across French and Italian cosmetic formulators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the market. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified therapeutic grades from conventional steam-distilled volumes and solvent-extracted commodity absolutes. Cost compression in absolute production is intensifying because REACH mandates tighter residual solvent limits and full toxicological disclosure. Small-batch estate producers exhibit least price sensitivity due to traceability premiums, while fragrance compounders face greatest pressure from synthetic neryl acetate substitution.
Supply Chain Analysis
Cape Town port congestion and container availability constraints on the South Africa-Europe trade lane periodically disrupt Western Cape biomass exports to Corsican and Balkan distillers. Supply concentrates in South Africa, France, and Croatia, with raw material flows drawing from wild-harvested Helichrysum italicum, organic-certified cultivation plots, and hexane solvent stocks. Single-source vulnerability runs through aging practitioner networks in Corsica where traditional steam distillation expertise concentrates. Distribution runs through blockchain-traceable multi-year offtake agreements displacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helichrysum oil functions as a service-attach opportunity where certified organic supply chain validation and distillation-as-a-service layers expand faster than commodity oil volumes.
For Market Incumbents: Fortify backward integration into controlled-environment agriculture in Croatia and Slovenia to offset wild harvest concentration risk in South Africa. Deepen ECOCERT validation investments to widen the premium gap against REACH-compressed absolutes. Secure multi-year offtake agreements with French prestige skincare houses before California and New York disclosure laws harden compliance differentiation. For New Entrants and Emerging Players: USDA Organic fast-track programs in Utah and emerging Western Cape cultivation projects offer the most penetrable entry points. Target direct-to-consumer wellness brands bypassing traditional distribution through online retail channels. Lead with single-origin traceability claims and blockchain documentation to command premium positioning against established bulk distributors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across supercritical CO2 extraction equipment as modular pilot-plant configurations miniaturize capital barriers for estate-level producers. Five-to-ten year viability favors acquisition targets with captive cultivation assets and pre-validated organic supply chains. Monitor EU Regulation 396/2005 pesticide residue threshold enforcement as the inflection signal separating compliant from stranded supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive supply of organic-certified biomass insulates against Western Cape climate volatility and land-use restrictions. |
| Supercritical CO2 Extraction Adoption | Modular pilot-plant configurations enable single-origin traceability claims commanding premium positioning in clean beauty. |
| Blockchain Traceability Implementation | Audit-depth documentation from seed stock through distillation displaces spot-market purchasing with multi-year offtake agreements. |
| ECOCERT Validation Investment | Organic certification cycles of 18-36 months create competitive moats against conventional suppliers facing testing cost inflation. |
| Direct-to-Consumer Channel Launch | Online retail bypass accelerates volume capture in aromatherapy applications while capturing margin lost to intermediaries. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, ECHA REACH registration filings, ECOCERT certification databases, and SEC disclosures from publicly listed cosmetic companies. Primary interviews engaged distillation facility operators in Corsica and the Balkans, procurement leads at French and Italian prestige skincare houses, organic certification auditors, and distribution channel partners. Bottom-up volume triangulation across cultivation acreage, distillation capacity, and offtake agreements was cross-validated against top-down demand aggregation from cosmetic formulator consumption patterns.
Segmentation dimensions modeled include extraction method, certification tier, application end-use, and distribution channel across the projection horizon. CAGRs were derived from growth rate convergence analysis applied to historical volume trajectories and forward-looking procurement commitments. Forecast inputs incorporated EU Regulation 396/2005 enforcement timelines, REACH residual solvent limit compression schedules, and state-level cosmetic disclosure law adoption patterns in California and New York.
Underlying assumptions cover sustained organic certification premium retention, stable Western Cape biomass flows, and REACH compliance cost pass-through, with deviation risk concentrated in synthetic terpene substitution acceleration and climate-induced wild harvest disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Nicotinic Acid Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Organic Herbal Extracts Market
Extracts
Global Rose Oils Market
Extracts
Palmarosa Oil Market
Extracts
Botanicals Market
Extracts
Floral Extract Market
Extracts
Patchouli Oil Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Solid Phase Extraction Market
Extracts
Bee Venom Extract Market
Extracts
Histidine Market
Extracts
Frankincense Oil Market
Extracts
Extracts and Distillates Market
Extracts
Phytochemicals Market
Extracts
Potassium Hydrogen Tartrate Market