
 Polygonum Cuspidatum Extract Market | 2026-2036
Polygonum Cuspidatum Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Polygonum Cuspidatum Extract Market Analytics
The gap between pharmaceutical-grade resveratrol specifications and commodity botanical powder is restructuring procurement hierarchies across the Polygonum Cuspidatum extract value chain. Shaanxi Jintai Biological anchors large-scale standardized extract output from China's Shaanxi province, leveraging captive raw material zones. Xi'an Tizan Tech & Industry differentiates through USP-grade resveratrol isolation protocols that sustain premium positioning in European nutraceutical channels.
Polygonum Cuspidatum extract is derived from the rhizome of Reynoutria japonica, containing trans-resveratrol (typically 20-98% standardized), emodin, and polydatin; manufacturers employ ethanol-water extraction followed by chromatographic purification to achieve pharmaceutical purity tiers. Powder formulations dominate volume throughput due to blending flexibility in capsule and tablet production, while liquid extracts capture faster growth in functional beverage applications where solubility parameters determine formulation compatibility. Direct sales channels to contract manufacturers concentrate margin pools, whereas online retail segments compete on price transparency with thinner conversion economics.
China's NMPA enforces Good Agricultural Practice (GAP) certification for medicinal botanical cultivation, while the FDA's New Dietary Ingredient (NDI) notification requirements constrain US market entry for novel extract specifications. The EU's EFSA novel food catalog inclusion process for resveratrol-enriched extracts creates asynchronous approval timelines across Atlantic regulatory zones. Stakeholders must monitor evolving pharmacovigilance reporting obligations for botanical extracts in major destination markets to preempt supply chain disruption.
Market Dynamics
Pharmaceutical-grade resveratrol specifications are splitting procurement hierarchies between standardized extract grades and commodity botanical powders, forcing contract manufacturers to requalify suppliers against tightening purity thresholds.
Growth Catalysts
- Clinical nutraceutical demand:North American contract manufacturers are expanding resveratrol inclusion in capsule and tablet formulations for cardiovascular and metabolic health applications.
- NMPA herbal registration pathways:China's Good Agricultural Practice certification requirements for medicinal botanical cultivation are professionalizing upstream supply quality.
- Chromatographic purification advances:Manufacturers employing ethanol-water extraction with subsequent chromatographic isolation are achieving USP-grade purity tiers that unlock European nutraceutical channels.
Market Restraints
- Raw material concentration:Captive cultivation zones in Shaanxi province create geographic supply vulnerability for non-integrated formulators.
- Regulatory asynchrony:The EU's EFSA novel food catalog inclusion process for resveratrol-enriched extracts operates on timelines misaligned with FDA New Dietary Ingredient notification requirements.
- Emodin contamination limits:Technical constraints in separating emodin from trans-resveratrol during purification restrict acceptable extract grades for pharmaceutical applications.
Strategic Opportunities
- Functional beverage integration:Liquid extract formats with enhanced solubility parameters are penetrating beverage applications where powder formulations face compatibility barriers.
- Japan's PMDA botanical frameworks:Regulatory clarity around Kampo-derived ingredient approvals creates pathway expansion for standardized extracts in East Asian pharmaceutical channels.
- Direct-to-manufacturer channels:Bypassing distributor intermediaries allows extract producers to capture margin pools currently absorbed by blending houses and trading intermediaries.
Industry Challenges
- Analytical chemistry talent scarcity:Chromatographic method development and validation capabilities are concentrated among specialized laboratories, constraining in-house quality assurance scaling.
- Dual certification burden:Simultaneous pursuit of USP-grade pharmaceutical specifications and organic agricultural certifications extends compliance timelines and documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polygonum Cuspidatum Extract Market |
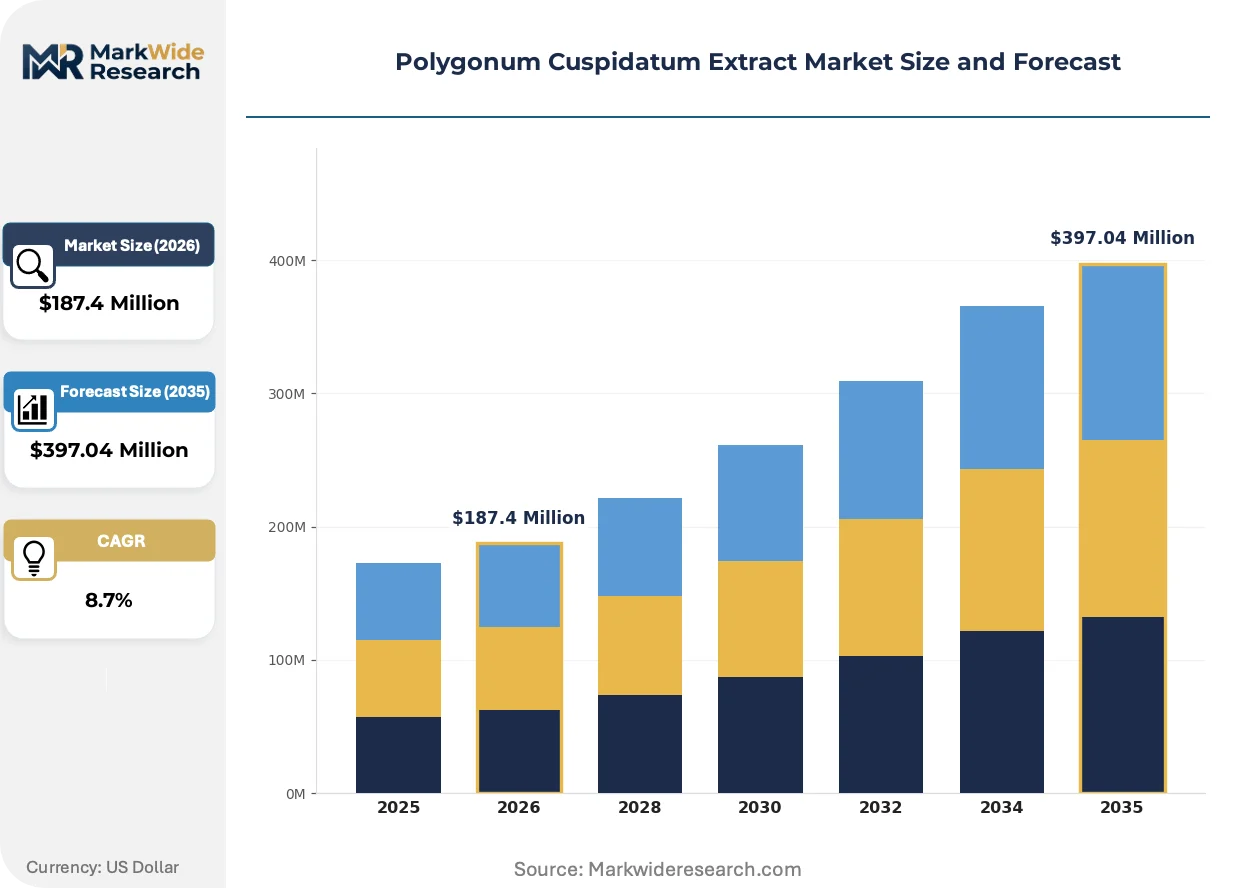
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tincture End Use Industry: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Form: Standardized Extract, Whole Herb, Concentrated Extract, Raw Material |
| Companies Covered | Shaanxi Jintai Biological, SV Spices, Organic Herb, Heking, Xi'an Tizan Tech & Industry, Xi'an Greena Biotech, New Natural, Huixin Biotech, Shaanxi Rebecca Bio-tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polygonum Cuspidatum Extract Market Evolving Landscape
Supercritical fluid extraction protocols and green chemistry purification methods are displacing conventional solvent-based processes, while regulatory authorities on both sides of the Atlantic tighten botanical extract documentation requirements.
Supercritical CO2 extraction technology is rewriting yield economics for high-purity resveratrol isolation. German pharmaceutical formulators are adopting these systems to reduce residual solvent burdens in final extract grades. This shift is compressing the cost differential between pharmaceutical-grade and premium nutraceutical specifications.
REACH registration requirements for botanical substances with novel extraction profiles are forcing European importers to submit comprehensive toxicological dossiers. The industrial consequence is supplier consolidation toward larger extract houses with dedicated regulatory affairs capabilities. Standardized extract grades above 50% trans-resveratrol concentration face the steepest compliance burden.
Buyer concentration among North American contract manufacturers is shortening qualification cycles and compressing supplier switching costs. Large capsule and tablet producers are consolidating vendor bases toward dual-certified extract houses with captive raw material control. This pattern is most visible in California and New Jersey manufacturing corridors where pharmaceutical and nutraceutical production overlap.
Polygonum Cuspidatum Extract Market Segmentation
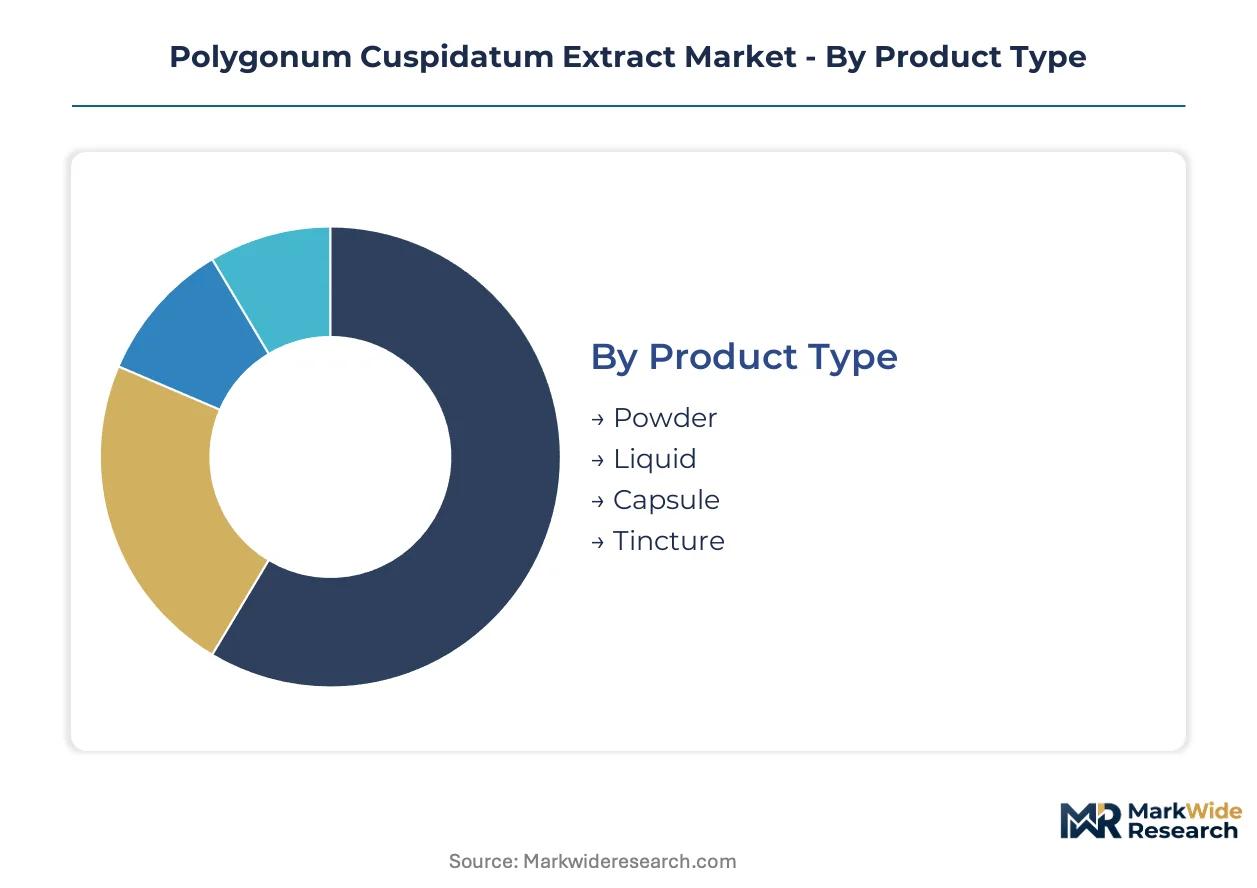
Specification tiers and format compatibility determine procurement economics across Polygonum Cuspidatum extract channels. Pharmaceutical-grade resveratrol isolation protocols split demand trajectories between standardized and commodity grades, while solubility requirements reshape formulation preferences.
Product Type:
Chromatographic purification depth and blending flexibility define competitive positioning across physical formats.
- Powder:Spray-dried or crystallized extracts with 20-98% trans-resveratrol standardization dominate capsule and tablet production lines. North American contract manufacturers in California and New Jersey corridors favor powder for its dosing precision and extended shelf stability.
- Liquid:Hydroalcoholic or glycerin-based solutions with enhanced solubility parameters penetrate functional beverage formulations. German beverage formulators are expanding liquid extract procurement for ready-to-drink cardiovascular health applications where powder dispersion fails.
- Capsule:Pre-encapsulated single-ingredient or blended formulations streamline downstream manufacturing for smaller nutraceutical brands lacking in-house blending capacity.
- Tincture:Traditional ethanol-based preparations with lower standardization capture artisanal and wellness retail channels prioritizing botanical authenticity over pharmaceutical-grade specifications.
Powder leads on scale; liquid leads on momentum.
End Use Industry:
Regulatory pathway complexity and purity thresholds stratify demand across downstream applications.
- Pharmaceuticals:USP-grade resveratrol specifications above 98% purity with sub-ppm emodin limits command premium positioning. Japan's PMDA Kampo-derived ingredient frameworks and EU EMA botanical drug pathways drive qualification investments for extract houses targeting prescription channels.
- Nutraceuticals:Standardized extracts at 50% trans-resveratrol concentration balance cost and clinical credibility for cardiovascular and metabolic health positioning. Direct sales to contract manufacturers concentrate volume in this segment.
- Cosmetics:Topical-grade extracts with antioxidant stabilization protocols address dermal delivery applications in South Korean and French formulation houses.
- Food & Beverage:Novel food authorization requirements under EFSA and FDA GRAS self-determination constrain resveratrol enrichment levels in commercial food matrices.
Nutraceuticals anchor current volume; pharmaceuticals command steepest expansion trajectory.
Distribution Channel:
Margin capture and customer relationship intensity vary sharply across channel architectures.
- Direct Sales:Long-term supply agreements with contract manufacturers and pharmaceutical formulators eliminate distributor markups. Shaanxi province extract houses with captive raw material control prioritize this channel for standardized extract grades.
- Online Retail:Price transparency and thin conversion economics dominate consumer-facing platforms, with commodity botanical powders competing on cost per gram of trans-resveratrol.
- Specialty Stores:Health food and natural products retailers curate premium-positioned extracts with organic or sustainability certifications for discerning supplement consumers.
- Supermarkets:Mass-market placement remains limited due to regulatory constraints on health claim substantiation for resveratrol-enriched products.
Direct sales concentrate margin pools; online retail expands access breadth.
Form:
Standardization depth and raw material traceability create tiered procurement hierarchies.
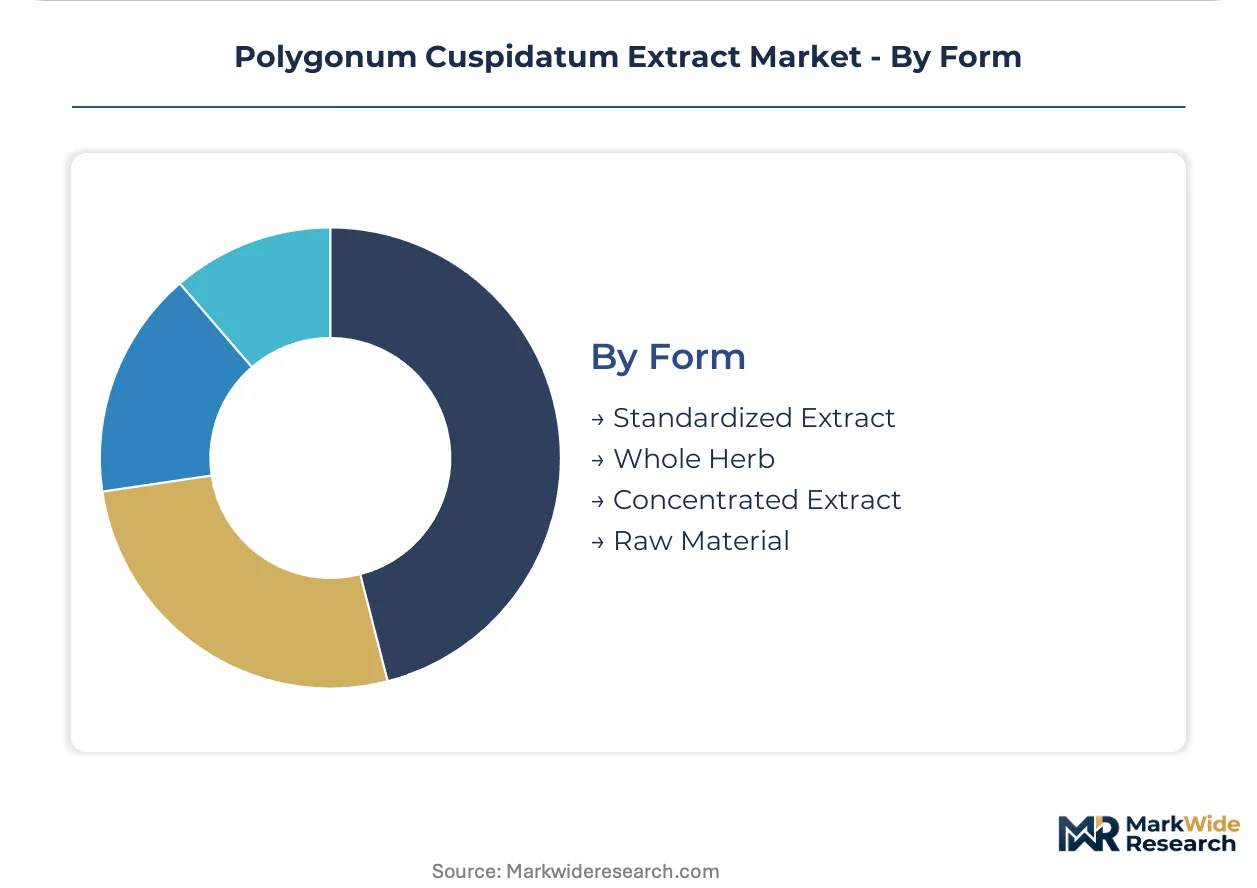
- Standardized Extract:Guaranteed trans-resveratrol concentration with batch-specific certificates of analysis satisfies pharmaceutical and clinical nutraceutical specifications. China's NMPA GAP certification requirements for upstream botanical cultivation reinforce traceability demands.
- Concentrated Extract:Partial purification without full chromatographic isolation offers intermediate purity tiers for premium wellness applications where cost sensitivity moderates.
- Whole Herb:Minimally processed rhizome preparations retain full phytochemical complexity for traditional medicine practitioners and holistic health channels.
- Raw Material:Unprocessed Reynoutria japonica rhizome supplies integrated extract houses with in-house purification capabilities, particularly in Shaanxi cultivation zones.
Standardized extract dominates revenue concentration; concentrated extract gains share fastest in mid-tier positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromatographic purification specialists cluster in Shaanxi province, anchoring China's dominance in standardized extract output. German and Japanese pharmaceutical formulators drive premium-grade resveratrol demand through divergent regulatory pathways.
China
Shaanxi province extract houses command upstream supply through captive Reynoutria japonica cultivation zones. NMPA enforces Good Agricultural Practice certification for medicinal botanical cultivation, professionalizing raw material quality assurance. Xi'an-based manufacturers concentrate chromatographic purification capacity serving North American contract manufacturing channels.
Germany
Pharmaceutical formulators in Bavaria and North Rhine-Westphalia expand supercritical CO2 extraction adoption for residual solvent reduction. REACH registration requirements for novel extraction profiles force toxicological dossier submissions on resveratrol-enriched imports. Frankfurt-Rhine-Main logistics clusters facilitate EU-wide distribution of USP-grade extract specifications.
Japan
Kampo-derived ingredient frameworks under PMDA create regulatory clarity for standardized extract approvals in prescription channels. Kansai region pharmaceutical manufacturers qualify Shaanxi suppliers against emodin contamination thresholds below 10 ppm. Osaka-based formulators integrate resveratrol into cardiovascular health positioning for aging demographics.
United States
California and New Jersey manufacturing corridors consolidate vendor bases toward dual-certified extract houses. FDA New Dietary Ingredient notification requirements constrain novel extract specification market entry. San Diego nutraceutical contract manufacturers shorten supplier qualification cycles for 50% standardized grades.
South Korea
Seoul Capital Area cosmetic formulators drive topical-grade extract procurement with antioxidant stabilization protocols. MFDS regulates botanical extract quality standards for dermal delivery applications. Incheon free trade zone importers navigate asynchronous EU-US regulatory timelines for resveratrol-enriched ingredients.
Polygonum Cuspidatum Extract Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade purification capacity, while mid-scale processors compete on standardized extract throughput. The vendor base stratifies across three archetypes: integrated extract houses with captive cultivation, specialized chromatographic purification laboratories, and commodity botanical powder traders. Dominant competitive moves include backward integration into Shaanxi raw material zones and direct sales channel expansion bypassing distributor intermediaries.
Within the integrated extraction tier, Shaanxi Jintai Biological and Xi'an Tizan Tech & Industry occupy positions exemplifying divergent strategic emphases—captive raw material control versus USP-grade protocol specialization. Xi'an Greena Biotech represents the mid-scale standardized segment serving nutraceutical contract manufacturing channels. These Shaanxi-based limited companies illustrate how geographic concentration in China's northwestern cultivation belt shapes competitive positioning without requiring vertical integration claims.
| Leading Market Players |
|---|
| Shaanxi Jintai Biological |
| SV Spices |
| Organic Herb |
| Heking |
| Xi'an Tizan Tech & Industry |
| Xi'an Greena Biotech |
| New Natural |
| Huixin Biotech |
| Shaanxi Rebecca Bio-tech |
| Others |
Value Network & Pricing Analysis
Captive Reynoutria japonica cultivation in Shaanxi province feeds through chromatographic purification intensity to determine downstream pricing tiers. NMPA GAP certification costs and emodin separation complexity stratify extract grades from commodity powder to USP-grade pharmaceutical specifications.
Pricing Analysis
Bundled analytical certification and unbundled raw extract supply split procurement economics across buyer segments. Pharmaceutical-grade resveratrol commands premium positioning through USP-grade purity protocols and sub-ppm emodin documentation, while commodity botanical powders compete on trans-resveratrol cost per gram. Price differentiation hinges on chromatographic purification depth and dual organic-pharmaceutical certification status. Cost compression in mid-tier standardized extracts intensifies as Shaanxi extract houses expand direct sales channels. Contract manufacturers in California and New Jersey corridors show least price sensitivity; online retail consumers exhibit highest.
Supply Chain Analysis
Reynoutria japonica rhizome supply rests on captive cultivation zones in China's Shaanxi province, with secondary sourcing from Sichuan and Gansu regions. Chromatographic purification capacity, ethanol-water extraction infrastructure, and supercritical CO2 equipment constitute critical input dependencies. Single-source vulnerability concentrates in Shaanxi's integrated extract houses controlling upstream botanical supply. Distribution runs through direct sales agreements with North American and European contract manufacturers, supplemented by specialty distributor networks for smaller nutraceutical brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Polygonum Cuspidatum extract market compounds steadily as clinical nutraceutical demand for standardized resveratrol grades sustains volume growth across cardiovascular and metabolic health applications.
For Market Incumbents: Anticipate emodin contamination threshold tightening from Japan's PMDA and EU EMA pharmacovigilance frameworks by investing in advanced chromatographic separation capacity. Secure backward integration into Shaanxi cultivation zones to defend raw material access against emerging Chinese competitors. Prioritize dual USP-grade and organic certification maintenance as qualification barriers rise.
For New Entrants and Emerging Players: Direct-to-manufacturer e-procurement platforms offer lowest-friction entry into mid-tier standardized extract supply. Target German beverage formulators seeking liquid extract formats with enhanced solubility parameters for functional cardiovascular applications. Lead with supercritical CO2 extraction positioning to differentiate from solvent-based incumbent processes.
For Investors and Strategic Acquirers: Roll-up economics work for chromatographic purification specialists because analytical chemistry talent scarcity and regulatory dossier capabilities concentrate value in specialized laboratories. Five-to-ten year viability hinges on extract houses capturing pharmaceutical channel qualification. Watch FDA NDI notification timelines for novel resveratrol specifications as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Chromatographic Capacity Expansion | Xi'an-based specialists achieve USP-grade purity tiers unlocking EMA-regulated pharmaceutical channels. |
| Supercritical CO2 Extraction Adoption | German formulators reduce residual solvent burdens to meet REACH registration requirements for novel extraction profiles. |
| Direct Sales Channel Buildout | Shaanxi extract houses capture margin pools previously absorbed by North American blending intermediaries. |
| Dual Certification Investment | Simultaneous USP-grade and organic agricultural certification extends compliance timelines but qualifies premium positioning. |
| Functional Beverage Format Development | Liquid extract solubility optimization penetrates German ready-to-drink cardiovascular health applications. |
Research Methodology
Multiple input streams — primary interviews with extract house technical directors, pharmaceutical formulator procurement leads, and regulatory affairs specialists; secondary validation against NMPA GAP certification databases, FDA NDI notification records, and EFSA novel food catalog entries; plus customs trade data on resveratrol-enriched extract flows — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from contract manufacturers across the projection horizon. Segmentation dimensions modeled include specification tier, physical format, end-use industry, and regional regulatory cluster. CAGRs were derived from trend extrapolation moderated by chromatographic purification yield improvements and emodin separation technology advancement curves.
The model assumes a particular technology adoption path; alternative pathways for supercritical CO2 extraction scale-up would alter the outlook. Forecasts reflect assumptions around NMPA enforcement consistency and EMA botanical drug pathway clarity. A small set of named triggers — PMDA emodin threshold revisions, REACH registration burden shifts, and FDA NDI notification backlog resolution — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Gum Turpentine Oil Market
Extracts
Helichrysum Oil Market
Extracts
Sage Extract Market
Extracts
Patchouli Oil Market
Extracts
Herba Houttuyniae Extract Market
Extracts
Amla Extract Market
Extracts
Belladonna Market
Extracts
Chlorophyll Extract Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Herb and Spice Extracts Market
Extracts
Solid Phase Extraction Market
Extracts
Saffron Extract Market
Extracts
Kelp Extracts Market
Extracts
Palmarosa Oil Market
Extracts
Global Azadirachtin Market
Extracts
Flower Extract Market