
 Floral Extract Market | 2026-2036
Floral Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Floral Extract Market Foresight
Supercritical CO2 extraction is fragmenting traditional solvent-based production across the fragrance supply chain. Givaudan leverages captive botanical sourcing networks across three continents to secure raw material consistency. Symrise anchors its competitive position through deep R&D integration in biotech-derived floral molecules. Robertet specializes in artisan-scale enfleurage methods for ultra-premium absolute oil grades.
Floral extract denotes concentrated aromatic compounds derived from flower biomass through mechanical, thermal, or chemical separation processes, typically yielding essential oils at 0.02-0.5% of fresh flower weight or absolutes at 0.1-0.3% through solvent washing. These materials serve as odor-active building blocks in formulated consumer products where synthetic replication fails to match botanical complexity. Essential oils and absolute oils together command the dominant share of value generation given their irreplaceable role in fine perfumery, while CO2 extraction represents the fastest-growing technology segment as supercritical systems eliminate thermal degradation and solvent residues. Hydrosols occupy a maturing, lower-margin position increasingly diverted from cosmetics into aromatherapy and wellness applications.
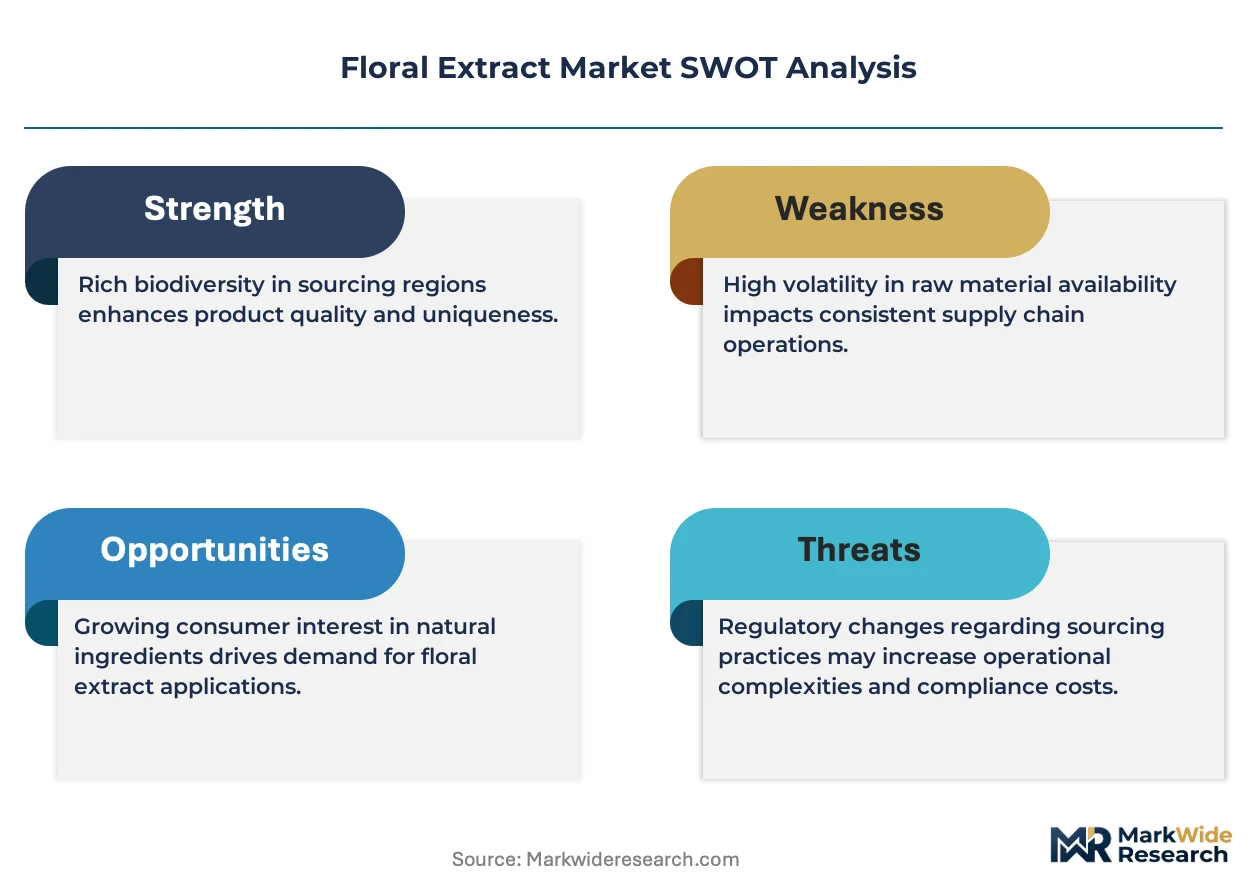
EMA and EFSA frameworks in Europe govern extract safety dossiers for cosmetic and food applications, while FDA oversight in the United States shapes GRAS determinations for floral ingredients entering food and beverage formulations. REACH registration requirements and evolving F-Gas Regulation constraints on solvent systems directly influence extraction technology investment decisions across manufacturing facilities. Stakeholders must monitor regulatory divergence between jurisdictions as classification thresholds for natural versus nature-identical claims harden in premium consumer segments.
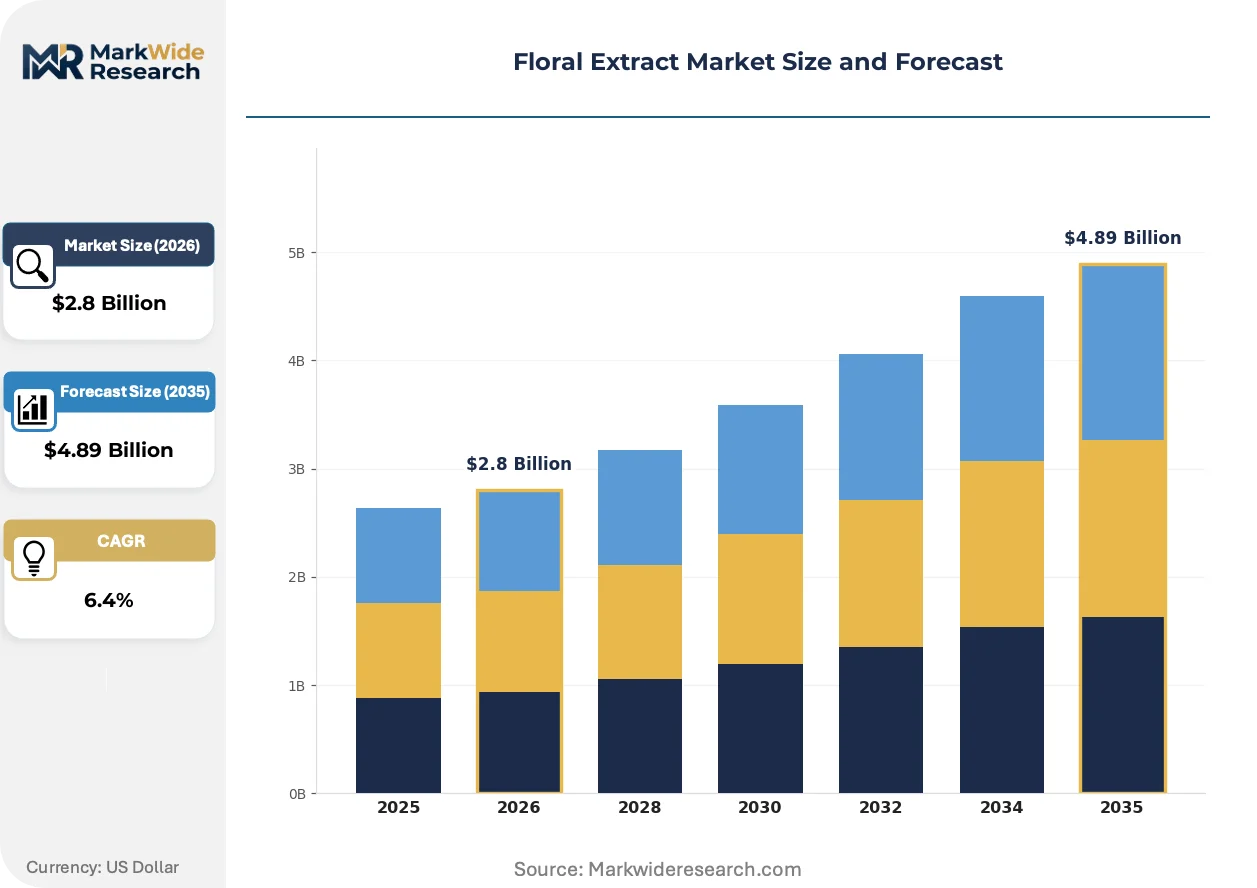
Market Dynamics
Supercritical CO2 extraction is fragmenting traditional solvent-based production across the fragrance supply chain, compressing margins for conventional absolute oil processors while enabling new entrants to bypass legacy infrastructure investments entirely.
Growth Catalysts
- REACH solvent residue thresholds:ECHA mandates tighten permissible solvent traces in absolute oils, pushing formulators toward CO2 and enfleurage alternatives that command premium positioning in clean-label cosmetics.
- Biotech-derived floral molecules:R&D integration in precision fermentation yields nature-identical compounds without agricultural volatility, securing supply consistency for mass-market fragrance houses.
- France's Grasse fragrance cluster:Concentrated expertise in artisan extraction methods preserves heritage techniques while attracting investment in scaled organic solvent recovery systems.
Market Restraints
- Jasmine and rose biomass volatility:Climate stress on Egyptian and Moroccan flower harvests creates input cost swings that destabilize processor margins and contract pricing.
- India's Kannauj essential oil belt concentration:Dependence on artisan distiller networks limits batch-to-batch consistency and scales contamination risk across premium supply tiers.
- Thermal degradation in steam distillation:Heat-sensitive floral compounds suffer yield loss, constraining essential oil quality grades available for fine perfumery applications.
Strategic Opportunities
- Underpenetrated aromatherapy channel:Hydrosol diversion from cosmetics into wellness applications opens volume absorption for lower-margin distillation byproducts.
- EU F-Gas Regulation phase-down:Solvent system constraints accelerate capital redeployment toward supercritical infrastructure eligible for green transition financing.
- Convergence of AI-driven molecule prediction:Computational chemistry platforms reduce screening cycles for novel floral accords, compressing development timelines for fragrance houses.
Industry Challenges
- Enfleurage skill scarcity:Mastery of traditional cold-fat absorption techniques concentrates among aging artisans in southern France, threatening artisan-scale capacity expansion.
- GRAS dossier complexity:FDA food-grade floral extract approvals require extensive toxicology investment, delaying market entry for botanical beverage applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floral Extract Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Absolute Oils, Concrete, Resinoids, Hydrosols Application: Perfumery, Cosmetics, Food & Beverages, Pharmaceuticals, Aromatherapy Extraction Technology: Steam Distillation, Solvent Extraction, Cold Pressing, CO2 Extraction, Enfleurage End User: Fragrance Manufacturers, Personal Care Manufacturers, Food Producers, Pharmaceutical Companies, Wellness Centers |
| Companies Covered | Givaudan, Symrise, Firmenich SA, International Flavors & Fragrances Inc., Robertet, Carrubba Incorporated, Naturalin Bio-Resources Co., Ltd., Katyani Exports, NESSO-Natural & Essential Oils Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floral Extract Market Shifts & Advancements
Extraction technology portfolios are bifurcating as sustainability mandates and quality premiums reshape capital allocation across fragrance manufacturing infrastructure.
Supercritical CO2 systems is migrating from pilot installations to commercial-scale deployment across mid-tier processors, eliminating thermal degradation pathways that compromise heat-sensitive floral volatiles. Cosmetics formulators in North American clean-beauty segments now specify CO2 extracts as default inputs, compressing demand for conventional hexane-washed absolutes in premium skincare lines.
EU F-Gas Regulation constraints on hydrofluorocarbon solvent systems are forcing extraction facility retrofits across European manufacturing bases, redirecting investment toward closed-loop CO2 and ethanol infrastructure. REACH registration burdens for novel solvent chemistries extend approval timelines, advantaging incumbent supercritical equipment suppliers with established compliance dossiers.
Direct-procurement contracts between cosmetics brands and captive botanical estates are displacing spot-market flower buying across premium fragrance supply tiers. Grasse-based houses and Indian distiller cooperatives now face buyer consolidation as L'Oréal and Estée Lauder entities establish exclusive biomass partnerships, compressing intermediary margins in traditional absolute oil trading channels.
Floral Extract Market Segmentation
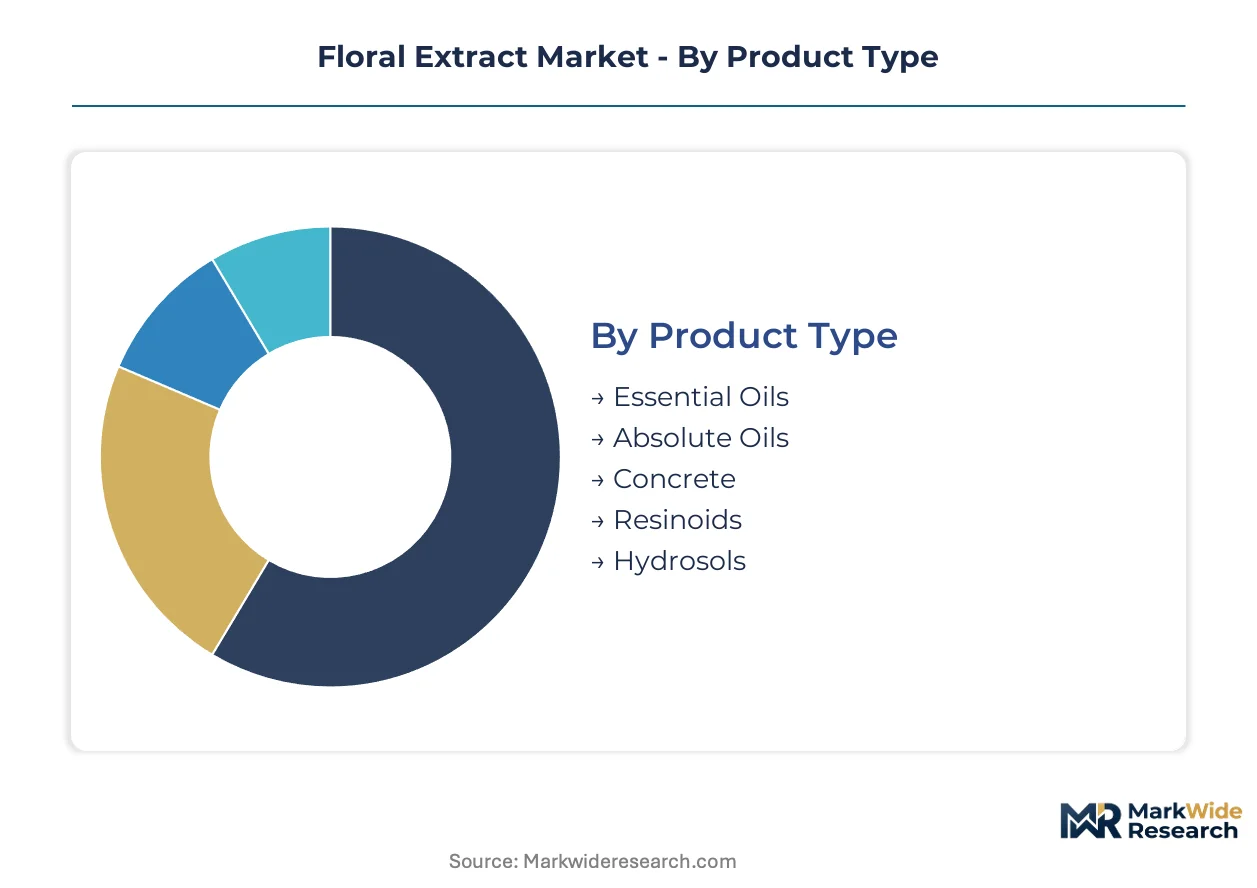
Segmentation in floral extracts reveals how value migrates across extraction methods and end-use specifications. Product categories differ radically in yield rates, solvent profiles, and regulatory treatment. Application channels impose divergent purity thresholds that reshape processor investment priorities.
Product Type:
Mature absolutes and essential oils dominate revenue concentration while emerging formats gain traction in clean-label segments.
- Essential Oils:Volatile aromatic compounds recovered through steam distillation or mechanical expression, typically comprising 0.02-0.5% of fresh flower mass. Demand concentrates in fine perfumery applications across France's Grasse cluster, where jasmine and rose oils command premium pricing tied to harvest volatility in Morocco and Egypt.
- Absolute Oils:Solvent-extracted concentrates yielding 0.1-0.3% of biomass, capturing heat-sensitive floral notes destroyed by distillation. Cosmetics formulators in North American clean-beauty segments specify absolutes for skincare lines, though REACH solvent residue thresholds are compressing hexane-washed supply.
- Concrete:Waxy, highly concentrated extract produced through hydrocarbon solvent washing of fresh flowers, serving as intermediate feedstock for absolute production.
- Resinoids:Solvent-extracted aromatic materials from resinous floral sources, primarily deployed in fixative applications for oriental fragrance families.
- Hydrosols:Aqueous co-products from steam distillation containing trace volatile compounds, increasingly diverted from cosmetics into aromatherapy and wellness applications.
Essential oils retain volume leadership; CO2-extracted absolutes hold the steepest expansion curve.
Application:
Cost tiers separate commodity fragrance inputs from pharmaceutical-grade specifications requiring exhaustive safety dossiers.
- Perfumery:Fine fragrance houses in France and Switzerland consume ultra-premium grades of jasmine, rose, and tuberose absolutes where synthetic replication fails. Batch-to-batch consistency requirements favor CO2 extracts for mass-market launches.
- Cosmetics:Skincare and color cosmetic formulators specify floral extracts for sensorial positioning and clean-label claims. EMA and EFSA cosmetic safety frameworks govern extract purity thresholds across European manufacturing.
- Food & Beverages:GRAS determinations by FDA constrain floral ingredient deployment in botanical beverages, with rose water and orange blossom extracts holding established approvals.
- Pharmaceuticals:Standardized extracts for traditional medicine applications face pharmacopeial compliance requirements that limit supplier qualification.
- Aromatherapy:Wellness channel absorption of lower-grade hydrosols and essential oils creates volume outlet for distillation byproducts.
Perfumery commands premium pricing tiers; cosmetics shows the fastest volume absorption.
Extraction Technology:
Technology choice determines capital intensity, yield quality, and regulatory exposure across processor facilities.
- Steam Distillation:Thermal separation yielding essential oils through vapor-phase extraction, dominating volume production for robust floral matrices. India's Kannauj belt relies on artisan distiller networks using traditional copper stills.
- Solvent Extraction:Hydrocarbon washing for absolute and concrete production, facing EU F-Gas Regulation constraints on solvent system emissions and REACH registration burdens for novel chemistries.
- Cold Pressing:Mechanical expression reserved for citrus floral tissues where peel oil co-extraction applies, limited relevance for true flower biomass.
- CO2 Extraction:Supercritical systems eliminate thermal degradation and solvent residues, migrating from pilot to commercial scale across mid-tier processors.
- Enfleurage:Traditional cold-fat absorption mastered by aging artisans in southern France, producing ultra-premium grades for heritage fragrance houses.
Steam distillation retains installed base dominance; CO2 extraction gains share fastest.
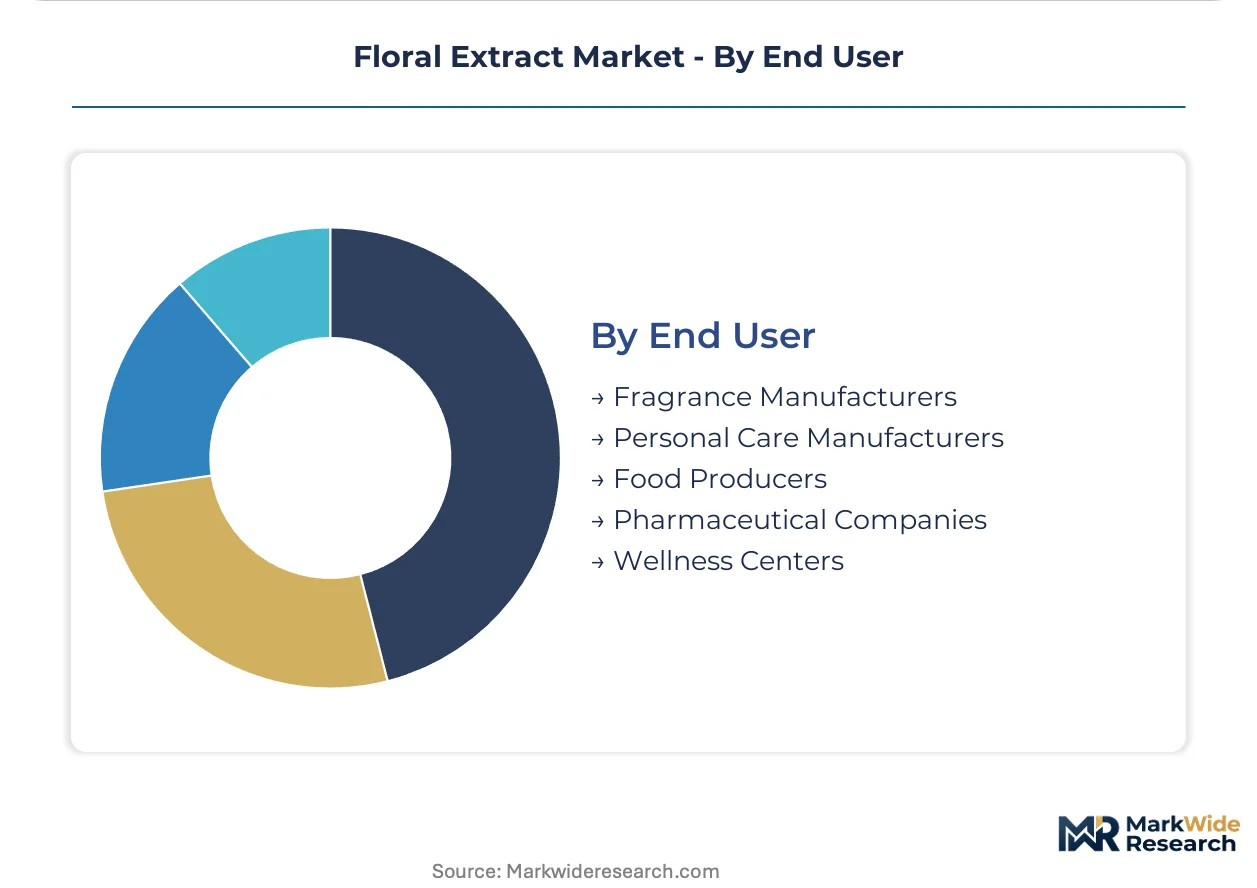
End User:
Customer type dictates contract structures, from spot-market spot buying to captive estate partnerships.
- Fragrance Manufacturers:Givaudan, Symrise, and Robertet anchor demand through direct-procurement contracts with botanical estates, displacing traditional absolute oil traders.
- Personal Care Manufacturers:L'Oréal and Estée Lauder entities establish exclusive biomass partnerships, compressing intermediary margins in premium supply tiers.
- Food Producers:Beverage and confectionery applications require food-grade certifications that extend approval timelines and limit qualified supplier pools.
- Pharmaceutical Companies:Standardized extract requirements for traditional medicine formulations favor vertically integrated processors with in-house analytical capabilities.
- Wellness Centers:Aromatherapy and spa channel demand absorbs lower-margin hydrosol volumes, creating outlet for distillation byproducts.
Fragrance manufacturers concentrate procurement power; personal care verticals show the steepest integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fragrance manufacturers in France and personal care conglomerates in the United States anchor procurement demand for floral extracts. India's artisan distiller networks supply essential oil volumes. Regulatory divergence across jurisdictions shapes extraction technology investment patterns.
France
Fine fragrance houses in Grasse drive demand for jasmine and rose absolutes in ultra-premium perfumery applications. ECHA REACH mandates tighten solvent residue thresholds for absolute oils entering cosmetic formulations. The Grasse fragrance cluster preserves heritage enfleurage techniques while attracting investment in scaled organic solvent recovery systems.
United States
Clean-beauty cosmetics formulators specify CO2 extracts as default inputs for skincare lines. FDA GRAS determinations constrain floral ingredient deployment in botanical beverages, extending approval timelines for rose water and orange blossom applications. Direct-procurement contracts between New Jersey-based personal care manufacturers and captive botanical estates displace traditional absolute oil trading channels.
India
Artisan distiller networks in Uttar Pradesh's Kannauj belt supply steam-distilled essential oils for fragrance compounding. FSSAI food-grade certification requirements limit qualified supplier pools for extract applications entering domestic and export markets. The Kannauj essential oil belt faces batch-to-batch consistency challenges as buyer consolidation pressures intermediary margins.
Switzerland
Precision fermentation R&D operations yield nature-identical floral molecules for mass-market fragrance houses. Swissmedic pharmaceutical-grade standards govern extract purity for traditional medicine applications. Geneva-based flavor and fragrance entities anchor competitive positioning through biotech-derived compound portfolios.
Morocco
Rose and jasmine harvests in the Dadès Valley supply biomass for absolute oil production across European fragrance supply chains. Climate stress on agricultural yields creates input cost volatility that destabilizes processor contract pricing. Casablanca-based extraction facilities face margin compression as supercritical CO2 alternatives bypass legacy solvent infrastructure.
Floral Extract Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Givaudan, Symrise, and Firmenich SA anchor demand through direct-procurement contracts with botanical estates. Three archetypes dominate: integrated fragrance houses with captive sourcing networks, mid-tier processors deploying supercritical extraction infrastructure, and artisan-scale specialists preserving heritage methods. Competitive moves concentrate on backward integration into upstream biomass control and technology licensing for CO2 extraction systems.
Within the integrated fragrance house tier, Givaudan and Symrise exemplify channel-controlling archetypes that secure raw material consistency through multi-continent botanical networks. Robertet occupies a position representing artisan-scale specialization in traditional extraction methods. International Flavors & Fragrances Inc. anchors the scale-driven segment with broad portfolio coverage across flavor and fragrance applications. These entities collectively illustrate how procurement power concentrates among buyers with direct estate partnerships, compressing margins for intermediary traders in absolute oil markets.
| Leading Market Players |
|---|
| Givaudan |
| Symrise |
| Firmenich SA |
| International Flavors & Fragrances Inc. |
| Robertet |
| Carrubba Incorporated |
| Naturalin Bio-Resources Co., Ltd. |
| Katyani Exports |
| NESSO-Natural & Essential Oils Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Marseille-Rotterdam freight corridors transmit Egyptian jasmine and Moroccan rose biomass cost volatility directly into absolute oil pricing tiers, amplifying spreads between artisan enfleurage grades and solvent-extracted standards as downstream buyers sort by clean-label positioning.
Pricing Analysis
Cost-plus contracts with Moroccan harvest indexation dominate procurement between Grasse fragrance houses and Dadès Valley suppliers, embedding agricultural risk into processor margins. Price differentiation rests on extraction method certification and REACH compliance grade, with CO2-extracted absolutes commanding premium positioning over hexane-washed alternatives. Pricing pressure intensifies in mid-tier solvent-extracted segments as supercritical alternatives bypass legacy infrastructure investments. Mass-market fragrance compounds exhibit highest price sensitivity; heritage perfumery houses demonstrate inelastic demand for artisan-scale enfleurage output.
Supply Chain Analysis
Upstream feedstock from Egyptian jasmine fields, Moroccan rose plantations, and Indian Kannauj distiller networks anchors global essential oil and absolute production volumes. The supply chain draws from copper still artisan infrastructure, hydrocarbon solvent recovery systems, and supercritical CO2 processing equipment. Single-source vulnerability concentrates in Egyptian and Moroccan biomass harvests exposed to climate stress. Distribution runs through direct-procurement contracts between fragrance houses and captive botanical estates, displacing spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floral extract markets exhibit cyclical recovery characteristics as cosmetics formulators restock clean-label inventories following pandemic-era destocking, with jasmine and rose harvest volatility serving as the primary cyclical driver.
For Market Incumbents: Harden procurement positions through exclusive biomass partnerships with Moroccan and Egyptian estates, locking in supply ahead of climate-stressed harvest cycles. Invest in closed-loop CO2 extraction infrastructure eligible for EU green transition financing to defend margin position against solvent-extracted competitors facing F-Gas Regulation constraints. For New Entrants and Emerging Players: North American wellness channel hydrosol absorption represents underpenetrated volume opportunity for distillation byproduct monetization. Target aromatherapy and spa segments with certified organic hydrosol SKUs, leveraging direct-to-wellness-brand distribution partnerships to bypass established fragrance house procurement gatekeepers. For Investors and Strategic Acquirers: Mid-tier processors with installed supercritical CO2 capacity and established REACH compliance dossiers present acquisition targets with technology licensing leverage. Monitor ECHA solvent residue threshold enforcement as inflection signal for accelerated CO2 extraction adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Botanical Estate Partnership | Secures jasmine and rose biomass consistency for Givaudan and Symrise procurement networks. |
| Supercritical CO2 Capacity Expansion | Positions processors ahead of REACH solvent residue threshold tightening across European manufacturing. |
| Heritage Enfleurage Method Preservation | Maintains Robertet artisan-scale differentiation in ultra-premium absolute oil segments. |
| Biotech-Derived Molecule R&D Integration | Enables Symrise to bypass agricultural volatility through precision fermentation supply security. |
| Hydrosol Wellness Channel Diversion | Absorbs lower-margin distillation byproducts into aromatherapy volume outlets. |
Research Methodology
A spread of perspectives from fragrance house procurement directors, cosmetics formulators, Indian distiller cooperative managers, and supercritical equipment suppliers converged on the working assumptions underlying this analysis. Primary interview intelligence combined with secondary validation from ECHA REACH registration databases, FAO agricultural harvest statistics, customs trade flow records, and SEC filings from publicly traded flavor and fragrance entities. Bottom-up volume estimates triangulated against top-down market sizing across extraction technology and application segments.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning product type, extraction technology, application channel, and end-user archetype. CAGRs derived from fitted growth curves applied to historical volume trajectories, incorporating jasmine and rose harvest yield volatility, regulatory compliance cost escalations, and CO2 extraction technology adoption rates as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese supercritical equipment manufacturers or accelerated biotech molecule substitution by Swiss fermentation specialists would shift outcomes beyond modeled ranges. Cross-checking against FAO floral biomass harvest statistics and ECHA solvent registration timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Pullulan Market
Extracts
Citrus Powder Market
Extracts
Anise Extract Market
Extracts
Rosa Roxburghii Powder Market
Extracts
Belladonna Market
Extracts
Extracts and Distillates Market
Extracts
Thymoquinone Market
Extracts
Organic Herbal Extracts Market
Extracts
CO2 Extract Market
Extracts
Myrrh Powder Market
Extracts
Botanicals Market
Extracts
Sandalwood Oil Market
Extracts
Asia-Pacific Mineral Turpentine Market
Extracts
Peppermint Leaf Powder Market
Extracts
Chlorophyll Extract Market
Extracts
Helichrysum Oil Market