
 Functional Extract Market | 2026-2036
Functional Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Extract Market Foresight
The gap between premium certified-organic extracts and commodity-grade botanicals is expanding. Givaudan leverages vertical integration from raw material sourcing to finished flavor systems. dsm-firmenich anchors its position through R&D intensity in fermentation-derived actives. Synthite Industries Ltd dominates spice extract production with manufacturing scale across South Asian supply chains.
Functional extracts are concentrated bioactive compounds isolated from plant, marine, microbial, or animal matrices through mechanical, chemical, or enzymatic processes, typically standardized to specific marker compound percentages for batch consistency. Supercritical fluid extraction using carbon dioxide at critical temperatures and pressures preserves thermolabile compounds for high-value nutraceutical applications. Plant-based extracts lead volume due to established agronomic supply chains, while marine extracts capture expanding margin pools in cosmeceutical formulations. Enzymatic extraction is displacing solvent-based methods in pharmaceutical-grade production as manufacturers target EU pharmacopeia compliance.
FDA GRAS notifications and EFSA novel food assessments shape market access timelines for new extract entrants in North America and Europe. REACH registration requirements and EU MDR standards for active cosmetic ingredients enforce traceability and toxicological documentation across supply chains. Stakeholders must monitor evolving classification debates around synthetic biology-derived extracts versus traditional botanicals.
Market Dynamics
Enzymatic extraction is overtaking solvent-based methods as pharmaceutical-grade producers chase EU pharmacopeia compliance, compressing batch-to-batch variability premiums while fragmenting equipment supplier tiers between legacy solvent-system vendors and bioprocessing specialists.
Growth Catalysts
- EU Green Deal procurement mandates:Food and beverage formulators in Germany now require certified-organic botanical traceability from Frankfurt and Hamburg processing clusters, pulling premium extract volumes upstream.
- Supercritical CO2 technology maturation:Critical-point carbon dioxide systems preserve thermolabile actives for nutraceutical applications, opening margin pools previously captured by synthetic alternatives.
- Clean-label formulation pressure:End-use brands are reformulating around plant-derived markers, standardizing procurement specifications to specific compound percentages rather than generic botanical grades.
Market Restraints
- Raw material concentration risk:Spice extract supply chains concentrate across South Asian agronomic belts, exposing processors to monsoon variability and port congestion at Mumbai and Kochi.
- REACH registration friction:ECHA documentation requirements for novel botanical actives extend market access timelines by 18-24 months for entrants lacking existing dossiers.
- Fermentation-derived substitution:Microbial production of identical marker compounds threatens premium pricing for agricultural extracts in cosmetic applications.
Strategic Opportunities
- Marine extract white space:Cosmeceutical formulators in South Korea and Japan are sourcing fucoidan and astaxanthin from North Atlantic and Pacific aquaculture operations, bypassing saturated plant-extract competition.
- FDA GRAS self-determination pathway:North American entrants are leveraging independent expert panel consultations to accelerate novel food ingredient timelines without full notification review.
- Direct-to-manufacturer platform distribution:Specialty chemical marketplaces are disintermediating traditional flavor house aggregators for mid-volume nutraceutical buyers.
Industry Challenges
- Phytochemical standardization expertise scarcity:Analytical chemists capable of validating marker compound consistency across heterogeneous agricultural inputs command premium compensation, constraining quality team scaling.
- Dual carbon goal compliance capex:China's MEE enforcement of energy-intensity benchmarks for extraction facilities requires solvent recovery system retrofits exceeding RMB 8 million for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Extract Market |
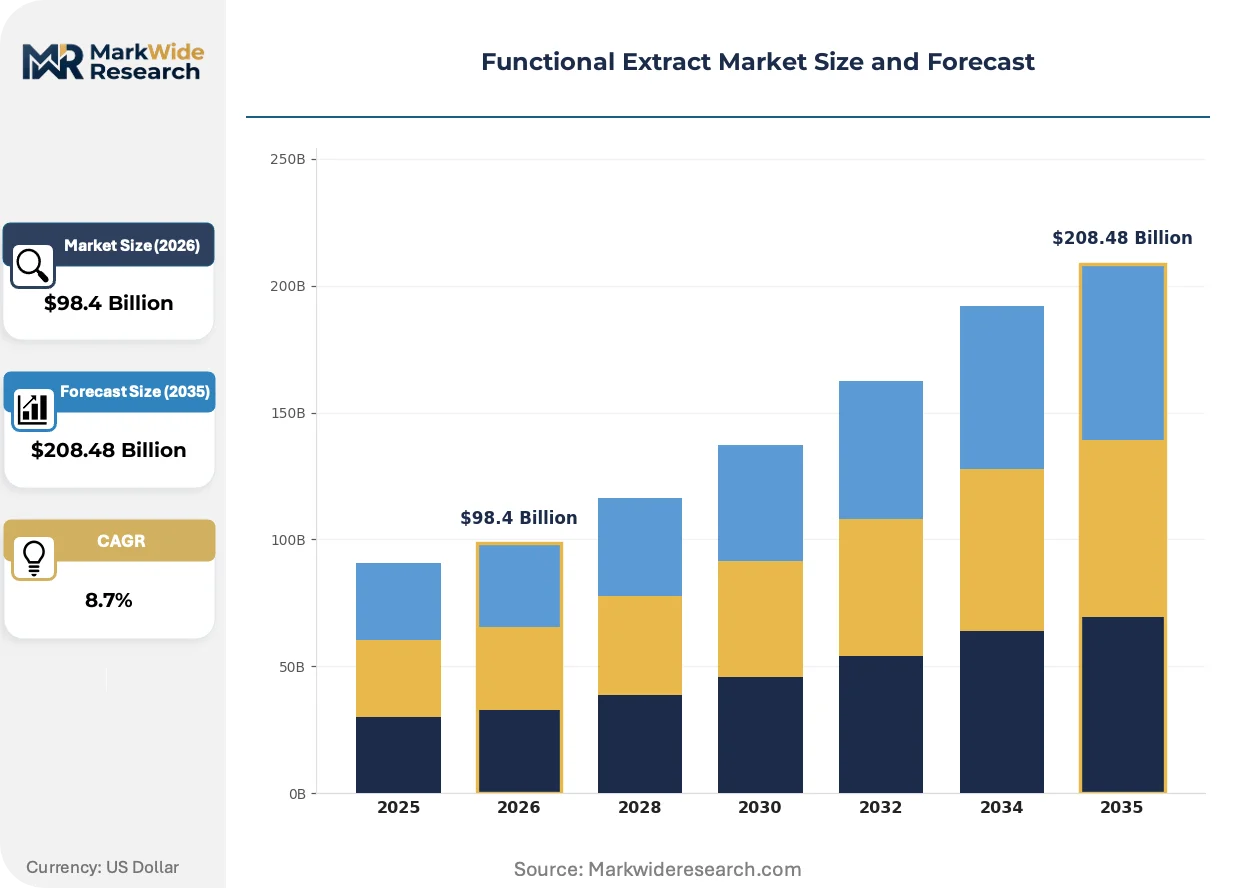
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $208.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Extracts, Marine Extracts, Microbial Extracts, Animal-Derived Extracts, Synthetic Extracts Application: Dietary Supplements, Functional Beverages, Nutraceuticals, Cosmetics, Food Additives Extraction Technology: Supercritical Fluid, Solvent Extraction, Ultrasound-Assisted, Microwave-Assisted, Enzymatic Extraction End User Industry: Personal Care Manufacturers, Food & Beverage Producers, Pharmaceutical Companies, Animal Nutrition Suppliers, Agricultural Firms |
| Companies Covered | Givaudan, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Symrise AG, dsm-firmenich, Synthite Industries Ltd, Indesso, Cargill Incorporated, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Extract Market Shifts & Advancements
Extraction technology is bifurcating between precision bioprocessing and legacy solvent infrastructure, with regulatory chemistry defining competitive moats more than scale economics. This divergence is compressing equipment replacement cycles and fragmenting vendor consolidation patterns.
Supercritical fluid extraction using carbon dioxide at critical temperatures and pressures is overtaking hexane-based methods in high-value nutraceutical production. European pharmaceutical-grade buyers now specify CO2-derived actives for thermolabile compounds, forcing solvent-system vendors to reposition toward commodity spice applications or exit. The technology is compressing yield-loss premiums previously embedded in batch variability insurance.
REACH registration requirements and EU MDR standards for active cosmetic ingredients are tightening toxicological documentation mandates across botanical supply chains. ECHA's 2024 updates to substance evaluation criteria now require in-vitro skin sensitization data for novel extracts, extending dossier preparation timelines. German and French cosmetic formulators are responding by consolidating supplier bases to incumbent registrants with existing Annex III listings.
Certification-driven procurement is fragmenting buyer-seller relationships as clean-label specifications proliferate beyond organic to include regenerative agriculture and fair-trade botanical sourcing. North American natural products retailers are unbundling flavor system purchases from full-service houses, instead contracting directly with certified extract processors for transparency documentation. This pattern is most visible in California and Colorado supplement manufacturing clusters, where lot-level blockchain traceability now appears in RFP requirements.
Functional Extract Market Segmentation
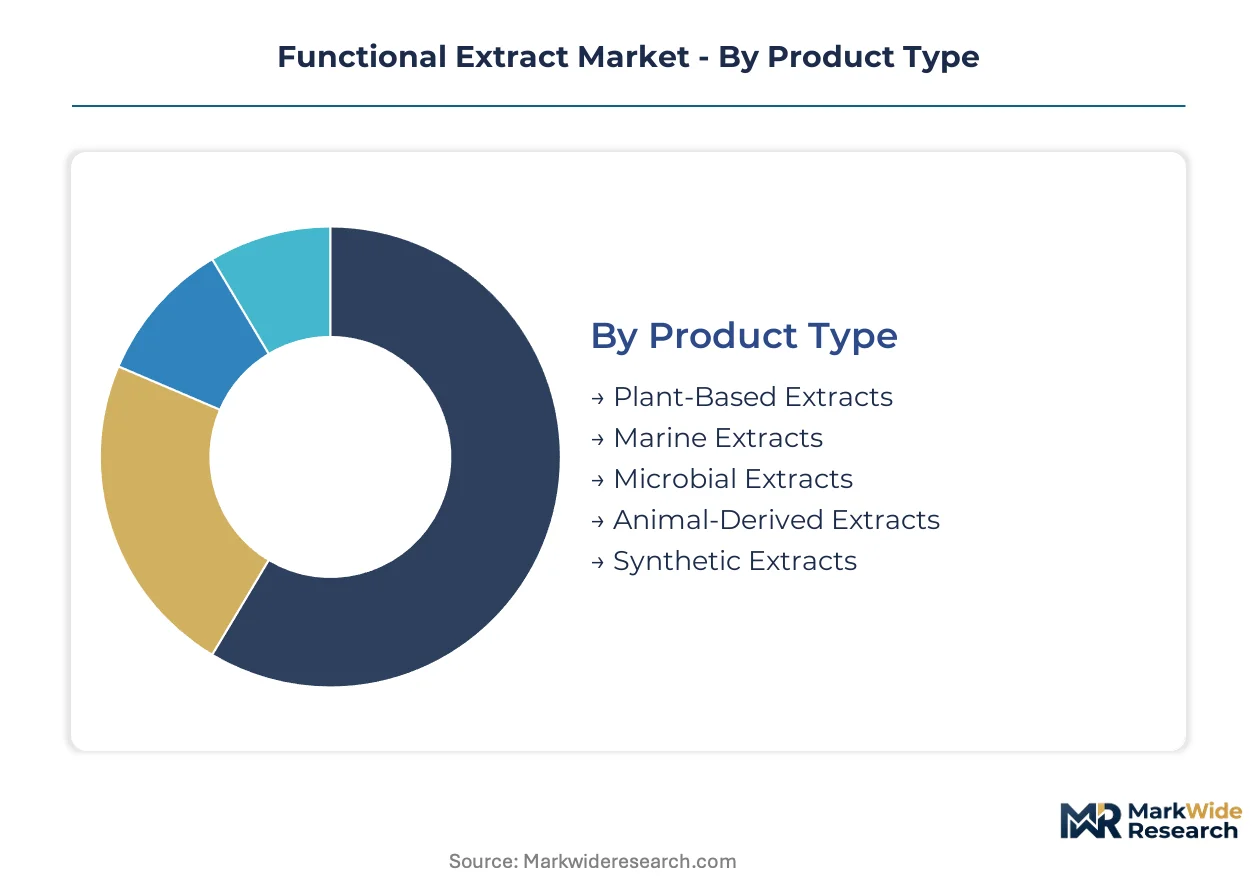
Segmentation in functional extracts reveals divergent margin architectures across sourcing matrices and processing intensities. Procurement specifications now standardize to marker compound percentages rather than generic botanical grades, compressing commodity premiums while elevating certified-organic and pharmacopeia-compliant tiers.
Product Type:
Volume leadership sits with established agronomic supply chains, while marine and microbial alternatives capture expanding margin pools in cosmeceutical and fermentation-derived applications.
- Plant-Based Extracts:Concentrated bioactive compounds isolated through mechanical, chemical, or enzymatic processes, typically standardized to specific marker percentages for batch consistency. Demand concentrates in Germany, where ingredient processors cluster around Frankfurt and Hamburg procurement clusters, pulled by EU Green Deal mandates for certified-organic botanical traceability.
- Marine Extracts:Fucoidan, astaxanthin, and other aquaculture-derived actives sourced from North Atlantic and Pacific operations. Cosmeceutical formulators in South Korea and Japan are bypassing saturated plant-extract competition, opening white-space margin pools previously captured by synthetic alternatives.
- Microbial Extracts:Fermentation-derived actives threatening premium pricing for agricultural extracts in cosmetic applications through identical marker compound production.
- Animal-Derived Extracts:Specialized protein and lipid fractions for pharmaceutical and nutraceutical formulations with established pharmacopeia monographs.
- Synthetic Extracts:Chemically identical bioactive reproductions facing classification debates versus traditional botanicals under evolving regulatory frameworks.
Today's leader: Plant-Based Extracts. Tomorrow's challenger: Marine Extracts.
Application:
End-use demand fragments between high-volume beverage fortification and high-margin cosmeceutical actives, with regulatory chemistry defining competitive moats more than scale economics.
- Dietary Supplements:Standardized botanical capsules and tablets requiring GRAS notifications or novel food assessments for market access. North American natural products retailers in California and Colorado clusters now demand lot-level blockchain traceability in procurement specifications.
- Functional Beverages:Clean-label fortification driving procurement of plant-derived markers. Food and beverage producers are scaling procurement volumes while unbundling purchases from full-service flavor houses to contract directly with certified extract processors.
- Nutraceuticals:Supercritical CO2-derived thermolabile actives for high-value applications, compressing yield-loss premiums previously embedded in batch variability insurance.
- Cosmetics:Active ingredients subject to EU MDR standards and ECHA skin sensitization data requirements, extending dossier preparation timelines for novel entrants.
- Food Additives:GRAS self-determination pathways accelerating timelines for North American entrants through independent expert panel consultations.
Dietary Supplements command current revenue concentration. Cosmetics exhibits the steepest expansion trajectory as EFSA and FDA toxicological documentation mandates consolidate supplier bases to incumbent registrants.
Extraction Technology:
Equipment replacement cycles are compressing as pharmaceutical-grade producers chase EU pharmacopeia compliance, fragmenting vendor tiers between legacy solvent-system suppliers and bioprocessing specialists.
- Supercritical Fluid:Carbon dioxide at critical temperatures and pressures preserves thermolabile compounds for nutraceutical applications. European pharmaceutical-grade buyers now specify CO2-derived actives, forcing solvent-system vendors to reposition toward commodity spice applications or exit.
- Solvent Extraction:Hexane-based methods losing share in high-value segments while retaining cost advantages for commodity spice processing. China's MEE enforcement of energy-intensity benchmarks requires solvent recovery system retrofits exceeding RMB 8 million for mid-scale processors.
- Ultrasound-Assisted:Mechanical cell disruption reducing extraction times and solvent volumes for heat-sensitive botanical matrices.
- Microwave-Assisted:Rapid heating protocols for polar compound recovery with reduced thermal degradation profiles.
- Enzymatic Extraction:Displacing solvent-based methods in pharmaceutical-grade production as manufacturers target EU pharmacopeia compliance, compressing batch-to-batch variability premiums.
Supercritical Fluid dominates premium positioning. Enzymatic Extraction is gaining share fastest through pharmacopeia alignment and sustainability metrics.
End User Industry:
Procurement concentration varies by documentation burden, with pharmaceutical and personal care buyers consolidating supplier bases while food and beverage formulators fragment toward direct processor relationships.
- Personal Care Manufacturers:German and French cosmetic formulators are consolidating supplier bases to incumbent registrants with existing Annex III listings under tightened ECHA substance evaluation criteria.
- Food & Beverage Producers:Scaling procurement of plant-based extracts for clean-label formulations with specifications standardizing to compound percentages rather than generic grades.
- Pharmaceutical Companies:Requiring EU pharmacopeia compliance and REACH registration dossiers, extending market access timelines by 18-24 months for entrants lacking existing documentation.
- Animal Nutrition Suppliers:Feed-grade botanical extracts with lower purity thresholds but volume-scale procurement patterns.
- Agricultural Firms:Biopesticide and biostimulant applications sourcing standardized phytochemical fractions for crop protection formulations.
Food & Beverage Producers anchor current volume. Pharmaceutical Companies are climbing the fastest as toxicological documentation mandates elevate incumbent advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled analytical chemists capable of validating marker compound consistency anchor demand concentration in Germany, while procurement specialists in South Korea and Japan drive marine extract specifications. This workforce distribution pulls processing investment toward Frankfurt-Hamburg clusters and Pacific aquaculture zones.
Germany
Ingredient processors cluster around Frankfurt and Hamburg procurement hubs, drawn by EU Green Deal mandates for certified-organic botanical traceability. ECHA REACH registration requirements enforce toxicological documentation standards that extend dossier preparation timelines. Quality teams in Hesse now command premium compensation for phytochemical standardization expertise.
United States
Natural products retailers in California and Colorado supplement manufacturing clusters demand lot-level blockchain traceability in procurement specifications. FDA GRAS self-determination pathways accelerate novel food ingredient timelines through independent expert panel consultations. Chicago-area flavor houses face disintermediation pressure as mid-volume nutraceutical buyers shift to direct processor relationships.
China
Mid-scale processors face MEE enforcement of energy-intensity benchmarks requiring solvent recovery system retrofits exceeding RMB 8 million. Dual carbon goal compliance capex is compressing equipment replacement cycles for legacy extraction facilities. Zhejiang and Jiangsu province chemical parks concentrate supercritical CO2 system adoption for thermolabile nutraceutical production.
South Korea
Cosmeceutical formulators source fucoidan and astaxanthin from North Atlantic and Pacific aquaculture operations, bypassing saturated plant-extract competition. MFDS cosmetic ingredient regulations align with tightened EU MDR standards for active botanical documentation. Seoul-based R&D centers anchor marine extract white-space development for regional beauty brands.
India
Synthite Industries Ltd dominates spice extract production with manufacturing scale across South Asian supply chains, exposing processors to monsoon variability and port congestion at Mumbai and Kochi. FSSAI clean-label formulation standards are pulling procurement specifications toward compound percentage standardization. Kerala and Karnataka agronomic belts concentrate raw material sourcing for global flavor houses.
Functional Extract Market Competitive Landscape
Top-tier vendors anchor premium pharmacopeia-compliant tiers, while mid-scale processors compete on certified-organic traceability documentation. The vendor base stratifies between full-service flavor houses with captive R&D intensity and specialty extract processors with direct-to-manufacturer platform distribution. Two strategic archetypes dominate: vertically integrated agronomic operators controlling raw material sourcing, and fermentation-derived active specialists threatening agricultural extract pricing. Competitive moves concentrate on M&A for backward integration into supply chains and technology licensing for enzymatic extraction systems.
Within the vertically integrated tier, Givaudan and dsm-firmenich represent archetypes of upstream control from raw material sourcing through finished formulation systems. Synthite Industries Ltd exemplifies scale-driven positioning across South Asian spice extract production. These three occupy positions that reflect divergent margin architectures: flavor-system integration, fermentation-derived R&D intensity, and agronomic supply chain scale respectively.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Symrise AG |
| dsm-firmenich |
| Synthite Industries Ltd |
| Indesso |
| Cargill Incorporated |
| ADM |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade buyers in Germany and France consolidate procurement around incumbent registrants with existing REACH dossiers, anchoring a contract-based long-term offtake model that rewards documentation depth over spot-market flexibility. This buyer concentration compresses commodity premiums while elevating certified-organic and pharmacopeia-compliant tiers through specification standardization to marker compound percentages.
Pricing Analysis
Full-service flavor houses bundle R&D, formulation, and regulatory support into premium service tiers, while specialty extract processors compete on unbundled transactional pricing for mid-volume nutraceutical buyers. Three-tier pricing structure across premium pharmacopeia-compliant, standard certified-organic, and economy commodity grades reflects certification investment and analytical validation depth. Cost compression in the economy tier intensifies as enzymatic extraction technology matures and equipment depreciation accelerates. Mid-volume nutraceutical buyers exhibit highest price sensitivity, whereas cosmetic formulators in South Korea and Japan prioritize lot-level traceability documentation over unit economics.
Supply Chain Analysis
EU Green Deal domestic-content mandates for certified-organic botanical traceability reshape sourcing patterns, pulling premium extract volumes toward Frankfurt and Hamburg processing clusters. Raw material supply concentrates in India for spice extracts, China for supercritical CO2 equipment and mid-scale processing, and Pacific aquaculture zones for marine actives. Agronomic inputs including turmeric rhizomes, green tea leaf, and kelp biomass anchor production costs, while critical processing components encompass carbon dioxide systems and fermentation bioreactors. Single-source vulnerability runs through South Asian monsoon-dependent harvests and Mumbai-Kochi port congestion. Distribution runs through direct-to-manufacturer platform marketplaces disintermediating traditional flavor house aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic extraction technology maturation offers margin expansion through yield optimization and reduced batch-to-batch variability insurance, while marine extract white spaces capture premium pricing previously absorbed by synthetic alternatives.
For Market Incumbents: Deepen backward integration into South Asian agronomic supply chains to secure raw material concentration against monsoon variability and port congestion exposure. Expand supercritical CO2 capacity in Zhejiang and Jiangsu province chemical parks to capture thermolabile active demand from European pharmaceutical-grade buyers. Fermentation-derived substitution threats from microbial marker compound production demand accelerated R&D intensity in proprietary enzymatic extraction systems. For New Entrants and Emerging Players: Launch via direct-to-manufacturer platform distribution targeting California and Colorado supplement manufacturing clusters with lot-level blockchain traceability specifications. Marine extract applications in South Korean and Japanese cosmeceutical formulations present the most penetrable white space, bypassing saturated plant-extract competition. FDA GRAS self-determination pathway through independent expert panel consultations offers accelerated market access without full notification review timelines. For Investors and Strategic Acquirers: Flavor houses with captive R&D intensity represent the most active acquirer category in this space, consolidating backward integration into supply chains and technology licensing for enzymatic systems. Long-term viability centers on documentation-capable processors with existing REACH dossiers and Annex III cosmetic ingredient listings. Watch ECHA substance evaluation criteria updates for inflection indicators on novel extract market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agronomic Supply | Secures raw material traceability against South Asian monsoon variability and Kochi port congestion. |
| Enzymatic Extraction Technology Licensing | Accelerates EU pharmacopeia compliance while compressing batch-to-batch variability premiums. |
| Marine Extract Aquaculture Partnership | Opens fucoidan and astaxanthin margin pools for South Korean and Japanese cosmeceutical formulators. |
| Direct-to-Manufacturer Platform Launch | Disintermediates traditional flavor house aggregators for mid-volume nutraceutical buyers in North America. |
| REACH Dossier Acquisition | Consolidates supplier bases under tightened ECHA substance evaluation criteria for cosmetic actives. |
Research Methodology
Direct dialogue with extraction technology vendors, quality assurance directors at ingredient processors, procurement leads at flavor houses, and regulatory affairs specialists at ECHA and FDA anchored qualitative grounding. Secondary validation drew from REACH registration databases, FDA GRAS notification filings, EFSA novel food assessment records, and customs trade data on botanical extract flows. Bottom-up and top-down triangulation cross-referenced equipment installation records with end-use procurement specifications.
Bottom-up modeling aggregated segment-level demand across extraction technology tiers, sourcing matrices, and application end-uses, while top-down analysis calibrated aggregate market evolution against regulatory chemistry shifts and agronomic supply patterns. Segmentation dimensions encompassed product type, application, extraction technology, and end-user industry across the projection horizon. CAGRs derived from equipment replacement cycle compression, certification-driven procurement fragmentation, and geographic demand concentration patterns. Industry-specific inputs included supercritical CO2 system adoption rates and enzymatic extraction capacity buildouts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA regulatory acceleration or South Asian climate disruption scenarios. Forecasts reflect documented assumptions on technology maturation curves and procurement specification evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Chamomile Oil Market
Extracts
Europe Mineral Turpentine Market
Extracts
Extracts and Distillates Market
Extracts
Labdanum Market
Extracts
Herb and Spice Extracts Market
Extracts
Fig Glycolic Extract Market
Extracts
Turpentine Market
Extracts
Copaiba Essential Oil Market
Extracts
Essential Oil Isolates Market
Extracts
Myrrh Powder Market
Extracts
Asia-Pacific Mineral Turpentine Market
Extracts
Potassium Hydrogen Tartrate Market
Extracts
Global Rose Oils Market
Extracts
CO2 Extract Market
Extracts
Palmarosa Oil Market
Extracts
Tagetes Oil Market