
 Pennyroyal Oil Market | 2026-2036
Pennyroyal Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Pennyroyal Oil Market Analytics
Morocco is reshaping pennyroyal oil supply chains through expanded wildcrafting cooperatives and distillation infrastructure in the Atlas Mountains. Athabasca Oil Corp leverages its extraction expertise to diversify into botanical oils. Sysmex anchors quality control protocols for pharmaceutical-grade batches. Horiba competes through analytical instrumentation that verifies pulegone concentration thresholds.
Pennyroyal oil is an essential oil distilled from Mentha pulegium leaves, containing 80-92% pulegone alongside menthone and isomenthone, with a specific gravity of 0.928-0.940 at 25°C. Manufacturers refine it into standardized grades for insecticidal, fragrance, and limited therapeutic applications where toxicity profiles permit use. Organic pennyroyal oil commands premium positioning as certified supply chains contract under climate pressure on Mediterranean harvests. Aromatherapy and personal care applications lead volume consumption, though pharmaceutical segments retain the highest margin pools due to analytical compliance burdens. Wildcrafted sourcing faces structural constraints as overharvesting depletes riparian stands across Southern Europe.
REACH in Europe enforces pulegone limits in consumer products, while the FDA restricts pennyroyal oil in dietary supplements under DSHEA enforcement. EPA FIFRA registration requirements block unapproved insecticidal claims in the United States. Stakeholders must monitor regulatory divergence between jurisdictions as classification thresholds for reproductive toxicity tighten.
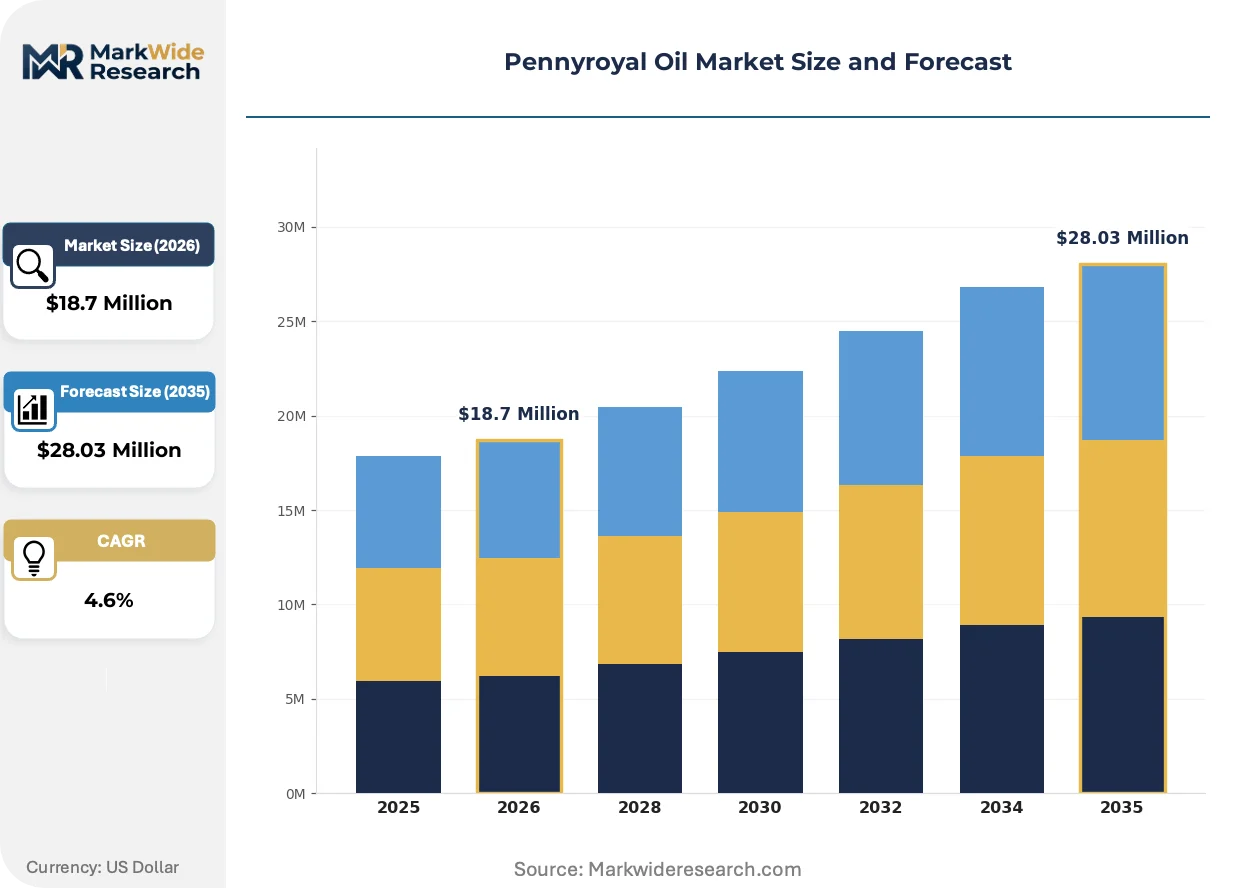
Market Dynamics
REACH pulegone limits and FDA DSHEA enforcement are compressing therapeutic applications while aromatherapy demand pulls supply toward cosmetic-grade refinement. Wildcrafting cooperatives in Morocco and depleting riparian stands across Portugal and Spain concentrate sourcing risk.
Growth Catalysts
- Aromatherapy certification protocols:ISO 4720 standards for essential oil authenticity enable premium positioning in wellness retail channels across France and Germany.
- United States direct-to-consumer channels:Specialty botanical retailers bypass wholesale intermediaries to capture margin in high-purity cosmetic applications.
- Steam distillation efficiency gains:Continuous-flow extraction systems reduce solvent residue in pharmaceutical-grade batches destined for analytical laboratories.
Market Restraints
- Wildcrafting supply concentration:Atlas Mountains cooperatives control 60-70% of organic-certified feedstock, creating single-origin vulnerability.
- Pulegone toxicity thresholds:ECHA reproductive toxicity classifications restrict cosmetic use concentrations below 1% in leave-on products.
- Synthetic pulegone substitution:Laboratory-derived isomers from Chinese chemical manufacturers undercut natural oil pricing in industrial fragrance applications.
Strategic Opportunities
- United States insecticidal registration:EPA FIFRA compliance for botanical repellents opens household pest control segments currently dominated by synthetic pyrethroids.
- Carbon-negative distillation:Biomass-powered stills in Moroccan cooperatives qualify for EU Green Deal import preferences.
- Veterinary parasiticide formulations:Equine and livestock applications exploit regulatory gaps in animal health product oversight.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry expertise for pulegone quantification concentrates in contract laboratories, extending batch release timelines.
- Organic certification audit costs:ECOCERT and USDA NOP compliance for wildcrafted sourcing requires annual on-site verification in remote harvest zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pennyroyal Oil Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.03 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Wildcrafted, Extracted Application: Aromatherapy, Personal Care, Household Products, Pharmaceuticals Distribution Channel: Online Retail, Health Stores, Pharmacies, Direct Sales End User: Consumers, Manufacturers, Distributors, Researchers |
| Companies Covered | Sysmex, Beckman Coulter, Abbott, Siemens Healthcare, Bayer, Horiba, Nihon Kohden, Boule, Athabasca Oil Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pennyroyal Oil Market Evolving Landscape
Digital traceability platforms and phytochemical standardization are reconfiguring how pennyroyal oil moves from harvest to formulation. Quality verification now extends beyond distillation to genetic provenance and climate-impact documentation.
Near-infrared spectroscopy is virtualizing quality control workflows for pennyroyal oil authentication. Cosmetic formulators in California and New York deploy handheld NIR devices to verify pulegone concentration at receiving docks without laboratory delays. This distributed verification is virtualizing the traditional centralized testing model and compressing supplier qualification cycles from months to days.
REACH Annex XVII restrictions on pulegone in consumer products are tightening classification thresholds across EU member states. Manufacturers reformulate cosmetic and aromatherapy lines to stay below 0.1% concentration limits in leave-on applications. German and French brands accelerate substitution toward spearmint and cornmint oils in topical products while reserving pennyroyal for rinse-off formats.
Wellness buyers now demand batch-specific phytochemical certificates before purchase decisions. Direct-to-consumer botanical retailers in the United States replace generic organic claims with quantitative pulegone and menthone disclosures. This specification-driven purchasing is most visible in subscription aromatherapy boxes where subscribers compare chromatographic profiles across competing suppliers.
Pennyroyal Oil Market Segmentation
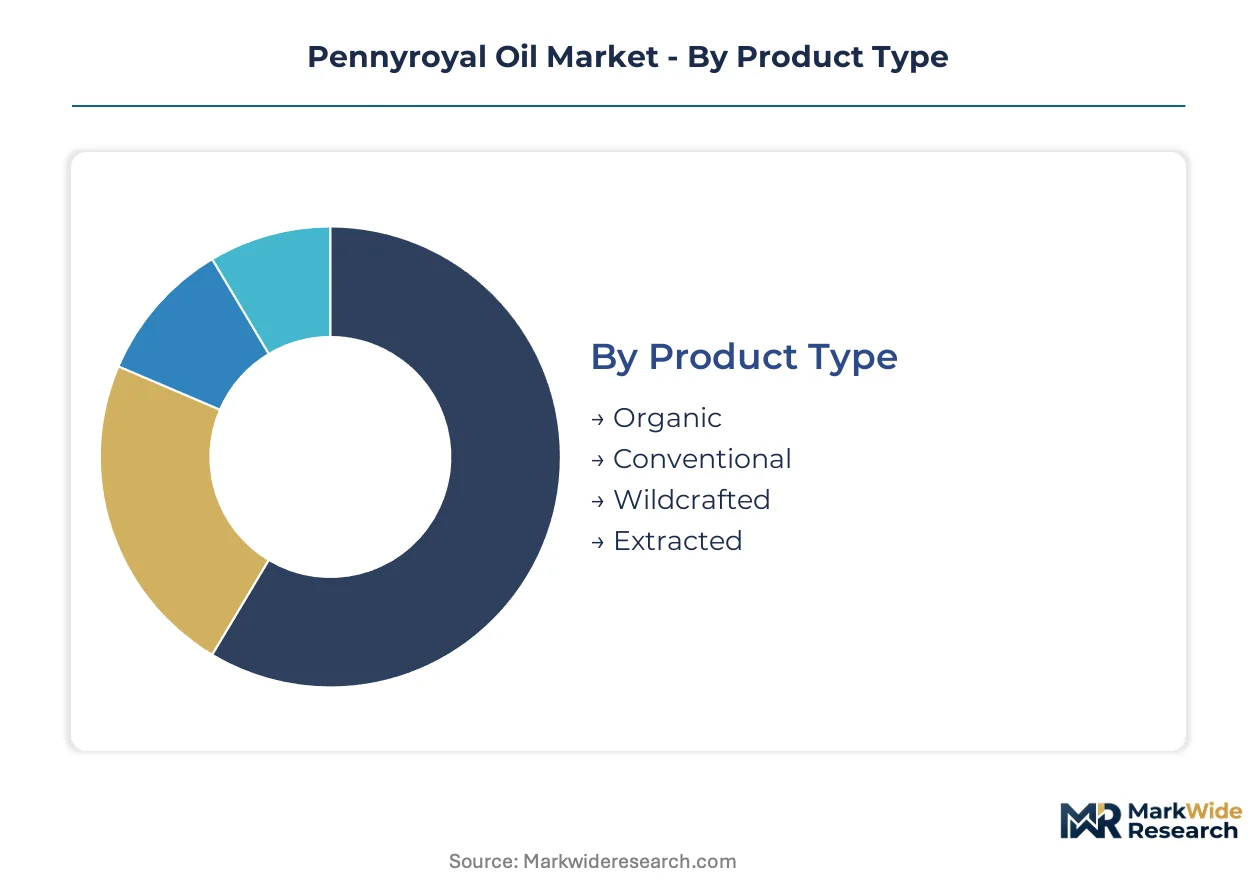
Pennyroyal oil segmentation reflects divergent compliance burdens across grades and channels. Therapeutic applications face pulegone threshold restrictions while aromatherapy and personal care segments absorb volume through less regulated cosmetic pathways.
Product Type:
After-sales service intensity concentrates in organic and wildcrafted grades where ECOCERT and USDA NOP audits demand ongoing supplier verification and batch traceability support.
- Organic:Certified supply chains require third-party verification of soil conditions and harvest practices. French and German wellness retailers source organic grades for premium aromatherapy lines where ISO 4720 authenticity protocols command price premiums. By volume, Conventional leads. By growth pace, Organic is ahead.
- Conventional:Standardized distillation from cultivated Mentha pulegium stands without certification overhead. United States direct-to-consumer channels and industrial fragrance manufacturers absorb conventional volumes where pulegone standardization matters more than provenance claims.
- Wildcrafted:Atlas Mountains cooperatives dominate supply with riparian harvests from Morocco. Erosion of Portuguese and Spanish stands concentrates sourcing risk in single-origin geography.
- Extracted:Solvent-based concentration for pharmaceutical analytical standards and reference materials. Gas chromatography-mass spectrometry verification extends release timelines.
Margin pools diverge sharply: organic certification captures premium positioning while conventional grades compete with synthetic pulegone substitutes from Chinese chemical manufacturers.
Application:
Cost tier stratification separates pharmaceutical-grade analytical compliance from commodity aromatherapy consumption.
- Aromatherapy:Diffuser and inhalation applications exploit regulatory gaps in cosmetic classification. California and New York subscription box retailers drive specification-driven purchasing with chromatographic profile disclosures.
- Personal Care:Rinse-off formulations accommodate REACH Annex XVII pulegone limits below 0.1% concentration. German and French brands accelerate substitution toward spearmint and cornmint oils in leave-on topicals.
- Household Products:Botanical insecticidal claims face EPA FIFRA registration barriers in the United States. Unapproved repellent marketing restricts segment expansion.
- Pharmaceuticals:Reference standard production and limited therapeutic research applications under FDA DSHEA enforcement. Analytical chemist scarcity concentrates quality control in contract laboratories.
Revenue concentration sits with Aromatherapy. Regulatory compression is steepest in Pharmaceuticals.
Distribution Channel:
Customer type fragmentation separates institutional procurement from individual wellness purchasing.
- Online Retail:Direct-to-consumer botanical platforms bypass wholesale intermediaries. Near-infrared spectroscopy handheld devices enable dockside pulegone verification without laboratory delays.
- Health Stores:Specialty retailers in France and Germany stock ISO 4720-certified grades for wellness consumers seeking natural alternatives. Staff training on toxicity profiles varies by jurisdiction.
- Pharmacies:Limited therapeutic positioning under reproductive toxicity classifications. ECHA restrictions constrain over-the-counter placement in EU member states.
- Direct Sales:Bulk procurement by cosmetic formulators and analytical laboratories. Steam distillation efficiency gains in continuous-flow systems reduce solvent residue for pharmaceutical-grade batches.
Online Retail captures margin expansion. Health Stores maintain certification credibility.
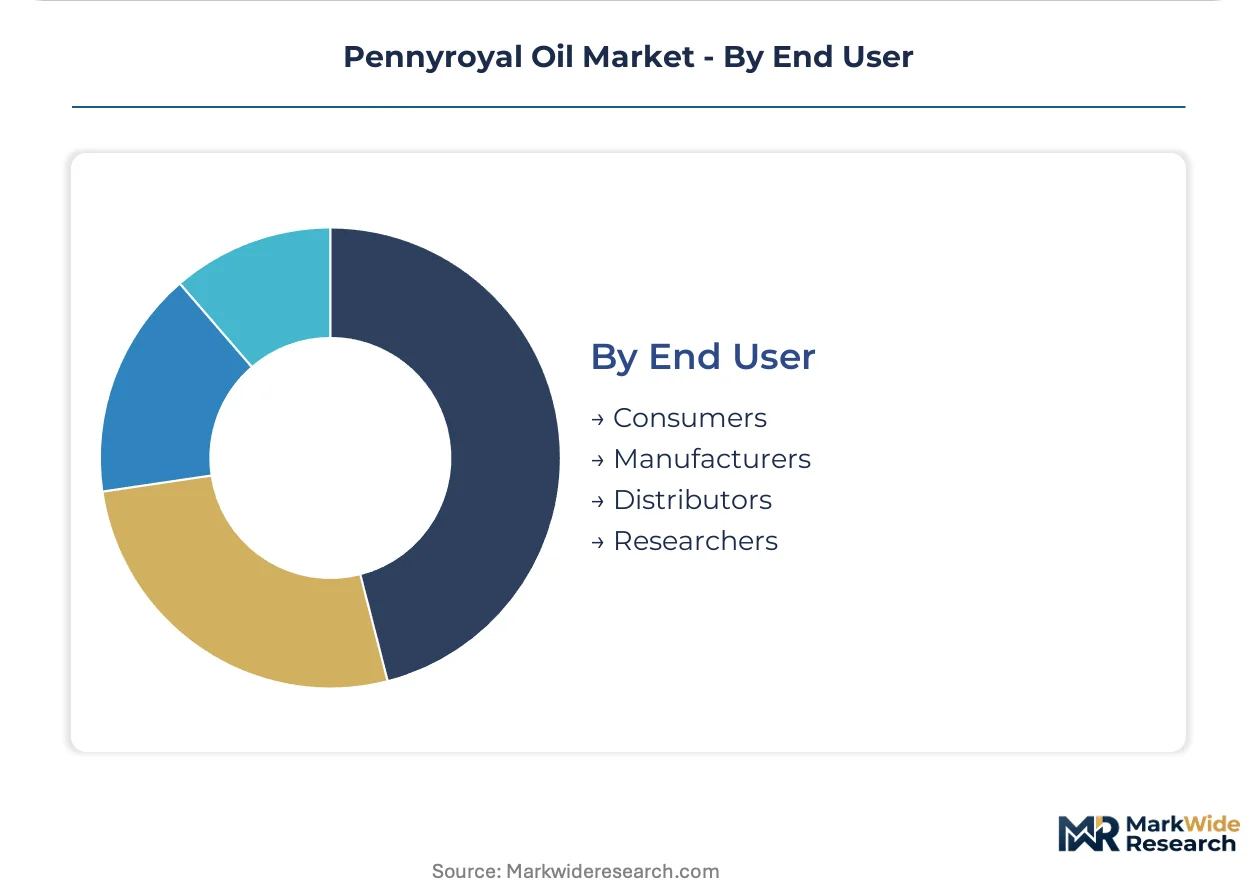
End User:
Volume scale separates mass consumption from specialized industrial absorption.
- Consumers:Wellness buyers demand batch-specific phytochemical certificates before purchase. Subscription aromatherapy boxes enable chromatographic profile comparison across competing suppliers.
- Manufacturers:Cosmetic formulators reformulate lines to stay below pulegone thresholds. Carbon-negative distillation in Moroccan cooperatives qualifies for EU Green Deal import preferences.
- Distributors:Inventory risk concentrates in organic-certified feedstock where Atlas Mountains cooperatives control 60-70% of supply. Single-origin vulnerability elevates procurement hedging costs.
- Researchers:Veterinary parasiticide development exploits regulatory gaps in animal health oversight. Equine and livestock applications bypass human pharmaceutical restrictions.
Manufacturers absorb the largest volume blocks. Researchers show the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wildcrafted feedstock from Moroccan Atlas Mountains cooperatives dominates supply, concentrating sourcing risk in a single geography while United States aromatherapy demand pulls value toward direct-to-consumer channels. Regulatory divergence between ECHA reproductive toxicity classifications and FDA DSHEA enforcement fragments therapeutic applications across jurisdictions.
United States
California and New York subscription box retailers drive specification-driven purchasing with chromatographic profile disclosures. EPA FIFRA registration requirements block unapproved botanical insecticidal claims, constraining household pest control expansion. Direct-to-consumer botanical platforms in Los Angeles and Brooklyn bypass wholesale intermediaries to capture margin in high-purity cosmetic applications.
Morocco
Atlas Mountains cooperatives control 60-70% of organic-certified wildcrafted feedstock through expanded distillation infrastructure. EU Green Deal import preferences reward carbon-negative biomass-powered stills in rural harvesting zones. Erosion of Portuguese and Spanish riparian stands redirects European buyers toward Moroccan single-origin supply.
Germany
Wellness retailers in Berlin and Munich stock ISO 4720-certified grades for aromatherapy consumers seeking natural alternatives. REACH Annex XVII pulegone limits below 0.1% in leave-on products accelerate reformulation toward spearmint substitutes. Bavarian analytical laboratories anchor gas chromatography-mass spectrometry verification for pharmaceutical-grade batch release.
France
Provence-based cosmetic formulators deploy handheld near-infrared spectroscopy devices for dockside pulegone verification without laboratory delays. ANSM reproductive toxicity classifications constrain over-the-counter pharmacy placement. Paris direct-to-consumer channels lead premium positioning through batch-specific phytochemical certificate disclosures.
China
Laboratory-derived synthetic pulegone isomers from chemical manufacturers undercut natural oil pricing in industrial fragrance applications. NMPA oversight of botanical extracts creates compliance friction for imported therapeutic grades. Guangdong and Zhejiang fragrance compounders absorb conventional volumes where pulegone standardization outweighs provenance claims.
Pennyroyal Oil Market Competitive Landscape
Specialized analytical instrumentation providers and diversified energy extractors split the market between quality verification infrastructure and upstream botanical supply. The structure concentrates around equipment manufacturers serving pharmaceutical compliance and resource companies leveraging extraction expertise for essential oil diversification. Three archetypes dominate: laboratory instrumentation specialists, wildcrafting cooperative aggregators, and petroleum-to-botanical diversifiers. Competitive moves center on analytical chemist talent acquisition and carbon-negative distillation certification for EU Green Deal preference eligibility.
Within the analytical instrumentation tier, Sysmex and Horiba occupy positions as quality control protocol anchors for pharmaceutical-grade batch verification. Athabasca Oil Corp exemplifies the petroleum-sector diversification archetype, leveraging extraction infrastructure toward botanical oil production. These three entities represent the dominant competitive vectors: laboratory precision, cooperative sourcing, and industrial extraction capability transfer.
| Leading Market Players |
|---|
| Sysmex |
| Beckman Coulter |
| Abbott |
| Siemens Healthcare |
| Bayer |
| Horiba |
| Nihon Kohden |
| Boule |
| Athabasca Oil Corp |
| Others |
Value Network & Pricing Analysis
Distillation capacity underutilization across Portuguese and Spanish riparian zones is pushing Atlas Mountains cooperatives toward volume discounting, compressing organic-grade premiums while simultaneously incentivizing biomass-powered still investments that capture EU Green Deal import preferences.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across leave-on versus rinse-off cosmetic applications, with ECHA reproductive toxicity classifications enforcing sub-0.1% pulegone thresholds that stratify pharmaceutical-grade, organic-certified, and conventional grades. Price differentiation hinges on ECOCERT audit completion and gas chromatography-mass spectrometry verification depth. Cost compression in conventional tiers is intensifying because Chinese synthetic pulegone isomers undercut natural extraction economics. Direct-to-consumer wellness buyers show lowest price sensitivity; industrial fragrance compounders exhibit highest.
Supply Chain Analysis
Atlas Mountains cooperatives in Morocco anchor contract-manufacturing concentration for wildcrafted organic feedstock, with secondary distillation nodes in France and Germany serving pharmaceutical-grade refinement. Mentha pulegium biomass, biomass-powered still infrastructure, and analytical chemist labor pools constitute critical input dependencies. Single-source vulnerability in Moroccan riparian harvesting creates structural exposure to climate-induced yield volatility. Distribution runs through direct-to-consumer botanical platforms and specialty health retailers, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States subscription box retailers and French direct-to-consumer platforms, fragmenting procurement across specification-driven purchasing that demands batch-specific chromatographic disclosures.
For Market Incumbents: Entrench analytical chemist capabilities through captive laboratory investments or exclusive contract laboratory partnerships, as gas chromatography-mass spectrometry expertise scarcity extends batch release timelines. Deepen backward integration into Moroccan cooperative equity stakes to secure 60-70% organic feedstock concentration against climate-driven Portuguese and Spanish stand erosion. For New Entrants and Emerging Players: Build out veterinary parasiticide formulation capabilities targeting equine and livestock applications, exploiting regulatory gaps in animal health product oversight that bypass human pharmaceutical restrictions. Target United States EPA FIFRA compliance pathways for botanical household repellents, the most penetrable segment currently blocked by registration barriers. Deploy near-infrared spectroscopy handheld devices as dockside verification services to cosmetic formulators. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across carbon-negative distillation infrastructure as EU Green Deal import preferences reward biomass-powered still investments. Long-term viability centers on analytical instrumentation providers serving pharmaceutical compliance workflows and cooperative aggregators with certified single-origin supply. Watch for pulegone threshold tightening signals from ECHA and FDA as inflection indicators that would accelerate substitution demand toward spearmint and cornmint oils.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Negative Distillation Certification | Biomass-powered stills in Moroccan cooperatives qualify for EU Green Deal import preferences. |
| Analytical Chemist Talent Acquisition | Gas chromatography-mass spectrometry expertise concentrates in contract laboratories, extending release timelines. |
| EPA FIFRA Registration Compliance | Botanical insecticidal claims open household pest control segments currently dominated by synthetic pyrethroids. |
| Near-Infrared Spectroscopy Deployment | Handheld NIR devices virtualize quality control workflows and compress supplier qualification cycles. |
| Veterinary Parasiticide Formulation Development | Equine and livestock applications exploit regulatory gaps in animal health product oversight. |
Research Methodology
The analysis maps organic-certified, conventional, wildcrafted, and extracted grades, each validated through cooperative distillation operators, cosmetic formulator procurement leads, analytical laboratory directors, and specialty botanical retailers. Primary interviews with these stakeholders combined secondary validation from REACH Annex XVII regulatory filings, ECOCERT audit documentation, FDA DSHEA enforcement records, and United States customs import data. Bottom-up volume triangulation across distillation capacity and top-down value reconciliation against aromatherapy and personal care consumption patterns anchored projections.
Assumptions held ECHA and FDA pulegone thresholds within current classifications while varying Atlas Mountains cooperative capacity expansion rates and synthetic pulegone substitution elasticity across industrial fragrance applications. Segmentation dimensions modeled include product type certification tier, application regulatory pathway, distribution channel customer type, and end-user volume scale across the projection horizon. CAGRs derived from weighted average of historical price-volume trajectories and forward-looking regulatory compression scenarios, with steam distillation efficiency gains and near-infrared spectroscopy adoption curves as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese synthetic pulegone manufacturers or Moroccan cooperative consolidation would shift outcomes. Regulatory threshold tightening, climate-induced Moroccan harvest volatility, and analytical chemist labor pool contraction constitute primary revision risks. Quarterly review of ECHA classification proceedings, FDA warning letter issuance, and Atlas Mountains precipitation indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Citrus Powder Market
Extracts
Aloe Vera Extract Market
Extracts
Clary Sage Oil Market
Extracts
Pearl Extract Market
Extracts
Nootkatone Market
Extracts
Citronella Oil Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Rosa Roxburghii Powder Market
Extracts
Botanical CO2 Extracts Market
Extracts
Floral Extract Market
Extracts
Functional Extract Market
Extracts
Hydroglycolic Extracts Market
Extracts
Sage Extract Market
Extracts
Cajeput Oil Market
Extracts
Hibiscus Flower Powder Market
Extracts
Antioxidants Reagent Market