
 Clary Sage Oil Market | 2026-2036
Clary Sage Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Clary Sage Oil Market Analysis
Pharmaceutical-grade specification upgrades is unwinding across the Clary Sage Oil Market as buyers demand higher linalyl acetate purity thresholds. Givaudan SA leverages captive sourcing from Provence to secure batch consistency for fragrance compounds. dsm-firmenich N.V. anchors its position through backward integration into distillation operations in southeastern Europe. Mountain Rose Herbs differentiates via certified organic supply chains that appeal to clean-label personal care brands.
Clary sage oil is an essential oil steam-distilled from flowering tops of Salvia sclarea L., typically containing 56-78% linalyl acetate and 6-24% linalool, prized in perfumery, aromatherapy, and cosmetic formulations for its fixative and calming properties. Organic Oil commands premium positioning as personal care manufacturers reformulate away from synthetic alternatives, while Aromatherapy Oil competes on traceability narratives and therapeutic-grade certifications. Food & Beverages applications remain nascent due to flavor potency constraints and regulatory dossier requirements, leaving margin pools concentrated in Personal Care and Pharmaceuticals.
EU REACH restricts residual solvent levels in extraction processes, compelling producers to validate supercritical CO2 methods or certified steam-distillation protocols. ISO 9001 and organic certifications under EU regulation 2018/848 govern market access for export-oriented Bulgarian and French distillers. Stakeholders must monitor evolving fragrance allergen labeling rules under the EU Cosmetics Regulation as these determine formulation eligibility across European personal care portfolios.
Market Dynamics
EU REACH solvent restrictions and the EU Green Deal carbon-footprint mandates are compressing conventional hexane extraction economics while rewarding supercritical CO2 and certified steam-distillation investments. Bulgarian and French cultivation clusters now face capital reallocation pressure to maintain EU 2018/848 organic certification access.
Growth Catalysts
- EU Green Deal decarbonization mandates:Distillers adopting biomass-powered stills in Provence and southeastern Bulgaria qualify for green financing and preferential procurement from cosmetics formulators under scope-3 reduction targets.
- Personal care clean-label reformulation:L'Oréal and Unilever tier-one suppliers are expanding organic clary sage oil offtake to replace synthetic linalyl acetate in fragrance compounds and skin-soothing serums.
- Salvia sclarea varietal improvement:French agricultural institutes are deploying marker-assisted selection to boost linalyl acetate content above 75%, tightening batch-to-batch consistency for pharmaceutical-grade buyers.
Market Restraints
- Hexane price volatility and residue compliance:Conventional extractors face margin compression from petrochemical feedstock swings plus ECHA monitoring of residual solvent thresholds in cosmetic-grade output.
- Cultivation concentration in Balkan drought zones:Bulgaria's Rose Valley and sub-Rhodope foothills supply 60% of EU raw material, exposing buyers to climate-induced yield variance without viable secondary sourcing.
- Lavender oil substitution in aromatherapy:Bulgarian and French lavender oils compete on price and familiarity for calming-positioned products, constraining clary sage penetration in mid-tier wellness retail.
Strategic Opportunities
- Underpenetrated German pharmaceutical channel:BfArM monograph alignment for mild sedative indications remains incomplete, creating first-mover advantage for dossier-ready extractors targeting pharmacy distribution.
- Supercritical CO2 extraction convergence with terpene fractionation:Technology pairing enables custom linalyl acetate:linalool ratios for niche perfumery houses seeking signature scent profiles unavailable from conventional distillation.
- Direct-to-brand digital procurement platforms:Traceability-verified bulk sales via blockchain-documented supply chains bypass traditional broker markups for clean-label personal care startups in Scandinavia.
Industry Challenges
- Distillation technician scarcity in rural Bulgaria:Aging workforce and youth migration to Sofia and Plovdiv constrain capacity expansion for organic-certified still operations.
- EU 2018/848 organic conversion timeline:Three-year field transition requirements delay new entrant certification, freezing supply response to price spikes.
- Fragrance allergen labeling complexity:EU Cosmetics Regulation linalool and geraniol disclosure mandates force reformulation costs on brands using non-fractionated oils.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clary Sage Oil Market |
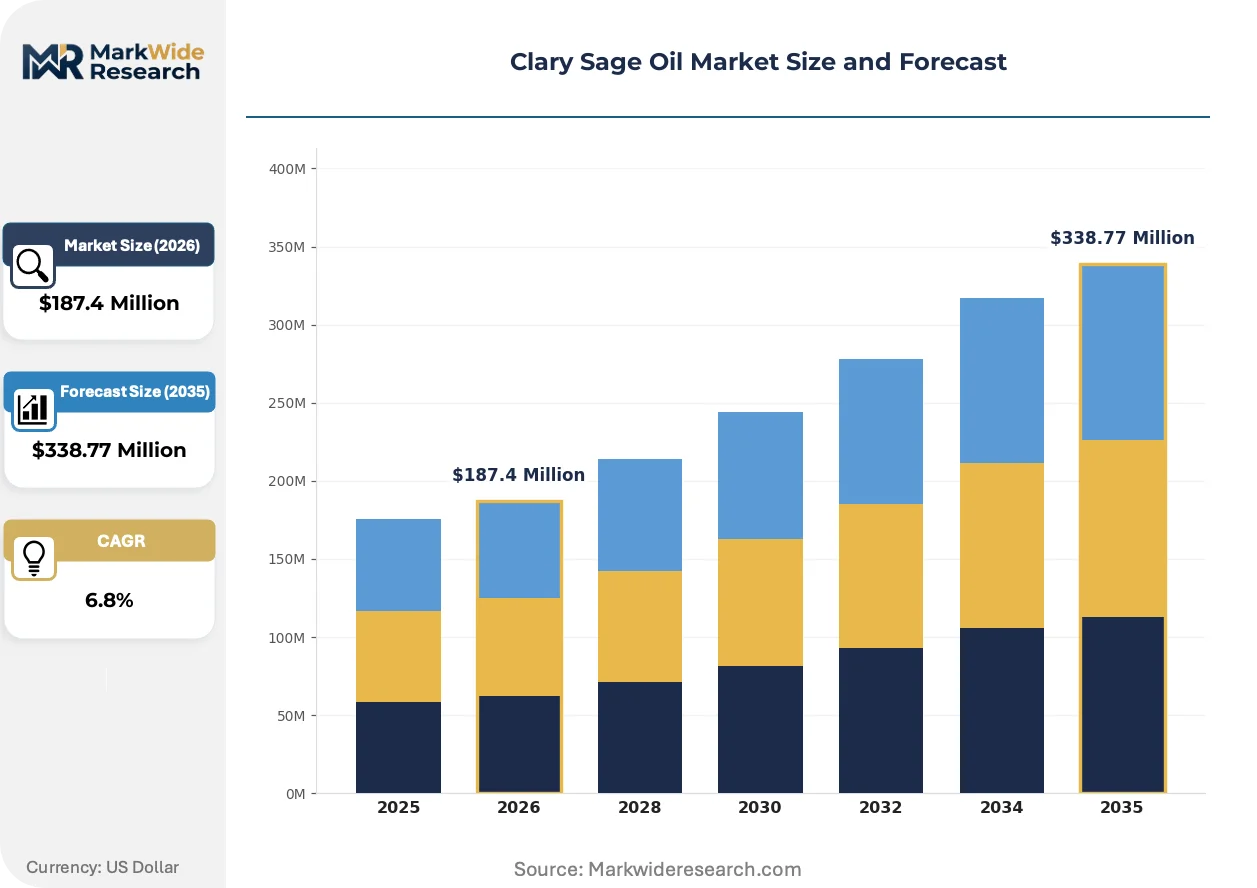
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Oil, Natural Oil, Refined Oil, Aromatherapy Oil Application: Personal Care, Food & Beverages, Pharmaceuticals, Household Products Form: Liquid, Concentrate, Infused Oil, Spray End User: Retail Customers, Manufacturers, Distributors, Wholesalers |
| Companies Covered | International Flavors & Fragrances Inc., Young Living Essential Oils, Givaudan SA, Mountain Rose Herbs, Biolandes, dsm-firmenich N.V., doTERRA International, Plant Therapy, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clary Sage Oil Market Emerging Trajectories
Extraction technology substitution and regulatory chemistry disclosure rules are rewriting competitive advantage in clary sage oil. Distillers must now embed carbon accounting and allergen management into core process design rather than treating compliance as peripheral.
Supercritical CO2 extraction with integrated terpene fractionation is displacing conventional steam distillation in premium fragrance applications. Givaudan and Firmenich captive facilities in Grasse and southeastern Europe are retrofitting CO2 units to deliver custom linalyl acetate concentrations above 78%. This displacement compresses commodity-grade margins while capturing value previously lost to downstream blending houses.
ECHA REACH restriction proposals on fragrance allergens are tightening linalool and geraniol concentration thresholds in leave-on cosmetics. The industrial consequence is forced investment in molecular distillation or selective adsorption to reduce sensitizer content. Personal care formulators in France and Germany are responding by qualifying fractionated oils that maintain scent character while meeting ANSM and BfArM safety guidance.
Clean-label certification is becoming a non-negotiable filter in buyer selection criteria. Indie beauty brands and B-Corp positioned multinationals are bypassing conventional brokers to contract directly with EU 2018/848 certified distillers in Bulgaria and Provence. This disintermediation is most visible in Scandinavian markets where KRAV and Ø-label equivalency requirements reward traceable organic supply chains with retail placement priority.
Clary Sage Oil Market Segmentation
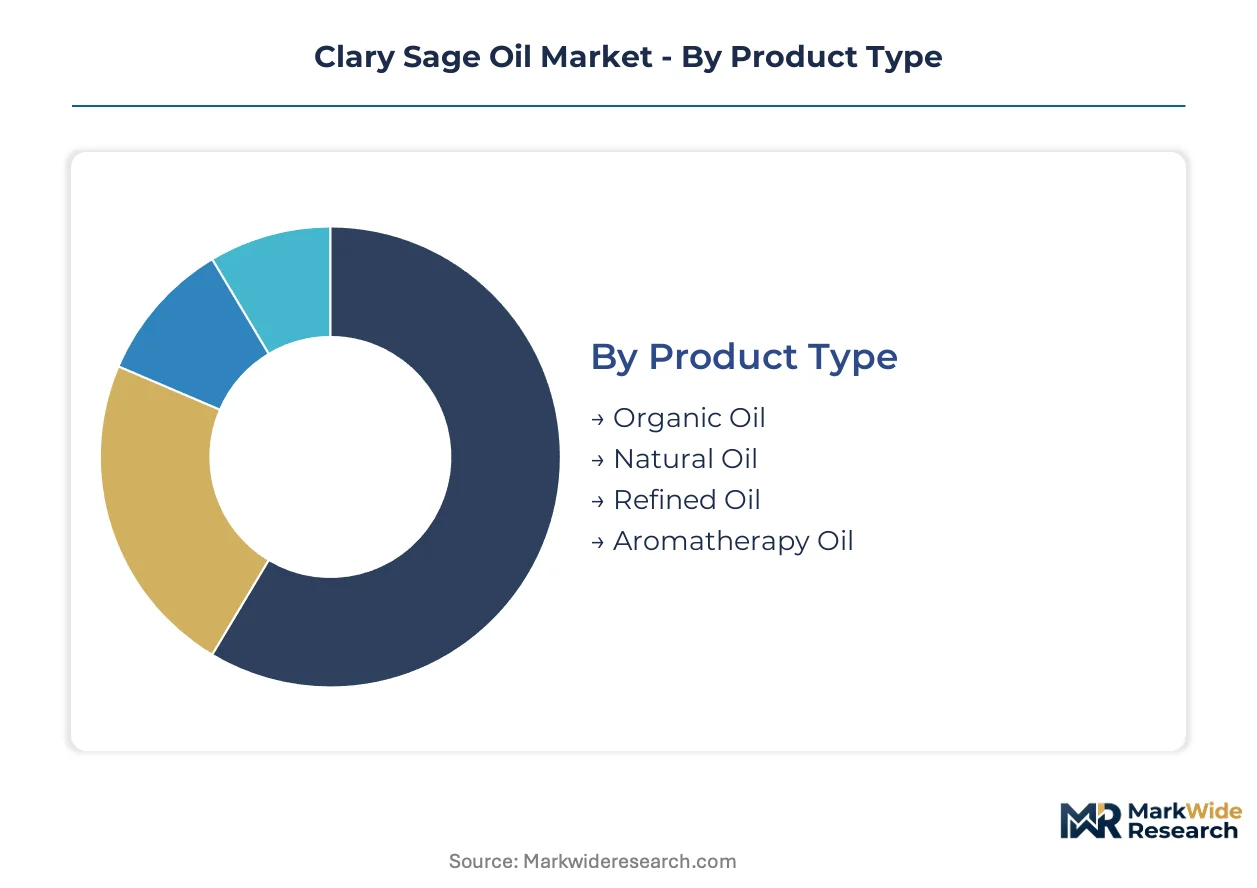
Segmentation in clary sage oil tracks how certification tiers, extraction methods, and buyer sophistication split procurement flows between commodity brokers and direct-to-brand channels. Understanding these divides exposes where margin pools concentrate and where traceability premiums command pricing power.
Product Type:
Domestic absorption of certified grades runs strongest in France and Germany, while Bulgarian distillers export conventional grades through traditional broker networks.
- Organic Oil:EU 2018/848 certification mandates three-year field transition and residue-free extraction protocols. L'Oréal and Unilever tier-one suppliers in France are locking in multi-year offtake agreements to secure batch consistency for clean-label fragrance compounds.
- Aromatherapy Oil:Therapeutic-grade specifications require GC-MS verified linalyl acetate profiles above 60%. Scandinavian wellness retailers are driving demand for blockchain-documented provenance from Provence and Bulgarian Rose Valley distillers.
- Natural Oil:Conventional steam-distilled output without organic certification serves mid-tier personal care formulators.
- Refined Oil:Molecular distillation reduces linalool and geraniol content for EU Cosmetics Regulation allergen compliance.
Organic Oil holds the largest share; momentum sits with Aromatherapy Oil.
Application:
Margin structures diverge sharply between fragrance houses paying certification premiums and food-grade buyers facing dossier barriers.
- Personal Care:Fragrance fixation and skin-soothing serums absorb the majority of high-linalyl acetate output. Givaudan SA and dsm-firmenich N.V. captive facilities in Grasse and southeastern Europe fractionate custom ratios for luxury perfume houses.
- Pharmaceuticals:BfArM monograph alignment for mild sedative indications remains incomplete, leaving pharmacy distribution underdeveloped relative to aromatherapy channels.
- Food & Beverages:Flavor potency constraints and EFSA novel food dossier requirements suppress commercial uptake.
- Household Products:Surface cleaners and fabric refreshers compete on cost with synthetic linalyl acetate alternatives.
Personal Care dominates value capture; Pharmaceuticals present the steepest expansion trajectory pending regulatory clearance.
Form:
Concentrate and infused oil formats concentrate in B2B manufacturing channels, while retail-facing liquid and spray forms require finished-goods regulatory compliance.
- Liquid:Standard bulk delivery for fragrance compound blending and cosmetic manufacturing. Bulgarian distillers ship ISO-tank quantities to German and French formulators under REACH-documented supply chains.
- Concentrate:High-potency extraction for professional aromatherapy practitioners and spa chains.
- Infused Oil:Carrier oil suspensions target indie beauty brands seeking ready-to-bottle formulations.
- Spray:Aerosol and pump formats face additional pressurized container regulations in EU member states.
Liquid commands volume leadership; concentrate formats are climbing fastest on professional channel expansion.
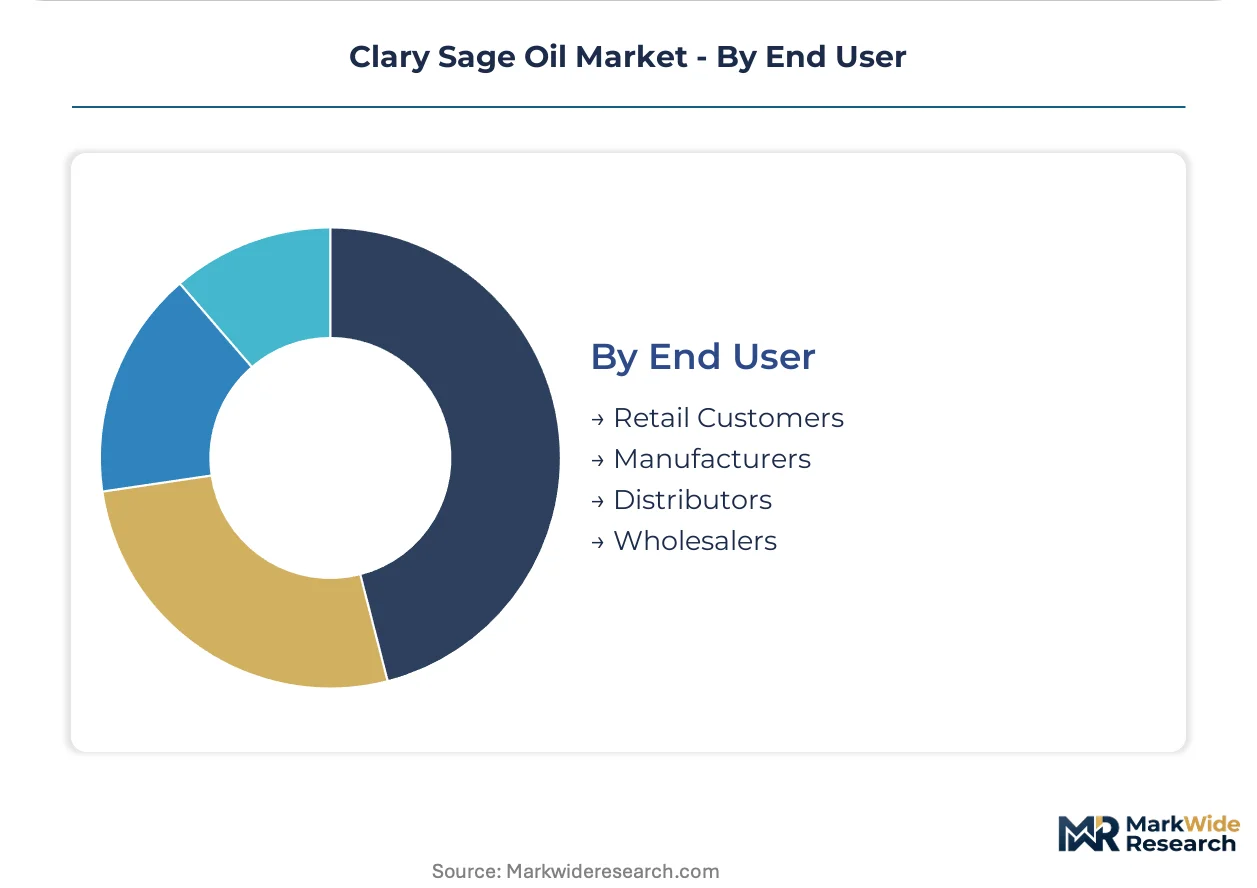
End User:
Manufacturer direct procurement is displacing traditional distributor intermediation as traceability requirements harden.
- Manufacturers:Tier-one personal care and fragrance houses are bypassing brokers to contract directly with EU 2018/848 certified Bulgarian and Provence distillers.
- Retail Customers:Wellness boutiques and e-commerce platforms absorb small-batch organic and aromatherapy grades at premium markups.
- Distributors:Traditional bulk handlers face margin compression as blockchain-verified platforms enable disintermediation.
- Wholesalers:Commodity-grade natural oil aggregation serves mid-tier formulators without certification requirements.
Manufacturers represent the dominant procurement channel; Retail Customers are gaining share fastest on direct-to-brand digital platform growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulgaria exports the majority of raw Salvia sclarea biomass to French and German fragrance houses, creating a trade-flow corridor that concentrates value capture in downstream formulation centers while upstream distillers compete on certification tiers.
France
Provence-based formulators from Givaudan SA and dsm-firmenich N.V. drive demand for high-linalyl acetate grades exceeding 75% purity. ANSM enforces fragrance allergen labeling under EU Cosmetics Regulation, compelling molecular distillation investments. Grasse and the broader Provence-Alpes-Côte d'Azur region host captive distillation facilities retrofitting supercritical CO2 units for custom terpene profiles.
Germany
Personal care manufacturers including L'Oréal and Unilever tier-one suppliers are expanding organic clary sage oil offtake for clean-label serums. BfArM maintains incomplete monograph alignment for mild sedative indications, constraining pharmacy distribution. The Rhine-Ruhr industrial corridor concentrates fragrance compound blending operations sourcing from Bulgarian and French distillers.
Bulgaria
The Rose Valley and sub-Rhodope foothills supply approximately 60% of EU raw material, exposing buyers to climate-induced yield variance. EU 2018/848 organic certification governs market access for export-oriented distillers facing three-year field transition timelines. Kazanlak-based operations confront technician scarcity as youth migration to Sofia and Plovdiv constrains capacity expansion.
United States
Wellness retailers and indie beauty brands absorb small-batch organic and aromatherapy grades at premium markups. FDA oversight of cosmetic ingredient safety interacts with state-level clean-label requirements in California. Direct-to-brand digital procurement platforms enable traceability-verified bulk sales bypassing traditional broker networks.
Italy
Specialty perfumery houses in Milan and Florence seek signature scent profiles through custom linalyl acetate:linalool ratios. REACH compliance documentation from upstream suppliers determines formulation eligibility for export-oriented personal care portfolios. The Lombardy region concentrates niche fragrance compounders competing on terpene fractionation capabilities.
Clary Sage Oil Market Vendor Landscape
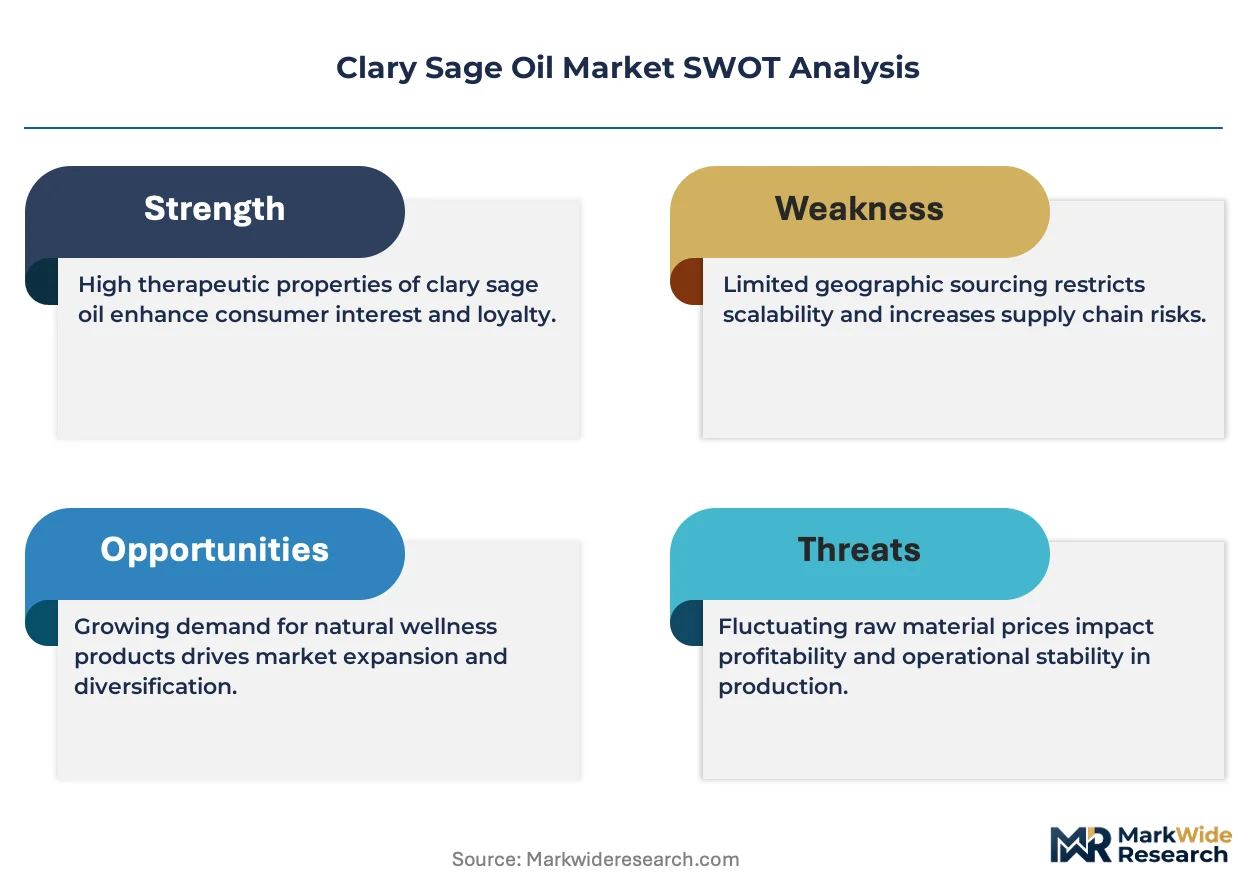
Listed leaders compete with private specialists across certification tiers and extraction technology vectors. The vendor base organizes around three strategic archetypes: integrated fragrance houses with captive sourcing, certified organic specialists serving clean-label personal care, and commodity distillers competing on volume. Capacity expansion and backward integration into cultivation represent the dominant competitive moves as traceability requirements harden.
Among integrated fragrance houses, Givaudan SA and dsm-firmenich N.V. exemplify the captive-sourcing archetype through Provence and southeastern European distillation assets. Mountain Rose Herbs occupies a position within the certified organic tier, appealing to clean-label personal care brands through EU 2018/848 supply chains. These three companies represent contrasting strategic postures: scale-driven vertical control, mid-tier certification specialization, and premium traceability positioning.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Young Living Essential Oils |
| Givaudan SA |
| Mountain Rose Herbs |
| Biolandes |
| dsm-firmenich N.V. |
| doTERRA International |
| Plant Therapy |
| Symrise AG |
| Others |
Supply Flow & Price Mechanics
Sixty-day inventory cycles among French fragrance houses concentrate pricing power with Bulgarian and Provence distillers holding EU 2018/848 organic certification. This lead-time band tightens when Rose Valley harvests underperform, forcing buyers toward premium contract tiers or spot-market exposure.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where linalyl acetate purity thresholds and EU 2018/848 certification status drive price differentiation. Personal care formulators in France and Germany absorb premium markups for organic grades, while mid-tier natural oil buyers exhibit highest price sensitivity. Cost compression in conventional hexane-extracted tiers is intensifying because ECHA residue monitoring raises compliance overhead.
Supply Chain Analysis
Strategic stockpile preferences dominate among German pharmaceutical buyers hedging against Bulgarian drought exposure, while French fragrance houses run leaner just-in-time programs. Raw biomass draws from Bulgaria, France, and limited Moroccan cultivation, with distillation equipment and supercritical CO2 units as critical capital inputs. Single-source vulnerability concentrates in the Rose Valley-Kazanlak corridor. Distribution runs through certified broker networks and emerging blockchain-verified direct platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction convergence with terpene fractionation is reshaping competitive economics, as EU Green Deal carbon-accounting mandates reward low-carbon distillation investments.
For Market Incumbents: Secure batch consistency through captive Salvia sclarea cultivation in southeastern Bulgaria, insulating against climate-induced yield variance that threatens multi-year offtake commitments. Deepen backward integration into biomass preprocessing to capture margin otherwise lost to independent farmers. Prioritize supercritical CO2 retrofitting in Provence facilities ahead of tightening ECHA solvent restrictions. For New Entrants and Emerging Players: Blockchain-documented traceability services represent an underexploited layer where incumbent distillers underinvest in digital infrastructure. Target Scandinavian wellness retailers demanding KRAV-equivalent organic certification with direct-to-brand procurement platforms that bypass traditional broker markups. Lead with fractional distillation capabilities enabling custom linalyl acetate:linalool ratios for niche Italian perfumery houses. For Investors and Strategic Acquirers: Long-term, this sits as a vertical consolidation play because certification barriers and technician scarcity constrain new entrant supply response. Target EU 2018/848-certified Bulgarian distillers with unexploited capacity expansion potential in the sub-Rhodope foothills. Watch BfArM monograph completion for mild sedative indications as the signal triggering pharmaceutical channel repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captures margin from Rose Valley biomass suppliers while securing EU 2018/848 organic certification timelines. |
| Supercritical CO2 Retrofitting | Enables custom terpene fractionation for Givaudan and Firmenich fragrance compounds ahead of REACH solvent restrictions. |
| Blockchain Traceability Platform | Bypasses traditional broker markups for Scandinavian clean-label personal care brands demanding provenance verification. |
| BfArM Dossier Preparation | Positions first-mover advantage for pharmacy distribution pending monograph alignment for mild sedative indications. |
| Technician Training Partnerships | Addresses distillation workforce scarcity in rural Bulgaria constraining organic-certified still capacity expansion. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the clary sage oil value chain, including fragrance compound blenders at Givaudan and Firmenich facilities, procurement leads at L'Oréal and Unilever tier-one suppliers, Bulgarian distillation plant managers, and Scandinavian wellness retail buyers. Secondary validation drew from ECHA REACH documentation, EU 2018/848 organic certification registries, ANSM fragrance allergen guidance, and Bulgarian agricultural ministry harvest statistics. Bottom-up volume modeling triangulated against top-down personal care and pharmaceutical formulation demand estimates.
Across the analysis window, projections segmented by product type (organic, aromatherapy, natural, refined), application (personal care, pharmaceuticals, food and beverages, household products), and end user (manufacturers, retail customers, distributors, wholesalers). CAGRs derived from historical price-volume relationships and elasticity assumptions around clean-label substitution trends. Industry-specific inputs included Salvia sclarea varietal improvement trajectories from French agricultural institutes and EU Green Deal carbon-accounting implementation timelines.
Forecasts assume regulatory continuity in EU REACH, EU 2018/848 organic frameworks, and BfArM monograph processes; material policy shifts would require re-modeling. Climate-induced yield variance in Balkan cultivation zones and ECHA fragrance allergen threshold revisions represent specific risk factors. Revision becomes warranted when linalyl acetate purity premiums compress below supercritical CO2 extraction cost recovery thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Medicinal Plant Extracts Market
Extracts
Orange Oil Market
Extracts
Peppermint Leaf Powder Market
Extracts
Global Marigold Flower Extract Market
Extracts
Kelp Extracts Market
Extracts
Bee Venom Extract Market
Extracts
Rosa Roxburghii Powder Market
Extracts
Organic Herbal Extracts Market
Extracts
Chlorophyll Extract Market
Extracts
Cornflower Extract Market
Extracts
Lemongrass Oil Market
Extracts
Essential Oil Isolates Market
Extracts
Peru Balsam Extract Market
Extracts
Solid Phase Extraction Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Global Azadirachtin Market