
 Pearl Extract Market | 2026-2036
Pearl Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Pearl Extract Market Analytics
Clean beauty consumers are redrawing procurement priorities across the pearl extract supply chain. Shiseido Company, Limited leverages its biotech research infrastructure to develop hydrolyzed pearl peptides for premium skincare. Mikimoto Co., Ltd. anchors its competitive position through captive pearl farming operations in Japan's Mie Prefecture. Croda Inc competes via its specialty ingredient distribution network spanning North American and European cosmetic laboratories.
Pearl extract comprises calcium carbonate, conchiolin protein, and trace minerals derived from nacreous mollusk shells, typically processed through enzymatic hydrolysis or acid dissolution to achieve bioavailable particle sizes below 50 microns for dermal penetration. Powder extract formulations command premium positioning in professional spa and clinic channels where treatment protocols demand measurable active concentration. Liquid extract variants are gaining fastest in nutraceutical applications where beverage fortification requires stable colloidal suspension. Cream form products occupy the largest volume channel through mass-market cosmetic retail, though margin pools concentrate in capsule form dietary supplements targeting mineral deficiency segments.
FDA cosmetic ingredient safety guidelines and EU REACH substance registration requirements shape formulation standards and import documentation burdens for pearl extract suppliers entering Western markets. China's NMPA and GB standards for cosmetic raw materials impose additional testing protocols for heavy metal content and microbial contamination in marine-derived inputs. Stakeholders must monitor evolving biocompatibility certification requirements across multiple jurisdictions to sustain market access without reformulation delays.
Market Dynamics
K-beauty manufacturers are compressing supplier qualification timelines as export orders for pearl extract surge, forcing raw material processors to accelerate enzymatic hydrolysis capacity expansion without sacrificing REACH purity documentation.
Growth Catalysts
- EU REACH substance registration:Tightening purity standards for marine-derived cosmetic ingredients are filtering out marginal suppliers and consolidating procurement among certified processors serving Western skincare brands.
- South Korea export-oriented production:K-beauty manufacturers source premium pearl extract at volume, creating dedicated supply lines that bypass spot-market volatility for high-grade hydrolyzed peptides.
- Enzymatic hydrolysis advancement:Bioavailable particle sizes below 50 microns now achieve consistent dermal penetration, unlocking professional spa and clinic channel positioning for powder extract formulations.
Market Restraints
- Captive pearl farming concentration:Premium nacreous mollusk supply concentrates in Japan's Mie Prefecture, exposing processors to single-origin biological risk and harvest seasonality constraints.
- China NMPA heavy metal testing:Additional GB standards for cosmetic raw materials impose documentation burdens that delay import clearance for marine-derived inputs lacking pre-certified assay records.
- Calcium carbonate substitution:Synthetic mineral complexes and plant-derived brightening agents compete on cost in mass-market cosmetic retail, pressuring pearl extract margin pools at standard grade tiers.
Strategic Opportunities
- Nutraceutical beverage fortification:Liquid extract variants with stable colloidal suspension properties are penetrating functional drink categories previously served by synthetic mineral additives.
- US FDA cosmetic ingredient safety guidelines:Early alignment with evolving safety documentation requirements positions suppliers for priority access as American clean beauty brands reshore ingredient sourcing.
- Capsule form dietary supplements:Mineral deficiency segments offer premium positioning for pearl-derived calcium and trace mineral complexes outside saturated topical cosmetic channels.
Industry Challenges
- Biocompatibility certification timelines:Multiple jurisdiction testing protocols for heavy metal content and microbial contamination extend product launch cycles by 8-14 months.
- Enzymatic hydrolysis specialist scarcity:Formulation chemists with marine protein processing expertise command premium compensation, constraining processor expansion velocity.
- Legacy acid dissolution asset stranding:Conventional processing infrastructure faces obsolescence as enzymatic methods achieve superior bioavailability metrics with lower environmental discharge liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pearl Extract Market |
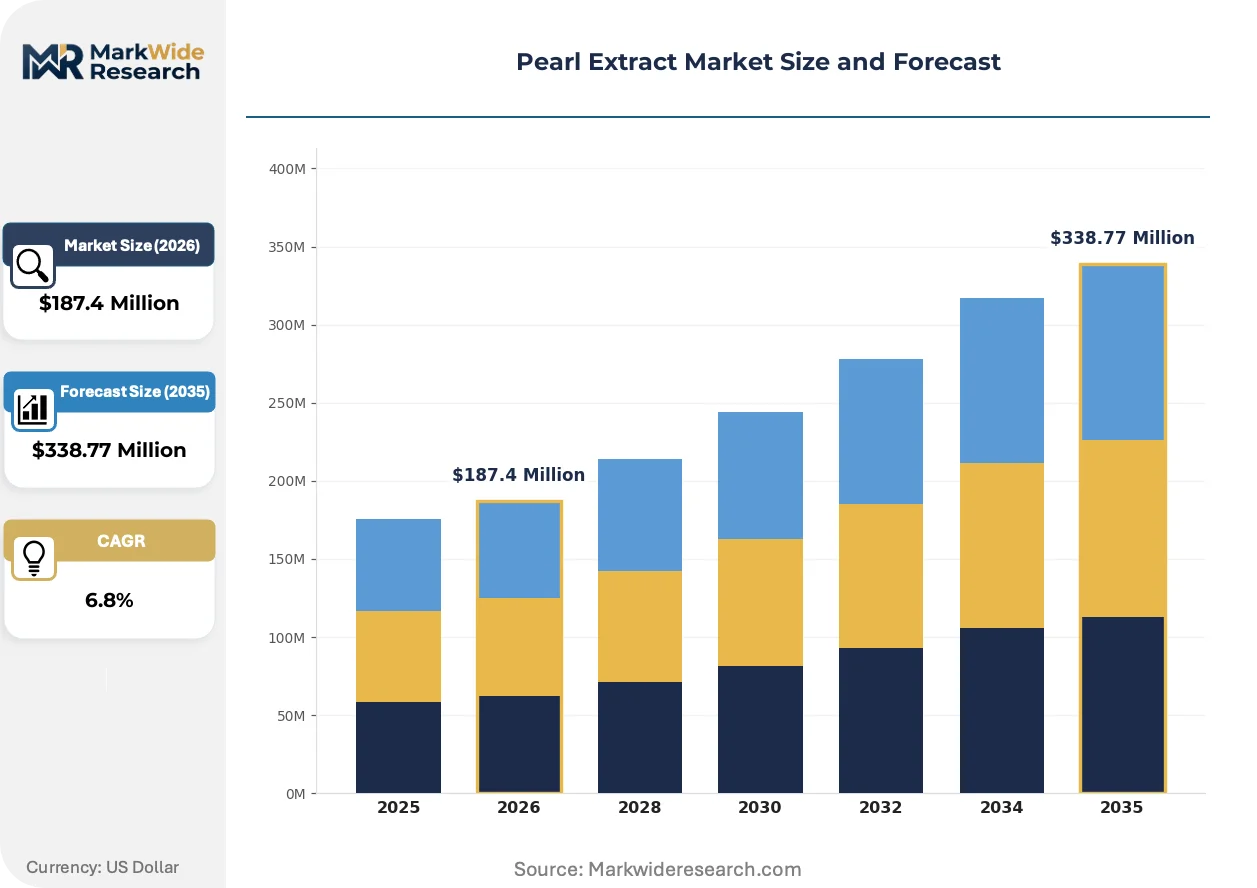
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Capsule Form, Cream Form Application: Skincare, Nutraceuticals, Cosmetics, Dietary Supplements Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Beauty Professionals, Health Enthusiasts, Retail Consumers, Manufacturers |
| Companies Covered | Beiersdorf AG, Croda Inc, Shiseido Company, Limited, Mikimoto Co., Ltd., KANEBO Cosmetics Inc., Longevity Power Inc, Pacifque Sud Ingrédients, Southern Cross Botanicals, Azelis Americas LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pearl Extract Market Evolving Landscape
Biotechnology integration is restructuring competitive advantage in pearl extract processing, with enzymatic methods displacing legacy acid dissolution and bioactive peptide isolation becoming the primary value-capture mechanism.
Enzymatic hydrolysis systems are miniaturizing from industrial batch reactors to modular continuous-flow units that reduce processing time from 48 hours to under 6 hours while improving peptide yield consistency. Mid-sized cosmetic ingredient processors in South Korea and Japan are adopting these systems to serve just-in-time K-beauty production schedules. The technology is miniaturizing minimum efficient scale requirements, enabling regional processors to compete against historically dominant bulk manufacturers without sacrificing REACH documentation quality.
EU REACH substance registration requirements are tightening purity thresholds for conchiolin protein extracts, mandating third-party assay verification for heavy metal content below 0.5 ppm and complete chain-of-custody documentation. This regulatory pressure is accelerating consolidation among European distributors who lack direct relationships with certified pearl farming operations. Professional spa and clinic channels face the steepest compliance cost increases, driving some mid-tier brands to reformulate with lower-specification liquid extracts.
Direct procurement contracts between skincare brands and captive pearl farming operations are displacing traditional spot-market purchasing through specialty chemical distributors. Clean beauty manufacturers with sustainability disclosure commitments now require farm-level traceability documentation that spot intermediaries cannot provide. This pattern concentrates most visibly in South Korea, where export-oriented K-beauty brands have established exclusive supply relationships with Japanese Mie Prefecture farming cooperatives, locking in multi-year volume commitments at fixed peptide concentration specifications.
Pearl Extract Market Segmentation
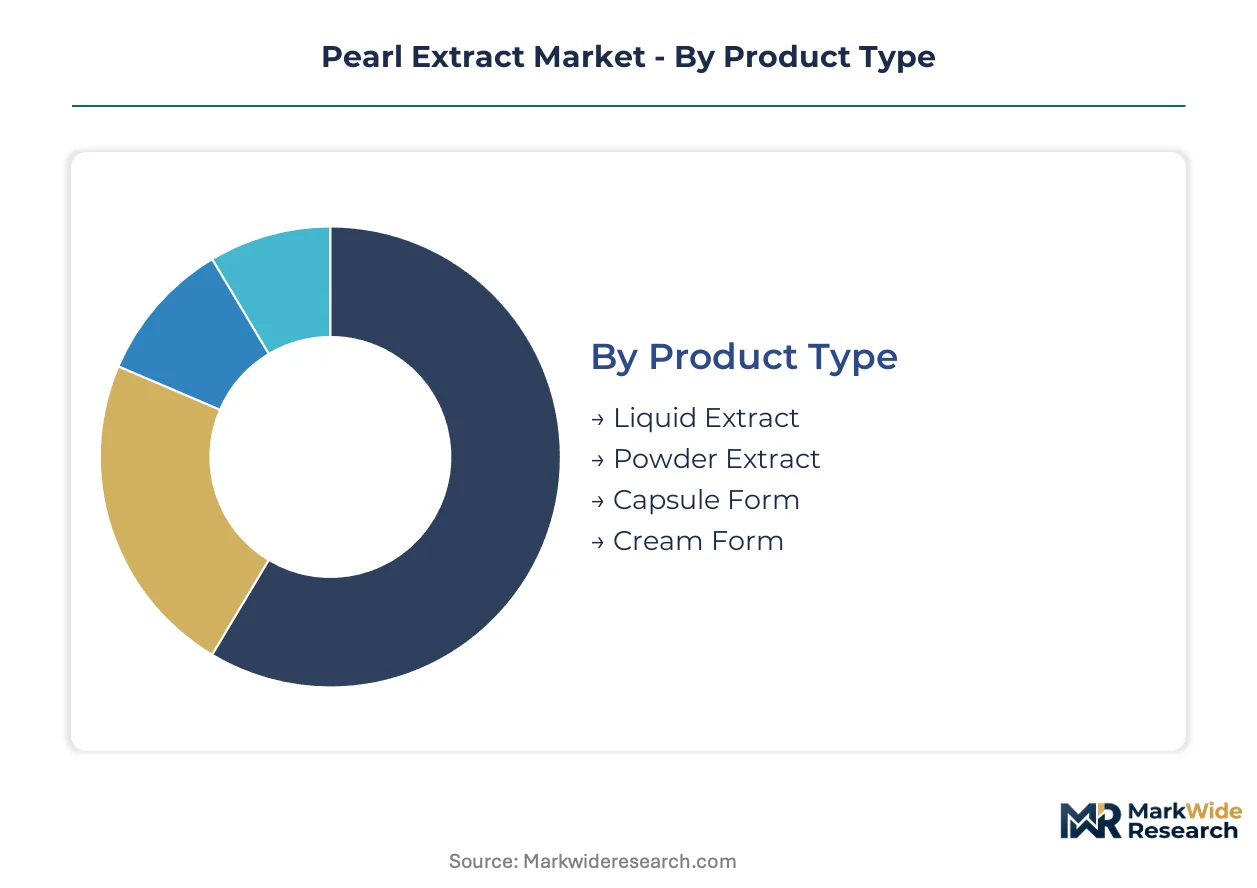
Pearl extract procurement channels diverge sharply by formulation physics and end-use certification requirements. Powder and liquid variants serve distinct professional versus retail pathways, while capsule forms bypass cosmetic regulatory complexity entirely.
Product Type:
Liquid extracts flow predominantly through nutraceutical bottlers and beverage fortification channels, whereas powder concentrates anchor professional spa procurement with measurable peptide specifications.
- Liquid Extract:Stable colloidal suspension properties enable functional drink integration where synthetic mineral additives previously dominated. South Korean beverage manufacturers source this grade for export-oriented beauty-from-within product lines, prioritizing batch consistency over raw material origin.
- Powder Extract:Bioavailable particle sizes below 50 microns achieve dermal penetration thresholds required by clinic-grade treatment protocols. Professional spa channels in Japan and South Korea specify hydrolyzed peptide concentration certificates that liquid variants cannot satisfy.
- Capsule Form:Mineral deficiency segments outside saturated topical channels drive demand for pearl-derived calcium complexes with third-party heavy metal assay documentation.
- Cream Form:Mass-market cosmetic retail absorbs the largest volume tonnage despite margin compression from synthetic brightening agent substitution.
Cream formulations dominate installed base volume. Liquid extract variants are where expansion concentrates most steeply.
Application:
Cost tiers separate medical-grade peptide isolation from commodity mineral fortification, with regulatory documentation burdens determining viable supplier pools.
- Skincare:Anti-aging serums and brightening formulations demand REACH-compliant hydrolyzed peptides with chain-of-custody verification from Japanese Mie Prefecture farming cooperatives.
- Nutraceuticals:Beverage fortification applications in South Korea require stable colloidal suspension properties that enzymatic hydrolysis methods now deliver consistently.
- Cosmetics:Mass-market color cosmetics incorporate pearl extract for optical luminosity where cost thresholds exclude professional-grade peptide specifications.
- Dietary Supplements:Capsule and tablet forms bypass EU Cosmetics Regulation complexity while capturing premium mineral complex positioning.
Skincare commands the premium tier. Nutraceuticals are climbing the fastest as functional beverage categories expand.
Distribution Channel:
Customer type determines channel viability, with professional buyers requiring documentation intermediaries that retail consumers bypass.
- Online Retail:Direct-to-consumer peptide cosmetics concentrate here, though heavy metal certification transparency remains inconsistent across marketplace vendors.
- Specialty Stores:Clean beauty retailers with sustainability disclosure commitments demand farm-level traceability that spot-market distributors cannot provide.
- Supermarkets:Mass-market cream formulations and capsule supplements occupy shelf space where price positioning tolerates lower peptide concentration specifications.
- Direct Sales:Professional spa and clinic channels source powder extracts through exclusive supply relationships with certified processors, locking in multi-year volume commitments.
Direct sales capture the highest margin pool. Online retail is expanding most quickly as K-beauty brands build direct consumer relationships.
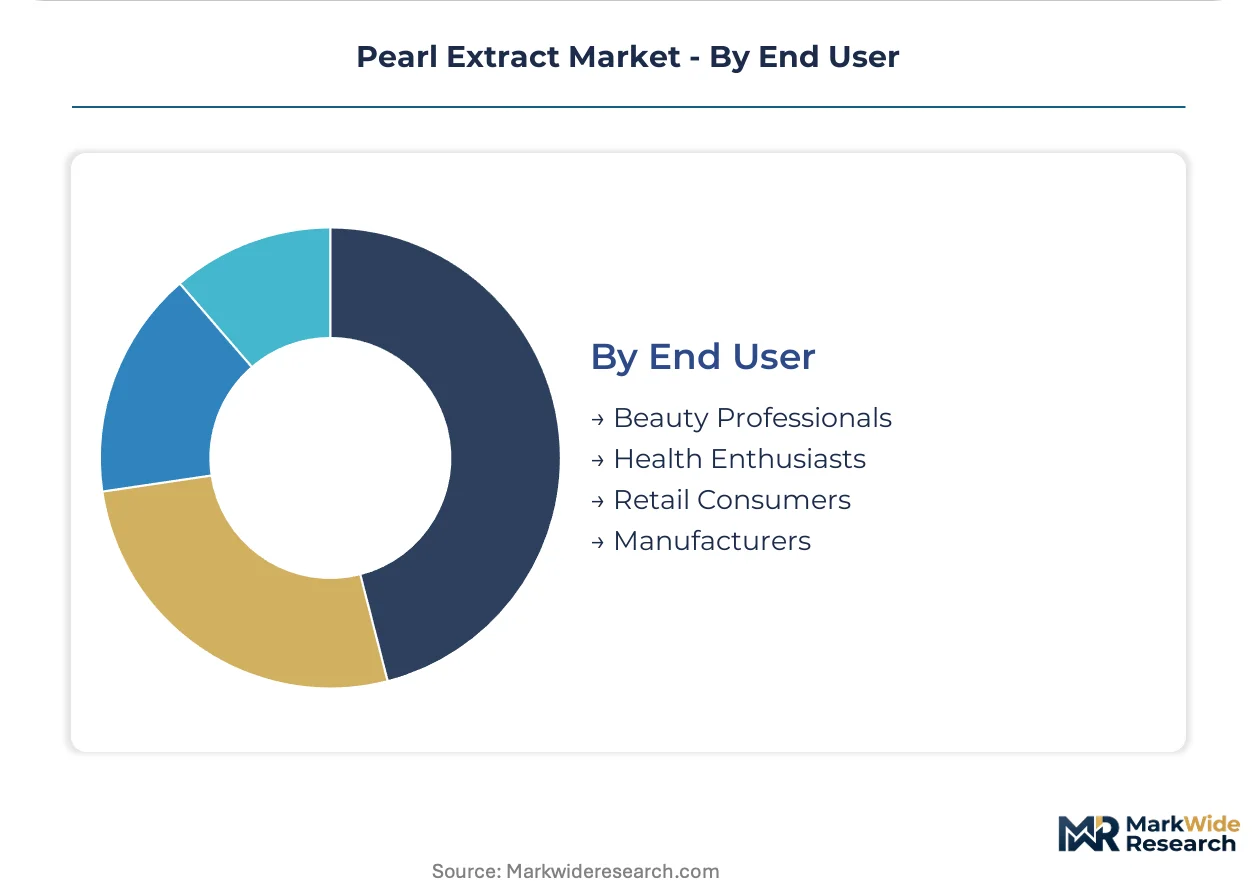
End User:
Procurement sophistication separates institutional buyers with enzymatic hydrolysis expertise from consumers purchasing finished formulations.
- Beauty Professionals:Clinic and spa operators specify bioavailable particle size thresholds below 50 microns, requiring processor relationships with continuous-flow enzymatic systems.
- Health Enthusiasts:Capsule and beverage purchasers prioritize mineral bioavailability claims over peptide cosmetic functionality.
- Retail Consumers:Mass-market cream and serum buyers respond to brightening efficacy marketing without technical specification awareness.
- Manufacturers:K-beauty and clean beauty brands establish captive supply relationships with Japanese farming cooperatives, compressing traditional distributor margins.
Manufacturers control upstream procurement volume. Beauty professionals are gaining share fastest as clinic-grade treatment protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean beauty manufacturers with sustainability disclosure commitments dominate procurement across major demand centers. K-beauty export orders and European REACH compliance documentation shape supplier qualification timelines. Japanese pearl farming cooperatives anchor upstream supply relationships.
South Korea
K-beauty manufacturers source premium pearl extract for export-oriented product lines, compressing traditional distributor margins. MFDS cosmetic ingredient standards govern heavy metal testing protocols for marine-derived inputs. Seoul Capital Area processors operate continuous-flow enzymatic hydrolysis systems to serve just-in-time production schedules.
Japan
Captive pearl farming operations in Mie Prefecture supply hydrolyzed peptide concentrates to professional spa channels. METI industrial standards and PMDA cosmetic safety guidelines shape bioavailability certification requirements. Osaka-based cosmetic ingredient processors maintain exclusive multi-year volume commitments with farming cooperatives.
United States
Clean beauty brands reshore ingredient sourcing as FDA cosmetic ingredient safety guidelines evolve. EPA environmental discharge regulations pressure processors to abandon legacy acid dissolution methods. California-based specialty ingredient distributors build direct relationships with certified Japanese farming operations.
China
Nutraceutical beverage manufacturers absorb liquid extract variants for functional drink fortification. NMPA and GB standards impose additional testing protocols for heavy metal content and microbial contamination. Yangtze River Delta cosmetic raw material processors expand enzymatic hydrolysis capacity to meet domestic skincare demand.
Germany
European skincare brands consolidate procurement among REACH-certified processors serving Western markets. ECHA substance registration requirements mandate third-party assay verification below 0.5 ppm heavy metal thresholds. Bavaria-based specialty chemical distributors face consolidation pressure from direct brand-to-farm procurement contracts.
Pearl Extract Market Competitive Landscape
Player mix skews toward vertically integrated pearl cultivators and specialty ingredient distributors with certified processing capabilities. Three tiers structure competitive positioning: captive farming operations with enzymatic hydrolysis assets, regional processors serving just-in-time K-beauty schedules, and legacy distributors facing margin compression from direct procurement. Dominant competitive moves include backward integration into pearl farming cooperatives and technology licensing for continuous-flow enzymatic systems.
Among Japanese-origin cultivators, Mikimoto Co., Ltd. and Shiseido Company, Limited occupy positions that exemplify the captive supply archetype, anchoring competitive advantage through direct control over Mie Prefecture farming operations. Specialty ingredient distribution networks spanning North American and European cosmetic laboratories represent the intermediary tier, with Croda Inc sitting within this category. These three entities illustrate the structural divergence between upstream biological asset control and downstream formulation channel access.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Croda Inc |
| Shiseido Company, Limited |
| Mikimoto Co., Ltd. |
| KANEBO Cosmetics Inc. |
| Longevity Power Inc |
| Pacifque Sud Ingrédients |
| Southern Cross Botanicals |
| Azelis Americas LLC |
| Others |
Value Network & Pricing Analysis
Continuous-flow enzymatic hydrolysis capacity utilization above 80% in South Korean and Japanese processing facilities concentrates supply-side pricing power among certified operators. Scale thresholds below 500 kilograms per batch strand marginal acid-dissolution processors, compressing margin pools at standard-grade tiers while elevating peptide-concentration premiums for REACH-compliant powder extracts.
Pricing Analysis
Cost-plus contracts with nacreous mollusk biomass indexation dominate procurement between Japanese Mie Prefecture farming cooperatives and K-beauty manufacturers. Three-tier pricing structure across premium hydrolyzed peptides, standard liquid extracts, and economy cream formulations separates professional spa channels from mass-market retail. Pricing pressure intensifies in cream formulations as synthetic calcium carbonate complexes and plant-derived brightening agents capture cost-sensitive supermarket shelf space. Beauty professionals purchasing powder extracts for clinic-grade protocols exhibit lowest price sensitivity, while nutraceutical beverage manufacturers sourcing liquid variants prioritize batch consistency over origin premiums.
Supply Chain Analysis
Just-in-time inventory strategies compress lead times for South Korean K-beauty export schedules, displacing strategic stockpiling historically favored by European distributors. Raw material supply concentrates in Japan's Mie Prefecture captive farming operations, with secondary processing nodes in South Korea's Seoul Capital Area and China's Yangtze River Delta. Enzymatic hydrolysis equipment, conchiolin protein assay certification, and heavy metal pre-testing documentation constitute critical input dependencies. Single-origin biological risk from Japanese pearl harvest seasonality threatens supply continuity. Distribution runs through direct procurement contracts between skincare brands and farming cooperatives, bypassing legacy specialty chemical intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic mineral complex substitution in mass-market brightening formulations threatens pearl extract incumbents with price-based displacement. Defense requires differentiation through bioavailability certification and captive supply control.
For Market Incumbents: Fortify upstream positioning through exclusive multi-year volume commitments with Mie Prefecture farming cooperatives, locking in peptide concentration specifications that synthetic substitutes cannot replicate. Accelerate continuous-flow enzymatic hydrolysis capacity expansion in South Korea to serve compressed K-beauty qualification timelines without sacrificing REACH documentation quality. Certification investment in EU REACH and FDA cosmetic ingredient safety guidelines creates switching costs for brand customers. For New Entrants and Emerging Players: Documentation transparency gaps in online retail peptide cosmetics present service-layer white space for entrants offering third-party heavy metal assay verification and farm-level traceability. Nutraceutical beverage fortification in South Korea represents the most penetrable application segment, with stable colloidal suspension liquid extracts displacing synthetic mineral additives. Go-to-market execution should target direct relationships with functional drink manufacturers seeking clean-label mineral sourcing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with modular continuous-flow enzymatic systems over legacy acid-dissolution asset bases. Long-term viability across the analysis window hinges on backward integration into certified pearl farming operations rather than distributor intermediation. Acquisition targets should demonstrate enzymatic hydrolysis specialist teams and existing REACH compliance documentation. Signal to monitor: MFDS and NMPA regulatory harmonization on marine-derived cosmetic heavy metal thresholds, which would accelerate consolidation among pre-certified processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Pearl Farming | Captive supply from Mie Prefecture cooperatives secures peptide concentration specifications and traceability documentation. |
| Continuous-Flow Enzymatic Hydrolysis Capacity Expansion | Modular systems reduce processing time from 48 hours to under 6 hours while improving yield consistency for K-beauty schedules. |
| EU REACH Substance Registration Alignment | Third-party assay verification below 0.5 ppm heavy metal thresholds filters out marginal competitors in Western markets. |
| Nutraceutical Beverage Fortification Partnership | Stable colloidal suspension liquid extracts penetrate functional drink categories previously served by synthetic mineral additives. |
| Direct-to-Brand Procurement Contracting | Bypassing specialty chemical distributors captures margin compression from sustainability disclosure commitments in clean beauty. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in documented operational reality. Research combined discussions with enzymatic hydrolysis formulation chemists, K-beauty procurement directors, pearl farming cooperative managers, and EU cosmetics regulatory consultants. Secondary sources included ECHA REACH substance registration databases, MFDS cosmetic ingredient safety guidelines, FDA cosmetic ingredient documentation requirements, and Japanese METI industrial standards publications. Bottom-up capacity assessments at continuous-flow processing facilities triangulated against top-down demand estimates from K-beauty export volume tracking.
Sensitivity analysis tested forecast robustness across enzymatic hydrolysis adoption speed, REACH compliance cost pass-through rates, and synthetic substitute pricing scenarios. Segmentation modeling incorporated product type differentiation, application channel requirements, distribution channel documentation burdens, and end-user procurement sophistication tiers. CAGRs derived from volume trajectory analysis weighted by regional regulatory cluster maturity and brand concentration indices. Industry-specific inputs captured enzymatic hydrolysis yield improvement curves and pearl harvest seasonality patterns.
Forecasts assume regulatory continuity in EU REACH, FDA cosmetic ingredient safety, and China NMPA GB standards regimes; material policy shifts would require re-modeling. Specific risks include biocompatibility certification timeline extensions, enzymatic hydrolysis specialist labor scarcity, and calcium carbonate substitution acceleration in mass-market channels. Revision becomes warranted when synthetic mineral complex cost-performance ratios cross thresholds that trigger reformulation decisions by price-sensitive cosmetic manufacturers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Peru Balsam Extract Market
Extracts
Potassium Hydrogen Tartrate Market
Extracts
Nicotinic Acid Market
Extracts
Helichrysum Oil Market
Extracts
Cornflower Extract Market
Extracts
Polygonum Cuspidatum Extract Market
Extracts
Yucca Extract Material Market
Extracts
Basil Extracts Market
Extracts
Gum Turpentine Oil Market
Extracts
Natural Morocco Argan Oil Market
Extracts
Irish Moss Market
Extracts
Pectinase Market
Extracts
Passion Flower Extracts Market
Extracts
Eucommia Extract Market
Extracts
Functional Extract Market
Extracts
Citrus Powder Market