
 Organic Extracts Market | 2026-2036
Organic Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Extracts Market Analytics
Phytochemistry expertise is reorganizing competitive dynamics as specialized extraction knowledge becomes scarcer than production capacity. Givaudan leverages captive botanical sourcing networks across multiple continents to secure rare plant matrices. Symrise AG anchors European supply through Rhône-Alpes extraction facilities serving fragrance and flavor houses. Martin Bauer Group dominates medicinal herb contracts by sustaining deep partnerships with controlled-origin farming cooperatives in Asia and Europe.
Organic extracts comprise concentrated bioactive compounds derived from plant materials through solvent extraction, steam distillation, or supercritical CO2 processing, yielding standardized phytochemical profiles for industrial formulation. Essential oils retain the highest margin pools in fragrance and aromatherapy applications, while herbal extracts command premium positioning in pharmaceutical and nutraceutical channels where standardization to marker compounds determines procurement decisions. Fruit extracts represent the fastest-growing product type as clean-label beverage developers replace synthetic colorants and flavor modifiers with anthocyanin-rich concentrates.
REACH registration requirements in Europe and FDA GRAS self-affirmation pathways in the United States create divergent compliance cost structures that filter market access for smaller extract suppliers. USDA Organic certification and EU organic labeling regulations increasingly determine B2B procurement eligibility rather than serving merely as consumer-facing marketing claims. Stakeholders must monitor evolving maximum residue limits for pesticides in botanical raw materials, as regulatory tightening in major import jurisdictions threatens supply continuity for non-vertically integrated processors.
Market Dynamics
Phytochemistry expertise scarcity is restructuring competitive dynamics as specialized extraction knowledge becomes more valuable than production capacity, forcing contract manufacturers to differentiate through captive botanical networks and certification depth.
Growth Catalysts
- EU Green Deal compliance mandates:REACH registration requirements and EU organic labeling regulations are accelerating procurement of certified organic botanicals by European cosmetic and food formulators seeking supply security.
- Clean-label beverage development:Anthocyanin-rich fruit concentrates are replacing synthetic colorants and flavor modifiers, creating pull-through demand for standardized extract profiles in functional drinks.
- Germany's extraction cluster concentration:Specialized contract manufacturers in Rhineland-Palatinate and Bavaria serve premium skincare brands with integrated phytochemical standardization capabilities.
Market Restraints
- Input cost volatility:Weather-driven botanical raw material availability and pesticide residue testing costs create margin compression for non-vertically integrated processors.
- Regulatory friction:Divergent compliance cost structures between REACH registration in Europe and FDA GRAS self-affirmation in the United States filter market access for smaller extract suppliers.
- Substitution threat:Synthetic biotechnology-derived compounds and fermentation-produced bioactives threaten premium positioning of plant-derived extracts in pharmaceutical applications.
Strategic Opportunities
- Underpenetrated nutraceutical channels:Standardized herbal extracts with marker compound verification remain underdeveloped in preventive health segments across Southeast Asian markets.
- Technology convergence:Integration of supercritical CO2 processing with AI-driven phytochemical fingerprinting enables real-time quality control and batch consistency for pharmaceutical buyers.
- Regulatory tailwind:USDA Organic certification is transitioning from consumer marketing claim to mandatory B2B procurement eligibility criterion in North American premium channels.
Industry Challenges
- Phytochemistry talent scarcity:Specialized extraction technologists and analytical chemists with botanical matrix expertise command premium compensation, constraining mid-tier processor expansion.
- Certification timeline compression:Evolving maximum residue limits for pesticides in major import jurisdictions threaten supply continuity for processors lacking in-house testing infrastructure.
- IP licensing complexity:Traditional knowledge documentation requirements and benefit-sharing protocols for exotic botanicals create legal friction in supply chain origination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Extracts Market |
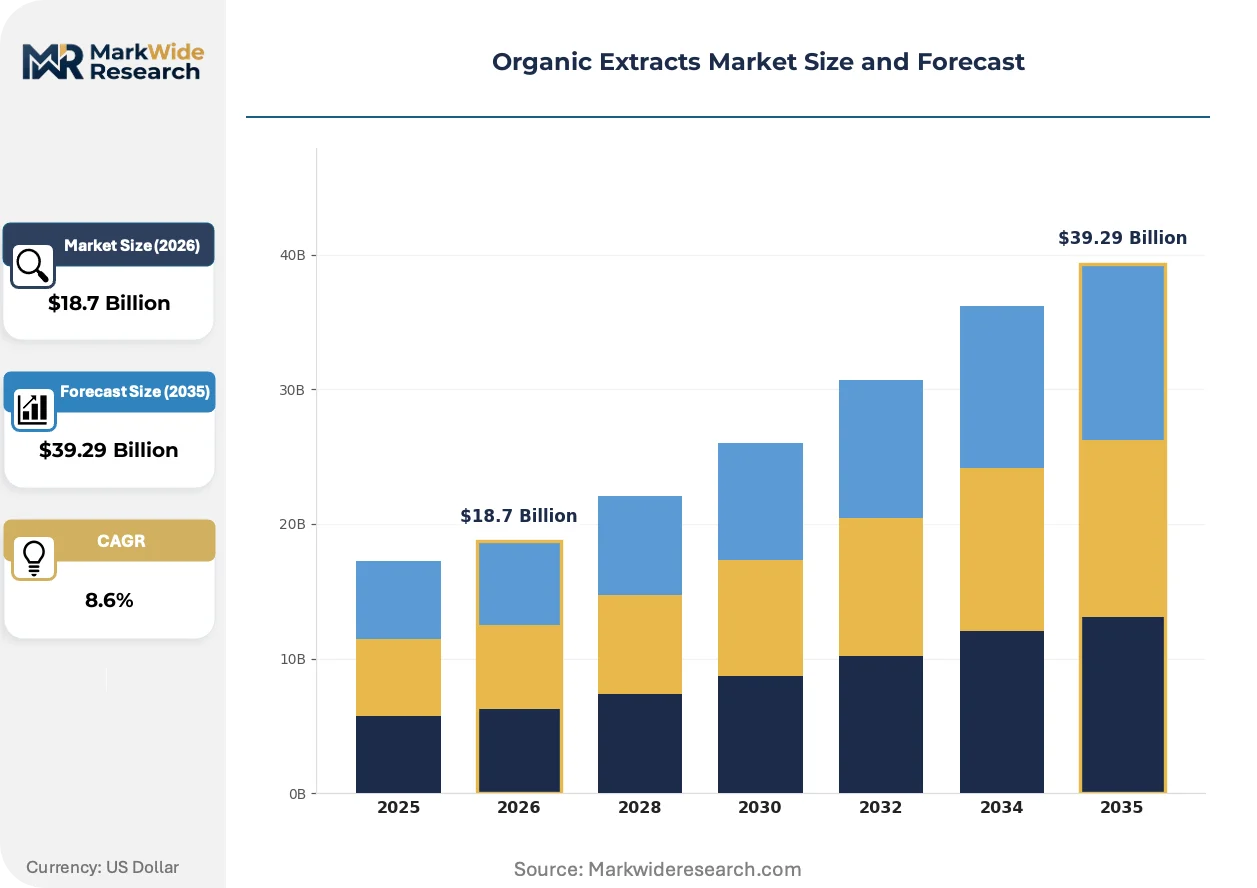
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbal Extracts, Fruit Extracts, Vegetable Extracts Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals End User: Food Manufacturers, Cosmetic Companies, Health Care Providers, Nutraceutical Brands Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Distributors |
| Companies Covered | Givaudan, Symrise AG, International Flavors & Fragrances Inc., Archer Daniels Midland Company, Kerry Group, Martin Bauer Group, Sabinsa Corporation, Kalsec Inc., Naturex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Extracts Market Evolving Landscape
Extraction technology convergence with digital quality assurance is compressing development cycles and redefining supplier-buyer relationships across fragrance, pharmaceutical, and functional food channels.
Supercritical CO2 extraction systems with integrated inline spectroscopic monitoring are displacing conventional solvent-based batch processing in high-value fragrance and pharmaceutical applications. Premium cosmetic formulators in France and Switzerland are adopting these systems to eliminate residual solvent concerns and achieve batch-to-batch consistency. The technology is displacing legacy hexane extraction infrastructure in European facilities serving clean-label markets.
REACH authorization requirements for novel botanical substances are tightening substance safety documentation obligations for extract importers into the European Economic Area. ECHA's evolving guidance on substance identification for complex natural extracts is forcing suppliers to invest in constituent profiling and toxicological data packages. Fragrance houses with legacy botanical libraries face the steepest compliance retrofit costs.
Certification-driven procurement criteria are restructuring buyer-supplier contracting patterns across premium channels. North American clean-label food developers now require USDA Organic and third-party pesticide residue verification as table stakes for supplier qualification, not premium tier differentiators. This behavioral shift is most visible in contract manufacturing agreements for ready-to-drink functional beverages in California and Colorado.
Organic Extracts Market Segmentation
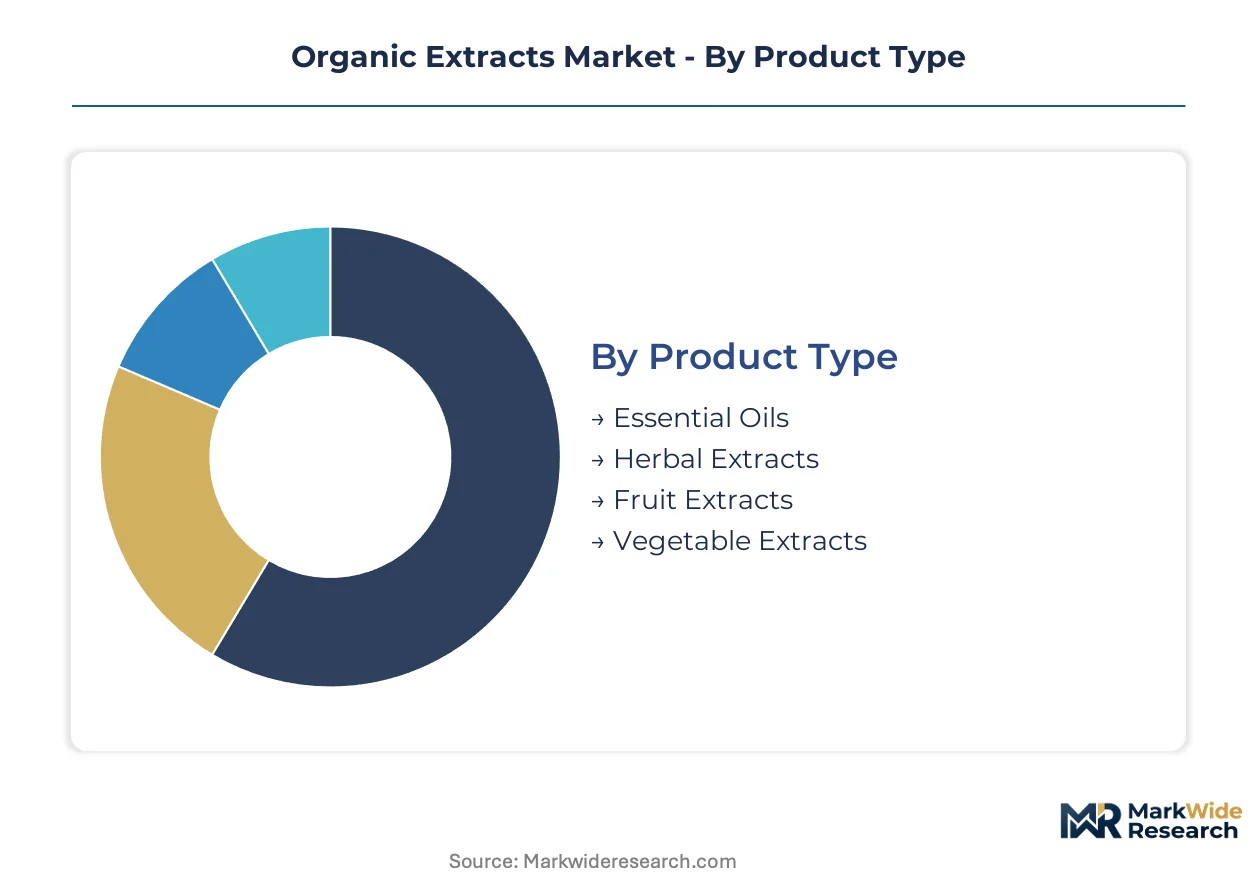
Segmentation in organic extracts reveals how phytochemistry expertise and certification depth concentrate value across distinct supply tiers. Procurement patterns diverge sharply between commodity-grade botanicals and standardized extracts requiring marker compound verification.
Product Type:
Essential oils and herbal extracts dominate export-led demand from European fragrance houses and Asian pharmaceutical formulators, while fruit and vegetable extracts serve more localized clean-label food processing clusters.
- Essential Oils:Volatile aromatic compounds captured through steam distillation or cold pressing, standardized for fragrance load and terpene profile. Demand concentrates in Grasse and Geneva fragrance houses seeking solvent-free extraction guarantees for luxury perfume formulations.
- Herbal Extracts:Concentrated bioactive matrices from medicinal plants, standardized to marker compounds like flavonoids or alkaloids. German pharmaceutical contract manufacturers in Bavaria anchor procurement for EU-compliant nutraceutical applications requiring EMA-aligned documentation.
- Fruit Extracts:Anthocyanin and polyphenol concentrates from berry and citrus matrices.
- Vegetable Extracts:Carotenoid and chlorophyll derivatives from leafy and root vegetables.
Essential oils hold the largest share; momentum sits with fruit extracts.
Application:
Cosmetics and pharmaceuticals command premium extraction standards, while food and nutraceutical applications drive volume scale through less stringent phytochemical specifications.
- Cosmetics:Bioactive compounds for skincare and fragrance requiring REACH-compliant safety dossiers and residue-free certification. French and Swiss formulators in Rhône-Alpes prioritize supercritical CO2 extracts for clean-label positioning.
- Pharmaceuticals:Standardized botanical extracts with verified marker compound content for therapeutic applications. German medicinal herb processors dominate contract supply under EU Traditional Herbal Medicinal Products Directive compliance.
- Food & Beverage:Natural colorants and flavor modifiers replacing synthetic additives.
- Nutraceuticals:Preventive health formulations with functional ingredient claims.
Cosmetics commands the highest margin pool; nutraceuticals show the steepest expansion trajectory.
End User:
Cosmetic companies and nutraceutical brands prioritize certified organic supply chains, while food manufacturers and health care providers emphasize cost-efficient standardization.
- Cosmetic Companies:Premium skincare and fragrance houses requiring batch-to-batch phytochemical consistency. Procurement concentrates in Paris and Milan headquarters with direct contracting to Rhineland-Palatinate extraction facilities.
- Nutraceutical Brands:Preventive health product developers seeking USDA Organic and third-party pesticide verification. California and Colorado functional beverage startups drive demand for anthocyanin-rich fruit concentrates.
- Food Manufacturers:Clean-label processors replacing synthetic additives.
- Health Care Providers:Institutional procurement for traditional medicine applications.
Cosmetic companies anchor premium tier revenue; nutraceutical brands are gaining share fastest.
Distribution Channel:
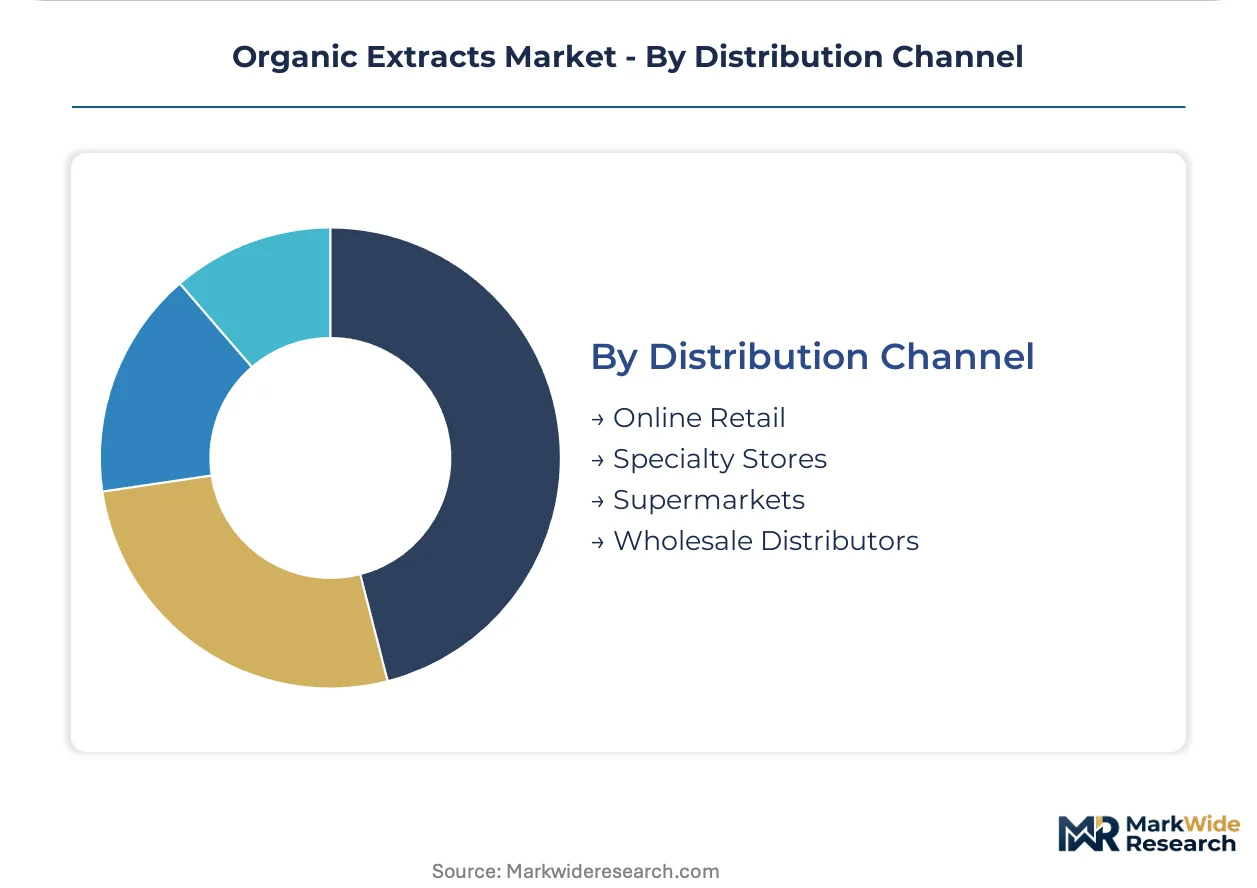
Wholesale distributors and specialty stores handle certified organic extracts requiring documentation chains, while online retail serves small-batch artisanal producers with lower compliance thresholds.
- Wholesale Distributors:Bulk supply to industrial formulators with integrated logistics and certification documentation. German and Dutch hubs dominate European organic extract distribution under EU organic labeling traceability requirements.
- Specialty Stores:Curated selection for artisanal cosmetic and food producers seeking rare botanical matrices. Paris and London retail clusters serve premium fragrance compound buyers with direct importer relationships.
- Online Retail:Direct-to-producer platforms for small-volume procurement.
- Supermarkets:Mass-market channels for commodity-grade extracts.
Wholesale distributors capture the largest volume flow; specialty stores deliver the highest margin realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA anchors European regulatory gravity for organic extracts, with REACH compliance costs filtering supplier access across the continent. Procurement clusters concentrate in Germany's extraction belt and France's fragrance corridor, while North American and Asian markets operate under divergent certification regimes.
Germany
Bavarian medicinal herb processors drive pharmaceutical-grade extract demand under EU Traditional Herbal Medicinal Products Directive compliance. The country's Federal Institute for Drugs and Medical Devices enforces strict marker compound verification for therapeutic applications. Rhineland-Palatinate extraction facilities serve premium skincare brands with integrated phytochemical standardization capabilities.
France
Grasse fragrance houses and Rhône-Alpes cosmetic formulators prioritize supercritical CO2 extracts for clean-label positioning. ANSM oversees cosmetic safety dossiers that exceed baseline EU requirements. Paris headquarters of major beauty brands contract directly to specialized extraction partners for rare botanical matrices.
United States
California and Colorado functional beverage startups pull anthocyanin-rich fruit concentrates for clean-label applications. FDA GRAS self-affirmation pathways create lower compliance barriers than European equivalents, enabling faster ingredient innovation. USDA Organic certification has become mandatory for supplier qualification in premium North American channels.
Switzerland
Swiss fragrance and cosmetic laboratories demand solvent-free extraction guarantees for luxury perfume formulations. Swissmedic alignment with EMA standards ensures pharmaceutical-grade extract acceptance across European markets. Geneva-based fragrance houses anchor high-margin procurement for volatile aromatic compounds.
India
CDSCO-regulated pharmaceutical formulators source standardized herbal extracts for domestic and export markets. The country's agricultural biodiversity supports diverse botanical raw material availability. Controlled-origin farming cooperatives in southern and western states supply medicinal herb matrices to European contract manufacturers.
Organic Extracts Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the organic extracts landscape. The market structures around three tiers: integrated fragrance houses with captive botanical networks, specialized extraction contractors with certification depth, and commodity-grade processors competing on raw material access. Dominant competitive moves include backward integration into controlled-origin farming and technology licensing for supercritical CO2 processing capabilities.
Within the integrated fragrance and flavor tier, Givaudan and Symrise AG exemplify archetypes combining captive botanical sourcing with multi-continental supply networks. Martin Bauer Group occupies a position representing medicinal herb specialists with deep cooperative partnerships across Asian and European growing regions. These three anchors illustrate how phytochemistry expertise scarcity is concentrating value among players with documented supply chain control and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Givaudan |
| Symrise AG |
| International Flavors & Fragrances Inc. |
| Archer Daniels Midland Company |
| Kerry Group |
| Martin Bauer Group |
| Sabinsa Corporation |
| Kalsec Inc. |
| Naturex |
| Others |
Value Network & Pricing Analysis
Anthocyanin-rich fruit concentrates displacing synthetic colorants in California functional beverage formulations are compressing procurement geography toward Rhineland-Palatinate extraction clusters while amplifying price premiums for certified organic supply chains. This substitution dynamic concentrates buyer power among clean-label developers willing to absorb higher per-kilogram costs for residue-free verification.
Pricing Analysis
Price spreads between German supercritical CO2 extracts and Indian solvent-based alternatives exceed threefold for comparable botanical matrices, with certification depth and batch consistency driving the wedge. Pricing stratifies across premium, standard, and economy tiers based on USDA Organic or EU organic labeling status and marker compound standardization. Cost compression in commodity-grade herbal extracts is intensifying because weather-driven raw material volatility and pesticide testing burdens squeeze non-vertically integrated processors. Nutraceutical brands exhibit highest price sensitivity due to thin formulation margins, while Swiss fragrance houses show least sensitivity given luxury positioning.
Supply Chain Analysis
Germany, India, and France anchor organic extract production through distinct specializations: Bavarian pharmaceutical-grade standardization, Indian medicinal herb raw material cultivation, and Grasse fragrance volatile extraction. Supply chains draw from controlled-origin farming cooperatives in southern India, Rhône-Alpes botanical gardens, and Rhineland-Palatinate contract manufacturing facilities. Single-source vulnerability concentrates in rare plant matrices where Givaudan's captive networks dominate procurement. Distribution runs through Dutch and German wholesale hubs serving EU organic labeling traceability requirements before downstream formulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic extract procurement is shifting toward platform-style certification ecosystems where USDA Organic and REACH compliance interoperability determines supplier eligibility rather than transactional spot purchasing.
For Market Incumbents: Consolidate backward integration into controlled-origin farming cooperatives in India and southern Europe to secure rare botanical matrices against fermentation-produced bioactive substitution threats. Deepen captive phytochemistry talent pools through specialized extraction technologist retention programs, as analytical chemistry expertise scarcity constrains mid-tier competitor expansion. For New Entrants and Emerging Players: Contract manufacturing flexibility for small-batch supercritical CO2 processing represents the most penetrable service gap, with California and Colorado functional beverage startups demanding rapid turnaround on anthocyanin-rich fruit concentrates. Target preventive health segments across Southeast Asian markets with marker compound-verified herbal extracts, leveraging FDA GRAS self-affirmation speed advantages over REACH registration timelines. For Investors and Strategic Acquirers: REACH authorization tightening for novel botanical substances reshapes the acquisition landscape toward targets with pre-submitted ECHA toxicological data packages and constituent profiling infrastructure. Long-term viability hinges on regulatory compliance depth rather than production scale alone. Watch ECHA guidance evolution on substance identification for complex natural extracts as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Origin Farming | Secures rare botanical matrices against weather-driven availability shocks and pesticide residue limit tightening. |
| Supercritical CO2 Processing Technology Licensing | Enables solvent-free extraction guarantees for French and Swiss clean-label cosmetic formulators. |
| REACH Registration Pre-Submission | Builds ECHA-compliant safety dossiers before authorization requirements tighten for novel botanical substances. |
| AI-Driven Phytochemical Fingerprinting Integration | Delivers real-time batch consistency for German pharmaceutical contract manufacturers under EMA-aligned documentation. |
| USDA Organic Certification Expansion | Qualifies suppliers for mandatory B2B procurement criteria in North American premium nutraceutical channels. |
Research Methodology
Operator-level perspectives from extraction facility managers, cosmetic formulation chemists, pharmaceutical procurement directors, and organic certification auditors anchored the qualitative base. Primary interviews with Rhineland-Palatinate contract manufacturers and Bavarian medicinal herb processors combined with secondary validation from ECHA substance registration databases, USDA Organic certification records, and EU organic labeling traceability systems. Bottom-up volume triangulation across product type and application segments converged with top-down macroeconomic sanity checks.
Sensitivity analysis stress-tested demand assumptions across regulatory scenario variations and substitution technology penetration rates. The analytical framework modeled segmentation dimensions including extraction technology type, certification tier, end-use industry vertical, and regional regulatory cluster throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for phytochemistry expertise scarcity constraints and clean-label beverage formulation pull-through effects.
Material uncertainties — ECHA guidance evolution on complex natural extract identification, maximum residue limit tightening trajectories, and fermentation-produced bioactive cost curves — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline compression and procurement pattern stickiness. Recalibration cycles align with material shifts in REACH authorization requirements and USDA Organic procurement eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Belladonna Market
Extracts
China Cedar Wood Oil Market
Extracts
Natural Morocco Argan Oil Market
Extracts
Aloe Vera Extract Market
Extracts
Cornflower Extract Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
CO2 Extract Market
Extracts
Yucca Extract Material Market
Extracts
Global Rose Oils Market
Extracts
Labdanum Market
Extracts
Plum Extract Market
Extracts
Global Azadirachtin Market
Extracts
Peru Balsam Extract Market
Extracts
Cassia Extract Market
Extracts
Pearl Extract Market
Extracts
Anise Extract Market