
 Irish Moss Market | 2026-2036
Irish Moss Market Size, Share, and Industry Trends Forecast 2026-2036
Irish Moss Market Foresight
Direct-to-consumer online retail is narrowing as health food stores and specialty shops consolidate shelf space for premium Irish moss SKUs. Emerald Isle Sea Moss leverages its coastal harvesting licenses to sustain supply security along Ireland's western seaboard. Starwest Botanicals competes through bulk distribution dominance in North American botanical supply chains. Ocean Harvest Technology differentiates via controlled-environment cultivation systems that reduce wild-harvest dependency.
Irish moss denotes the red algae Chondrus crispus, harvested from cold North Atlantic waters and dried to preserve its carrageenan content, a sulfated polysaccharide valued for gelling, thickening, and stabilizing properties across food and pharmaceutical applications. The nutraceuticals segment anchors premium pricing as collagen-alternative and gut-health formulations drive gel and capsule uptake, while the food industry segment sustains volume throughput through dairy-alternative and processed meat applications where carrageenan replaces synthetic stabilizers. Powdered Irish moss leads manufacturing efficiency for industrial buyers, though flaked variants occupy artisan and small-batch channels where visual provenance commands margin.
Ireland's Sea Fisheries Protection Agency and the EU's REACH framework govern harvesting quotas and chemical safety disclosures, while the FDA maintains import alert protocols for heavy metal screening that shape transatlantic shipment protocols. BIS certification requirements in India and EFSA novel food assessments in Europe further fragment market access pathways for unprocessed biomass. Stakeholders must monitor evolving marine spatial planning designations that could restrict wild-harvest zones before alternative aquaculture yields achieve commercial scale.
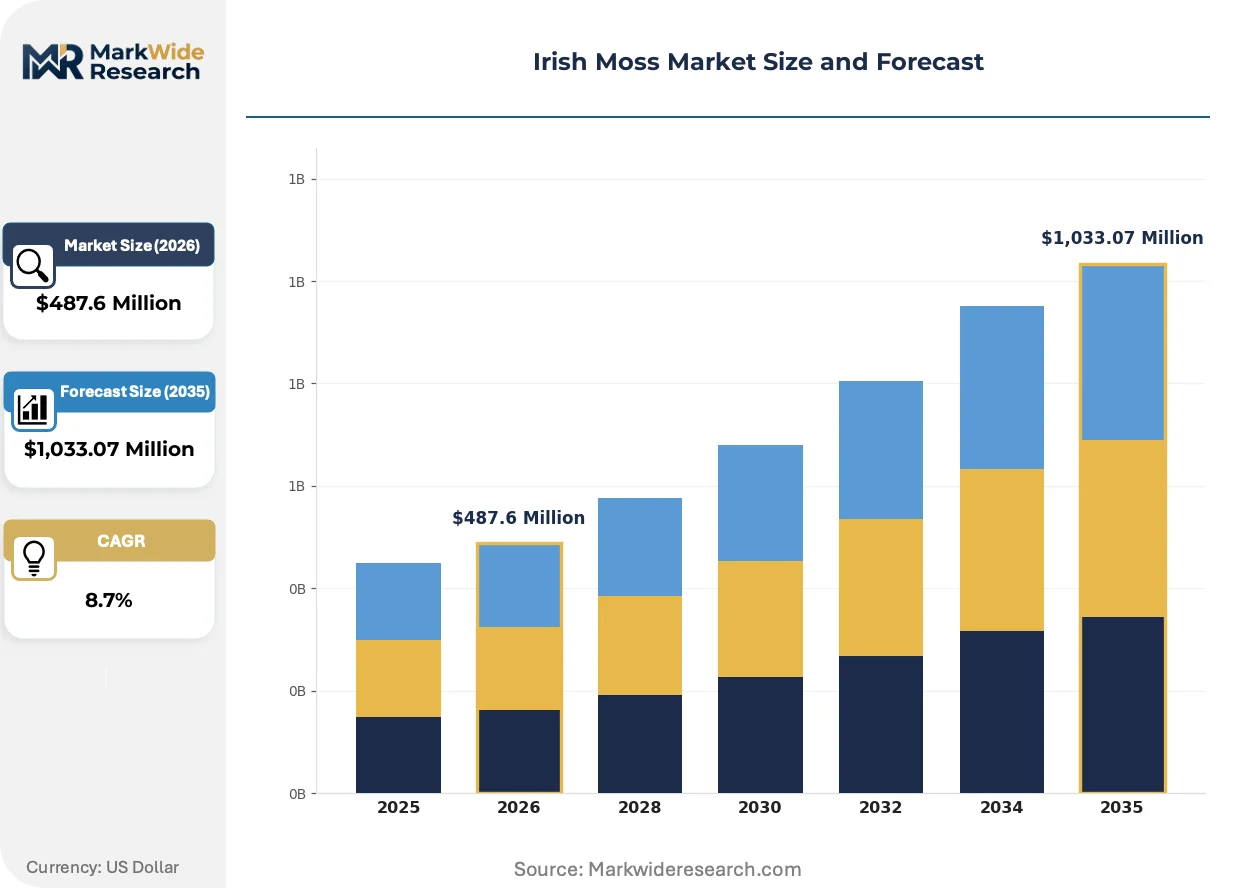
Market Dynamics
The Irish Moss Market operates under tightening marine spatial planning designations that restrict wild-harvest zones along Ireland's western seaboard while aquaculture alternatives remain sub-scale.
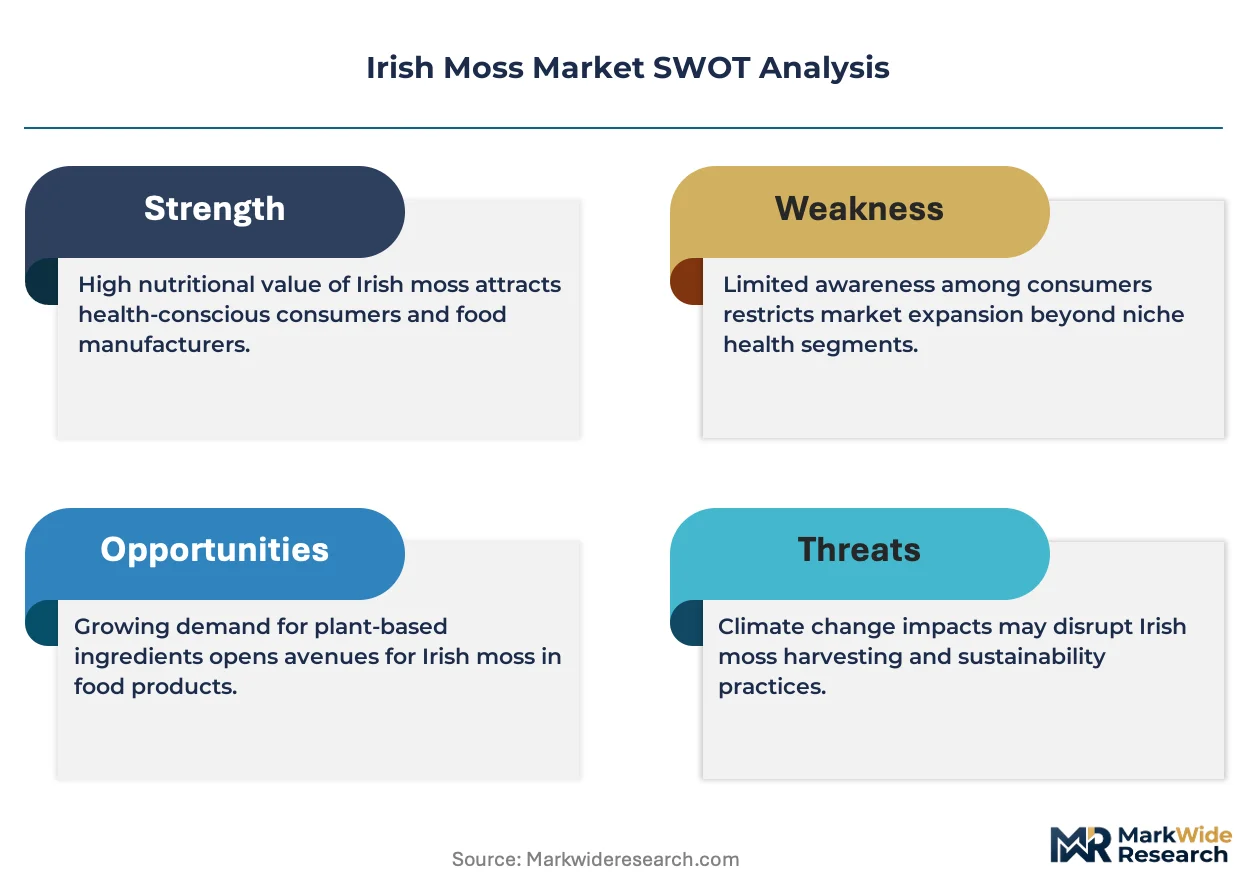
Growth Catalysts
- EU Novel Food Regulation:EFSA novel food assessments create compliance barriers for unprocessed biomass importers, advantaging certified Irish processors who pre-qualify gel and powdered extracts for functional food formulations.
- Nutraceuticals manufacturers:Collagen-alternative and gut-health formulations accelerate procurement of carrageenan-rich gel and capsule formats, anchoring premium pricing tiers.
- North Atlantic harvesting corridor:Cold-water Chondrus crispus stocks from Ireland, Nova Scotia, and Brittany supply superior carrageenan yields compared to tropical alternatives.
Market Restraints
- Wild-harvest quota volatility:Ireland's Sea Fisheries Protection Agency imposes seasonal biomass limits that constrain raw material predictability for processors dependent on coastal licenses.
- Heavy metal screening costs:FDA import alert protocols mandate batch-level testing for arsenic and lead, adding transatlantic shipment friction and working capital requirements.
- Plant-based hydrocolloid substitution:Locust bean gum and guar gum from established agricultural supply chains compete on price stability and volume scalability.
Strategic Opportunities
- Controlled-environment cultivation:Photobioreactor and tank-based systems reduce wild-harvest dependency while satisfying EFSA traceability requirements for novel food status.
- Indian nutraceuticals channel:BIS certification requirements filter out uncertified competitors, creating first-mover advantage for Irish processors meeting dual EU-India standards.
- Specialty retail consolidation:Health food stores and apothecaries in Germany and Netherlands expand shelf space for premium flaked variants with visual provenance claims.
Industry Challenges
- Marine biologist talent scarcity:Cultivation system design and algae strain optimization require specialized phycology expertise concentrated in Cork and Galway research clusters.
- Dual certification timelines:Concurrent EU organic and MSC chain-of-custody audits extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irish Moss Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Irish Moss, Powdered Irish Moss, Gel Irish Moss, Flaked Irish Moss End Use: Food Industry, Cosmetics, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Form: Whole, Extract, Capsules, Tablets |
| Companies Covered | Irish Moss Co., Emerald Isle Sea Moss, Irish Sea Moss, Starwest Botanicals, Ocean Harvest Technology, Sea Moss Ireland, Wild Irish Sea Moss, TrueSeaMoss, Atlantic Sea Moss, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irish Moss Market Shifts & Advancements
Processing technology and regulatory compliance frameworks are compressing supply chain configurations while buyer concentration in nutraceuticals reconfigures procurement patterns.
Photobioreactor cultivation is virtualizing raw material sourcing for Irish moss processors. Tank-based algae production in Cork and Galway facilities eliminates weather-dependent wild-harvest cycles. Nutraceuticals buyers are adopting these supplies for consistent carrageenan potency in collagen-alternative formulations.
REACH framework chemical safety disclosures are tightening raw material traceability across EU supply chains. ECHA registration requirements now cover sulfated polysaccharide derivatives entering food and pharmaceutical channels. Irish processors with pre-submitted dossiers capture formulation partnerships that exclude late-compliance competitors.
Direct purchasing from harvester cooperatives is displacing traditional broker networks in the premium segment. Specialty shops and apothecaries in Germany and Netherlands now contract directly for flaked variants with documented coastal provenance. This channel compression squeezes margin from intermediaries while rewarding processors with captive harvesting licenses.
Irish Moss Market Segmentation
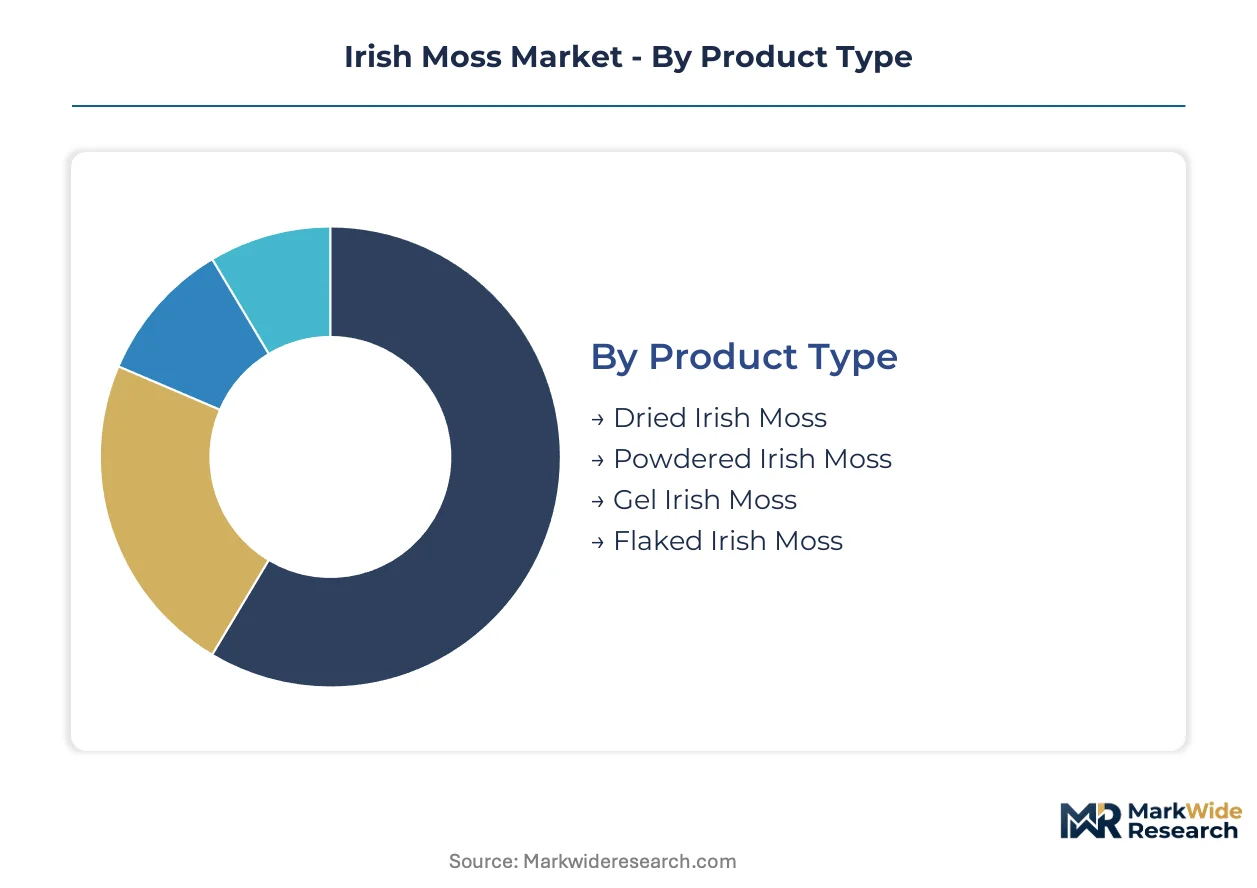
Segmentation in the Irish Moss Market reveals how carrageenan potency, processing intensity, and regulatory compliance requirements stratify buyer procurement patterns across industrial and consumer channels. Each dimension exposes distinct margin structures and supply chain vulnerabilities.
Product Type:
Mature industrial formats dominate volume throughput while emerging value-added preparations capture premium positioning in functional formulations.
- Powdered Irish Moss:Finely milled dried biomass standardized to carrageenan content between 55-75% enables precise dosing in dairy-alternative and processed meat applications. Manufacturing efficiency concentrates procurement among North Atlantic processors supplying industrial hydrocolloid blenders in Germany and the Netherlands.
- Gel Irish Moss:Hydrated and stabilized aqueous extracts deliver ready-to-use functionality for nutraceuticals manufacturers formulating collagen-alternative supplements. Cold-chain logistics and shorter shelf lives restrict sourcing radius to EFSA-certified processors within EU member states.
- Dried Irish Moss:Traditional sun-dried whole thalli preserved in baled format for rehydration by artisan food producers and apothecaries.
- Flaked Irish Moss:Visually distinctive coarse-cut dried material commanding provenance premiums in specialty retail channels.
Powdered Irish Moss retains volume leadership; Gel Irish Moss holds the steepest expansion curve.
End Use:
Application-driven segmentation maps carrageenan functionality against regulatory pathway complexity and reimbursement economics.
- Nutraceuticals:Collagen-alternative and gut-health formulations leverage sulfated polysaccharide bioactivity for premium capsule and gel positioning. EFSA novel food dossiers and BIS certification requirements in India filter competition toward dual-compliant Irish processors.
- Food Industry:Dairy alternatives and processed meats deploy carrageenan for texture stabilization where synthetic stabilizer replacement drives procurement from REACH-registered suppliers.
- Pharmaceuticals:Excipient-grade carrageenan meeting USP-NF monographs for tablet binding and controlled-release matrices.
- Cosmetics:Film-forming and emulsifying properties in topical formulations with emerging clean-label positioning.
Food Industry commands absolute volume; Nutraceuticals delivers the highest value-per-kilogram realization.
Distribution Channel:
Channel segmentation reflects consolidation pressure on intermediaries as provenance documentation becomes a purchasable attribute.
- Health Food Stores:Apothecaries and independent retailers in Germany and the Netherlands consolidate shelf space for flaked variants with coastal harvesting documentation. Direct contracting with Irish harvester cooperatives displaces traditional broker networks.
- Specialty Shops:Premium positioning through visual provenance claims and small-batch narrative supports margin extraction above commodity benchmarks.
- Online Retail:Direct-to-consumer narrowing as platform algorithm changes and fulfillment cost inflation compress unit economics.
- Supermarkets:Mass-market penetration limited by price positioning against locust bean gum and guar gum alternatives.
Health Food Stores anchor premium throughput; Specialty Shops are gaining share fastest in the provenance-attributed segment.
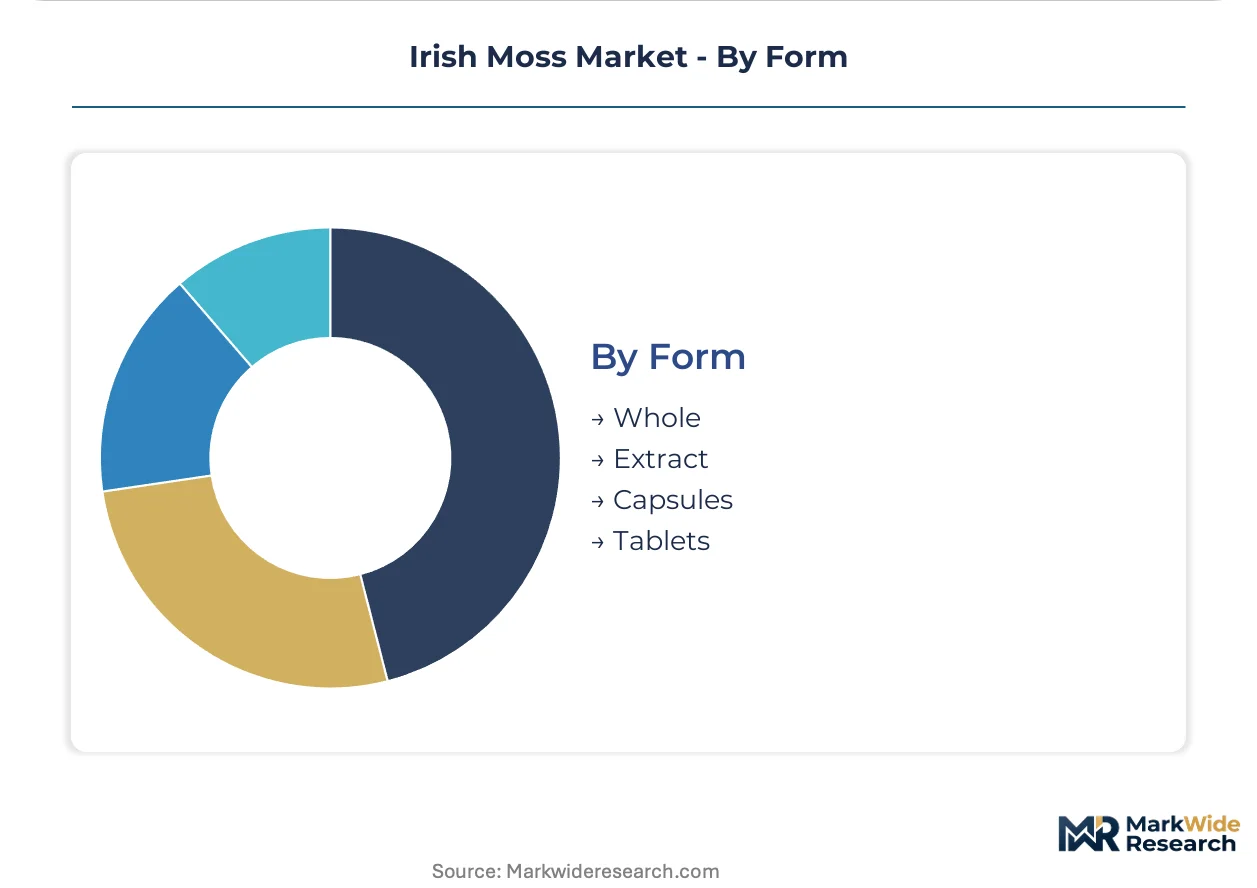
Form:
Physical presentation determines manufacturing integration depth and end-user technical capability requirements.
- Extract:Concentrated carrageenan solutions or powders with defined sulfate content and viscosity profiles for industrial hydrocolloid blending. Standardized specifications enable just-in-time procurement by food technologists.
- Capsules:Pre-measured unit dosing for nutraceuticals brands targeting consumer convenience in gut-health and immune-support positioning.
- Whole:Unprocessed dried thalli requiring end-user rehydration and processing capability.
- Tablets:Compressed formulations combining Irish moss with complementary actives for specific health claims.
Extract maintains manufacturing dominance; Capsules show the most rapid uptake in direct-to-consumer nutraceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments and REACH chemical safety disclosures anchor European demand for certified Irish moss extracts. Harvesting licenses and processing clusters concentrate along cold-water North Atlantic coastlines where carrageenan yields exceed tropical alternatives.
Ireland
Nutraceuticals manufacturers in Cork and Galway drive gel and capsule procurement for collagen-alternative formulations. The Sea Fisheries Protection Agency imposes seasonal biomass limits that constrain raw material predictability for processors dependent on western seaboard licenses. Photobioreactor facilities in County Cork are eliminating weather-dependent wild-harvest cycles through tank-based Chondrus crispus production.
United States
FDA import alert protocols for heavy metal screening shape transatlantic shipment patterns and working capital requirements for Irish exporters. Bulk distribution networks in North American botanical supply chains sustain volume throughput for powdered and flaked variants. Starwest Botanicals anchors procurement relationships with harvester cooperatives seeking REACH-registered supply security.
Germany
Health food stores and apothecaries in Berlin and Hamburg consolidate shelf space for premium flaked SKUs with documented coastal provenance. ECHA registration requirements for sulfated polysaccharide derivatives filter formulation partnerships toward pre-compliant Irish processors. Direct contracting from harvester cooperatives is displacing traditional broker networks in the premium segment.
India
BIS certification requirements for unprocessed biomass imports create compliance barriers that advantage dual EU-India certified processors. Nutraceuticals brands in Mumbai and Bangalore accelerate procurement of carrageenan-rich gut-health formulations. The FSSAI framework governs novel food assessments for algae-derived supplements entering domestic channels.
Canada
Cold-water Chondrus crispus stocks from Nova Scotia supply superior carrageenan yields for North American hydrocolloid blenders. Health Canada and PMRA import protocols align with FDA screening standards for arsenic and lead batch-level testing. Processing clusters in Atlantic provinces are emerging as alternative sourcing nodes to Irish supply corridors.
Irish Moss Market Competitive Landscape
Coastal license holders and controlled-environment cultivators split the market between wild-harvest provenance and supply security. Procurement concentration in nutraceuticals and food industry hydrocolloid blenders rewards processors with dual certification portfolios. Two archetypes dominate: harvester-integrated processors with captive western seaboard licenses, and photobioreactor operators reducing weather dependency through tank-based systems. Competitive moves center on backward integration into harvesting cooperatives and EFSA novel food dossier pre-submission to capture formulation partnerships.
Within the coastal license tier, Emerald Isle Sea Moss and Wild Irish Sea Moss exemplify harvester-integrated positioning through geographic naming that signals Atlantic provenance. Ocean Harvest Technology occupies the controlled-environment archetype, its name indicating cultivation system differentiation. Starwest Botanicals anchors bulk distribution scale in North American supply chains. These three patterns—provenance-signaling, technology-differentiated, and scale-driven—capture the strategic vectors compressing intermediary margins.
| Leading Market Players |
|---|
| Irish Moss Co. |
| Emerald Isle Sea Moss |
| Irish Sea Moss |
| Starwest Botanicals |
| Ocean Harvest Technology |
| Sea Moss Ireland |
| Wild Irish Sea Moss |
| TrueSeaMoss |
| Atlantic Sea Moss |
| Others |
Supply & Pricing Matrix
Undercapacity in Ireland's wild-harvest zones drives processors toward controlled-environment alternatives while tightening pricing power among license holders. Tank-based Chondrus crispus cultivation in County Cork facilities eliminates seasonal biomass volatility that previously forced spot-market purchasing.
Pricing Analysis
Geographic price spreads between Irish gel extracts and Asian carrageenan alternatives compress as EFSA novel food certification creates compliance premiums for EU-sourced material. Three-tier pricing structure across premium certified gel, standard powdered industrial grade, and economy dried whole thalli segments reflects certification intensity and carrageenan potency standardization. Pricing pressure stems from locust bean gum substitution in dairy-alternative applications where cost-sensitive food manufacturers prioritize volume scalability over Atlantic provenance. Industrial hydrocolloid blenders exhibit highest price sensitivity; nutraceuticals brands purchasing collagen-alternative formulations show lowest sensitivity due to reimbursement-adjacent positioning.
Supply Chain Analysis
Tariff exposure between Ireland and post-Brexit UK disrupts traditional cross-border processing flows for dried biomass. Raw material sourcing concentrates in Ireland, Nova Scotia, and Brittany where cold-water Chondrus crispus yields superior sulfated polysaccharide content. Processing depends on wild-harvest licenses from Ireland's Sea Fisheries Protection Agency and seasonal biomass quotas that constrain predictability. Distribution runs through REACH-registered processors supplying industrial hydrocolloid blenders in Germany and the Netherlands, with premium flaked variants bypassing intermediaries through direct harvester cooperative contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among nutraceuticals manufacturers and industrial hydrocolloid blenders who consolidate procurement volumes and demand dual EU-India certification portfolios. This consolidation squeezes margin from processors lacking captive supply or controlled-environment cultivation scale.
For Market Incumbents: Harden supply security through backward integration into western seaboard harvesting cooperatives before marine spatial planning designations restrict wild-harvest zones. Pre-submit EFSA novel food dossiers for gel and powdered extracts to lock out late-compliance competitors from formulation partnerships with German nutraceuticals brands. Cultivation system R&D in Cork and Galway research clusters addresses marine biologist talent scarcity that constrains photobioreactor scale-up.
For New Entrants and Emerging Players: Build out controlled-environment cultivation capacity in Atlantic Canada or Brittany to bypass Ireland's seasonal quota volatility and establish alternative North Atlantic supply nodes. Target Indian nutraceuticals channels where BIS certification requirements filter competition toward dual EU-India compliant processors. Position through direct contracting with Mumbai and Bangalore gut-health formulation brands seeking carrageenan-rich supply with documented traceability.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with captive western seaboard licenses and pre-qualified EFSA novel food status serving nutraceuticals manufacturers. Long-term viability over the next decade hinges on aquaculture yield scalability displacing weather-dependent wild-harvest cycles. Acquisition targets should demonstrate photobioreactor operational experience or established direct retail relationships with German health food stores and apothecaries. Watch for marine spatial planning designation announcements that would abruptly devalue wild-harvest dependent assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvester Cooperatives | Captive supply secures western seaboard licenses against marine spatial planning restrictions. |
| EFSA Novel Food Dossier Pre-Submission | Pre-qualified status captures formulation partnerships that exclude late-compliance competitors. |
| Photobioreactor Cultivation Scale-Up | Tank-based systems in Cork facilities eliminate weather-dependent harvest cycles for nutraceuticals buyers. |
| Dual EU-India Certification Investment | BIS compliance unlocks Mumbai and Bangalore nutraceuticals channels filtering uncertified biomass. |
| Direct-to-Retailer Channel Compression | Bypassing broker networks captures margin from German apothecaries seeking coastal provenance documentation. |
Research Methodology
Desk research of EU regulatory filings, customs trade databases, and marine spatial planning documents preceded structured interviews with harvester cooperative managers, nutraceuticals procurement directors, hydrocolloid blenders in Germany and the Netherlands, and phycology researchers at Cork and Galway facilities. Primary fieldwork with Sea Fisheries Protection Agency officials and EFSA novel food assessment teams validated secondary data on quota volatility and certification timelines. Bottom-up triangulation across processing facility capacity estimates and top-down reconciliation against end-use demand in collagen-alternative formulations anchored volume projections.
Assumptions held fixed include EFSA novel food assessment timelines, REACH chemical safety disclosure requirements, and FDA import alert protocols for heavy metal screening; variables tested include marine spatial planning designation timing, photobioreactor yield achievement rates, and BIS certification pathway efficiency across the analysis window. Segmentation modeling incorporated product type, end-use application, distribution channel, and physical form dimensions with industry-specific weighting for carrageenan potency standardization. CAGRs derived from regression against historical nutraceuticals procurement patterns and food industry hydrocolloid substitution rates, with sensitivity analysis on aquaculture yield scalability.
The forecast holds incumbent behavior within observed patterns; aggressive moves by photobioreactor operators or harvester cooperative consolidation would shift outcomes. Macroeconomic deviation in plant-based hydrocolloid feedstock costs, regulatory acceleration in marine spatial planning, or breakthrough cultivation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Saffron Extract Market
Extracts
Copaiba Essential Oil Market
Extracts
Solid Phase Extraction Market
Extracts
Tagetes Oil Market
Extracts
Lemon Balm Extract Market
Extracts
Flower Extract Market
Extracts
Lotus Extract Market
Extracts
Cochineal Extract Market
Extracts
Histidine Market
Extracts
Hydroglycolic Extracts Market
Extracts
Pectinase Market
Extracts
Global Pine-Derived Chemicals Market
Extracts
Botanicals Market
Extracts
Global Aphrodisiac Powder Market
Extracts
Marigold Essential Oil Market