
 Lavender Oil Market | 2026-2036
Lavender Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Lavender Oil Market Outlook
Asset-light contract farming and distillation leasing is rewriting competitive entry barriers for lavender oil producers. Mountain Rose Herb leverages direct relationships with organic growers across the Pacific Northwest to secure traceable supply chains. The Body Shop anchors its global sourcing through co-investment models with Bulgarian farming cooperatives. Aura Cacia differentiates via vertical control over steam distillation capacity in select Mediterranean zones.
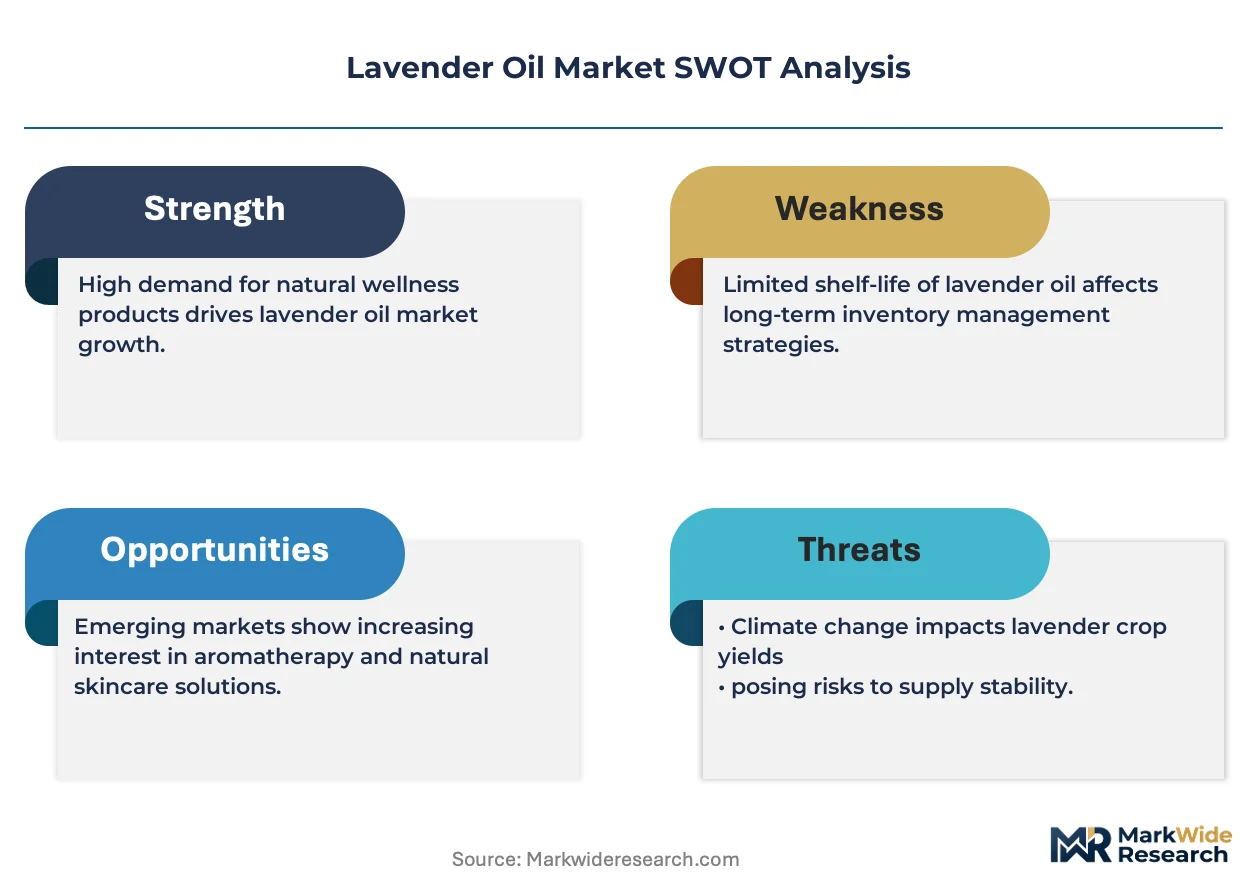
Lavender oil is a volatile essential oil extracted primarily from Lavandula angustifolia flowers through steam distillation, containing linalool and linalyl acetate as dominant active compounds that confer antimicrobial, anti-inflammatory, and calming properties for therapeutic and cosmetic applications. Pure Oil commands premium positioning in clinical aromatherapy and high-end cosmetic formulations where standardization matters. Essential Oil Blends compete on convenience and dosage consistency for home users and spa operators. The Personal Care application segment sustains the deepest margin pools as brands integrate lavender oil into premium skincare and haircare lines at concentration levels that justify price premiums.
EU REACH and ECHA guidelines govern chemical safety documentation for lavender oil sold across European cosmetic and home care supply chains. FDA regulations in the United States distinguish between lavender oil marketed as a cosmetic ingredient versus structure-function claims that trigger drug oversight. Organic certifications from USDA and EU bodies shape demand by constraining allowable pesticide residues and distillation methods. Stakeholders must monitor how evolving fragrance allergen labeling rules across multiple jurisdictions reshape formulation strategies and consumer communication.
Market Dynamics
EU REACH compliance and organic certification requirements are elevating quality thresholds for imported oils, forcing producers to restructure distillation methods and documentation protocols across Mediterranean and Pacific Northwest supply clusters.
Growth Catalysts
- EU REACH chemical safety documentation:Mandatory registration under ECHA guidelines creates competitive moats for compliant producers, squeezing informal suppliers from European cosmetic supply chains.
- Aromatherapy portfolio expansion:Personal care brands are prioritizing natural wellness solutions, pulling lavender oil into premium skincare and home fragrance formulations at higher concentration levels.
- Cultivation cluster maturation:Processing infrastructure consolidation in France, Bulgaria, and China is shortening harvest-to-distillation windows and improving linalool yield consistency.
Market Restraints
- Climate volatility in Provence and Balkan highlands:Erratic precipitation patterns and temperature spikes threaten Lavandula angustifolia flowering cycles, compressing reliable harvest windows.
- Synthetic linalool substitution:Petrochemical-derived fragrance compounds from BASF and Givaudan laboratories undercut natural oil pricing in mass-market personal care applications.
- Organic certification timelines:USDA and EU organic transition periods spanning 36 months lock conventional growers out of premium pricing tiers during conversion.
Strategic Opportunities
- Clinical aromatherapy standardization:Pharmacopeial-grade lavender oil for hospital and wellness clinic protocols commands 3-4x cosmetic-grade pricing with tighter specification tolerances.
- Carbon-neutral distillation:Biomass-fired stills and solar thermal capture align with EU Green Deal incentives, opening preferential procurement channels with sustainability-mandated buyers.
- Direct-to-practitioner e-commerce:Aromatherapists and spa formulators are bypassing traditional distributors, creating margin capture opportunities for traceable-origin producers.
Industry Challenges
- Gas chromatography-mass spectrometry analytical capacity:Batch-to-batch linalool and linalyl acetate verification requires capital-intensive equipment that small-scale distillers struggle to finance.
- Fragrance allergen labeling complexity:Evolving IFRA and EU Cosmetics Regulation disclosure rules force reformulation and relabeling cycles that fragment inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lavender Oil Market |
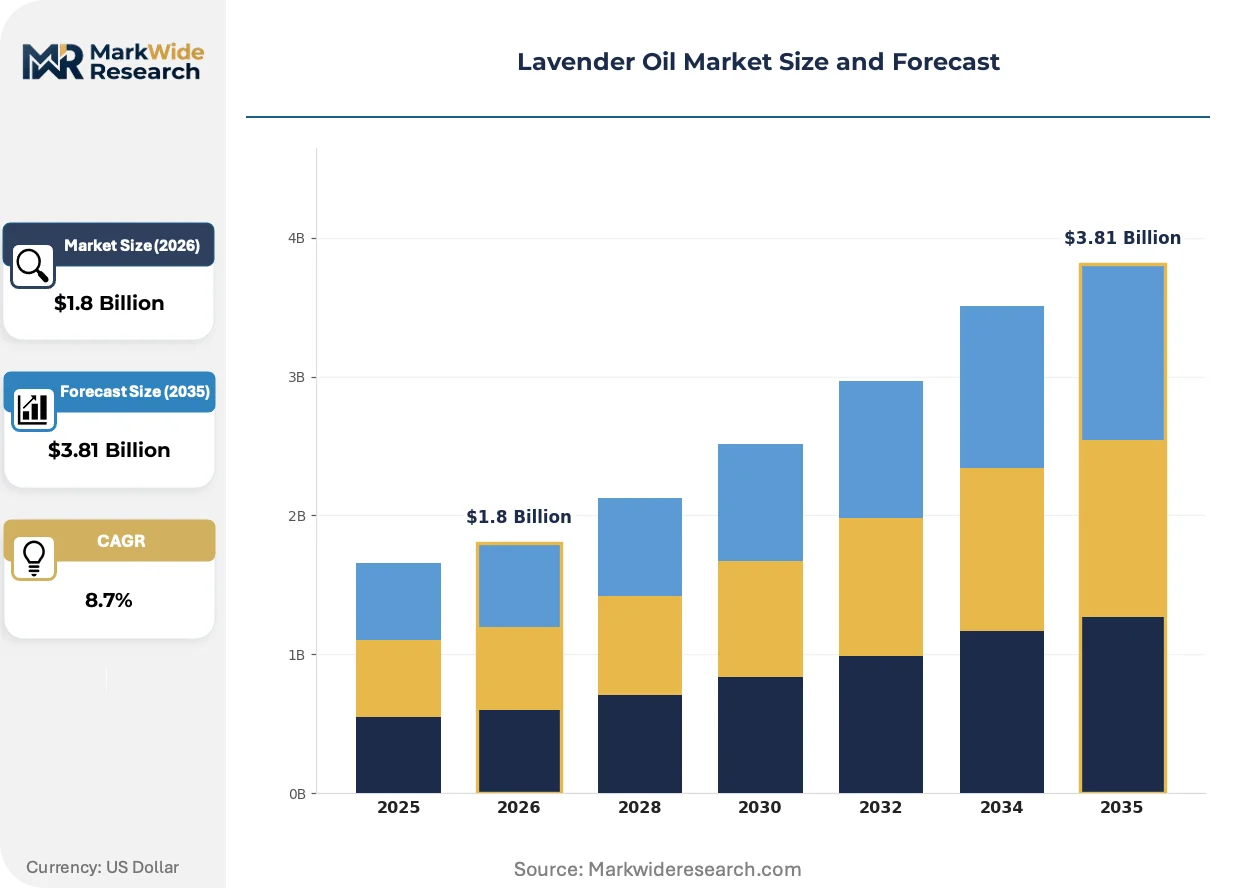
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Oil, Essential Oil Blends, Fragrance Oils, Aromatherapy Products Application: Cosmetics, Food & Beverage, Home Care, Personal Care Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies End User: Home Users, Spa & Wellness Centers, Cosmetic Manufacturers, Food Industry |
| Companies Covered | Camenae, Pretty Valley, Frei, Mountain Rose Herb, The Body Shop, AFU, NextBox, Aura Cacia, AA Skincare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lavender Oil Market Strategic Shifts
Steam distillation is yielding to precision-controlled extraction methods, while regulatory disclosure mandates and practitioner-direct procurement are compressing traditional supply chain intermediaries.
Supercritical CO2 extraction technology is digitizing batch control parameters for linalool recovery optimization. Premium cosmetic formulators in France and Switzerland are adopting these systems to achieve sub-ppm solvent residue specifications. This precision is digitizing quality assurance workflows, compressing analytical turnaround from weeks to hours and enabling real-time release decisions.
EU fragrance allergen labeling rules under the Cosmetics Regulation are mandating individual component disclosure for 26 sensitizing substances including linalool oxidation products. Cosmetic manufacturers are responding by reformulating with lower-linalool lavender fractions or encapsulation technologies. The personal care segment is absorbing the highest compliance burden, with indie beauty brands facing disproportionate documentation costs relative to multinational portfolios.
Practitioner buyers are consolidating purchasing through specialized aromatherapy supply cooperatives, displacing traditional essential oil brokers. These cooperatives aggregate volume from 50-200 clinical aromatherapists and spa formulators, negotiating direct contracts with Bulgarian and French distillers. The shift is most pronounced in Germany and the United Kingdom, where professional association membership correlates with cooperative enrollment.
Lavender Oil Market Segmentation
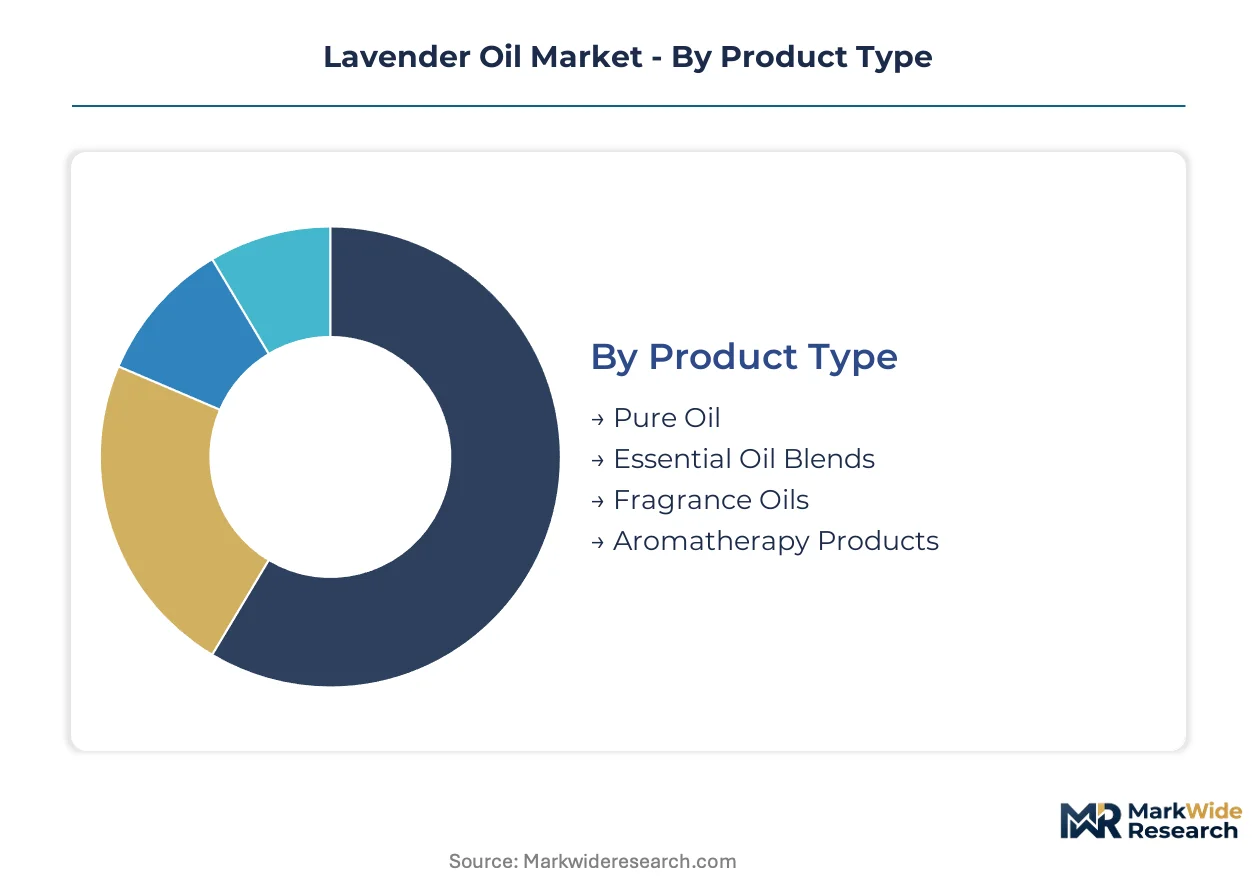
Lavender oil segmentation reflects divergent purity standards and procurement behaviors across therapeutic, cosmetic, and industrial use cases. Each category maps to distinct margin structures and regulatory exposure, from pharmacopeial-grade clinical applications to mass-market fragrance formulations.
Product Type:
Use-case spectrum spans clinical-grade standardization through commodity fragrance substitution, with purity thresholds determining pricing power and regulatory documentation burden.
- Pure Oil:Steam-distilled Lavandula angustifolia extract with linalool concentrations exceeding 25% and linalyl acetate above 30%, meeting ISO 3515 and AFNOR pharmacopeial specifications. Demand concentrates in French and Swiss clinical aromatherapy protocols and premium cosmetic formulations where batch traceability supports therapeutic claims.
- Essential Oil Blends:Pre-formulated combinations with carrier oils or complementary botanicals, standardized for dosage consistency in spa and home-use applications. Bulgarian cooperatives and Pacific Northwest distillers supply this segment through practitioner-direct channels, capturing margin by eliminating traditional broker layers.
- Fragrance Oils:Lower-concentration formulations incorporating synthetic extenders or alternative lavender species for cost-sensitive applications.
- Aromatherapy Products:Finished goods including diffusers, inhalers, and roll-on applicators with embedded oil delivery systems.
The dominant share belongs to Pure Oil, while Essential Oil Blends is closing the gap fastest.
Application:
Margin concentration varies sharply across application tiers, with cosmetic and personal care commanding premium positioning versus industrial fragrance and food-grade volumes.
- Personal Care:Premium skincare and haircare lines integrate lavender oil at 0.5-2% concentrations, with EU Cosmetics Regulation allergen disclosure requirements driving reformulation toward lower-linalool fractions or encapsulation technologies. French and German indie beauty brands absorb disproportionate compliance costs relative to multinational portfolios.
- Cosmetics:Color cosmetics and perfumery applications prioritize olfactory stability over therapeutic standardization. Givaudan and Firmenich procurement specifications favor Bulgarian-origin oils for consistent linalool profiles in fine fragrance compounds.
- Home Care:Surface cleaners, laundry additives, and air fresheners utilize lower-grade oils or synthetic substitutes.
- Food & Beverage:Flavoring applications require FEMA GRAS or EU 1334/2008 compliance, constraining allowable species to Lavandula angustifolia and Lavandula latifolia with strict pesticide residue limits.
Personal Care captures the deepest margin pools, with Cosmetics expanding most quickly through clean beauty portfolio expansion.
Distribution Channel:
Channel structure is bifurcating between traceability-focused direct procurement and convenience-oriented retail aggregation.
- Specialty Stores:Independent aromatherapy retailers and natural product apothecaries in Germany, the United Kingdom, and France emphasize origin documentation and organic certification visibility. These outlets serve practitioner buyers and educated consumers willing to pay 40-60% premiums over mass-market alternatives.
- Online Retail:Direct-to-practitioner platforms and brand-owned e-commerce displace traditional distributors, with Bulgarian and French distillers establishing proprietary storefronts. German aromatherapy cooperatives aggregate 50-200 practitioner accounts for volume contracting.
- Supermarkets:Mass-market personal care and home fragrance placements prioritize price positioning over provenance disclosure.
- Pharmacies:Clinical-grade and pharmacopeial oils distributed through regulated health channels, particularly in France and Switzerland where reimbursement frameworks support aromatherapy prescriptions.
Specialty Stores retain the dominant position, while Online Retail is gaining share fastest through cooperative purchasing consolidation.
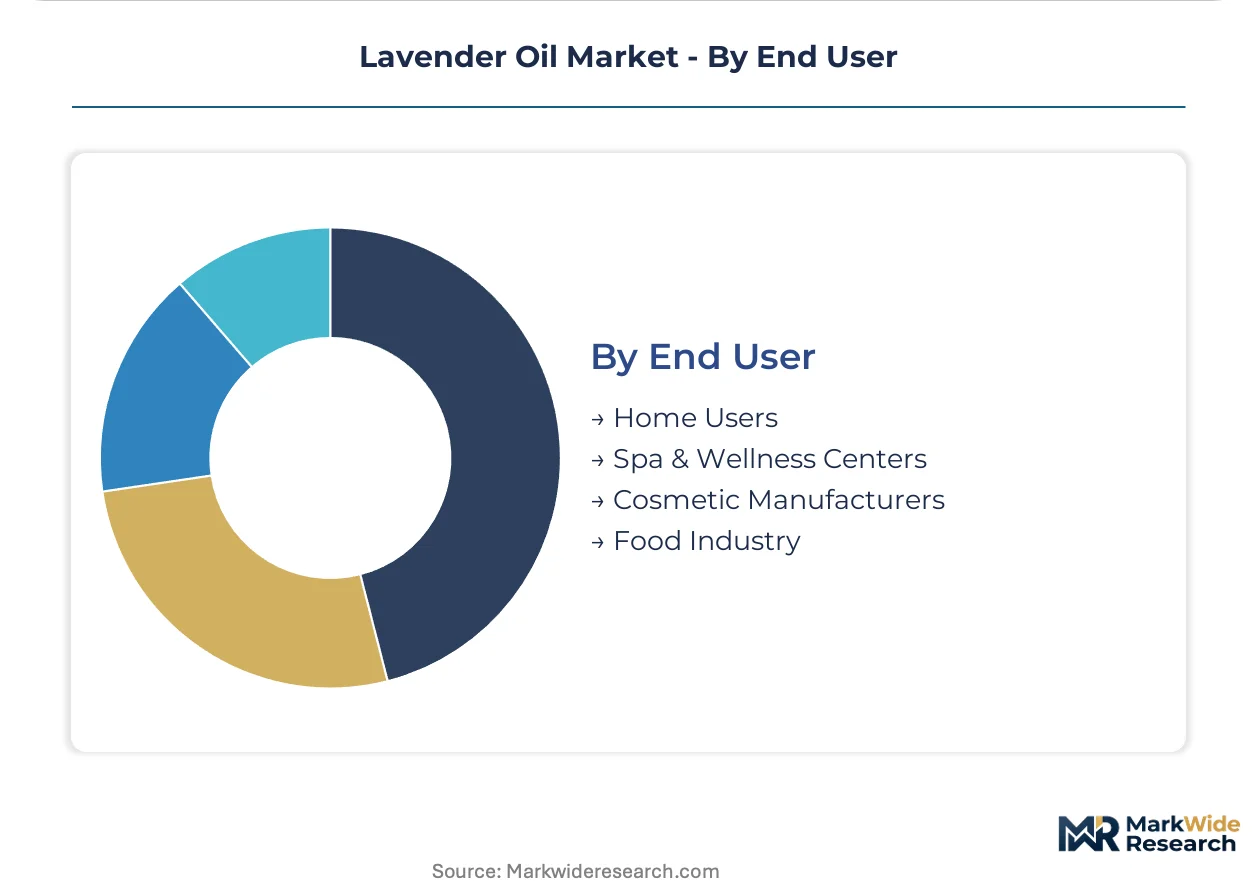
End User:
End-user segmentation maps to procurement sophistication, from industrial-scale formulation through individual consumption.
- Cosmetic Manufacturers:Multinational and indie beauty brands specify linalool profiles, solvent residues, and carbon footprint documentation. EU REACH registration and organic certification gate European market access, with compliance timelines favoring established French and Bulgarian suppliers.
- Spa & Wellness Centers:Treatment protocols demand consistent batch quality for liability and efficacy claims. German and UK clinical aromatherapists increasingly source through cooperative structures, negotiating direct contracts with named distillers.
- Home Users:Individual consumers purchasing through retail or e-commerce channels, with demand fragmenting across purity grades and price points.
- Food Industry:Flavor houses and natural food manufacturers requiring food-grade certification and supply chain segregation from cosmetic-grade processing.
Cosmetic Manufacturers command the dominant procurement volume, while Spa & Wellness Centers are climbing the fastest through professional association enrollment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon-neutral incentives are redirecting distillation investment toward biomass-fired infrastructure in Mediterranean and Pacific Northwest cultivation zones. France, Bulgaria, and China anchor processing capacity expansion as harvest-to-distillation windows compress.
France
Provence lavender cooperatives supply Givaudan and Firmenich with ISO 3515 pharmacopeial-grade oils for fine fragrance compounds. ANSM enforces EU Cosmetics Regulation allergen disclosure for linalool oxidation products in cosmetic formulations. Grasse processing clusters now integrate supercritical CO2 systems to achieve sub-ppm solvent residues for Swiss and German cosmetic manufacturers.
Bulgaria
Balkan highland distillers export 60% of output to German aromatherapy cooperatives and UK spa formulators. ECHA REACH registration requirements gate EU cosmetic supply chain access, favoring established distillers with analytical documentation capacity. Kazanlak Valley processing infrastructure is consolidating through cooperative investment models that shorten harvest-to-extraction timelines.
China
Xinjiang and Yunnan cultivation zones supply domestic personal care manufacturers expanding aromatherapy portfolios for middle-class wellness demand. SAMR cosmetic ingredient safety filings parallel EU disclosure frameworks for fragrance allergen labeling. Shanghai and Guangzhou formulation labs are sourcing traceable-origin oils through direct contracts with named distillers, bypassing traditional broker layers.
United States
Pacific Northwest organic growers supply Mountain Rose Herb and Aura Cacia with USDA-certified oils for clinical aromatherapy and premium cosmetic applications. FDA distinguishes cosmetic ingredient marketing from structure-function claims that trigger drug oversight. Oregon and Washington distillation clusters are digitizing batch control parameters for linalool yield optimization.
Germany
German aromatherapy cooperatives aggregate 50-200 practitioner accounts for volume contracting with Bulgarian and French distillers. BfR and EU EFSA guidelines constrain allowable pesticide residues in food-grade lavender oil applications. Munich and Hamburg distribution hubs are consolidating practitioner-direct procurement channels that displace traditional essential oil brokers.
Lavender Oil Market Competitive Environment
On the supply side, the industry is bifurcating between traceability-focused organic specialists and scale-driven fragrance compound suppliers. Distillers compete through pharmacopeial certification attainment, carbon-neutral processing infrastructure, and cooperative purchasing consolidation. Three archetypes dominate: Pacific Northwest organic growers with direct-to-brand relationships, Bulgarian cooperative-anchored Mediterranean processors, and clinical-grade standardization specialists. Capacity expansion and direct e-commerce storefront establishment constitute the dominant competitive moves.
Within the organic-specialist tier, Mountain Rose Herb and Aura Cacia exemplify supply chain archetypes. Mountain Rose Herb occupies a position anchored in Pacific Northwest grower relationships. Aura Cacia represents vertical control over distillation capacity in Mediterranean zones. The Body Shop sits within the multinational brand-cooperative investment model, sourcing through Bulgarian farming cooperative co-investment structures. These three entities illustrate how geographic origin and procurement architecture determine competitive positioning without requiring scale parity.
| Leading Market Players |
|---|
| Camenae |
| Pretty Valley |
| Frei |
| Mountain Rose Herb |
| The Body Shop |
| AFU |
| NextBox |
| Aura Cacia |
| AA Skincare |
| Others |
Value Chain & Pricing Dynamics
Bulgarian and French distillation clusters anchor upstream supply concentration, channeling margin capture toward pharmacopeial-grade standardization specialists and carbon-neutral processing innovators downstream. Certification-attainment timelines and analytical documentation capacity determine which producers access premium pricing tiers versus commodity fragrance substitution markets.
Pricing Analysis
Certification level creates the primary spread between pharmacopeial-grade and cosmetic-grade lavender oil, with ISO 3515 and AFNOR compliance commanding substantial premiums over unstandardized alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects linalool concentration thresholds, organic certification status, and batch traceability depth. Cost compression in mass-market personal care tiers is intensifying because petrochemical-derived synthetic linalool from BASF and Givaudan laboratories undercuts natural oil positioning. Home care and industrial fragrance buyers exhibit highest price sensitivity, while clinical aromatherapy practitioners and Swiss cosmetic formulators demonstrate lowest sensitivity due to therapeutic liability and sub-ppm solvent residue requirements.
Supply Chain Analysis
Lavandula angustifolia cultivation draws from established growing regions in France, Bulgaria, and China, with harvest-to-distillation windows compressing as Kazanlak Valley and Xinjiang processing infrastructure matures. Raw material dependencies center on organic fertilizer inputs, steam distillation fuel sources, and gas chromatography-mass spectrometry analytical reagents for batch verification. Single-source vulnerability concentrates in Bulgarian cooperative-anchored supply for German aromatherapy procurement, where ECHA REACH registration gates European market access. Distribution runs through practitioner-direct e-commerce platforms and specialty retail channels, displacing traditional essential oil brokers as German cooperatives aggregate volume for named distiller contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lavender oil markets exhibit cyclical recovery characteristics as climate volatility in Provence and Balkan highlands constrains reliable harvest windows, tightening supply against sustained aromatherapy portfolio expansion by personal care brands.
For Market Incumbents: Entrench pharmacopeial-grade positioning through supercritical CO2 extraction investment and carbon-neutral distillation infrastructure that captures EU Green Deal procurement preferences. Threat from synthetic linalool substitution in mass-market tiers demands defensive certification depth in clinical and premium cosmetic segments. Backward integration into Pacific Northwest organic grower relationships or Bulgarian cooperative investment structures secures traceable supply chains against harvest volatility. For New Entrants and Emerging Players: Xinjiang and Yunnan cultivation zones in China offer geographic underpenetration relative to established Mediterranean supply bases, with domestic personal care manufacturers expanding aromatherapy portfolios for middle-class wellness demand. Direct-to-practitioner e-commerce platforms bypass traditional broker layers, capturing margin through cooperative purchasing consolidation. Target clinical aromatherapy standardization protocols where pharmacopeial-grade specifications command premium positioning and regulatory documentation creates competitive moats. For Investors and Strategic Acquirers: Capital is best deployed toward traceability-focused organic specialists with established ECHA REACH registration and direct grower relationships across Pacific Northwest or Mediterranean zones. Long-term viability rests on carbon-neutral processing infrastructure and analytical documentation capacity that gates European cosmetic supply chain access. Monitor EU fragrance allergen labeling rule evolution as inflection indicator for reformulation-driven demand shifts toward lower-linalool fractions or encapsulation technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Neutral Distillation Investment | Biomass-fired stills align with EU Green Deal incentives, opening preferential procurement channels with sustainability-mandated buyers. |
| Pharmacopeial Certification Attainment | ISO 3515 and AFNOR compliance gates access to clinical aromatherapy protocols and Swiss cosmetic manufacturer supply chains. |
| Direct-to-Practitioner E-Commerce Launch | Proprietary storefronts displace traditional essential oil brokers, capturing margin through cooperative purchasing consolidation in Germany and UK. |
| Supercritical CO2 Extraction Scale-Up | Sub-ppm solvent residue specifications meet French and Swiss cosmetic formulator procurement requirements for premium applications. |
| Organic Grower Relationship Deepening | Pacific Northwest and Bulgarian cooperative partnerships secure traceable supply chains against climate volatility in Provence and Balkan highlands. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, EU Cosmetics Regulation disclosure filings, and customs trade data for lavender oil imports across European and North American markets. Distiller operations managers, organic certification auditors, cosmetic formulator procurement leads, and German aromatherapy cooperative administrators provided structured input on harvest-to-distillation timelines and batch standardization practices. Bottom-up volume triangulation from named cultivation clusters in France, Bulgaria, China, and the Pacific Northwest was cross-checked against top-down personal care brand aromatherapy portfolio disclosures.
Forecast inputs include product type segmentation across pure oil, essential oil blends, and fragrance oil grades; application tiers spanning personal care, cosmetics, and clinical aromatherapy; and distribution channel evolution between specialty retail and direct e-commerce procurement. Modeled CAGRs derive from segment-level volume trajectories and value-per-unit trends across certification tiers, with EU REACH compliance timelines and organic transition periods factored as supply-side constraints. Climate volatility patterns in Mediterranean growing regions and synthetic substitution elasticity in mass-market personal care inform scenario boundaries.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by carbon-neutral processing specialists or rapid synthetic linalool cost reduction would shift outcomes substantially. Cross-checking against ECHA registration volume trends and EU organic certification issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Patchouli Oil Market
Extracts
Botanical CO2 Extracts Market
Extracts
Medicinal Plant Extracts Market
Extracts
Herb and Spice Extracts Market
Extracts
Sage Extract Market
Extracts
Global Magnolia Bark Extract Market
Extracts
Asia-Pacific Mineral Turpentine Market
Extracts
Aloe Vera Extract Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Frankincense Oil Market
Extracts
Europe Mineral Turpentine Market
Extracts
Ovalbumin Powder Market
Extracts
Salvia Miltiorrhiza Extract Market
Extracts
Marigold Essential Oil Market
Extracts
Solid Phase Extraction Market
Extracts
Wild Yam Powder Market