
 Antibacterial Soap Market | 2026-2036
Antibacterial Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Antibacterial Soap Market Analysis
The FDA's 2016 ban on triclosan and triclocarban in consumer wash products is realigning the cost-of-entry calculus for antibacterial soap manufacturers, forcing reformulation around benzalkonium chloride, benzethonium chloride, or alcohol-based alternatives. Procter & Gamble leverages its massive R&D infrastructure to navigate these regulatory shifts across multiple active ingredient pathways. Johnson & Johnson sustains brand trust in clinical-grade segments through rigorous testing protocols that exceed baseline compliance. Unilever competes aggressively in emerging economies with region-specific formulations that accommodate varying water hardness and storage conditions.
Antibacterial soap denotes a cleansing formulation containing biocidal active ingredients designed to reduce or eliminate bacteria on skin surfaces, typically incorporating quaternary ammonium compounds, phenolic derivatives, or alcohols at concentrations between 0.1% and 4.0% by weight. Its primary commercial purpose spans personal hygiene, healthcare infection prevention, and food safety compliance where microbial load reduction carries regulatory or operational significance. Liquid formats dominate volume in healthcare and hospitality channels due to dispenser compatibility and controlled dosing, while bar soap retains structural importance in household segments across South Asia and Sub-Saharan Africa where unit economics favor solid formats. The food industry end-user category represents an accelerating margin pool as HACCP-aligned facilities upgrade from standard soap to verified antibacterial formulations with documented kill-rate claims.
The EPA regulates antibacterial soap claims under FIFRA when products assert public health benefits beyond basic cleansing, while the FDA governs cosmetic and drug classifications based on active ingredient concentrations and intended use claims. India's BIS mandates ISI certification for soap products, creating a dual-compliance burden for multinational manufacturers targeting both export and domestic channels. China's NMPA requires registration of disinfectant-class soaps under hygiene product rules that demand local efficacy testing. Stakeholders must monitor evolving definitions of cosmetic versus drug claims across jurisdictions, as reclassification triggers entirely different approval timelines and clinical evidence requirements.
Market Dynamics
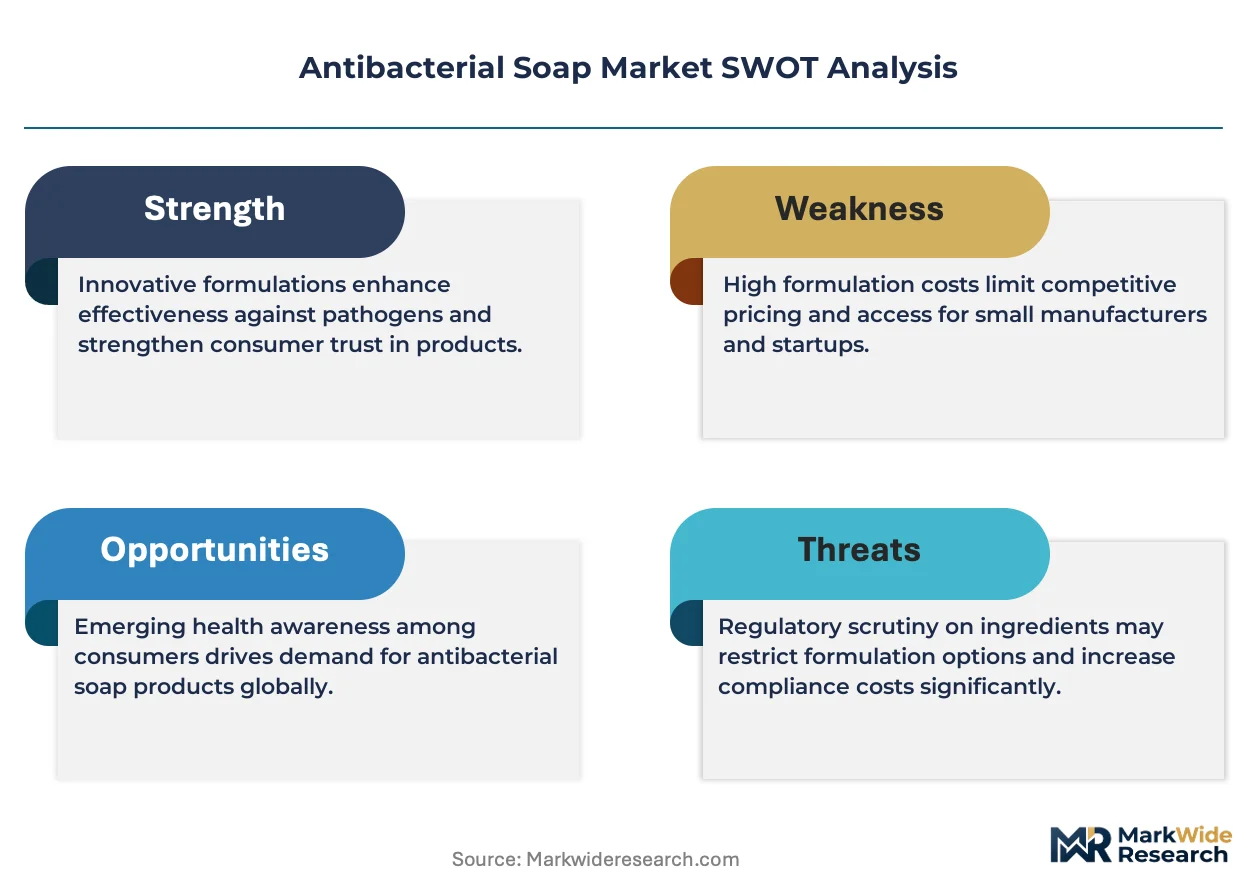
Reformulation mandates around biocidal actives are compressing manufacturing flexibility while fragmenting competitive advantage across distinct regulatory compliance pathways.
Growth Catalysts
- Hospital infection control protocols:Post-pandemic institutional standards now mandate documented bacterial kill rates in hand hygiene products, expanding verified-formula procurement across acute care networks.
- FDA's triclosan ban:The 2016 prohibition forced innovation into benzalkonium chloride and alcohol-based alternatives, creating first-mover advantages for manufacturers with pre-approved active portfolios.
- India's tier-two urbanization:Sachet-format affordability is unlocking household penetration in cities like Indore and Lucknow where per-capita soap consumption remains below metro benchmarks.
Market Restraints
- Palm oil price volatility:Fatty acid feedstock swings directly compress bar soap margins, particularly for mass-market producers lacking long-term plantation contracts.
- Active ingredient supply concentration:Quaternary ammonium compound production clusters in China's Jiangsu province, exposing formulators to single-point disruption risks.
- Alcohol-based substitution:Hand sanitizer gel formats are capturing outpatient clinic and retail channels where rinse-free convenience outweighs traditional soap efficacy claims.
Strategic Opportunities
- Food safety compliance:HACCP-aligned facilities in Brazil and Mexico are upgrading to documented antibacterial formulations, opening certified-product premiums in processing and packaging plants.
- PLI scheme manufacturing:India's production-linked incentive framework subsidizes domestic active ingredient synthesis, reducing import dependency for benzalkonium chloride.
- Digital B2B procurement platforms:Institutional buyers in hospitality and healthcare are consolidating vendor relationships through integrated supply contracts that favor multi-site service capabilities.
Industry Challenges
- Biocidal efficacy testing backlog:EPA FIFRA registration timelines for new active ingredients now extend 18-24 months, freezing pipeline launches.
- Formulation chemist scarcity:Specialized expertise in quaternary ammonium stability across varying water hardness conditions commands premium compensation, constraining mid-tier R&D expansion.
- Legacy dispenser incompatibility:Healthcare facilities face capital expenditure requirements to retrofit automated units for next-generation liquid formats with different viscosity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibacterial Soap Market |
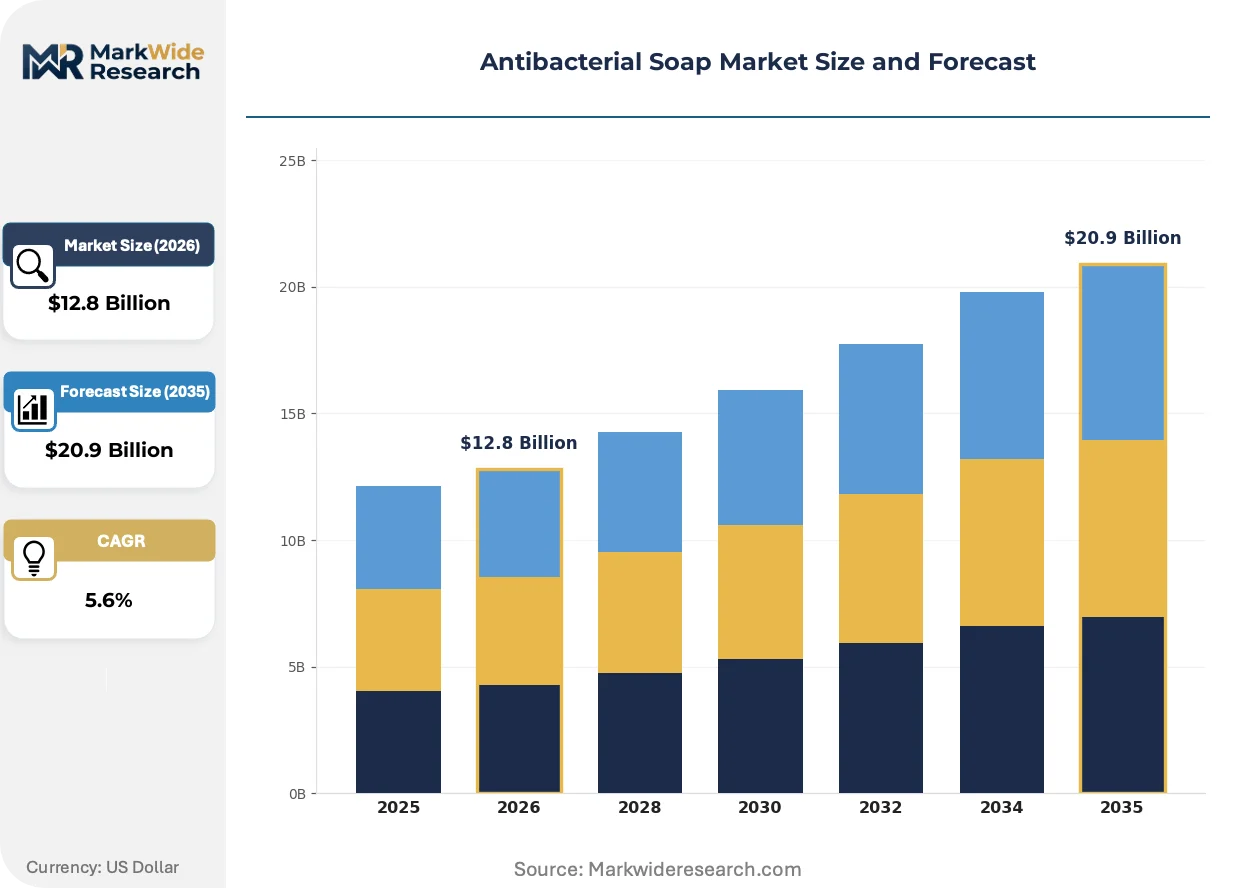
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.9 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Foam, Gel, Bar Packing Type: Plastic Bottle, Tube, Pump Dispenser, Refill End User: Household, Healthcare, Hospitality, Food Industry Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores |
| Companies Covered | 3M Company, Johnson & Johnson, Reckitt Benckiser Group PLC, Amway Corporation, Godrej Consumer Products Limited, Procter & Gamble Company, Henkel AG & Co. KGaA, Vi-Jon, Inc., Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibacterial Soap Market Emerging Trajectories
Active ingredient diversification is fragmenting technical roadmaps while digital traceability requirements are reshaping how efficacy claims get verified across institutional procurement channels.
Alcohol-benzalkonium hybrid formulations are consolidating technical investment as manufacturers seek dual-mechanism kill claims that satisfy both FDA cosmetic and EPA public health registration pathways. Hospital systems in the United States are fast-tracking adoption of these verified dual-actives to preempt Joint Commission audit findings. The consolidation is compressing single-mechanism product lines into commodity positioning while premium pricing attaches to documented spectrum efficacy.
REACH biocidal product regulation in Europe is forcing substance-level authorization for quaternary ammonium compounds used above 0.1% concentration, triggering re-evaluation of legacy formulations. Manufacturers serving EU markets must now submit full dossiers on benzalkonium chloride environmental fate, extending compliance timelines by 12-18 months. Personal care brands are responding by bifurcating product portfolios—maintaining traditional actives for non-EU channels while accelerating alcohol-dominant formats for European distribution.
Institutional procurement teams are unbundling soap supply from dispenser hardware, reversing decade-long bundled-service contracts that locked facilities into single-vendor dependencies. Healthcare procurement officers in Germany and the Netherlands now separate chemical purchasing from equipment leasing, enabling multi-source qualification for actives. This disintermediation is most visible in hospital networks where total-cost-of-ownership modeling now dominates supplier selection over brand loyalty.
Antibacterial Soap Market Segmentation
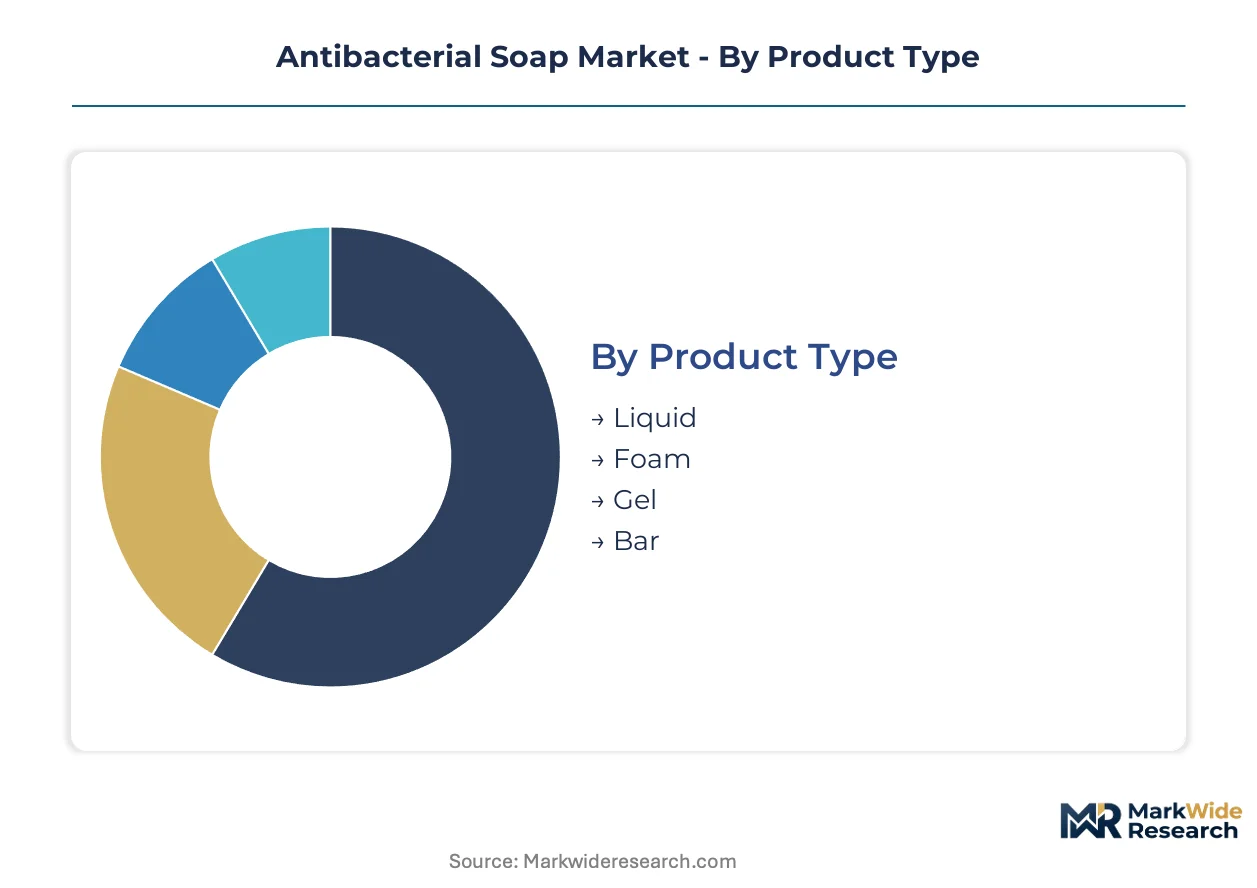
Antibacterial soap manufacturers configure production lines around viscosity, packaging compatibility, and dispenser integration rather than uniform output. Segment boundaries determine capital allocation for formulation equipment, with liquid and foam formats requiring distinct mixing infrastructure versus bar soap extrusion systems.
Product Type:
Liquid formats command premium shelf positioning in healthcare and hospitality channels, while bar soap dominates unit volume in emerging market households where water hardness and storage conditions favor solid formats.
- Liquid:Pump-dispensed formulations with 0.1% to 4.0% active ingredient concentrations integrate with automated hospital hygiene stations. Demand concentrates in US acute care networks where Joint Commission audits mandate documented bacterial kill rates. Viscosity engineering for dispenser compatibility requires specialized rheology testing.
- Bar:Fatty acid-based solid formulations packaged in paper wraps or cartons serve cost-sensitive households across India and Sub-Saharan Africa. Godrej Consumer Products and Hindustan Unilever compete aggressively in tier-two Indian cities like Indore and Lucknow where per-capita consumption trails metro benchmarks. Sachet economics and refill culture sustain structural importance despite liquid format growth elsewhere.
- Foam:Pre-lathered dispersions reduce water consumption in commercial restrooms and food processing facilities. HACCP-aligned installations in Brazil and Mexico are upgrading to verified foam systems.
- Gel:Thickened alcohol-benzalkonium hybrids target outpatient clinics seeking rinse-free convenience with residual activity claims. Alcohol-based substitution pressure from hand sanitizers constrains gel soap expansion in retail channels.
Mature deployment sits with bar soap. Newer deployment is concentrated in foam and gel formats for institutional compliance.
Packing Type:
Packaging selection tracks end-user infrastructure: built-in dispenser systems favor pump and refill formats, while household channels fragment across bottles and tubes based on bathroom counter space and travel portability.
- Pump Dispenser:Integrated pump mechanisms in rigid PET or HDPE housings serve hospitality and healthcare facilities with high-frequency handwashing protocols. European hospital networks in Germany and the Netherlands now unbundle soap procurement from dispenser hardware leasing, enabling multi-source qualification. Total-cost-of-ownership modeling favors pump systems with refill compatibility.
- Plastic Bottle:Squeeze bottles with flip-top closures dominate household retail across North American supermarkets. Procter & Gamble leverages massive R&D infrastructure to optimize bottle ergonomics and active ingredient stability.
- Tube:Collapsible aluminum or laminate tubes target travel-size segments and professional kits. Portability requirements drive tube preference in gym and airline amenity channels.
- Refill:Bulk concentrate pouches reduce per-use packaging cost for institutional buyers with existing dispenser infrastructure. Digital B2B procurement platforms favor refill contracts with multi-site service capabilities.
Standardized deployment sits with plastic bottles. Consolidating deployment is concentrated in pump dispensers and refill systems for institutional cost control.
End User:
End-user segmentation separates regulated institutional procurement with documented efficacy requirements from discretionary household purchasing driven by price and brand familiarity.
- Healthcare:Hospitals and clinical settings represent the steepest expansion trajectory as post-pandemic infection control protocols tighten. US acute care networks now mandate verified bacterial kill rates, expanding procurement of dual-mechanism alcohol-benzalkonium formulations. Johnson & Johnson sustains brand trust through testing protocols exceeding baseline FDA compliance.
- Household:Mass-market consumers in India, Nigeria, and Indonesia purchase antibacterial soap primarily through sachet and affordable bar formats. Water hardness variation across geographies forces region-specific formulation adjustments.
- Hospitality:Hotel and restaurant chains balance guest perception with operational cost, favoring mid-tier liquid formats with neutral fragrance profiles. Procurement consolidation through digital platforms is fragmenting legacy bundled-service contracts.
- Food Industry:HACCP-aligned processing and packaging facilities in Brazil and Mexico are upgrading from standard soap to verified antibacterial formulations with documented kill-rate claims. This end-user category captures accelerating margin premiums.
Volume concentration sits with household segments. Fastest margin expansion is concentrated in healthcare and food industry compliance-driven procurement.
Distribution Channel:
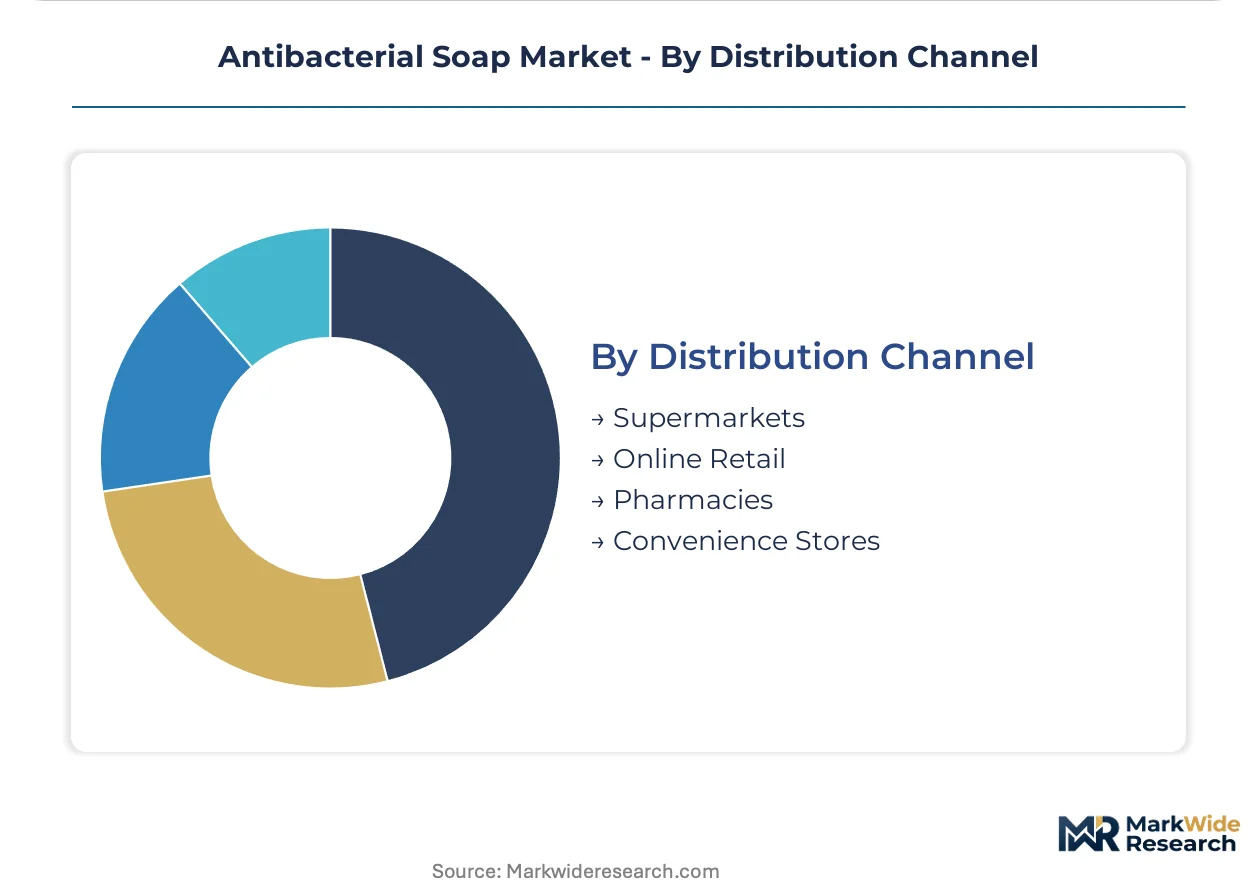
Channel strategy must reconcile impulse purchase behavior in physical retail with the specification-heavy procurement patterns of institutional buyers migrating to integrated digital platforms.
- Supermarkets:Mass merchandisers and grocery chains maintain antibacterial soap visibility through end-cap displays and promotional pricing. Shelf space allocation favors liquid formats with higher ring margins.
- Online Retail:E-commerce platforms aggregate subscription and bulk purchasing for household stockpiling and small institutional buyers. Amazon and regional equivalents capture growing share of refill and multi-pack transactions.
- Pharmacies:Drugstore chains position antibacterial soap adjacent to first-aid and wellness categories, emphasizing clinical credibility. Pharmacist recommendation influence sustains premium pricing for dermatologist-tested formulations.
- Convenience Stores:Small-format urban retailers serve emergency and travel-size purchasing with limited SKU breadth. High turnover velocity compensates for lower per-unit margins.
Established volume sits with supermarkets. Channel investment is concentrating in online retail and pharmacy clinical positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's production-linked incentive zones for specialty chemicals are concentrating active ingredient synthesis capacity, drawing multinational formulators to establish localized benzalkonium chloride production.
United States
Hospital infection control protocols mandate documented bacterial kill rates, expanding procurement of dual-mechanism formulations. The FDA's ongoing review of alternative actives under the 2016 triclosan ban continues reshaping compliance requirements. Manufacturing clusters in New Jersey and North Carolina host reformulation facilities serving acute care networks.
India
Tier-two urbanization in Indore and Lucknow drives sachet-format household penetration where per-capita consumption trails metro benchmarks. BIS mandates ISI certification for soap products, creating dual-compliance burdens for export-oriented manufacturers. Godrej Consumer Products and Hindustan Unilever compete aggressively in these emerging city markets.
Germany
Healthcare procurement officers unbundle soap supply from dispenser hardware, enabling multi-source qualification for actives. REACH biocidal product regulation forces substance-level authorization for quaternary ammonium compounds above 0.1% concentration. Hospital networks in the Netherlands and Belgium follow similar procurement disintermediation patterns.
Brazil
HACCP-aligned food processing facilities upgrade from standard soap to verified antibacterial formulations with documented kill-rate claims. ANVISA registration requirements for disinfectant-class products demand local efficacy testing. São Paulo and Minas Gerais concentrate upgrading activity in meatpacking and dairy packaging plants.
China
Quaternary ammonium compound production clusters in Jiangsu province expose formulators to single-point disruption risks. NMPA requires registration of disinfectant-class soaps under hygiene product rules with local efficacy testing mandates. Yangtze River Delta manufacturers serve both domestic demand and export formulation supply.
Antibacterial Soap Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct regulatory compliance pathways. The vendor base stratifies into three tiers: multinational consumer goods giants with massive R&D infrastructure, regional champions with localized formulation expertise, and mid-tier contract manufacturers serving private-label channels. Dominant competitive moves include portfolio diversification into alcohol-benzalkonium hybrid formats and geographic expansion through sachet-format penetration in tier-two emerging cities.
Among diversified conglomerates, Procter & Gamble and Unilever occupy positions spanning multiple active ingredient portfolios and regional compliance frameworks. Johnson & Johnson anchors the clinical-grade segment through testing protocols exceeding baseline FDA requirements. Godrej Consumer Products represents the regional champion archetype with concentrated presence in Indian tier-two urban markets.
| Leading Market Players |
|---|
| 3M Company |
| Johnson & Johnson |
| Reckitt Benckiser Group PLC |
| Amway Corporation |
| Godrej Consumer Products Limited |
| Procter & Gamble Company |
| Henkel AG & Co. KGaA |
| Vi-Jon, Inc. |
| Unilever PLC |
| Others |
Supply Flow & Price Mechanics
Captive production of quaternary ammonium compounds in China's Jiangsu province anchors both supply security and pricing power for formulators serving institutional procurement channels. Manufacturers with backward integration into benzalkonium chloride synthesis command premium positioning in EPA FIFRA registration pathways, while spot-market dependent players absorb feedstock volatility in fatty acid bar soap segments.
Pricing Analysis
Short lead-time premiums attach to dual-mechanism alcohol-benzalkonium hybrids as hospital procurement officers accelerate verified-formula qualification timelines. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade formulations with documented kill-rate claims from commodity bar soaps in sachet channels. Cost compression in mass-market bar segments intensifies because palm oil feedstock swings directly squeeze margins for producers lacking plantation contracts. Household consumers in tier-two Indian cities exhibit highest price sensitivity, while US acute care networks prioritize efficacy documentation over per-unit cost.
Supply Chain Analysis
EPA FIFRA and REACH BPR qualification gating fragments supplier bases into approved-actives cohorts with multi-year registration timelines. Active ingredient synthesis concentrates in China, India, and Germany, with Jiangsu province hosting quaternary ammonium production and Indian PLI zones emerging for domestic benzalkonium chloride. Fatty acid feedstocks, surfactant intermediates, and packaging resins draw from agricultural commodity markets and petrochemical derivatives. Single-source vulnerability in Jiangsu quaternary ammonium clusters exposes formulators to regional disruption risks. Distribution runs through institutional procurement platforms, retail merchandisers, and B2B digital marketplaces with diverging service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antibacterial soap sector sits in active-ingredient transition as alcohol-benzalkonium hybrids displace legacy single-mechanism formulations under tightening FDA and EPA registration requirements.
For Market Incumbents: Deepen backward integration into benzalkonium chloride synthesis through Indian PLI-subsidized facilities to insulate margin structures from Jiangsu supply concentration. Fortify EPA FIFRA registration portfolios ahead of 18-24 month approval backlogs that threaten pipeline continuity. Alcohol-based hand sanitizer substitution in outpatient channels demands accelerated dual-mechanism formulation investment to defend clinical-grade positioning. For New Entrants and Emerging Players: E-commerce subscription platforms offer the lowest-friction route to household penetration in India's tier-two cities where sachet-format demand outpaces established distribution coverage. White-space concentration sits with HACCP-aligned food processing facilities in Brazil and Mexico upgrading from standard soap to verified antibacterial formulations. Direct procurement relationships with institutional buyers through digital B2B platforms bypass legacy bundled-service contracts that lock incumbents into dispenser hardware dependencies. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified consumer goods conglomerates seeking EPA FIFRA-registered active portfolios. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone, compressing valuation premiums for pure-play formulators without registration dossiers. Watch for EPA registration timeline compression or REACH BPR substance-level authorization delays as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Active Ingredient Backward Integration | PLI-subsidized Indian benzalkonium chloride production reduces Jiangsu import dependency for formulators. |
| Dual-Mechanism Formulation Launch | Alcohol-benzalkonium hybrids satisfy both FDA cosmetic and EPA public health registration pathways. |
| Digital B2B Platform Partnership | Institutional procurement consolidation favors suppliers with multi-site service capabilities. |
| REACH BPR Dossier Submission | Substance-level authorization for quaternary ammonium compounds secures EU market access. |
| HACCP Certification Alignment | Documented kill-rate claims unlock premium positioning in Brazil and Mexico food processing. |
Methodological Framework
Document review covered EPA FIFRA registration databases, REACH BPR substance dossiers, BIS certification records, and trade flow data, complemented by interviews with formulation chemists, hospital procurement officers, and specialty chemical distributors. Primary fieldwork engaged plant managers at quaternary ammonium synthesis facilities, category buyers at Indian retail chains, and regulatory affairs leads navigating dual FDA-EPA compliance pathways. Secondary validation drew from customs records, SEC 10-K disclosures by diversified consumer goods conglomerates, and industry association technical bulletins. Bottom-up demand modeling triangulated against top-down market sizing across product format, end-use segment, and regional regulatory cluster dimensions.
Segment-level projections incorporate active ingredient transition timelines, institutional procurement pattern shifts, and sachet-format penetration curves across the analysis window. Modeled dimensions span liquid, bar, foam, and gel product types; healthcare, household, hospitality, and food industry end-users; and pump dispenser, plastic bottle, tube, and refill packaging formats. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory inflection points and feedstock cost elasticity. Forecast inputs include palm oil price volatility indices, EPA registration queue lengths, and tier-two urbanization rates in Indian secondary cities.
Inputs from EPA, BIS, and ANVISA regulatory databases were available through the study window; gaps in real-time Jiangsu production capacity utilization introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented registration timelines, feedstock cost structures, and procurement pattern shifts. A model refresh is warranted upon material change in FDA alternative-active review outcomes or REACH BPR authorization decisions for quaternary ammonium compounds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Razor Market
Personal Grooming Products
Feminine Hygiene Products Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
Facial Hair Care Wipes Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Mexico Beard Trimmer Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Shavers Market