
 Shaving Pen Market | 2026-2036
Shaving Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Shaving Pen Market Analytics
Aftermarket blade replacement and cartridge refill services is reconfiguring margin capture across the shaving pen value chain. Philips leverages its vertical integration into precision motor manufacturing to sustain premium positioning in cordless units. Panasonic Corporation anchors its competitive stance through ceramic blade technology leadership. Gillette competes via mass-market channel control and supermarket shelf-space dominance.
A shaving pen is a handheld personal grooming device engineered with oscillating or rotary cutting heads, typically powered by rechargeable lithium-ion cells or single-use batteries, designed for facial hair trimming and edge definition with blade gaps measured in micrometers. The device serves both consumer bathroom counters and professional barber stations where ergonomic grip geometry and motor torque consistency determine commercial utility. Refillable product types now command the highest margin pools as recurring blade purchases extend lifetime customer value. Metal material grades, particularly surgical stainless formulations, differentiate premium tiers from commodity plastic alternatives. Online distribution channels are displacing supermarket placements for direct-to-consumer subscription models.
REACH substance restrictions in Europe and FDA cosmetic device guidance in the United States constrain material selections and blade sterilization claims. ISO 13485 medical device quality standards and IEC 60335 household appliance safety protocols govern manufacturing certifications for products crossing into clinical or professional use categories. Stakeholders must monitor regulatory divergence between jurisdictions to preempt compliance-driven redesign cycles.
Market Dynamics
Professional barber stations and grooming salons now drive specification requirements for torque consistency and micrometer-grade blade precision, forcing manufacturers to recalibrate motor engineering and ergonomic grip geometry around commercial durability standards rather than consumer convenience alone.
Growth Catalysts
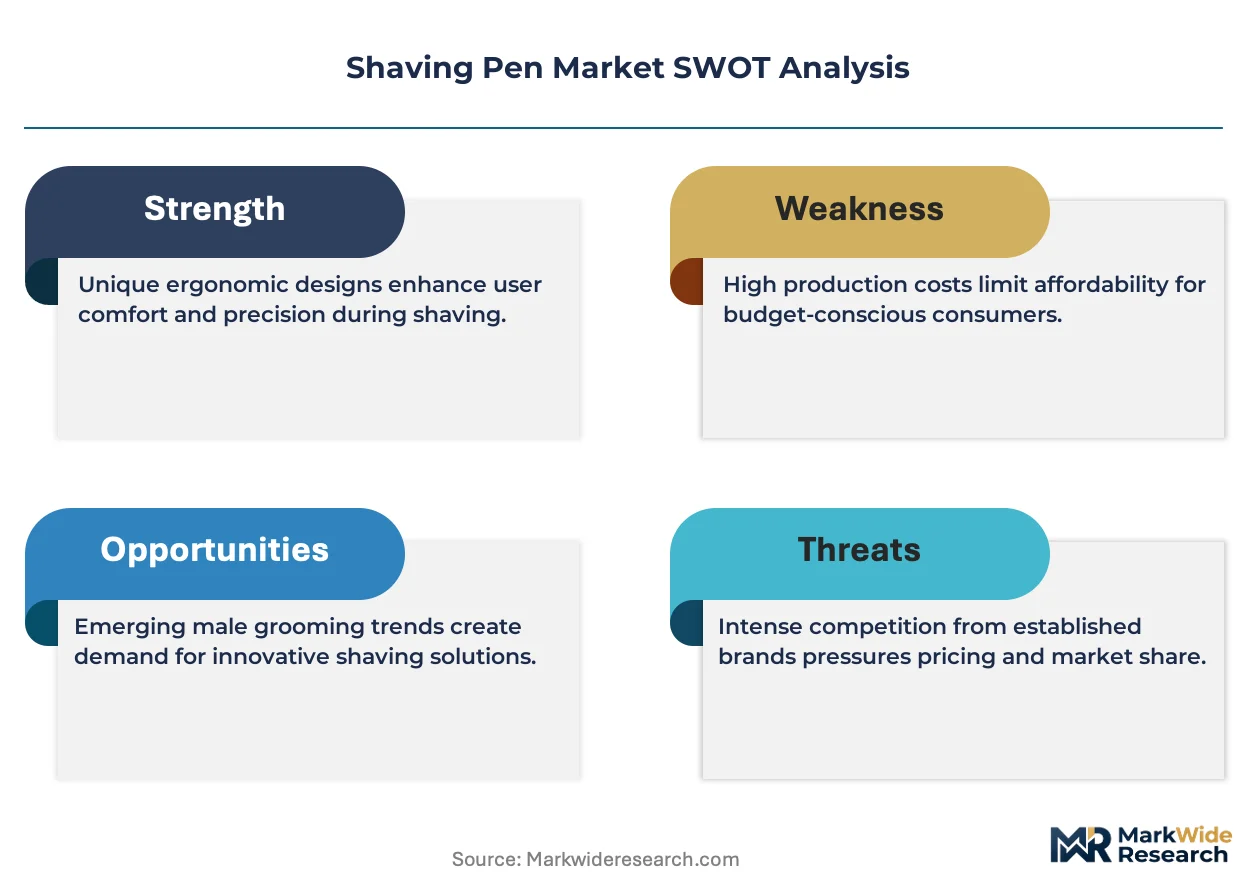
- Ceramic blade technology:Advanced ceramic formulations deliver superior edge retention and thermal stability during extended professional use, expanding replacement cycles and service intervals in high-volume barber environments.
- REACH substance restrictions:ECHA-mandated material exclusions in Europe accelerate R&D investment into biocompatible coatings and nickel-free surgical stainless formulations that command premium positioning.
- Germany's industrial manufacturing clusters:Concentrated precision tooling expertise around Solingen and Stuttgart enables rapid prototyping of custom blade geometries for private-label salon equipment.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing dependency on East Asian cell manufacturers creates input cost volatility and extended lead times for cordless unit production.
- Surgical stainless steel grade scarcity:Limited mill capacity for 440C and ATS-34 formulations constrains premium tier expansion and forces allocation decisions among competing personal care device categories.
- FDA cosmetic device guidance friction:Evolving classification ambiguity around blade sterilization claims delays product launches and requires redundant testing protocols for US market entry.
Strategic Opportunities
- Direct-to-consumer subscription blade replenishment:Recurring cartridge models bypass traditional supermarket shelf-space gatekeeping and capture lifetime value through automated fulfillment.
- Japan's precision tool districts:Untapped white space in metropolitan Tokyo and Osaka barber cooperatives for connected devices with usage analytics and predictive maintenance alerts.
- EU Green Deal circular economy mandates:Repairability scoring and extended producer responsibility frameworks favor modular designs with field-replaceable motor assemblies.
Industry Challenges
- ISO 13485 medical device quality certification:Extended audit timelines and documentation burdens delay professional-grade product launches by 8-14 months.
- Legacy barber supply chain integration:Wholesale distributor networks resist disintermediation and demand exclusive territorial arrangements that conflict with direct digital strategies.
- Micromachining talent scarcity:Specialized grinding and honing expertise for sub-50-micron blade gaps concentrates among aging European and Japanese master craftsmen.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shaving Pen Market |
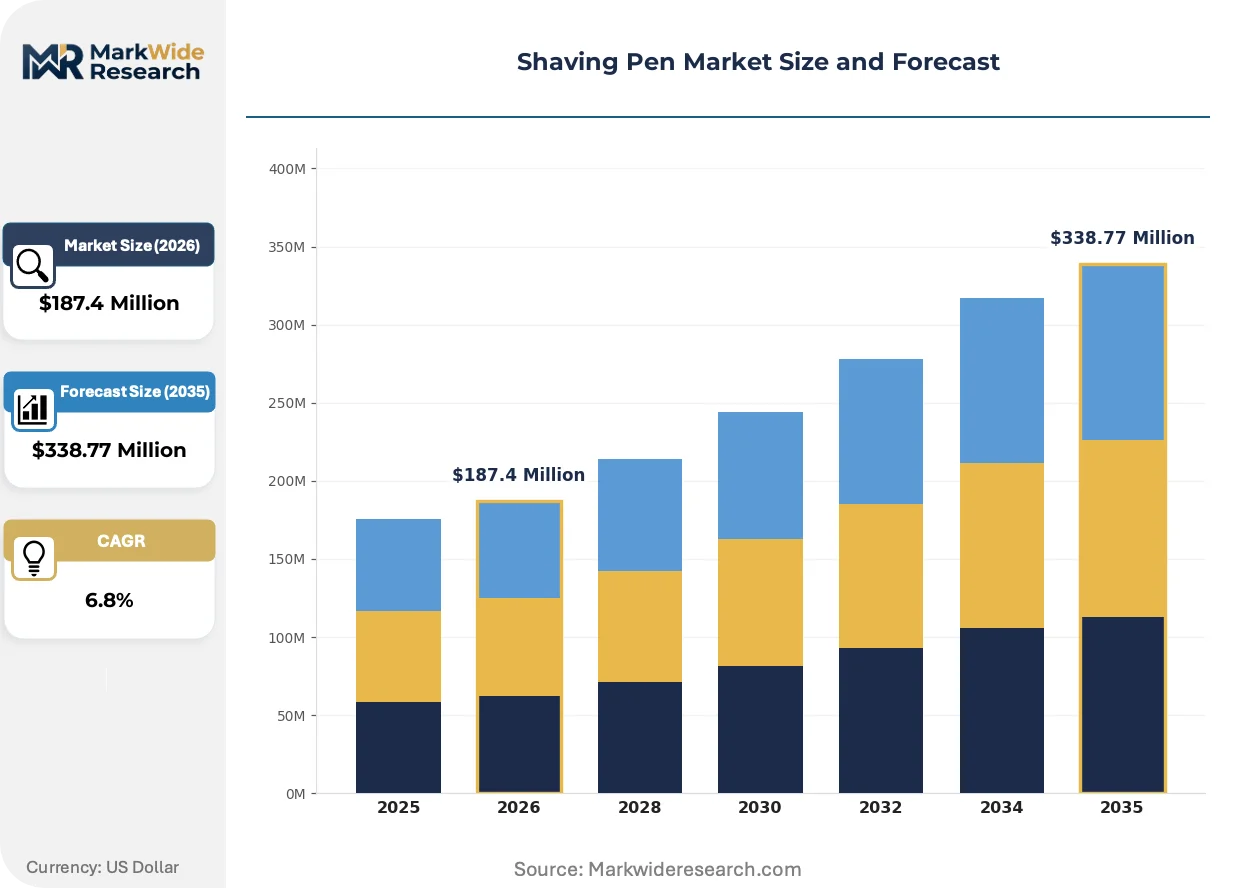
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Refillable, Eco-friendly, Compact Material: Plastic, Metal, Biodegradable, Glass Packaging Type: Boxed, Blister Pack, Pouch, Bulk Distribution Channel: Online, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Philips, Panasonic Corporation, Gillette, Wahl Clipper Corporation, Remington, Braun GmbH, Andis Company, KAI Group, Conair Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shaving Pen Market Evolving Landscape
Connected sensor integration and predictive maintenance algorithms are redefining how professional users interact with precision grooming equipment, shifting value capture from hardware margins to ongoing service relationships.
Smart blade monitoring systems is digitizing maintenance scheduling and inventory replenishment for high-volume barber chains. Salon operators in South Korea and the United Arab Emirates deploy these systems to minimize downtime during peak hours. The technology compresses traditional wholesale distribution by enabling manufacturers to capture recurring service revenue directly.
REACH substance restrictions and evolving FDA cosmetic device guidance are converging to mandate nickel-free surgical stainless and biocompatible coating disclosures. Manufacturers must maintain parallel material certification dossiers for European and American regulatory submissions. Professional-grade product lines face the steepest compliance burden due to sterilization claim requirements.
Subscription blade replenishment models displace supermarket and pharmacy shelf-space dependence for direct digital relationships. Independent barber cooperatives in Germany and metropolitan grooming chains in Japan pilot automated cartridge delivery tied to usage telemetry. This channel rotation concentrates highest-margin recurring revenue with manufacturers who control end-user data infrastructure.
Shaving Pen Market Segmentation
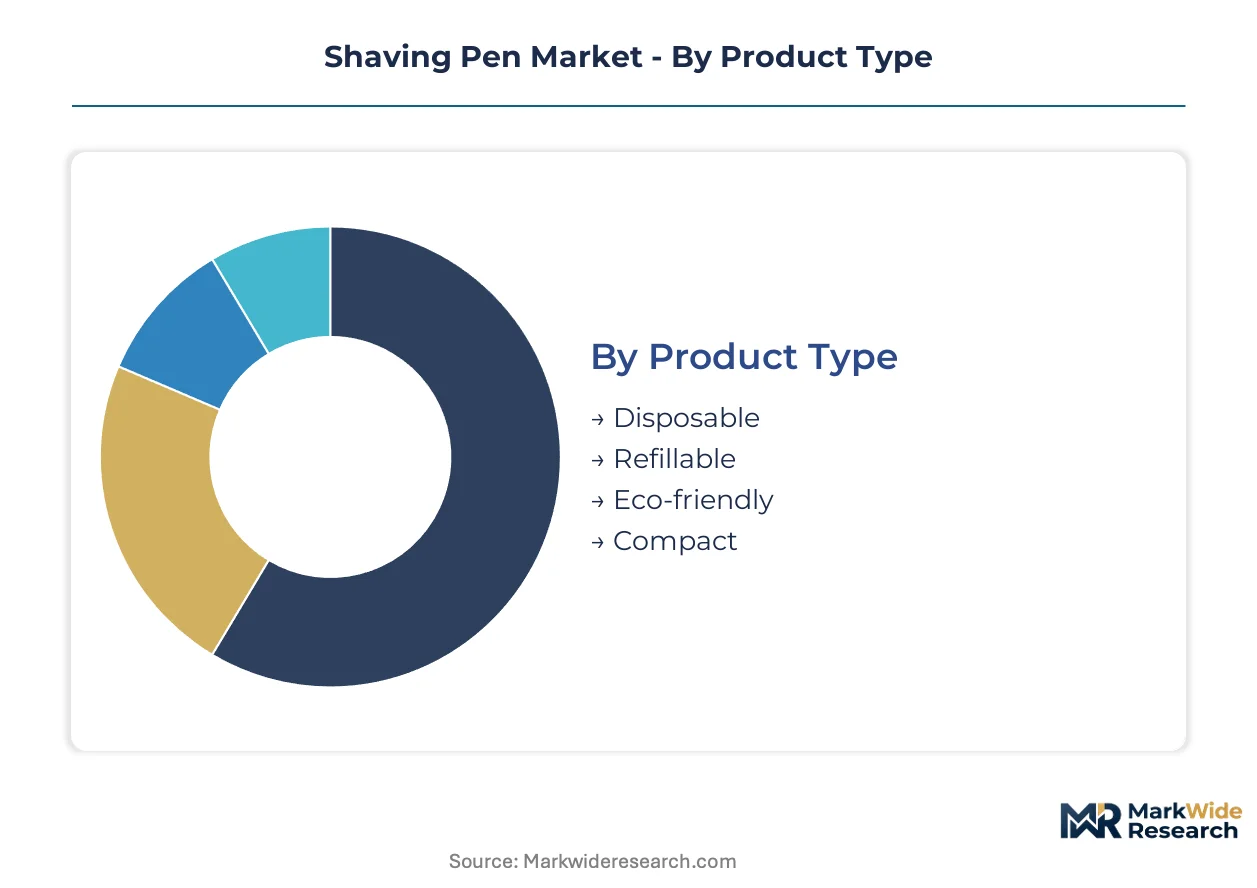
Shaving pen segmentation reveals how aftermarket service intensity varies dramatically across product configurations. Refillable systems generate recurring blade revenue streams while disposable formats sacrifice lifetime value for upfront accessibility. Material grades and distribution channels further stratify margin capture and customer retention economics.
Product Type:
After-sales-service intensity peaks with refillable architectures where blade cartridge replenishment locks in multi-year customer relationships.
- Refillable:Engineered with standardized cartridge interfaces and proprietary blade geometries that create switching costs. German barber cooperatives and Japanese grooming chains drive specification requirements for torque-matched motor systems. Subscription replenishment models capture recurring revenue pools that dwarf initial hardware margins.
- Disposable:Single-use units with sealed battery and integrated blade assemblies prioritize upfront affordability over longevity. Mass-market pharmacy channels in the United States and supermarket placements across France move volume without service attachment. Environmental compliance costs erode profitability as EU Green Deal extended producer responsibility mandates expand.
- Eco-friendly:Biodegradable chassis materials and recyclable blade cartridges address regulatory pressure from ECHA substance restrictions.
- Compact:Travel-format dimensions sacrifice motor capacity for portability in airline carry-on compliant dimensions.
Refillable holds the largest share; momentum sits with Eco-friendly as circular economy mandates harden.
Material:
Cost tier stratification separates surgical-grade formulations from commodity polymers, with certification requirements widening the gap.
- Metal:Surgical stainless 440C and ATS-34 formulations deliver micrometer-grade blade precision for professional barber stations. REACH nickel-free mandates and FDA biocompatibility claims force parallel certification dossiers. Limited mill capacity constrains premium tier expansion.
- Plastic:ABS and polycarbonate housings dominate mass-market disposable production with lower tooling costs and faster cycle times. Consumer bathroom counters absorb volume despite inferior thermal stability during extended use.
- Biodegradable:Polylactic acid and hemp-fiber composites respond to EU Green Deal repairability scoring.
- Glass:Borosilicate reinforcement elements appear in luxury positioning tiers.
Plastic holds the largest share; momentum sits with Metal as professional salon specifications harden.
Packaging Type:
Volume economics and retail channel requirements dictate format selection, with bulk configurations serving institutional procurement.
- Blister Pack:Thermoformed PET and PVC shells maximize shelf visibility in pharmacy and supermarket environments. Impulse purchase dynamics favor single-unit accessibility over protective durability.
- Boxed:Rigid paperboard with magnetic closures supports premium unboxing experiences for gift and subscription channels. Direct-to-consumer fulfillment tolerates higher dimensional weight.
- Pouch:Flexible film laminates reduce shipping cube for e-commerce replenishment.
- Bulk:Master cartons with minimal unit packaging serve hotel chains and airline amenity programs.
Blister Pack holds the largest share; momentum sits with Boxed as digital channel rotation accelerates.
Distribution Channel:
Customer type fragmentation separates professional procurement from consumer self-service, with data infrastructure determining margin retention.
- Online:Direct-to-consumer platforms and marketplace aggregators bypass wholesale distributor gatekeeping. Automated blade replenishment tied to usage telemetry captures lifetime value previously lost to retail intermediaries.
- Specialty Stores:Barber supply houses and professional grooming retailers provide technical consultation and immediate replacement part availability. Legacy territorial exclusivity arrangements conflict with manufacturer digital strategies.
- Supermarkets:Shelf-space dominance by mass-market brands constrains premium positioning.
- Pharmacies:Healthcare-adjacent positioning supports sterilization claim credibility.
Supermarkets holds the largest share; momentum sits with Online as subscription infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional barber stations in Germany absorb premium-priced units with minimal price elasticity, while mass-market consumers in the United States and India prioritize disposable formats at entry price points.
Germany
Barber cooperatives in Solingen and Stuttgart drive specification requirements for micrometer-grade blade precision. REACH substance restrictions enforced by ECHA mandate nickel-free surgical stainless formulations. The Baden-Württemberg precision tooling cluster enables rapid prototyping of custom blade geometries for private-label salon equipment.
United States
Mass-market pharmacy channels and supermarket shelf-space dominance move high volumes of disposable units with limited service attachment. FDA cosmetic device guidance creates classification ambiguity around blade sterilization claims. The Chicago metropolitan area anchors wholesale distributor networks resisting direct-to-consumer disintermediation.
Japan
Metropolitan Tokyo and Osaka barber cooperatives pilot connected devices with usage analytics and predictive maintenance alerts. METI industrial standards govern precision motor manufacturing certifications. The Chubu region around Nagoya concentrates ceramic blade grinding expertise for sub-50-micron edge geometries.
South Korea
High-volume barber chains in Seoul deploy smart blade monitoring systems to minimize downtime during peak hours. MFDS medical device regulations constrain sterilization claim substantiation for professional-grade lines. The Seoul Capital Area drives adoption of sensor-integrated grooming equipment with automated inventory replenishment.
India
Mass-market consumers in Maharashtra and Gujarat prioritize upfront affordability in disposable formats over refillable architectures. BIS quality standards and DGFT import regulations shape material sourcing decisions. The Karnataka industrial corridor around Bangalore emerges as a contract manufacturing hub for plastic-housing consumer units.
Shaving Pen Market Competitive Landscape
Vertically integrated conglomerates and specialized grooming equipment fabricators split the market into distinct competitive spheres. The vendor base concentrates around three strategic archetypes: precision motor manufacturers with captive blade production, mass-market consumer brands with channel control, and professional salon specialists with technical service networks. Consolidation pressures intensify as direct-to-consumer subscription models erode traditional wholesale distributor gatekeeping. Capacity expansion in ceramic blade manufacturing and strategic licensing agreements for connected device platforms represent dominant competitive moves.
Among diversified electronics conglomerates, Philips and Panasonic Corporation occupy positions exemplifying backward integration into precision motor manufacturing and ceramic blade technology leadership respectively. Braun GmbH anchors the German-engineered premium tier with professional salon credibility. These three entities represent distinct strategic postures: captive supply chain control, materials science specialization, and regional brand equity with technical service infrastructure.
| Leading Market Players |
|---|
| Philips |
| Panasonic Corporation |
| Gillette |
| Wahl Clipper Corporation |
| Remington |
| Braun GmbH |
| Andis Company |
| KAI Group |
| Conair Corporation |
| Others |
Value Network & Pricing Analysis
Lithium-ion cell supply concentration in East Asian manufacturing clusters determines both the pricing spread between cordless and corded tiers and the geographic shape of procurement networks. Manufacturers face margin compression when battery pack sourcing costs spike, forcing allocation decisions that favor premium professional lines over mass-market disposable formats.
Pricing Analysis
Aftermarket blade cartridge replenishment drives lifetime value capture and separates profitable refillable architectures from margin-thin disposable units. Three-tier pricing structure across premium surgical stainless, standard nickel-free formulations, and economy plastic tiers reflects certification grade differentiation and torque-matched motor engineering. Pricing pressure stems from REACH-mandated material substitutions that raise input costs for European market compliance. Mass-market pharmacy channels in the United States exhibit highest price sensitivity, while German barber cooperatives absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Surgical stainless steel feedstock draws from limited mill capacity in Germany, Japan, and select United States specialty producers. Ceramic blade formulations and precision motor assemblies rest on concentrated sourcing from the Chubu region of Japan and South Korean electronics manufacturing clusters. Single-source vulnerability in 440C and ATS-34 steel grades threatens premium tier expansion timelines. Distribution runs through legacy wholesale barber supply networks resisting disintermediation, though direct-to-consumer platforms are capturing replenishment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as connected device ecosystems and predictive maintenance subscriptions restructure value capture away from transactional hardware sales.
For Market Incumbents: Harden defensive positioning through captive ceramic blade manufacturing capacity and ISO 13485 certification investment that delays professional-grade competitor launches. Lock in exclusive territorial arrangements with German and Japanese barber cooperatives before direct-to-consumer platforms erode wholesale channel control. Prioritize backward integration into precision motor production to sustain torque consistency advantages.
For New Entrants and Emerging Players: Metropolitan Tokyo and Osaka barber cooperatives piloting usage analytics represent the most penetrable entry point for connected device platforms with predictive maintenance subscriptions. India's Karnataka industrial corridor offers contract manufacturing partnerships for plastic-housing consumer units at entry price points. Deploy direct-to-consumer subscription blade replenishment to bypass supermarket shelf-space gatekeeping and capture recurring revenue.
For Investors and Strategic Acquirers: EU Green Deal circular economy mandates reshape the acquisition landscape by favoring modular designs with field-replaceable motor assemblies and repairability scoring compliance. Target specialists with established ECHA certification dossiers and nickel-free surgical stainless formulations across the medium-term horizon. Monitor ceramic blade grinding expertise concentration among aging European and Japanese master craftsmen as a supply constraint inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Blade Capacity Expansion | Panasonic Corporation's technology leadership in sub-50-micron edge geometries commands premium positioning in professional salon channels. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models bypass wholesale distributor gatekeeping and capture lifetime value through automated fulfillment infrastructure. |
| REACH Compliance Certification | ECHA-mandated nickel-free formulations and biocompatible coatings create switching costs that protect European market positioning. |
| Connected Device Integration | Smart blade monitoring systems with predictive maintenance alerts compress traditional distribution and enable recurring service revenue capture. |
| Precision Motor Manufacturing Scale-Up | Captive supply of torque-matched motor systems sustains competitive differentiation in high-volume barber environments. |
Research Methodology
The analysis maps refillable architectures, disposable formats, ceramic blade technologies, and connected device platforms, each validated through procurement managers at German barber cooperatives, Japanese grooming chain operators, United States pharmacy category buyers, and precision tooling engineers in Solingen and Stuttgart. Primary interview insights triangulate against customs records, ECHA substance restriction filings, FDA cosmetic device guidance documents, and METI industrial standard certifications. Bottom-up unit economics and top-down market sizing converge through iterative reconciliation across the analysis window.
Assumptions around REACH enforcement timelines, lithium-ion cell cost trajectories, and professional salon adoption curves for connected devices were held fixed while regional regulatory divergence and ceramic blade grinding capacity expansion were varied as sensitivity inputs. Segmentation modeling incorporates product type, material grade, distribution channel, and end-use intensity dimensions. CAGRs derive from fitted growth curves against historical replacement cycle data and subscription attach rate benchmarks.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, East Asian battery supply disruptions, or ECHA substance restriction expansion would shift the trajectory. Forecasts reflect documented assumptions regarding professional barber station specification hardening and direct-to-consumer channel rotation velocity. Cross-checking against hospital procurement database trends and GPO contract structures for adjacent personal care devices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
North America Mosquito Repellent Market
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Shoe Insert Market