
 China Massage Equipment Market | 2026-2036
China Massage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Massage Equipment Market Insights
Guangdong's contract manufacturing base is repositioning toward branded output as domestic consumption rises. Wuxi Healthpro Technology Co., Ltd. leverages its Jiangsu production cluster to control component sourcing costs. Xiaomi Inc. competes through ecosystem integration, bundling massage devices with its smart home platform. OSIM International Pte. Ltd. anchors its China position through flagship stores in tier-one retail corridors.
Massage equipment encompasses electrically or manually actuated apparatus designed for myofascial manipulation, incorporating motors generating percussive forces, heated roller assemblies, or pneumatic compression chambers. These devices serve therapeutic muscle recovery, circulatory stimulation, and stress reduction across consumer and clinical environments. Massage chairs command the dominant revenue position within product type segmentation, while handheld massagers represent the fastest-expanding category due to portability and lower price accessibility. Commercial wellness centers drive application-level demand, though physiotherapy clinics concentrate margin pools through reimbursement-linked therapeutic device procurement.
NMPA oversight of therapeutic claim classifications and GB standards for electrical safety shape product development pathways for domestic manufacturers. SAMR enforcement of advertising standards constrains how brands communicate health benefits to consumers. Stakeholders must monitor evolving medical device reclassification thresholds that could shift substantial product volumes into regulated pathways requiring clinical evidence submission.
Market Dynamics
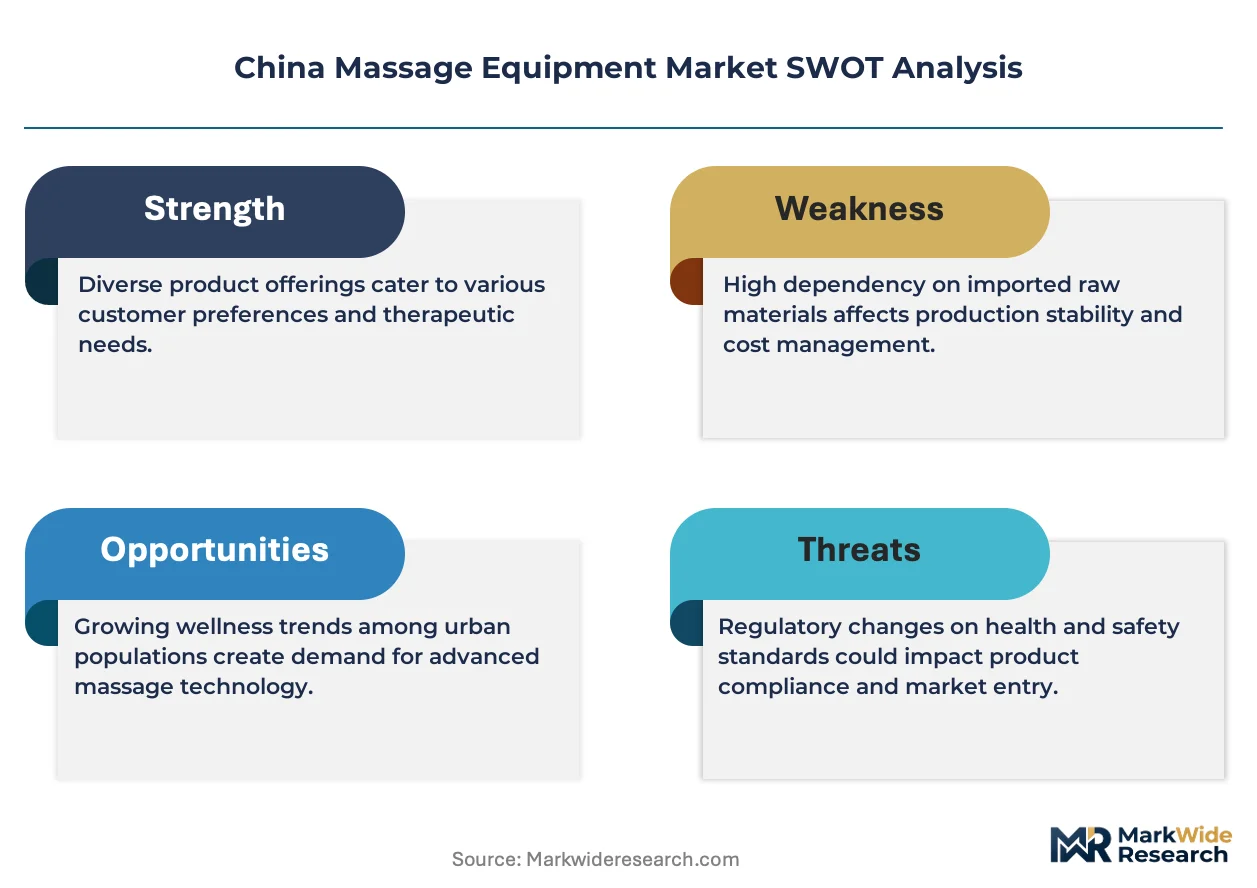
NMPA's medical device reclassification initiative is forcing manufacturers to recalibrate therapeutic claims documentation, compressing time-to-market for new entrants while advantaging incumbents with established clinical evidence portfolios.
Growth Catalysts
- Shanghai's premium wellness corridor:Concentrated high-net-worth household density drives flagship retail absorption for therapeutic-grade massage chairs, creating demonstration effects that cascade into tier-two provincial capitals.
- GB electrical safety standard harmonization:Unified testing protocols reduce certification duplication costs for domestic manufacturers, accelerating product refresh cycles and enabling faster feature iteration.
- Percussive therapy motor miniaturization:Advances in brushless DC motor density allow handheld massagers to deliver chair-comparable force output, opening clinical adjacencies previously reserved for stationary equipment.
Market Restraints
- Copper and rare-earth magnet price volatility:Motor assemblies depend on neodymium and copper windings, with spot market fluctuations compressing gross margins for mid-tier manufacturers lacking forward purchase agreements.
- Guangdong contract manufacturer concentration:Over half of domestic OEM capacity clusters in the Pearl River Delta, exposing the supply base to single-region weather, labor, or logistics disruptions.
- Lithium-ion cell thermal runaway risk:Portable device battery safety incidents trigger SAMR recall protocols, imposing remediation costs and brand equity damage that disproportionately affects emerging competitors.
Strategic Opportunities
- Chengdu-Chongqing economic circle:Western China's rising disposable income and undersaturated premium retail presence offer first-mover positioning before established coastal brands complete distribution buildout.
- Smart home ecosystem integration:Massage devices embedding MIIT-certified IoT protocols enable voice-activated session programming, attracting tech-forward households already invested in connected appliance platforms.
- Dual carbon goals compliance positioning:MEE energy efficiency labeling requirements create differentiation for manufacturers achieving standby power thresholds below regulatory minimums, unlocking government procurement preferences.
Industry Challenges
- Clinical evidence generation timelines:NMPA Class II medical device pathways require 12-18 month prospective studies for pain management claims, straining R&D budgets and delaying revenue recognition.
- After-sales service network scaling:Massage chair reliability demands field technician density that outpaces manufacturer training pipeline capacity in third- and fourth-tier cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Massage Equipment Market |
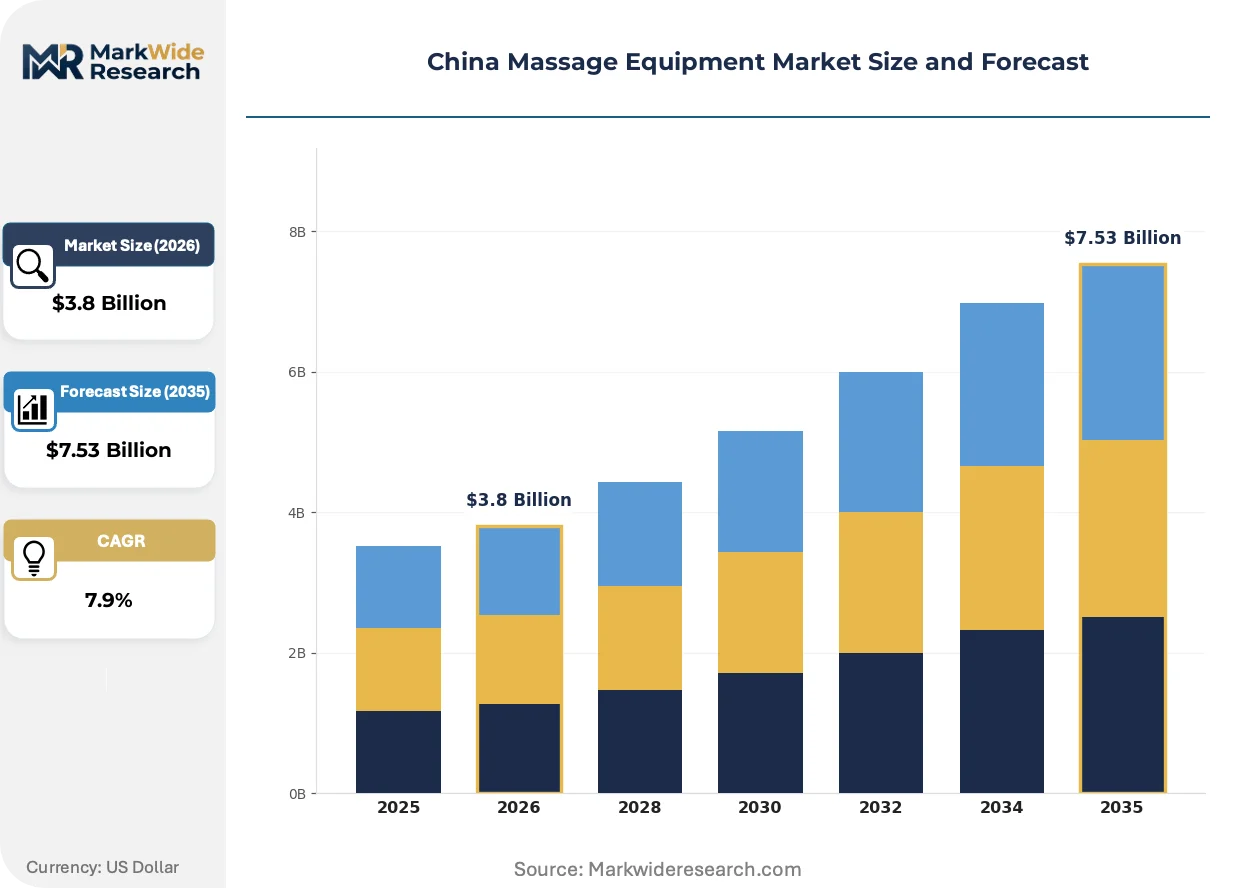
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Massage Chairs, Handheld Massagers, Foot Massagers, Massage Tables Application: Home Use, Commercial Wellness Centers, Physiotherapy Clinics, Sports Rehabilitation End User: Adults, Seniors, Athletes, Health Enthusiasts Technology: Electric, Manual, Compression, Vibration |
| Companies Covered | Wuxi Healthpro Technology Co., Ltd., Xiaomi Inc., iRest Group, Panasonic Holdings Corp., OSIM International Pte. Ltd., Fujian Jingtuo Health Technology Co., Ltd, Guangzhou Foworld Electronic Technology Co., Ltd, Naipo, Reead (Shanghai) Intelligent Technology Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Massage Equipment Market Trends and Innovations
Thermal-pneumatic hybrid actuation systems and AI-driven pressure mapping are compressing the feature gap between clinical physiotherapy devices and consumer-grade equipment, forcing repositioning across price tiers.
Brushless motor arrays with real-time torque feedback are electrifying the handheld segment's performance ceiling. Physiotherapy clinics in Beijing and Shenzhen are adopting these units as adjunct modalities, displacing manual therapist hours for routine myofascial release protocols. The technology is compressing equipment procurement cycles as clinics refresh portable inventories ahead of stationary chair replacement schedules.
SAMR's tightened advertising substantiation rules for therapeutic health claims are forcing brands to migrate marketing spend from broadcast media toward in-store experiential demonstration. Manufacturers must now maintain clinical study archives accessible to provincial enforcement inspections. Massage chair brands with established flagship retail footprints in Shanghai and Guangzhou are responding by expanding trained product specialist headcount.
Direct-to-consumer subscription financing is displacing traditional appliance retail credit for purchases above RMB 15,000. Young professional households in Hangzhou and Suzhou are adopting these instruments, unbundling the purchase decision from liquidity constraints. Wellness-focused e-commerce platforms are capturing this flow, compressing traditional department store channel share in coastal provinces.
China Massage Equipment Market Segmentation
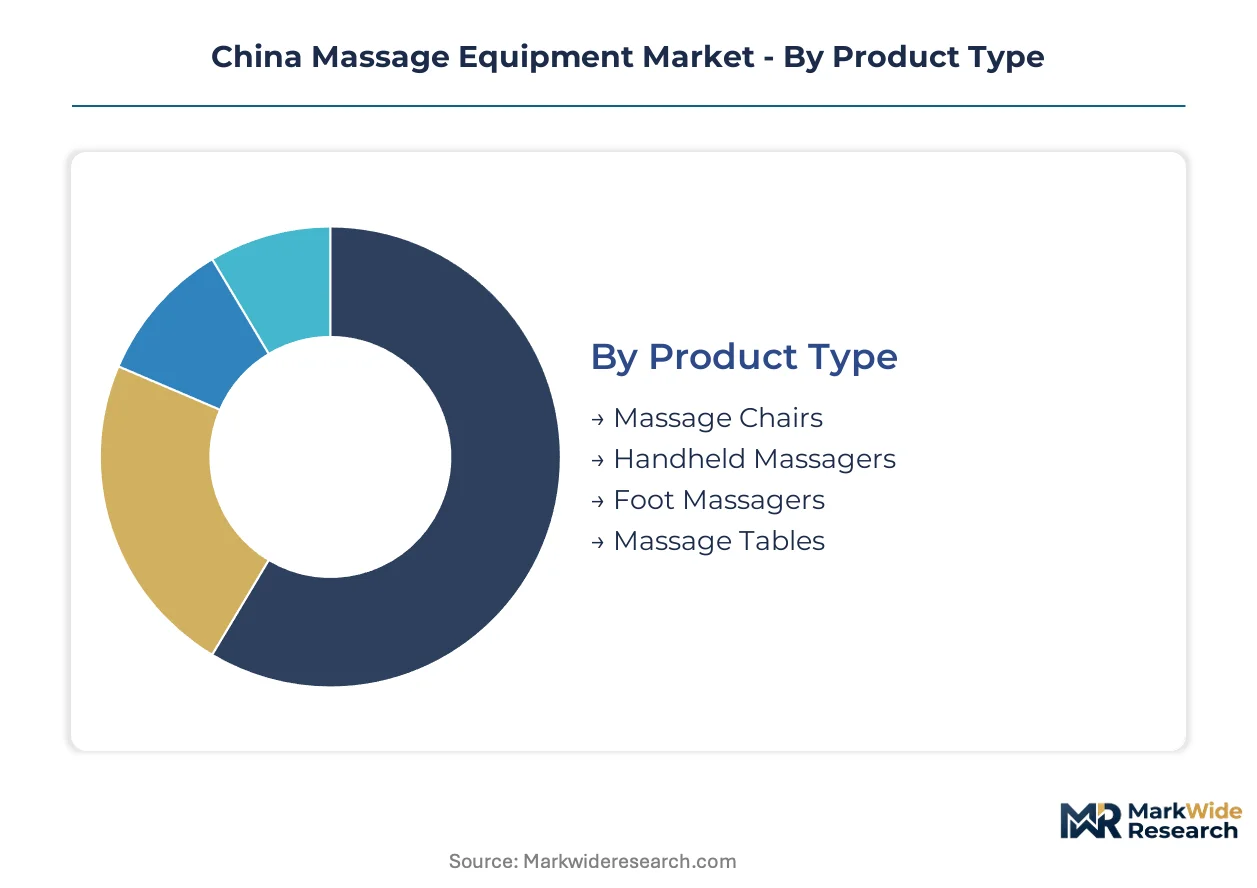
Massage equipment manufacturers in China must navigate divergent margin structures across stationary and portable form factors. Product type selection determines NMPA regulatory pathway exposure, while application focus shapes channel strategy and service infrastructure requirements.
Product Type:
Volume concentrates in stationary full-body systems, yet premium pricing power migrates toward portable therapeutic devices with clinical-grade force output.
- Massage Chairs:Stationary units integrating heated roller assemblies, pneumatic airbags, and zero-gravity positioning frameworks. Shanghai's high-net-worth households absorb flagship showroom inventory, with demonstration effects cascading into provincial capitals. The segment commands dominant revenue share through therapeutic-grade positioning and extended warranty attach rates.
- Handheld Massagers:Portable percussive devices leveraging brushless DC motor miniaturization to deliver chair-comparable force density. Beijing and Shenzhen physiotherapy clinics adopt these as adjunct modalities, displacing manual therapist hours for routine myofascial release. This segment is expanding most quickly due to lower price accessibility and clinical adjacency penetration.
- Foot Massagers:Electric or manual units targeting plantar fascia manipulation and circulatory stimulation. Residential adoption concentrates among seniors in Jiangsu and Zhejiang provinces.
- Massage Tables:Stationary or portable platforms for prone-position manual therapy. Commercial wellness centers in tier-two cities drive procurement cycles.
Today's leader: Massage Chairs. Tomorrow's challenger: Handheld Massagers.
Application:
Channel selection determines margin capture, with clinical reimbursement pathways offering superior unit economics despite longer sales cycles.
- Home Use:Residential installations spanning living room and dedicated wellness spaces. Direct-to-consumer subscription financing above RMB 15,000 unbundles purchase decisions from liquidity constraints for Hangzhou and Suzhou young professionals.
- Commercial Wellness Centers:High-traffic facilities requiring durable equipment with rapid session turnover protocols. Guangdong contract manufacturers supply this channel through OEM relationships with established spa chains.
- Physiotherapy Clinics:Clinical environments demanding NMPA Class II medical device certification for reimbursement-linked procurement. Beijing and Shenzhen facilities refresh portable inventories ahead of stationary chair replacement schedules.
- Sports Rehabilitation:Athletic training facilities and recovery centers adopting percussive therapy for acute muscle recovery. This application is climbing the fastest as professional sports infrastructure expands in Chengdu-Chongqing.
Clinical pathways yield superior per-unit margins. Consumer channels deliver volume scale.
End User:
Age-based segmentation aligns with distinct distribution and service requirements, from senior-focused residential sales to athlete-targeted performance positioning.
- Adults:Working-age consumers aged 25-55 seeking stress reduction and post-workout recovery. E-commerce platforms capture this demographic through wellness-focused verticals.
- Seniors:Consumers over 55 prioritizing circulatory stimulation and chronic pain management. Residential settings in Jiangsu and Zhejiang anchor adoption, with after-sales technician density requirements straining manufacturer training pipelines in lower-tier cities.
- Athletes:Professional and amateur competitors requiring acute recovery protocols. Sports medicine clinics in tier-one cities concentrate this demand.
- Health Enthusiasts:Wellness-focused consumers integrating massage into preventive health routines. Smart home ecosystem integration attracts this segment through MIIT-certified IoT protocol compatibility.
Seniors dominate installed base. Health enthusiasts drive replacement velocity.
Technology:
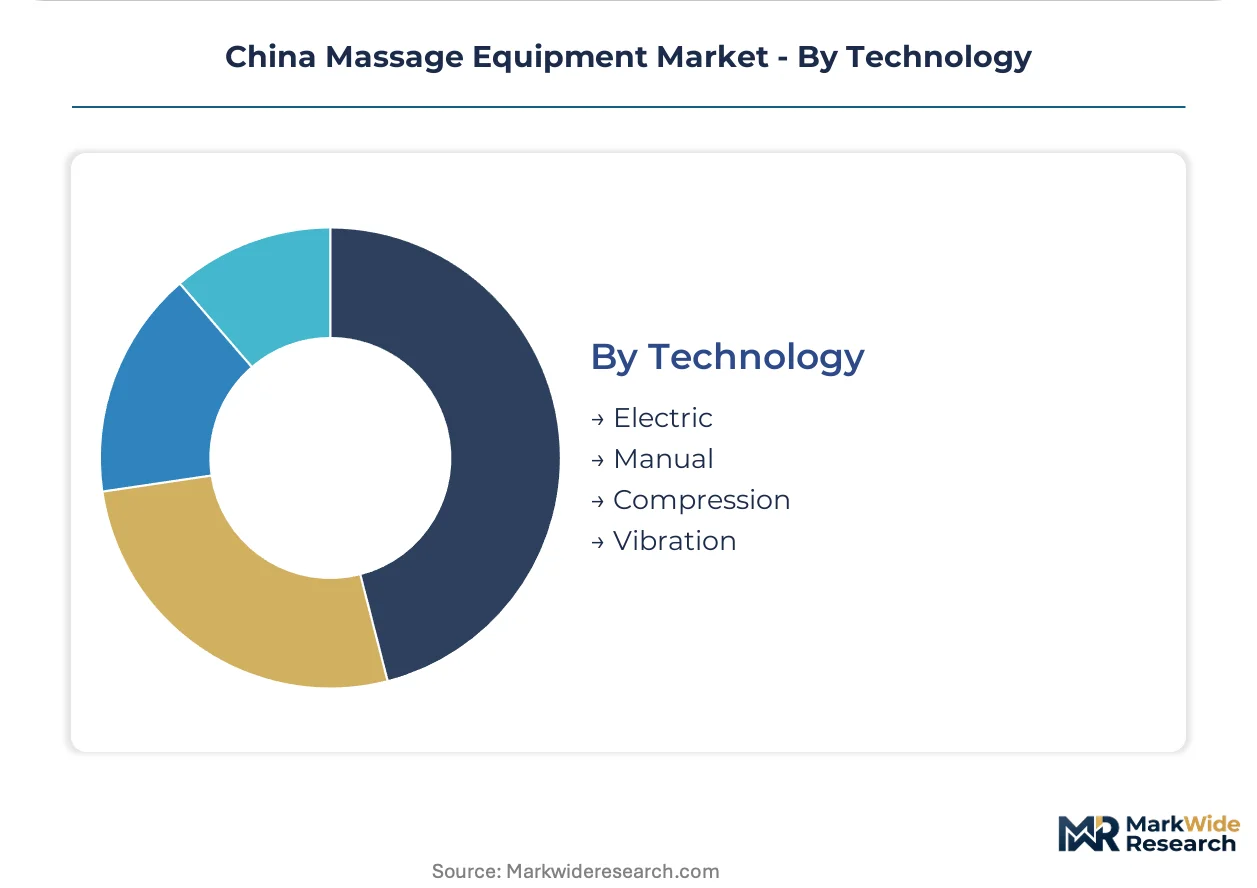
Actuation mechanism selection determines regulatory classification, energy efficiency positioning, and clinical evidence requirements.
- Electric:Motor-driven systems incorporating AC or DC power sources with programmable intensity modulation. GB electrical safety standard harmonization reduces certification duplication costs for domestic manufacturers.
- Manual:Human-actuated devices without electrical components, circumventing NMPA medical device oversight. Price accessibility sustains rural market presence.
- Compression:Pneumatic chamber systems delivering sequential pressure for lymphatic and circulatory stimulation. Thermal-pneumatic hybrid actuation advances compress the feature gap with clinical equipment.
- Vibration:Oscillating motor arrays targeting surface-level muscle relaxation. This technology is gaining share fastest in portable handheld formats due to miniaturization advances.
Electric systems anchor revenue. Vibration mechanisms enable form factor innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with streamlined medical device pathways and lower certification costs. Cost-of-compliance gaps between coastal and interior provinces are accelerating facility relocation. Provincial incentive structures now determine where therapeutic-grade assembly concentrates.
Yangtze River Delta
Shanghai's premium wellness corridor absorbs flagship showroom inventory for therapeutic-grade massage chairs, with demonstration effects cascading into Hangzhou and Suzhou. NMPA's medical device reclassification initiative compresses time-to-market for Jiangsu-based manufacturers with established clinical evidence portfolios. Wuxi Healthpro Technology Co., Ltd. leverages its Jiangsu production cluster to control component sourcing costs across motor assemblies and heated roller systems.
Pearl River Delta
Guangdong's contract manufacturing base is repositioning toward branded output as domestic consumption rises, with Shenzhen and Guangzhou driving premium retail absorption. SAMR enforcement of advertising standards constrains how brands communicate health benefits to consumers in this manufacturing heartland. Over half of domestic OEM capacity clusters in the Pearl River Delta, exposing the supply base to single-region weather, labor, or logistics disruptions.
Beijing-Tianjin-Hebei
Physiotherapy clinics in Beijing concentrate margin pools through reimbursement-linked therapeutic device procurement, driving NMPA Class II medical device certification demand. GB electrical safety standard harmonization reduces certification duplication costs for domestic manufacturers operating across Hebei assembly facilities. Beijing and Shenzhen facilities refresh portable inventories ahead of stationary chair replacement schedules, anchoring clinical adjacency penetration.
Sichuan-Chongqing
Western China's rising disposable income and undersaturated premium retail presence offer first-mover positioning before established coastal brands complete distribution buildout. MEE energy efficiency labeling requirements create differentiation for manufacturers achieving standby power thresholds below regulatory minimums, unlocking government procurement preferences in Chengdu. Sports rehabilitation infrastructure expansion in Chengdu-Chongqing is climbing fastest as professional sports facilities adopt percussive therapy protocols.
Shandong Peninsula
Qingdao and Jinan's manufacturing bases supply mid-tier massage equipment to residential settings across northern provinces, with senior-focused circulatory stimulation products dominating local demand. Dual carbon goals compliance positioning distinguishes Shandong manufacturers achieving sub-threshold standby power consumption. After-sales service network scaling strains manufacturer training pipeline capacity in these third- and fourth-tier city markets.
China Massage Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart home ecosystem integration and clinical-grade portable formats. The vendor base stratifies across three tiers: premium therapeutic-grade incumbents with flagship retail footprints, mid-tier domestic brands leveraging contract manufacturing scale, and ecosystem-integrated technology platforms bundling massage devices with connected appliance platforms. Dominant competitive moves include backward integration into motor and controller production and strategic partnerships with physiotherapy clinic networks for clinical validation.
Among Jiangsu-based fabricators, Wuxi Healthpro Technology Co., Ltd. occupies a position exemplifying regional production cluster leverage. Xiaomi Inc. represents the ecosystem-integrated archetype, anchoring competitive positioning through smart home platform bundling. OSIM International Pte. Ltd. sits within the premium-tier vector, demonstrating flagship retail corridor anchoring in tier-one cities.
| Leading Market Players |
|---|
| Wuxi Healthpro Technology Co., Ltd. |
| Xiaomi Inc. |
| iRest Group |
| Panasonic Holdings Corp. |
| OSIM International Pte. Ltd. |
| Fujian Jingtuo Health Technology Co., Ltd |
| Guangzhou Foworld Electronic Technology Co., Ltd |
| Naipo |
| Reead (Shanghai) Intelligent Technology Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor miniaturization simultaneously compresses production costs for portable devices and concentrates sourcing leverage among Jiangsu-based motor specialists with captive controller production. This technology shift redraws cost curves across handheld and stationary segments while amplifying dependency on rare-earth magnet supply chains.
Pricing Analysis
Retailer markup layers absorb margin in Shanghai's premium wellness corridor, where flagship showroom positioning commands brand premiums unattainable in provincial markets. Three-tier pricing structure across premium therapeutic-grade, standard residential, and economy portable levels separates NMPA-certified clinical devices from consumer-grade alternatives. Pricing pressure stems from copper and neodymium spot volatility, compressing mid-tier manufacturers lacking forward purchase agreements. Young professionals in Hangzhou exhibit lowest price sensitivity through subscription financing instruments, while seniors in Shandong's third-tier cities drive volume at economy tiers.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Guangdong spa chains and Beijing physiotherapy clinic networks. Component sourcing concentrates in China for rare-earth magnets and motor assemblies, South Korea for precision bearings, and Japan for thermal-pneumatic control systems. Critical dependencies include neodymium permanent magnets, lithium-ion cells, and heated roller subassemblies. Single-region vulnerability in the Pearl River Delta exposes half of domestic OEM capacity to weather and logistics disruptions. Distribution runs through wellness-focused e-commerce platforms, flagship retail corridors, and clinical procurement channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's massage equipment market reads as a late-cycle quality story, with demand migration toward NMPA-certified therapeutic-grade specifications rewarding clinical evidence investment and penalizing undifferentiated commodity positioning.
For Market Incumbents: Deepen backward integration into motor and controller production to insulate margins from rare-earth price volatility. Secure exclusive distribution partnerships with Beijing and Shenzhen physiotherapy clinic networks before emerging entrants complete clinical validation. Prioritize NMPA Class II certification maintenance as SAMR tightens advertising substantiation rules, converting regulatory compliance into competitive moats against unverified therapeutic claims. For New Entrants and Emerging Players: E-commerce wellness platforms offer lowest customer acquisition costs for portable device launches targeting health enthusiasts. Chengdu-Chongqing's undersaturated premium retail presence provides first-mover positioning before coastal brands complete western distribution buildout. Pursue smart home ecosystem integration through MIIT-certified IoT protocols, capturing tech-forward households already invested in connected appliance platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among Jiangsu-based contract manufacturers repositioning toward branded output with established component sourcing control. Long-term viability favors clinical-grade portable specialists with NMPA pathways and physiotherapy clinic validation over undifferentiated consumer appliance producers. Monitor NMPA medical device reclassification thresholds as the critical inflection signal—shifts toward regulated pathways will accelerate consolidation toward evidence-capable incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Certification Investment | Unlocks reimbursement-linked procurement in Beijing and Shenzhen physiotherapy clinics. |
| Backward Integration into Motor Production | Captures margin compression from neodymium price volatility affecting Guangdong assemblers. |
| Smart Home Ecosystem Integration | Attracts health enthusiasts through MIIT-certified IoT protocol compatibility with Xiaomi platforms. |
| Flagship Retail Corridor Expansion | Creates demonstration effects cascading from Shanghai into Hangzhou and Suzhou premium markets. |
| Clinical Evidence Portfolio Buildout | Accelerates time-to-market advantage as NMPA reclassification compresses pathways for new entrants. |
Research Methodology
Coverage spans China's Yangtze River Delta, Pearl River Delta, Beijing-Tianjin-Hebei, Sichuan-Chongqing, and Shandong Peninsula, with primary inputs from each production cluster and consumption corridor. Primary interviews with massage equipment product managers, NMPA regulatory consultants, physiotherapy clinic procurement officers, and wellness retail category buyers combined with secondary validation from SAMR enforcement bulletins, NMPA medical device registration databases, GB standards documentation, and MIIT IoT certification records. Bottom-up manufacturer shipment data triangulated against top-down retail absorption estimates across tier-one and tier-two city markets.
Granularity-level modeling addressed product type segmentation at the device-format level, application channels at the procurement-pathway level, and end-user demographics at the age-cohort and income-tier intersection. CAGRs derived from fitted growth curves applied to base-year volume estimates, with cross-segment consistency checks across the projection horizon. Industry-specific forecast inputs included NMPA medical device reclassification timelines, rare-earth magnet price trajectory assumptions, and smart home ecosystem penetration rates in coastal provinces.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA regulatory pathway shifts, rare-earth supply disruption events, and SAMR advertising enforcement intensity. Forecasts reflect documented assumptions regarding motor miniaturization cost curves and clinical adoption velocity in physiotherapy settings. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Notebook Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
North America Smartphone Accessories Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Smart Connected TV Market
Consumer Electronics
Europe Mobile Phone Accessories Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
China Smartphone Market