
 Subwoofer Market | 2026-2036
Subwoofer Market Size, Share, and Industry Trends Forecast 2026-2036
Subwoofer Market Analytics
The subwoofer category is consolidating around a sharp split between premium audiophile-grade systems and mass-market commodity units. Harman International leverages its automotive OEM relationships to sustain a dominant position in factory-installed bass systems. Bose Corporation anchors the premium residential segment through proprietary acoustic engineering and controlled retail distribution. Sony Corporation competes across both tiers with manufacturing scale that spans consumer electronics and professional audio channels.
A subwoofer is a loudspeaker engineered to reproduce low-frequency audio signals, typically spanning 20 Hz to 200 Hz, using large-diameter drivers ranging from 8 to 21 inches and dedicated amplifier circuits in active configurations. Its primary commercial purpose is to extend bass response in audio reproduction systems where main speakers cannot physically generate sufficient acoustic output at the lowest octaves. Active subwoofers lead volume shipments due to integrated amplification simplifying system matching, while wireless connectivity features are capturing the fastest growth as consumers eliminate cable runs in modern living spaces. Professional audio applications maintain the highest margin pools because venue installations demand extended low-frequency output and road-worthy enclosure durability.
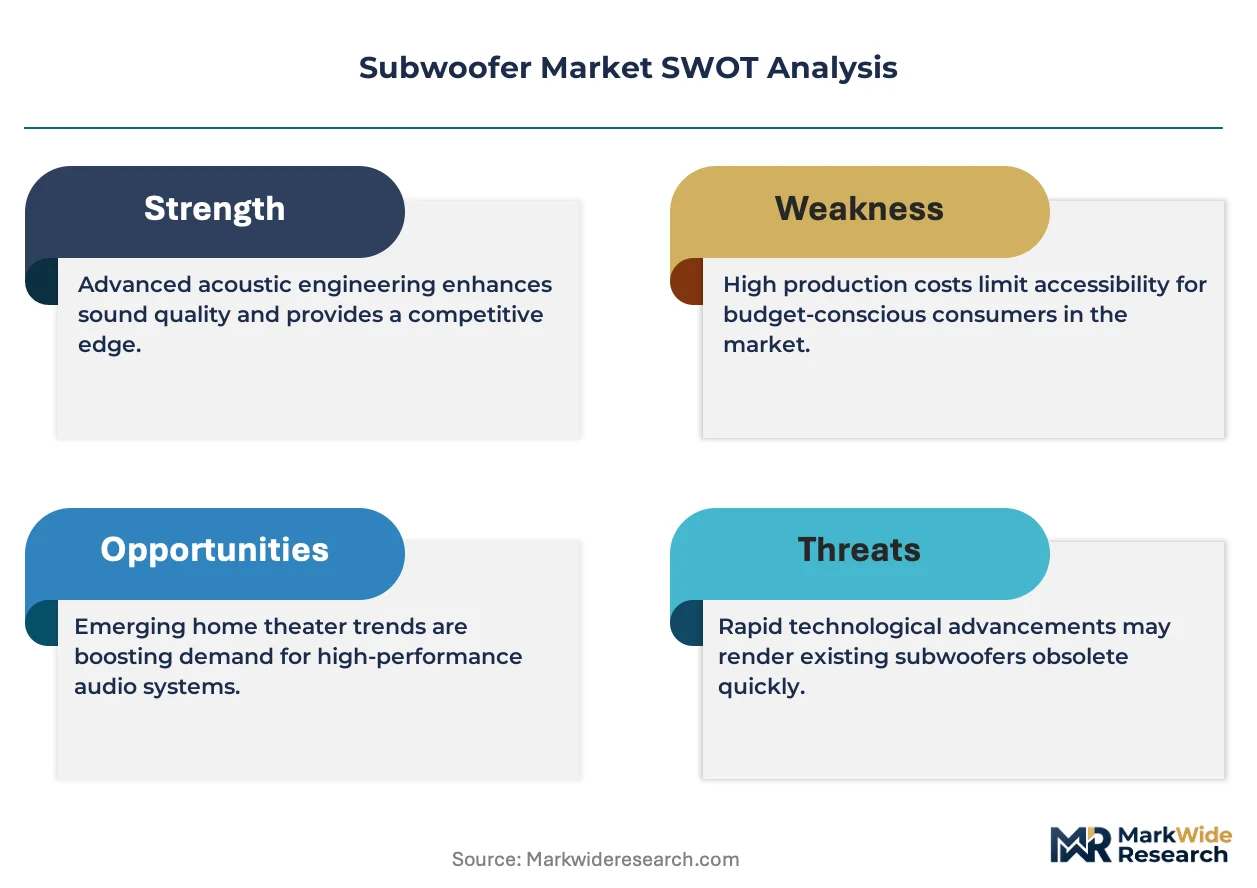
The Federal Communications Commission regulates wireless transmission protocols used in connected subwoofer models, while the EPA oversees hazardous substance limits in electronics manufacturing through RoHS-aligned enforcement. The EU's Ecodesign Directive and CE marking requirements shape product efficiency standards and market access conditions for imported audio equipment. Stakeholders must monitor evolving wireless spectrum allocation decisions and energy efficiency thresholds that will determine which product configurations retain commercial viability in major economies.
Market Dynamics
Wireless connectivity protocols and DSP integration are compressing product development cycles while fragmenting the vendor base between integrated platform specialists and legacy acoustic engineering houses.
Growth Catalysts
- Home Theater Expansion:Residential installations in the United States and Germany are pulling multi-subwoofer configurations into mainstream consumer budgets as streaming content normalizes cinematic bass reproduction.
- RoHS-Aligned Manufacturing:The EPA's hazardous substance enforcement is accelerating material substitutions that reduce enclosure weight and shipping costs across North American supply chains.
- Automotive OEM Integration:Factory-installed bass systems in electric vehicles are creating captive demand for compact, high-efficiency transducer designs that traditional aftermarket channels cannot replicate.
Market Restraints
- Magnet Supply Concentration:Rare earth processing capacity clusters in China, exposing driver manufacturers to export quota volatility and forced technology transfer requirements.
- Wireless Spectrum Friction:The FCC's evolving 6 GHz allocation decisions are creating certification uncertainty for Wi-Fi 6E-enabled subwoofer models targeting the United States market.
- Amplifier Semiconductor Constraints:Class-D IC lead times from foundry partners in Taiwan and South Korea are extending finished goods inventory cycles beyond historical norms.
Strategic Opportunities
- India Residential Penetration:The country's PLI scheme for electronics manufacturing is reducing import duties on driver components, enabling price-competitive positioning in Mumbai and Delhi metro clusters.
- Outdoor Entertainment Systems:Weatherized active subwoofers for patio and poolside installations represent an underserved application with premium pricing tolerance in Australian and Californian markets.
- EU Ecodesign Tailwinds:The directive's standby power thresholds are advantaging designs with integrated signal-sensing auto-on circuits over legacy manual-switch products.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Thiele-Small parameter optimization and enclosure modeling expertise concentrates among retiring specialists in Denmark and Germany, constraining new product velocity.
- Legacy Home Theater Integration:Consumers with pre-HDMI 2.1 receivers face compatibility gaps with eARC-enabled wireless subwoofers, forcing costly adapter solutions or full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subwoofer Market |
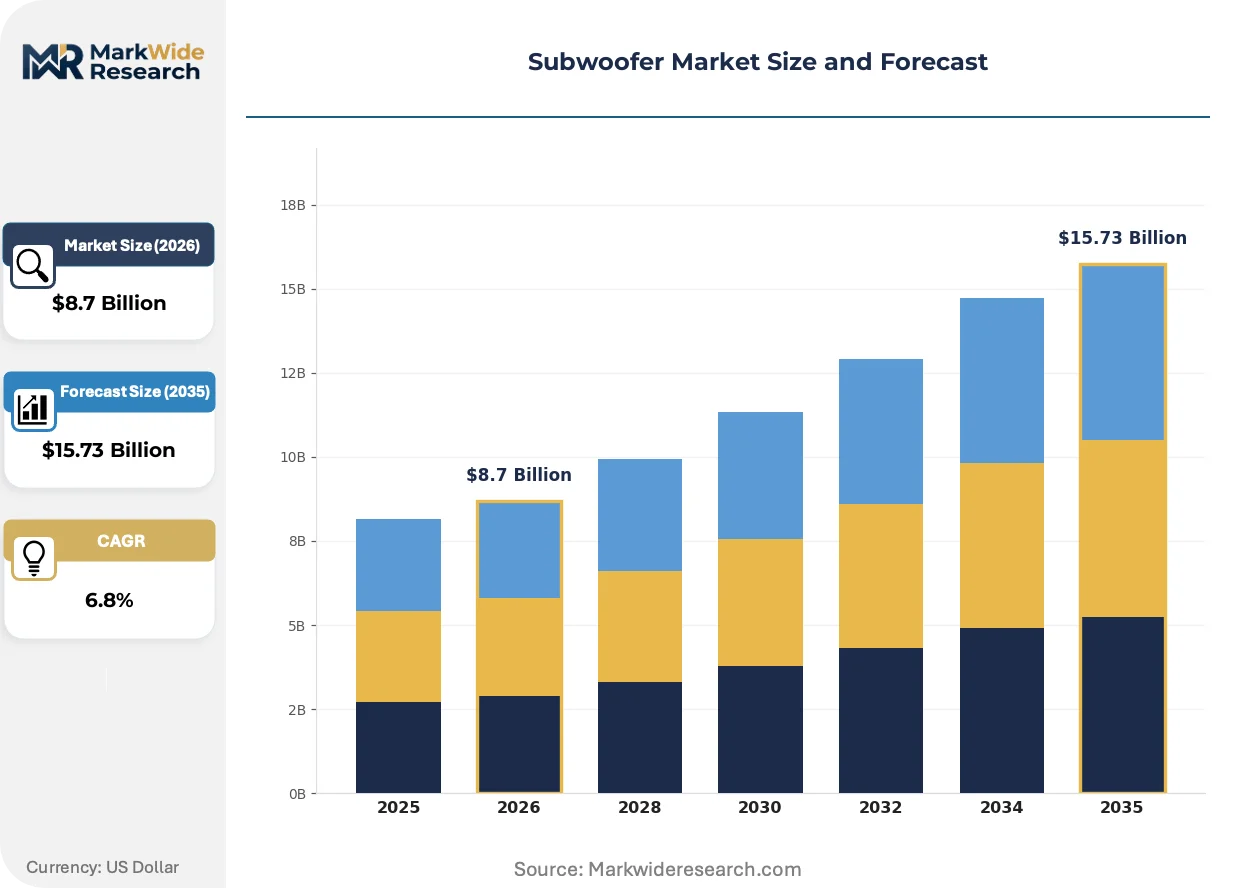
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Subwoofers, Passive Subwoofers, In-Wall Subwoofers, Portable Subwoofers Technological Feature: Wireless Connectivity, High-Level Input, Digital Signal Processing, Zone Control Application: Home Theater, Professional Audio, Automotive, Gaming End User: Residential, Commercial, Audiophiles, Event Venues |
| Companies Covered | Harman International, Bose Corporation, Sony Corporation, Yamaha Corporation, SVS, JL Audio, Polk Audio, Bowers & Wilkins, Klipsch Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subwoofer Market Evolving Landscape
Signal processing architectures are displacing passive crossover networks as the primary value-creation layer, compressing hardware margins while expanding software-defined audio service opportunities.
DSP-enabled room correction is integrating real-time acoustic analysis to eliminate standing wave artifacts without physical repositioning. Residential installers in the United States are specifying these systems for 40% of new home theater commissions. The technology is integrating calibration automation that previously required professional measurement equipment, compressing the addressable market for standalone acoustic consulting services.
The EU's Ecodesign Directive is tightening standby power limits for networked audio equipment below 2 watts, forcing redesigns of always-on wireless subwoofer models. Manufacturers serving European distribution channels are consolidating power supply architectures to meet multi-territory efficiency requirements. Professional audio rental houses in Germany and the Netherlands are accelerating fleet refresh cycles to preempt compliance deadlines.
Direct-to-consumer channel expansion is compressing traditional retail markups while fragmenting brand discovery patterns. Specialty audio retailers in Japan and the United Kingdom are unbundling demonstration services from product sales, charging consultation fees for listening room evaluations. This shift is most visible in premium residential segments where buyers research extensively online before requesting localized installation support.
Subwoofer Market Segmentation
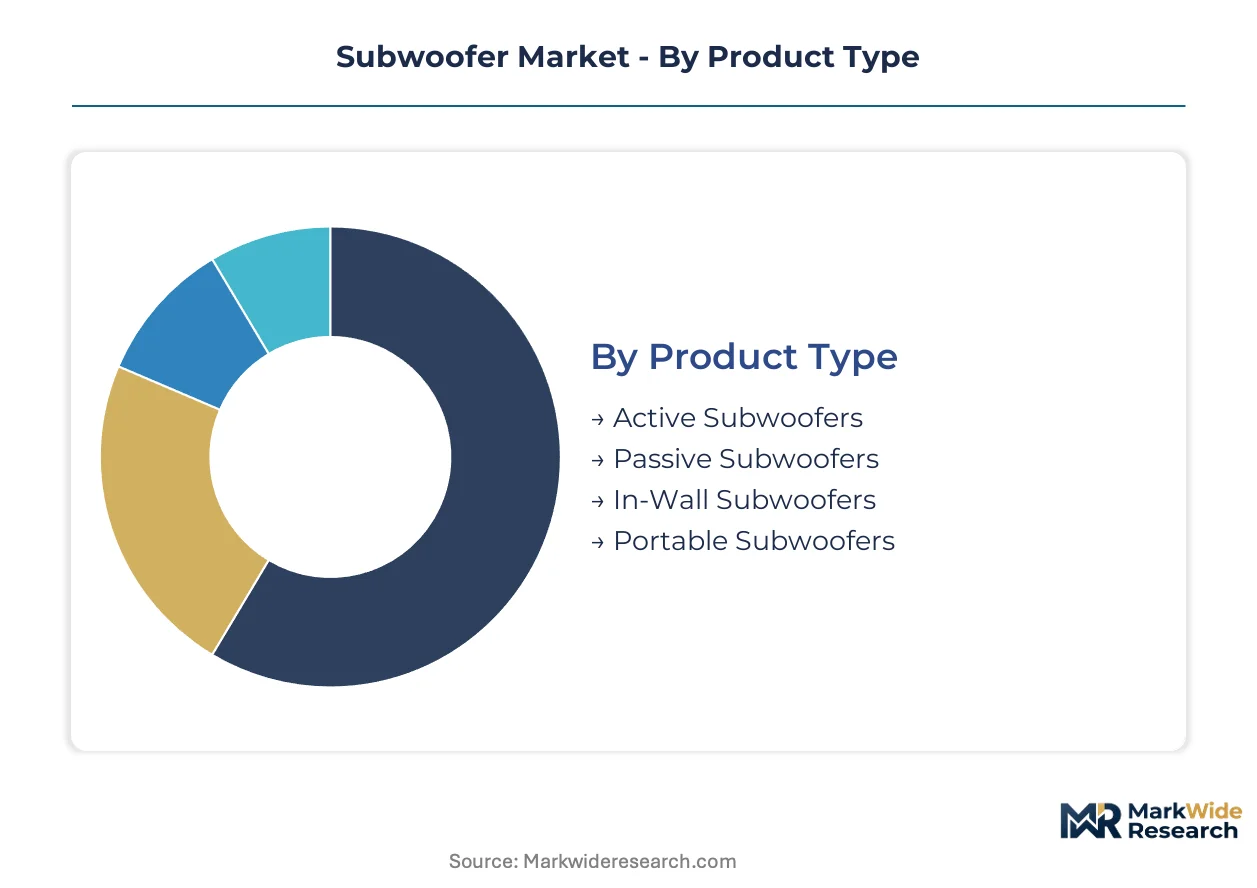
Subwoofer purchasing decisions fragment across installation constraints, connectivity requirements, and acoustic performance thresholds. Each segmentation dimension carries distinct regulatory obligations and margin structures that reshape vendor positioning strategies.
Product Type:
FCC Part 15 certification governs all active and wireless-enabled variants, while passive configurations face lighter electromagnetic compliance burdens. CE marking and RoHS substance restrictions apply uniformly across all four product categories entering European distribution channels.
- Active Subwoofers:Self-amplified designs integrate Class-D power stages and line-level inputs, eliminating external amplifier matching. Residential installations in the United States and Germany favor these units for simplified system integration. RoHS-aligned manufacturing of internal power supplies adds material cost but streamlines North American customs clearance.
- Passive Subwoofers:Unpowered enclosures rely on external amplification, appealing to audiophiles with existing high-current amplifier inventory. Demand concentrates among enthusiast communities in Denmark and Japan where legacy equipment retention rates exceed regional averages.
- In-Wall Subwoofers:Flush-mount designs require UL 2043 plenum certification for commercial installations in the United States. These units sacrifice enclosure volume for architectural integration, limiting low-frequency extension compared to floor-standing alternatives.
- Portable Subwoofers:Battery-powered configurations with Bluetooth transmission target outdoor entertainment use cases in Australian and Californian markets. IPX ratings and lithium transport regulations add compliance layers absent from mains-powered categories.
Active Subwoofers sit at the top of the volume ranking, with Portable Subwoofers climbing the fastest.
Technological Feature:
Feature differentiation now determines price tier placement more than driver diameter or enclosure materials. DSP-enabled variants command manufacturing cost premiums of 15-25% over analog-only designs while reducing return rates through room correction automation.
- Wireless Connectivity:Wi-Fi and proprietary RF protocols eliminate cable runs but introduce FCC and CE radio certification requirements. Residential consumers in Germany and the United States increasingly specify these for renovation-friendly installations. Spectrum allocation uncertainty around 6 GHz bands creates regulatory friction for next-generation product roadmaps.
- High-Level Input:Speaker-level connection interfaces preserve compatibility with legacy receivers lacking dedicated subwoofer outputs. Demand persists among upgrade-oriented consumers in Japan and the United Kingdom with pre-HDMI home theater equipment.
- Digital Signal Processing:Parametric equalization and room correction algorithms compress the need for physical acoustic treatment. Professional audio rental houses in Germany specify DSP-enabled units to reduce venue-specific calibration time.
- Zone Control:Multi-room bass management via app-based interfaces targets whole-home audio installations. These features require continuous network connectivity, triggering EU Ecodesign standby power thresholds below 2 watts.
Wireless Connectivity commands the largest installed base, while Digital Signal Processing expands most quickly.
Application:
Application segmentation separates consumer convenience priorities from professional durability requirements. Automotive integration demands thermal management and space constraints that residential designs ignore.
- Home Theater:Multi-subwoofer configurations for low-frequency modal averaging dominate residential specification in the United States. Streaming service content with dedicated LFE channels drives replacement cycles.
- Professional Audio:Road-worthy enclosures with tour-grade hardware and extended SPL capability serve rental houses and fixed installations. German and Dutch venues lead refresh cycles to meet EU Ecodesign compliance deadlines.
- Automotive:Factory-installed systems in electric vehicles require compact, high-efficiency transducers that aftermarket channels struggle to replicate. OEM relationships with tier-one suppliers create captive demand pools.
- Gaming:Near-field desktop configurations with USB connectivity target PC and console users. Haptic feedback integration distinguishes this segment from traditional audio reproduction.
Home Theater maintains volume leadership, with Automotive gaining share fastest.
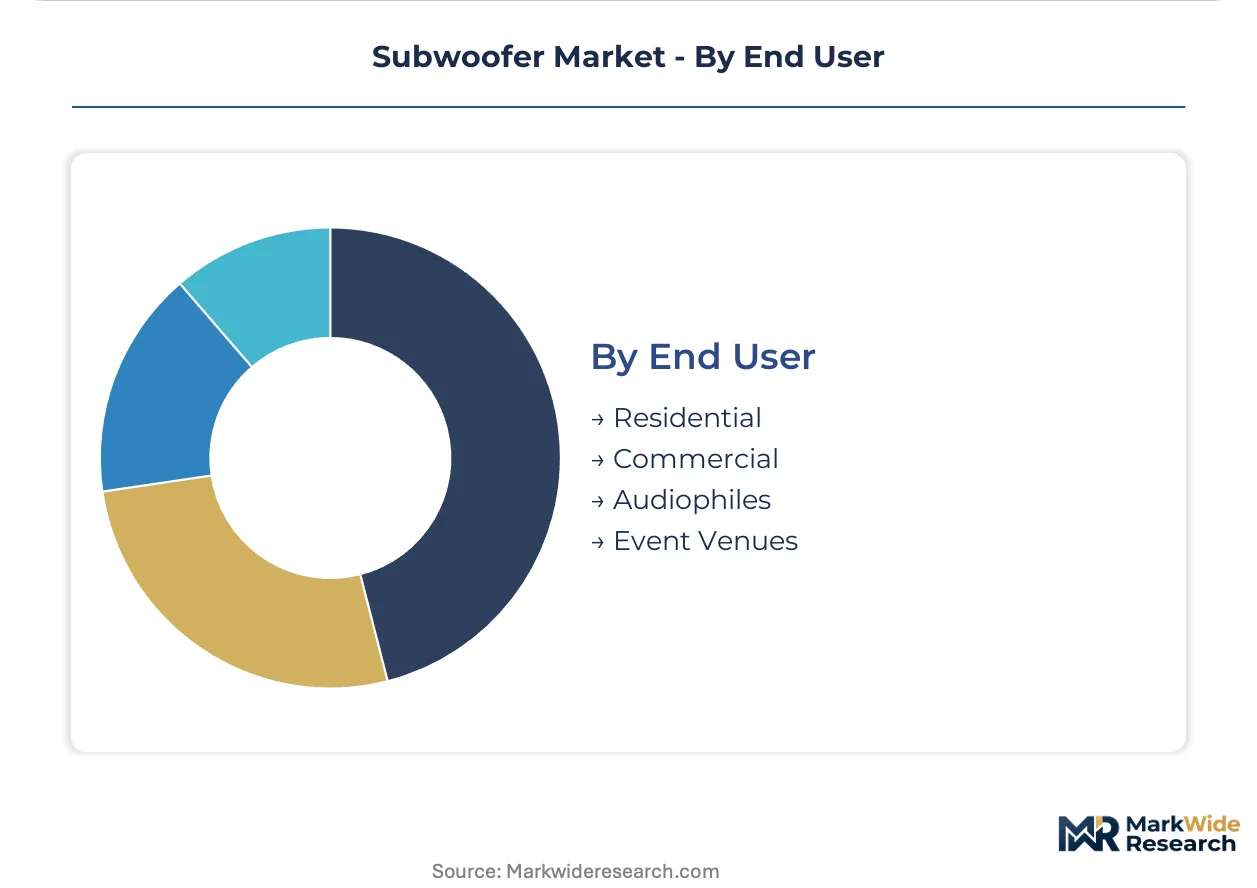
End User:
End user categories separate price-insensitive performance seekers from specification-driven commercial buyers. Each segment imposes distinct service and warranty expectations that reshape distribution economics.
- Residential:Mainstream consumers prioritize plug-and-play simplicity and aesthetic integration over absolute technical performance. Online research patterns compress traditional retail demonstration value.
- Commercial:Corporate boardrooms, hospitality venues, and retail spaces demand installation reliability and multi-year service contracts. BIS certification requirements affect import positioning for Indian commercial projects.
- Audiophiles:Performance-focused buyers accept complex setup procedures and premium pricing for measured low-distortion output. This segment retains preference for passive configurations with external amplification.
- Event Venues:Concert halls, theaters, and temporary event infrastructure require weatherized, high-output systems with rapid deployment hardware. Rental depreciation schedules accelerate replacement cycles versus installed residential equipment.
Residential dominates unit shipments, with Event Venues expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acoustic engineering talent concentrates in Denmark and Germany, where Thiele-Small parameter optimization expertise anchors driver design capabilities. This workforce distribution shapes regional production advantages and constrains new product velocity elsewhere.
United States
Residential home theater installations in California and Texas metro areas pull multi-subwoofer configurations into mainstream consumer budgets. The FCC regulates wireless transmission protocols under Part 15 certification requirements for connected models. Los Angeles and Austin clusters host professional audio rental houses accelerating fleet refresh cycles to meet efficiency deadlines.
Germany
Professional audio venues in Berlin and Hamburg demand road-worthy enclosures with extended SPL capability for touring applications. The EU Ecodesign Directive tightens standby power limits below 2 watts for networked equipment entering European distribution. Bavaria-based engineering houses concentrate DSP integration expertise for room correction automation.
China
Manufacturing scale spans consumer electronics and professional audio channels, with rare earth processing capacity clustering around domestic magnet supply. The Ministry of Industry and Information Technology oversees GB standards alignment for electronics production. Shenzhen and Dongguan hubs drive component cost compression through vertically integrated supply chains.
Japan
Audiophile communities in Tokyo and Osaka retain preference for passive configurations with external amplification, sustaining demand for legacy-compatible designs. METI administers JIS standards for audio equipment safety and performance. Specialty retailers in the Kanto region unbundle demonstration services from product sales, charging consultation fees for listening room evaluations.
India
The PLI scheme for electronics manufacturing reduces import duties on driver components, enabling price-competitive positioning in Mumbai and Delhi metro clusters. BIS certification requirements affect commercial project specifications for corporate and hospitality installations. Karnataka and Tamil Nadu states attract assembly operations targeting residential penetration in tier-one cities.
Subwoofer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the subwoofer category, creating a tiered structure where manufacturing scale separates premium positioning from commodity volume. The vendor base consolidates around integrated platform specialists leveraging DSP architectures and legacy acoustic engineering houses defending driver optimization expertise. Three archetypes dominate: automotive OEM-captive suppliers, premium residential audio brands, and manufacturing-scale conglomerates spanning multiple price tiers. Competitive moves concentrate on strategic partnerships for wireless protocol licensing and portfolio diversification into outdoor and portable categories.
Within the automotive-captive tier, Harman International and Bose Corporation occupy positions shaped by factory-installed system relationships with electric vehicle manufacturers. Sony Corporation represents the manufacturing-scale archetype, competing across both premium and mass-market tiers through consumer electronics and professional audio channel breadth. These three entities exemplify how vertical integration depth and distribution control determine margin capture in a market fragmenting between wireless convenience features and measured acoustic performance.
| Leading Market Players |
|---|
| Harman International |
| Bose Corporation |
| Sony Corporation |
| Yamaha Corporation |
| SVS |
| JL Audio |
| Polk Audio |
| Bowers & Wilkins |
| Klipsch Group |
| Others |
Value Network & Pricing Analysis
Rare earth magnet costs originating in Chinese processing facilities cascade through driver manufacturing tiers, compressing margins on mass-market active subwoofers while premium passive configurations in Japan and Denmark retain pricing power through acoustic engineering scarcity.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes specialty audio retailers in Japan and the United Kingdom from direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels reflects DSP integration depth and wireless certification tiers. Cost compression in the portable segment intensifies because lithium transport regulations and IPX rating compliance add fixed overhead. Residential mainstream buyers exhibit highest price sensitivity, while event venue procurement teams prioritize durability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with neodymium magnet processing concentrated in China, exposing driver manufacturers to export quota volatility. Taiwan and South Korea anchor Class-D amplifier IC fabrication, while enclosure materials draw from North American and European timber and composite suppliers. Tariff exposure runs through rare earth supply chains. Distribution runs through OEM captive channels for automotive, direct-to-consumer for residential, and rental house networks for professional audio.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where the EU Ecodesign Directive's tightening standby power thresholds below 2 watts force redesign cycles that favor integrated platform specialists over legacy acoustic houses.
For Market Incumbents: Deploy DSP architecture licensing as the primary lever to defend against emerging platform specialists. Deepen backward integration into driver magnet supply through captive offtake agreements with Chinese rare earth processors. Accelerate certification investment for Wi-Fi 6E protocols before FCC spectrum allocation finalizes.
For New Entrants and Emerging Players: Launch via outdoor entertainment system specialization targeting Australian and Californian patio installations where weatherized active designs command premium positioning. Exploit underpenetrated India residential markets leveraging PLI scheme duty reductions on driver components. Pursue direct-to-consumer channel control to bypass retail markup compression.
For Investors and Strategic Acquirers: Consolidation pressure builds where acoustic engineering talent scarcity in Denmark and Germany constrains new product velocity for mid-scale competitors. Long-term viability favors asset-light designers with DSP platform control over capital-heavy enclosure manufacturers. Monitor FCC 6 GHz allocation decisions as inflection indicator for wireless-enabled product roadmaps.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Protocol Licensing Partnership | Secures FCC Part 15 certification pathways for Wi-Fi 6E-enabled residential models. |
| Rare Earth Magnet Supply Agreement | Locks neodymium pricing through Chinese processor relationships amid export quota volatility. |
| DSP Platform Acquisition | Integrates room correction automation that compresses standalone acoustic consulting services. |
| Outdoor Product Line Extension | Captures premium pricing tolerance in Australian and Californian patio entertainment markets. |
| EU Ecodesign Compliance Redesign | Preempts standby power threshold enforcement through auto-on circuit integration. |
Research Methodology
Bottom-up residential and professional audio modeling reconciled against top-down driver component supply tracking forms the analytical core. Primary interviews with acoustic engineering specialists, OEM procurement managers, rental house fleet directors, and specialty audio retailers combined with secondary validation from FCC certification databases, EU Ecodesign directive filings, and customs trade records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of home theater installation rates and automotive OEM integration patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, connectivity feature, application, and end-user category. CAGRs derived from regression analysis of shipment volumes against macroeconomic indicators and regulatory milestone timing. Industry-specific forecast inputs incorporate rare earth pricing volatility indices and wireless spectrum allocation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden FCC spectrum reallocation or Chinese export quota restriction scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
Ultra-Portable Speakers Market
Consumer Electronics
North America Smartphone Accessories Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
Vape Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Headphones Market
Consumer Electronics
Laptop Accessories Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market
Consumer Electronics
Action Camera Market