
 Outdoor Sports Apparel Market | 2026-2036
Outdoor Sports Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Sports Apparel Market Intelligence
Modular layering systems is restructuring how outdoor consumers build their wardrobes across seasons. Patagonia anchors its market position through transparent supply chain documentation and repair-first service models. Columbia Sportswear Company leverages its Interchange system to capture buyers seeking adaptable three-in-one jacket configurations. Arc'teryx specializes in alpine-specific hardshell engineering that commands premium positioning among technical users.
Outdoor sports apparel encompasses garments engineered with waterproof-breathable membranes, seam-taped construction, and body-mapped insulation zones designed to manage thermoregulation during high-exertion activities in variable weather conditions. The primary commercial purpose is to replace cotton and basic synthetics with performance textiles that reduce hypothermia risk, moisture accumulation, and abrasion failure during extended wilderness exposure. Jackets carrying the highest margin pools as technical hardshell and insulated categories justify premium pricing through membrane licensing costs and complex manufacturing. Merino wool is gaining share as a base layer material due to its odor-resistance and moisture-wicking properties that outperform synthetic alternatives across multi-day trips. Online Retail is capturing growing volume as direct-to-consumer platforms enable brands to bypass wholesale markups while collecting usage data for product development.
The EU Green Deal and REACH chemical restrictions are tightening permissible substance lists for DWR treatments and membrane adhesives, forcing reformulation of waterproofing chemistries across European supply chains. The EPA's PFAS regulations in the United States are accelerating industry transition to fluorine-free water repellency technologies ahead of compliance deadlines. China's GB standards and dual carbon goals are raising energy efficiency requirements for textile dyeing and finishing operations that supply synthetic fabrics. Stakeholders must monitor how diverging regional chemical regimes fragment product portfolios and determine where localized manufacturing investment becomes necessary to maintain market access.
Market Dynamics
The EU Green Deal's textile sustainability mandates are forcing a wholesale chemistry reformulation across waterproof-breathable membranes and DWR treatments, compressing legacy supply chains while opening certification-driven purchasing channels.
Growth Catalysts
- REACH chemical restrictions:ECHA's tightening PFAS limits are accelerating fluorine-free water repellency R&D, creating first-mover advantages for brands with compliant product lines.
- Trail running technicalization:Alpine clubs in Germany and Austria are driving replacement cycles for lightweight hardshells with body-mapped ventilation.
- Recycled polyester scaling:Post-consumer plastic supply agreements with EU waste processors are securing feedstock for circular production models.
Market Restraints
- Membrane licensing costs:Gore-Tex and ePTFE patent holders extract royalties that compress margins on mid-tier jacket categories.
- Dyeing energy intensity:China's GB standards on textile finishing are raising synthetic fabric input costs for brands dependent on Yangtze River basin suppliers.
- Merino wool supply concentration:Australian and New Zealand wool processors control premium fiber grading, creating price volatility for base layer manufacturers.
Strategic Opportunities
- Repair-first service models:Patagonia's Worn Wear platform demonstrates how resale and refurbishment can capture lifetime value from technical outerwear.
- Biodegradable treatments:EU Ecolabel certification pathways are opening for brands investing in enzymatic hydrolysis research for synthetic fiber end-of-life.
- Direct-to-consumer platforms:Usage data collection from owned e-commerce is enabling predictive sizing and regional climate-specific product drops.
Industry Challenges
- Seam-taping technician scarcity:Specialized manufacturing skills for three-layer laminate construction are concentrating in Alpine European factory clusters.
- Dual chemistry inventory:Diverging EPA PFAS timelines and EU REACH substance lists are fragmenting product portfolios and complicating forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Sports Apparel Market |
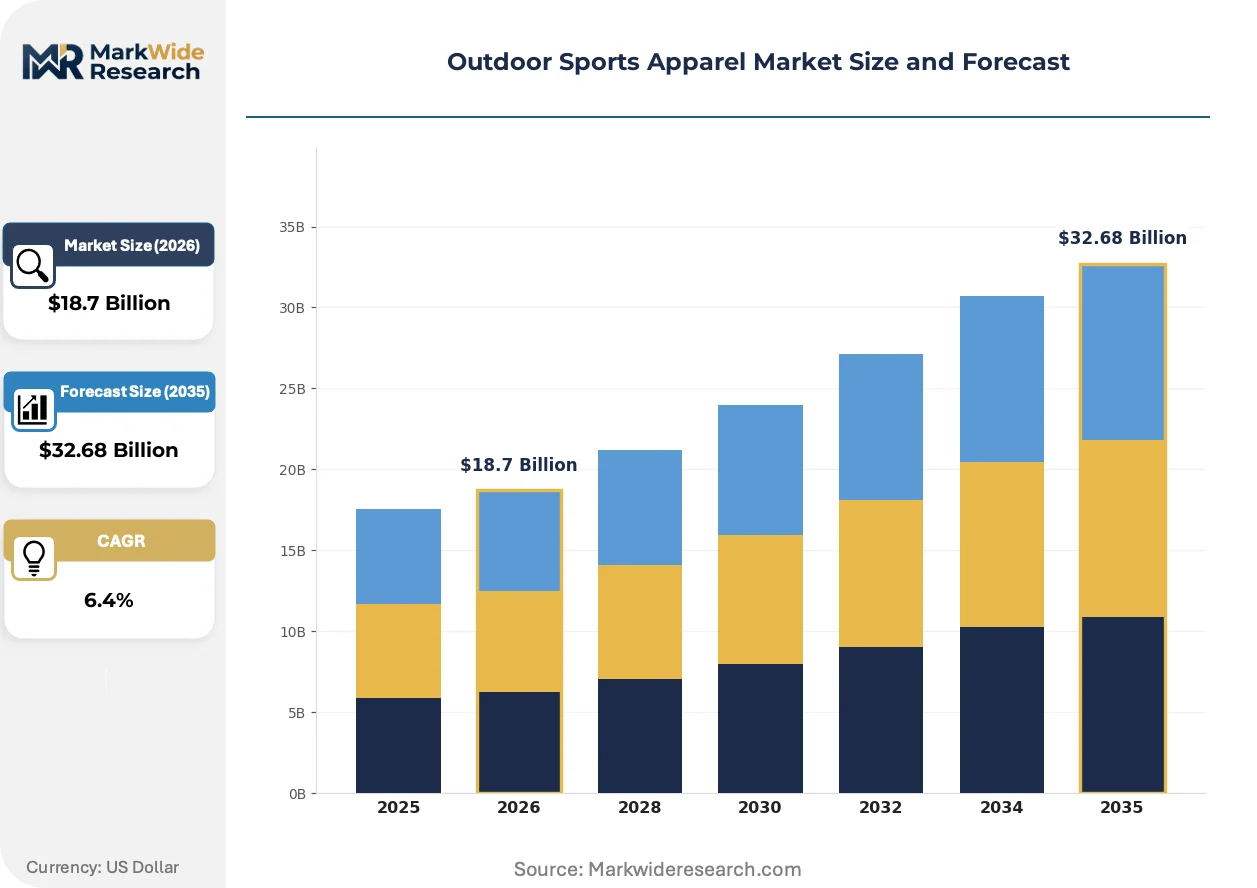
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-shirts, Jackets, Shorts, Footwear Material: Polyester, Nylon, Cotton, Merino Wool End User: Men, Women, Kids, Athletes Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | The North Face, Patagonia, Columbia Sportswear Company, Adidas, Nike, Under Armour, Arc'teryx, Lululemon Athletica, Anta Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Sports Apparel Market Strategic Shifts & Innovations
Modular layering architectures are replacing standalone garment purchases as athletes demand season-spanning versatility from fewer pieces. Three convergent developments are compressing traditional category boundaries while elevating performance expectations.
Bio-based membrane technologies are decentralizing waterproof-breathable performance away from petroleum-derived ePTFE dependence. Startups and established suppliers alike are commercializing polyurethane alternatives derived from castor oil and algae biomass. Alpine guide services and search-and-rescue teams are field-testing these materials under extended exposure conditions. The structural consequence is decentralizing membrane supply away from concentrated patent holders toward distributed biopolymer processors.
EPA PFAS regulations are accelerating industry transition to C6 and fluorine-free water repellency chemistries ahead of 2025 compliance deadlines. Formulation labs are racing to match the durability of legacy C8 treatments without the environmental persistence. Hardshell and insulated jacket categories face the steepest reformulation costs, with brands holding dual inventory for US and EU markets.
Rental and subscription models are capturing trial-oriented outdoor participants who resist premium price points for infrequent use. Specialty retailers in Germany's Alpine regions are piloting seasonal hardshell leasing programs backed by professional cleaning infrastructure. This behavioral shift is most visible among urban-based trail runners and backcountry skiers who prioritize access over ownership.
Outdoor Sports Apparel Market Segmentation
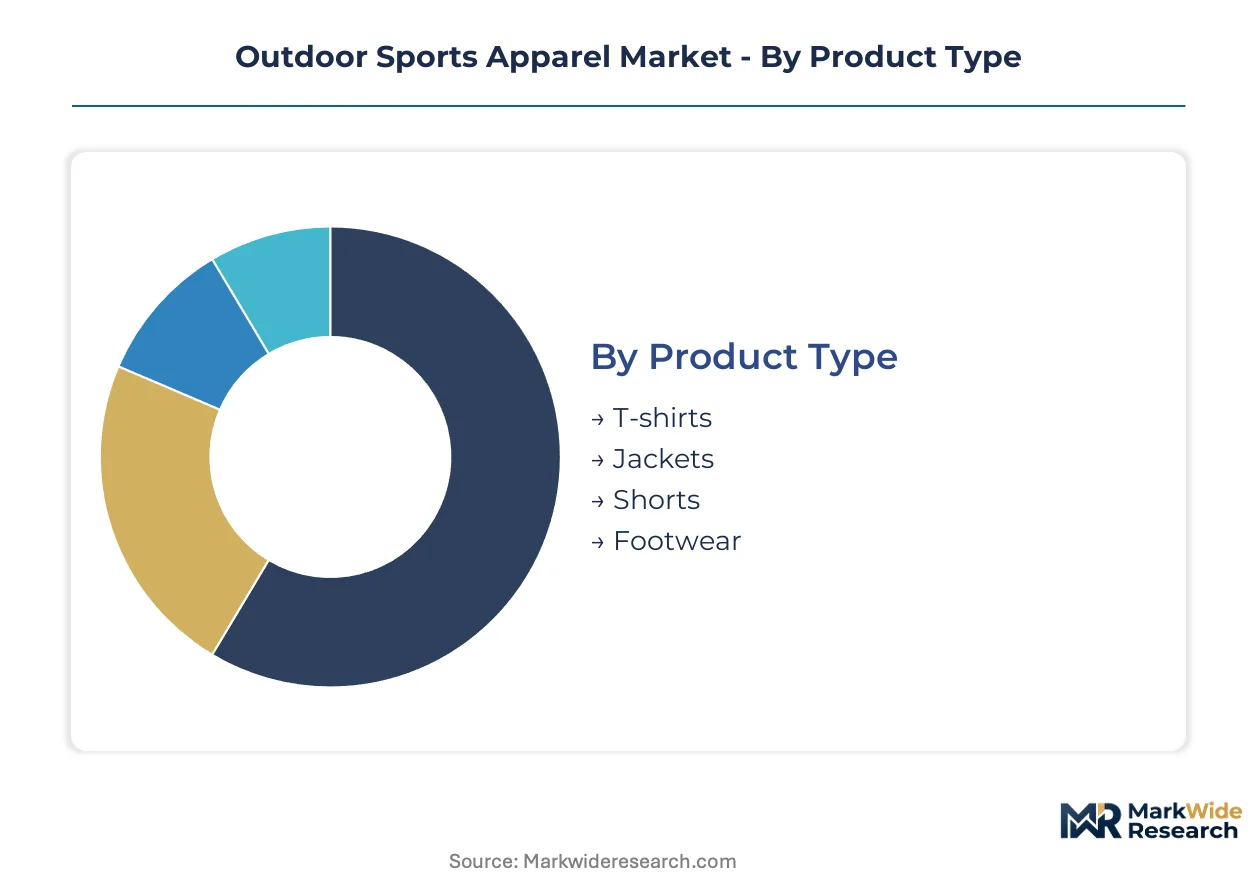
Segmentation in outdoor sports apparel reveals how technical specifications, material science, and channel economics fragment purchasing behavior across user profiles. Distinct performance requirements separate casual trail walkers from alpine professionals, while sustainability preferences increasingly split material choices along circularity credentials.
Product Type:
Jackets function as standalone technical systems with membrane-dependent waterproofing, while T-shirts and shorts operate as embedded layering components within modular wardrobes.
- Jackets:Three-layer laminate construction with seam-taped waterproof-breathable membranes dominates technical hardshell and insulated categories. Demand concentrates in Germany's Alpine regions where local clubs drive premium replacement cycles for body-mapped ventilation systems.
- Footwear:Mid-cut hiking boots and trail running shoes integrate waterproof-breathable booties with lug-patterned outsoles engineered for specific terrain. Athletes in Austria's backcountry skiing communities prioritize aggressive tread compounds for mixed snow-rock conditions.
- T-shirts:Moisture-wicking synthetic or merino wool base layers manage thermoregulation during high-exertion activities.
- Shorts:Lightweight nylon or polyester constructions with gusseted crotches for range of motion during scrambling.
Jackets lead volumes today; footwear is gaining share fastest.
Material:
Cost tiers separate petroleum-derived synthetics from premium natural fibers, with recycled feedstocks creating a mid-tier positioning around circularity certification.
- Polyester:Dominant synthetic fiber derived from petroleum or post-consumer plastic feedstocks, engineered for moisture-wicking and quick-dry properties. Recycled polyester supply agreements with EU waste processors are securing feedstock for circular production models.
- Merino Wool:Premium natural fiber from Australian and New Zealand processors, prized for odor-resistance and moisture management across multi-day trips. Alpine guide services specify merino base layers for extended wilderness exposure.
- Nylon:High-tenacity synthetic used in outer shell fabrics for abrasion resistance against rock and brush.
- Cotton:Traditional fiber largely displaced from technical applications due to moisture retention and hypothermia risk.
Polyester leads volumes today; merino wool is climbing the fastest.
End User:
Application intensity varies from recreational weekend use to professional mountain rescue, with athletes representing the most specification-sensitive purchasing segment.
- Men:Largest addressable base with established sizing standards and established brand loyalties in technical categories.
- Women:Fast-expanding segment with demand for anatomically patterned harness-compatible jackets and proportioned layering systems.
- Athletes:Professional and competitive users requiring certified protective equipment for sanctioned events and expedition insurance.
- Kids:Growth-out replacement cycles with emphasis on durability and adjustable features for multi-season wear.
Men lead volumes today; women is expanding most quickly.
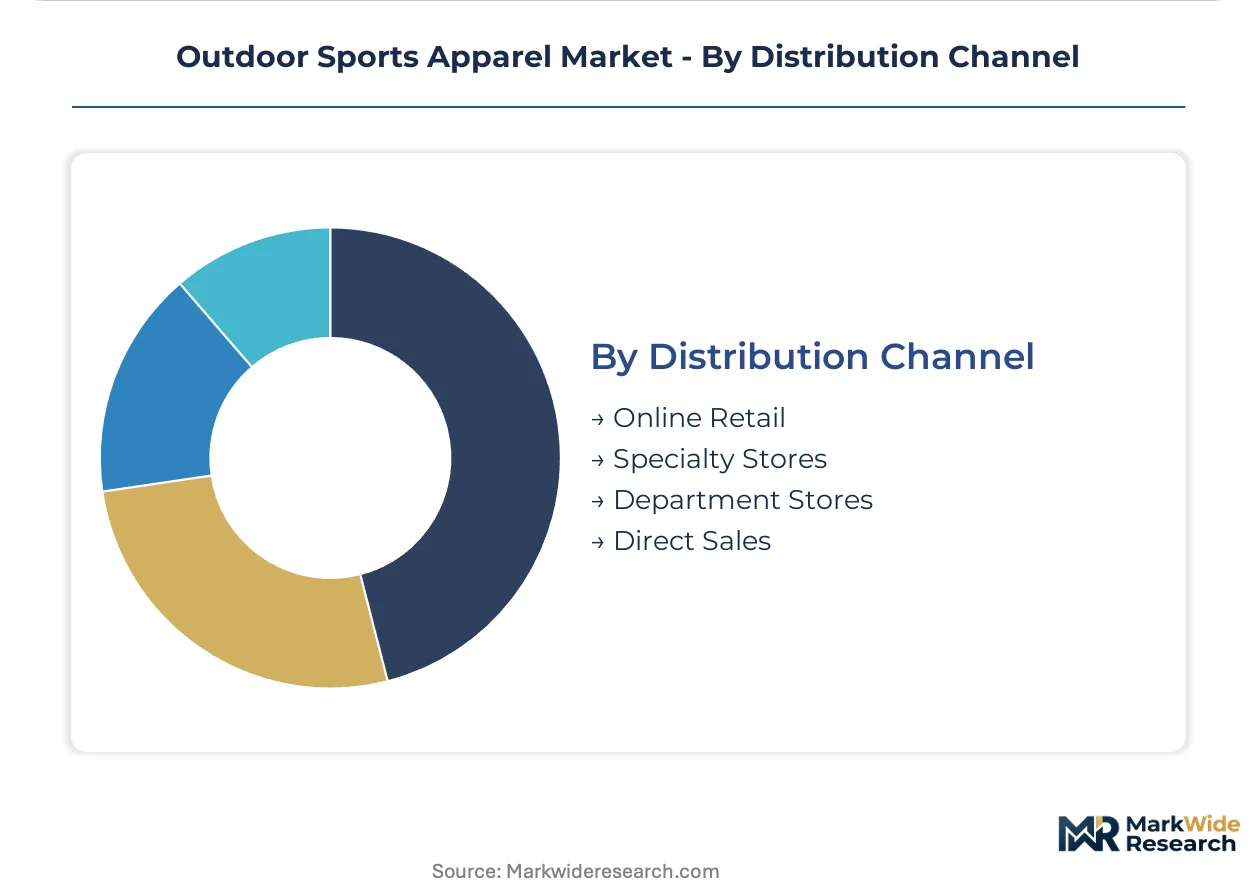
Distribution Channel:
Margin structures diverge sharply between wholesale-dependent retail and direct-to-consumer platforms that capture usage data for product development.
- Online Retail:Brand-owned e-commerce and marketplace platforms enabling predictive sizing and regional climate-specific product drops. Direct-to-consumer channels bypass wholesale markups while collecting behavioral data.
- Specialty Stores:Independent retailers in Alpine regions providing technical fitting expertise and seasonal leasing programs for trial-oriented participants.
- Department Stores:Mass-market access for entry-level synthetic basics with limited technical specification depth.
- Direct Sales:Guide service partnerships and expedition outfitter relationships for bulk professional procurement.
Specialty stores lead volumes today; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical outerwear originated in Alpine European climbing communities during the mid-twentieth century, with German and Austrian manufacturers pioneering seam-taped construction methods that remain foundational today.
United States
Trail running participation in Colorado and the Pacific Northwest drives lightweight hardshell demand among high-exertion athletes. EPA PFAS regulations are accelerating fluorine-free water repellency transitions ahead of compliance deadlines. Seattle and Portland host concentrated brand headquarters where direct-to-consumer platforms collect usage data for predictive sizing.
Germany
Alpine clubs in Bavaria and Baden-Württemberg enforce premium replacement cycles for body-mapped ventilation systems among technical users. EU Green Deal textile sustainability mandates are forcing chemistry reformulation across waterproof-breathable membranes. Munich anchors manufacturing clusters where seam-taping technician skills concentrate for three-layer laminate construction.
China
Domestic outdoor participation growth in Sichuan and Yunnan provinces expands mid-tier synthetic apparel demand. GB standards on textile dyeing and finishing are raising energy efficiency requirements for Yangtze River basin suppliers. Shanghai and Shenzhen host integrated supply chains where recycled polyester feedstock agreements with EU waste processors are negotiated.
Japan
Urban trail running communities in Tokyo and Osaka prioritize packable emergency shells for mountain-adjacent training. METI industrial policy supports domestic membrane R&D for fluorine-free alternatives. Nagoya and Osaka manufacturing bases specialize in precision seam-taping for export-grade technical outerwear.
Australia
Multi-day bushwalking culture in New South Wales and Victoria elevates merino wool base layer specification among extended wilderness users. TGA-aligned chemical safety assessments influence DWR treatment import approvals. Melbourne hosts specialty retail clusters where seasonal hardshell leasing programs target trial-oriented participants.
Outdoor Sports Apparel Market Key Industry Players
The competitive structure tilts toward brand-led differentiation rather than manufacturing scale. Premium positioning depends on membrane licensing relationships and repair-service infrastructure rather than unit cost optimization. Three archetypes dominate: heritage Alpine specialists with vertical supply chain control, diversified sportswear conglomerates leveraging apparel cross-selling, and direct-to-consumer insurgents capturing data-rich customer relationships. Capacity expansion and strategic partnership formation represent the primary competitive vectors as chemistry reformulation costs reshape supplier economics.
Within the heritage specialist tier, Patagonia and Arc'teryx exemplify divergent approaches to premium positioning—one through transparent supply chain documentation and resale infrastructure, the other through alpine-specific engineering depth. Columbia Sportswear Company occupies a position bridging technical credibility and accessible price points through modular interchange systems. These three anchors demonstrate how brand origin stories and service model investments create defensive moats against commodity synthetic competition.
| Leading Market Players |
|---|
| The North Face |
| Patagonia |
| Columbia Sportswear Company |
| Adidas |
| Nike |
| Under Armour |
| Arc'teryx |
| Lululemon Athletica |
| Anta Sports |
| Others |
Cost & Logistics Intelligence
Membrane-licensing cost bifurcation separates premium hardshell manufacturers from commodity outerwear producers, with this tier divergence manifesting in both royalty-inflated retail pricing and concentrated supply chain control over ePTFE sourcing. Pricing power accumulates with patent holders while mid-tier brands absorb margin compression from dual-chemistry inventory requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with differentiation driven by membrane certification grade and repair-service bundling. Price erosion runs through mid-tier jacket categories as fluorine-free reformulation costs compress margins without commensurate retail uplift. Athletes and alpine professionals show lowest price sensitivity, while recreational trail walkers resist premium positioning for infrequent-use garments.
Supply Chain Analysis
Dual-sourcing requirements for waterproof-breathable membranes mandate multi-supplier qualification across German, Vietnamese, and Chinese manufacturing bases. Raw material dependencies center on petroleum-derived polyester chips, Australian merino wool grading, and castor-oil biopolymer feedstocks. Single-source vulnerability concentrates in Alpine European seam-taping technician clusters. Distribution runs through brand-owned direct-to-consumer platforms and specialty retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in circular service models and premium-tier membrane licensing, justified by repair-first economics reducing customer acquisition costs.
For Market Incumbents: Anchor defensive positioning through captive supply of fluorine-free DWR chemistries and backward integration into recycled polyester feedstock processing. Consolidate seam-taping technician capacity in Munich manufacturing clusters to offset labor scarcity. Deepen vertical control over membrane R&D partnerships before biopolymer alternatives commoditize waterproof-breathable performance.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route into trial-oriented urban trail runners resistant to ownership premiums. Target Germany's Alpine club networks with seasonal leasing programs backed by professional cleaning infrastructure. White-space exists in women's anatomically patterned harness-compatible jackets where specification depth remains underdeveloped.
For Investors and Strategic Acquirers: Consolidation pressure builds where repair-service infrastructure and transparent supply chain documentation create defensive moats against commodity synthetic competition. Viable acquisition targets combine heritage Alpine engineering credibility with direct-to-consumer data assets. Watch fluorine-free chemistry durability benchmarks as the inflection signal for membrane technology substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Chemistry Transition | EPA PFAS deadlines and EU REACH restrictions mandate C6 and fluorine-free DWR reformulation across hardshell categories. |
| Repair-First Service Platform | Patagonia's Worn Wear model demonstrates lifetime value capture through resale infrastructure and refurbishment economics. |
| Biopolymer Membrane R&D | Castor-oil and algae-derived polyurethane alternatives decentralize supply away from concentrated ePTFE patent holders. |
| Direct-to-Consumer Channel Expansion | Owned e-commerce platforms bypass wholesale markups while collecting usage data for predictive sizing and regional product drops. |
| Recycled Polyester Supply Agreement | Post-consumer plastic partnerships with EU waste processors secure circular production feedstock against virgin polymer volatility. |
Research Approach
Direct dialogue with brand sustainability officers, Alpine club procurement managers, seam-taping factory supervisors, and specialty retail buyers grounded the qualitative foundation. Secondary validation drew from EU Ecolabel certification databases, EPA PFAS regulatory filings, ECHA REACH substance restrictions, and customs trade data for synthetic fiber imports. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Segment-level outputs reflect disaggregation by product type, material science tier, end-user intensity, and distribution channel economics over the projection horizon. CAGRs derived from trend extrapolation of trail running participation rates, replacement cycle compression, and chemistry reformulation cost curves. Industry-specific inputs incorporated EU Green Deal compliance timelines and membrane patent expiration schedules.
The model assumes a particular technology adoption path; alternative pathways for bio-based membrane commercialization would alter the outlook for petroleum-dependent supply chains. Deviation in EPA PFAS enforcement timelines or EU Ecolabel certification uptake would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Boot Market
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
Football Kits Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Lingerie Market
Apparel & Footwear
Polo Shirt Market
Apparel & Footwear
Secondhand Apparel Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Vegan Women's Fashion Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Compression Wear and Shapewear Market