
 Europe Denim Jeans Market | 2026-2036
Europe Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Denim Jeans Market Insights
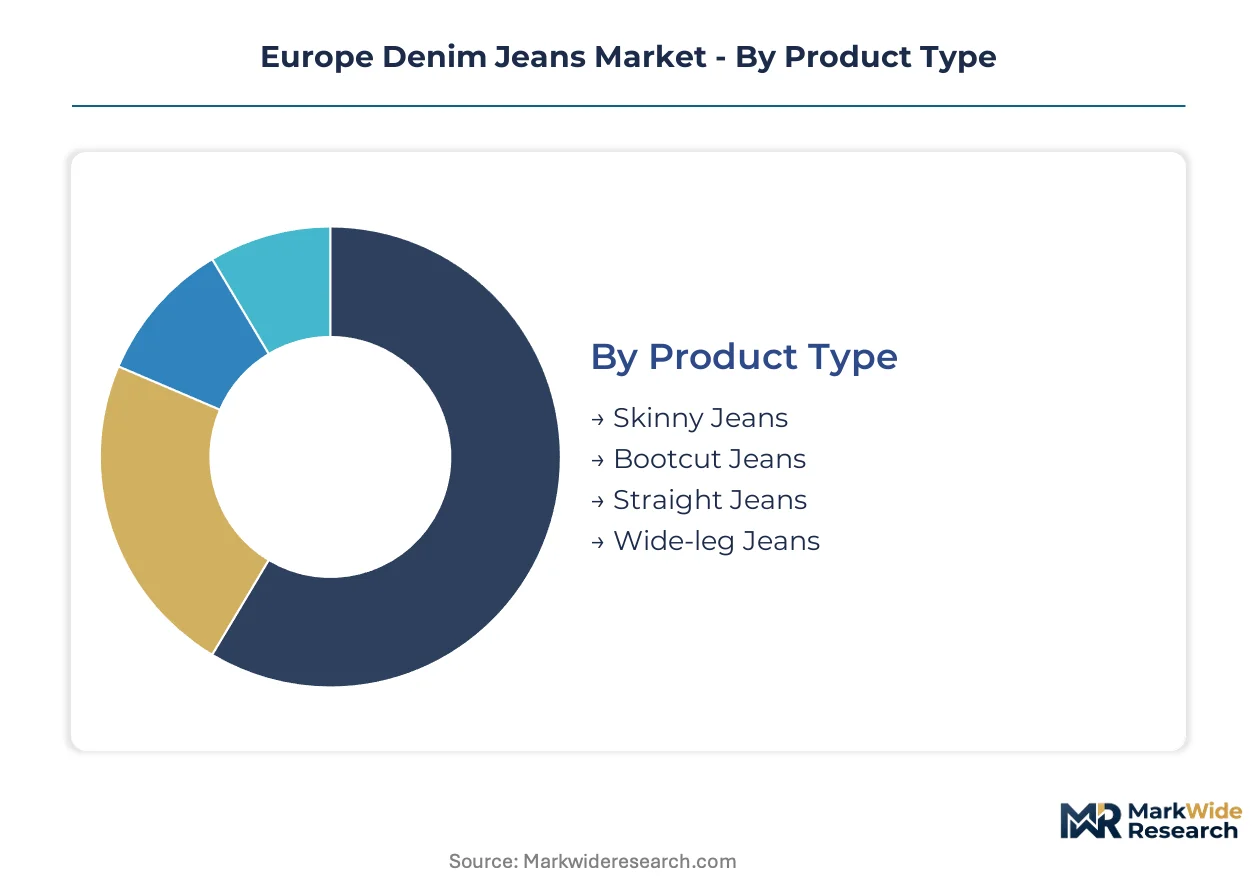
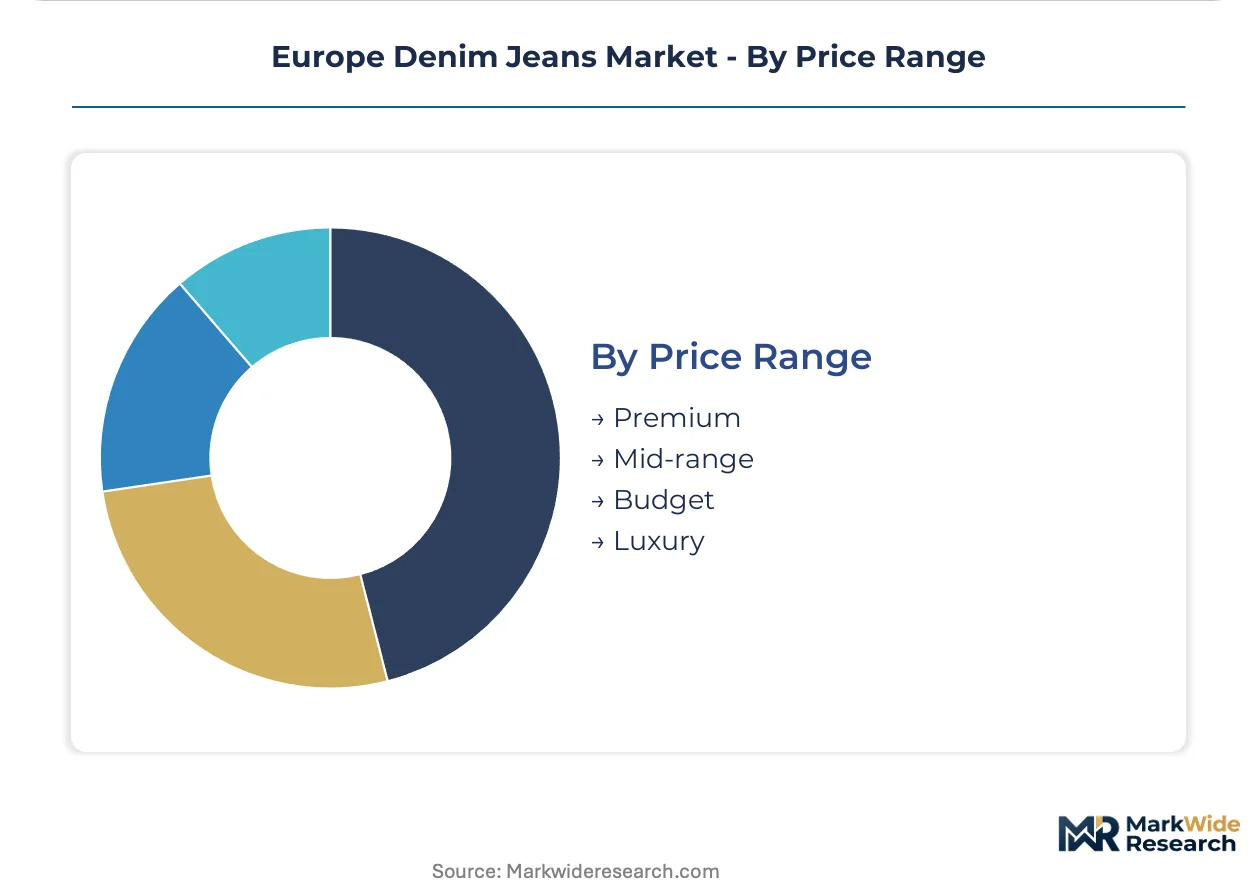
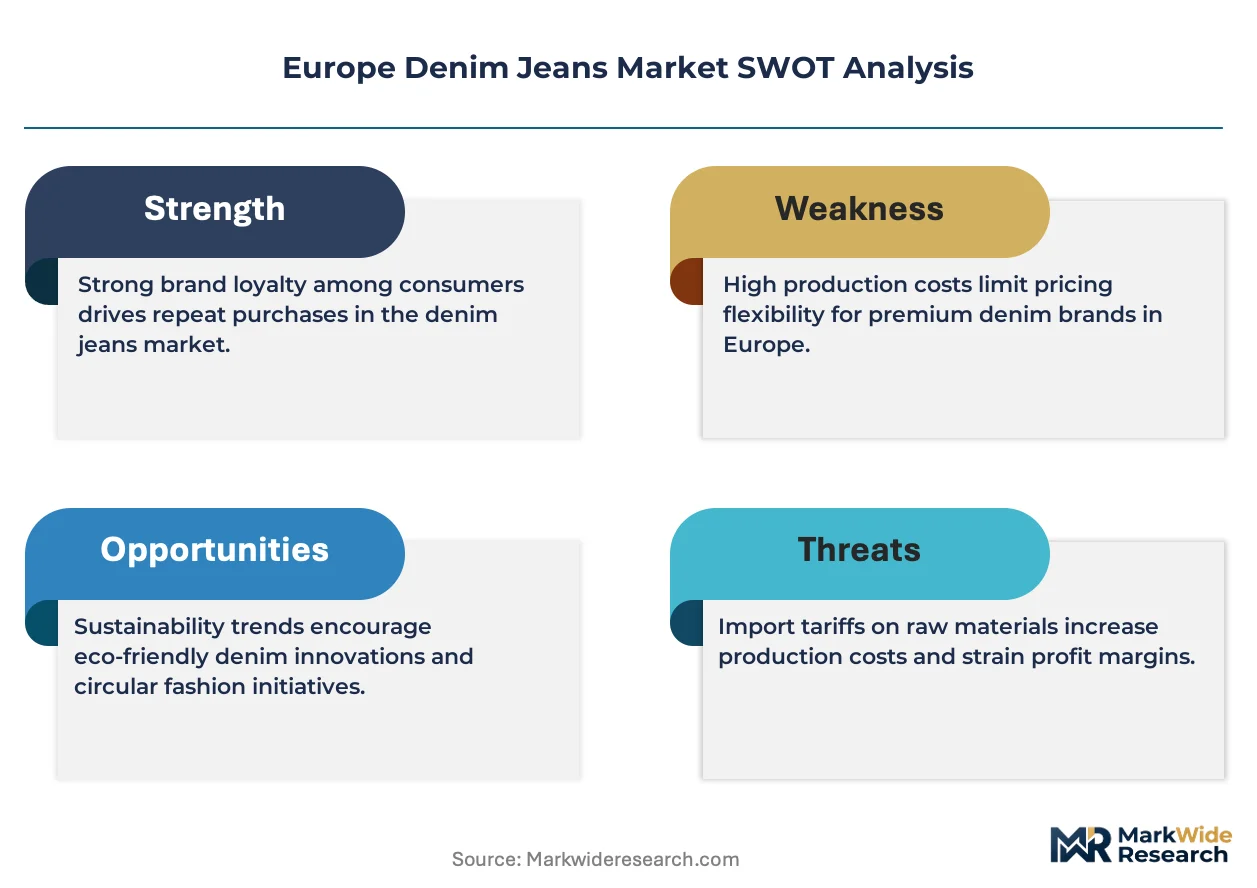
The premium and commodity tiers is recalibrating around sustainability credentials and supply chain transparency rather than price alone. Levi Strauss & Co leverages its Water Europe denim jeans constitute twill-woven cotton garments with warp-faced construction, typically using indigo-dyed yarn and weighing 12 to 14 ounces per square yard for standard-weight applications. The fabric's diagonal rib structure provides tensile strength and abrasion resistance for everyday apparel. Skinny jeans retain volume leadership across mass retail channels, while selvedge denim commands concentrated margin pools among heritage-conscious buyers in Amsterdam and Milan. Stretch denim blends with elastane now dominate women's fast-fashion assortments, though raw denim sustains cult demand among Japanese-influenced European workshops. The EU Green Deal and REACH enforcement by ECHA restrict hazardous dye discharge and formaldehyde finishing, compelling Turkish and North African suppliers serving European brands to upgrade effluent systems. France's AGEC anti-waste law and extended producer responsibility frameworks in Germany and the Netherlands mandate fiber traceability and recycling infrastructure investment. Stakeholders must monitor how CSRD disclosure requirements reshape competitive transparency around Scope 3 emissions before committing to long-term supplier contracts. REACH chemical restrictions and the EU Green Deal are forcing wholesale transformation of European denim supply chains, compelling Turkish and North African suppliers to abandon conventional dyeing infrastructure for waterless and closed-loop systems. Get the full picture before you read further. Download a free sample with table of contents, companies, segments, and methodology. Denim manufacturing is pivoting from volume-centric mass production toward precision-engineered, low-impact systems where sustainability verification determines shelf placement and wholesale account access. Laser finishing technology is automating surface design and distressing operations that previously required manual sandblasting or potassium permanganate spraying. Premium heritage brands in Amsterdam and Milan are adopting these systems at accelerated pace to eliminate hazardous chemical handling. This shift is automating quality consistency while compressing sample-to-production lead times from weeks to days. The EU Green Deal's textile strategy and France's AGEC law are mandating fiber content disclosure and recycled input minimums across all EU member states. Industrial consequence includes mandatory separation infrastructure investment and third-party audit proliferation. Premium positioning in Germany and the Netherlands now depends on verified post-consumer recycled cotton integration exceeding regulatory floors. Urban young adult women are abandoning seasonal replenishment cycles for curated capsule wardrobes with higher per-unit spend and extended wear expectations. Fast-fashion mass retailers face channel compression as direct-to-consumer resale platforms and brand-owned recommerce capture wallet share. This behavioral pivot is most visible in Paris and Berlin, where MUD Jeans and comparable circular operators report lease-to-purchase conversion rates above conventional e-commerce benchmarks. Denim segmentation in Europe reflects divergent paths between mass-market standardization and artisanal customization. Product architecture, fabric provenance, and price positioning create distinct competitive arenas governed by REACH compliance thresholds and CSRD disclosure mandates. The customization-vs-standardization spectrum spans from algorithmically produced basics to hand-finished heritage cuts, with laser-finishing technology compressing lead times across all silhouettes. Leading the category by volume: Skinny Jeans. Growing fastest: Wide-leg Jeans. Customer lifetime value calculations diverge sharply across gender and age cohorts, with women's segments commanding higher per-unit sustainability premiums. Dominant by revenue: Women. Expanding most quickly: Teens. Material specifications now function as compliance documentation, with fiber traceability determining wholesale account access across German and Dutch retail networks. Highest volume: Cotton Denim. Steepest expansion trajectory: Selvedge Denim. Three-tier pricing structure separates CSRD-compliant premium positioning from commodity tiers where Turkish supplier concentration exposes margins to energy price volatility. Revenue concentration: Premium. Gaining share fastest: Luxury. Need this report tailored to your region? Request specific countries, segments, or companies — tailored to your requirements. Amsterdam anchors Europe's circular denim innovation, with MUD Jeans and comparable operators pioneering lease-return infrastructure that is now scaling into adjacent markets. Berlin's capsule wardrobe movement drives premium organic cotton adoption among young adult women. Extended producer responsibility frameworks mandate fiber traceability documentation. The Ruhr Valley logistics corridor hosts automated distribution centers serving circular recommerce platforms. Parisian flagship channels sustain luxury selvedge positioning through limited-batch Italian mill partnerships. AGEC anti-waste law mandates repairability indices and take-back obligations. Lyon-based technical textile institutes collaborate with brands on laser-ozone finishing certification. Milan's heritage manufacturing clusters command concentrated margin pools for hand-finished selvedge denim. REACH enforcement by ECHA restricts hazardous dye discharge from Veneto finishing houses. Florence workshops sustain raw denim cult demand through Japanese-influenced repair-atelier partnerships. Amsterdam-based circular brands prioritize wide-leg silhouettes for lease-return durability and pattern efficiency. CSRD disclosure requirements reshape competitive transparency around Scope 3 emissions. Rotterdam port infrastructure enables direct Turkish mill-to-warehouse logistics compression. London's resale platform penetration compresses new-unit demand for fast-fashion skinny jeans. ECHA authorization timelines delay alternative chemical input reformulation. Manchester heritage manufacturers retrofit narrow-width equipment to capture premium selvedge tier expansion. Capital-heavy producers compete with asset-light designers across a tiered structure where vertical integration depth determines REACH compliance speed. The vendor base clusters around three strategic archetypes: heritage artisans with shuttle-loom capacity, mass-market retailers with Castellón-style logistics hubs, and circular specialists with lease-return infrastructure. Dominant competitive moves include strategic partnerships with Turkish mill networks and portfolio diversification into waterless dyeing platforms. Among American heritage anchors, Levi Strauss & Co exemplifies technology-licensing archetypes through its WaterLess platform standardization. Swedish circular operators MUD Jeans and Nudie Jeans Co. occupy positions within closed-loop consumption models. Spanish retail conglomerate Inditex represents rapid-replenishment logistics integration. These three anchors illustrate the competitive spectrum from compliance-driven premium positioning to volume-centric mass-market infrastructure. Laser-ozone finishing adoption across Turkish and North African mills simultaneously compresses unit processing costs and concentrates premium-tier supply among REACH-compliant operators, creating asymmetric pricing power for certified producers serving German and Dutch retail networks.
Value-based pricing anchored to verified organic cotton certification and blockchain traceability documentation separates premium-tier positioning from commodity floors. Three-tier pricing structure across premium, standard, and economy levels stratifies by ECHA compliance depth and fiber provenance granularity. Cost compression in mid-range tiers intensifies because Turkish mill dependency exposes margins to regional energy volatility. Fast-fashion mass retailers exhibit highest price sensitivity, while heritage-conscious buyers in Milan and Amsterdam accept sustained premiums for selvedge construction with repair-service bundling. Organic cotton supply rests on certified acreage concentration in Turkey, Egypt, and Greece, with climate-sensitive yields creating recurrent input instability. Raw material dependencies span indigo dye precursors, elastane fiber, and narrow-width shuttle-loom equipment. Single-source vulnerability runs through Izmir and Denizli manufacturing basins where European brands concentrate wet-processing orders. Distribution runs through Rotterdam port infrastructure and Castellón-style logistics hubs enabling rapid replenishment cycles. Get the full picture before you read further. Download a free sample with table of contents, companies, segments, and methodology. Limited certified organic cotton acreage functions as the binding capacity constraint, propping pricing power for producers with verified sourcing relationships and backward integration into Turkish mill networks.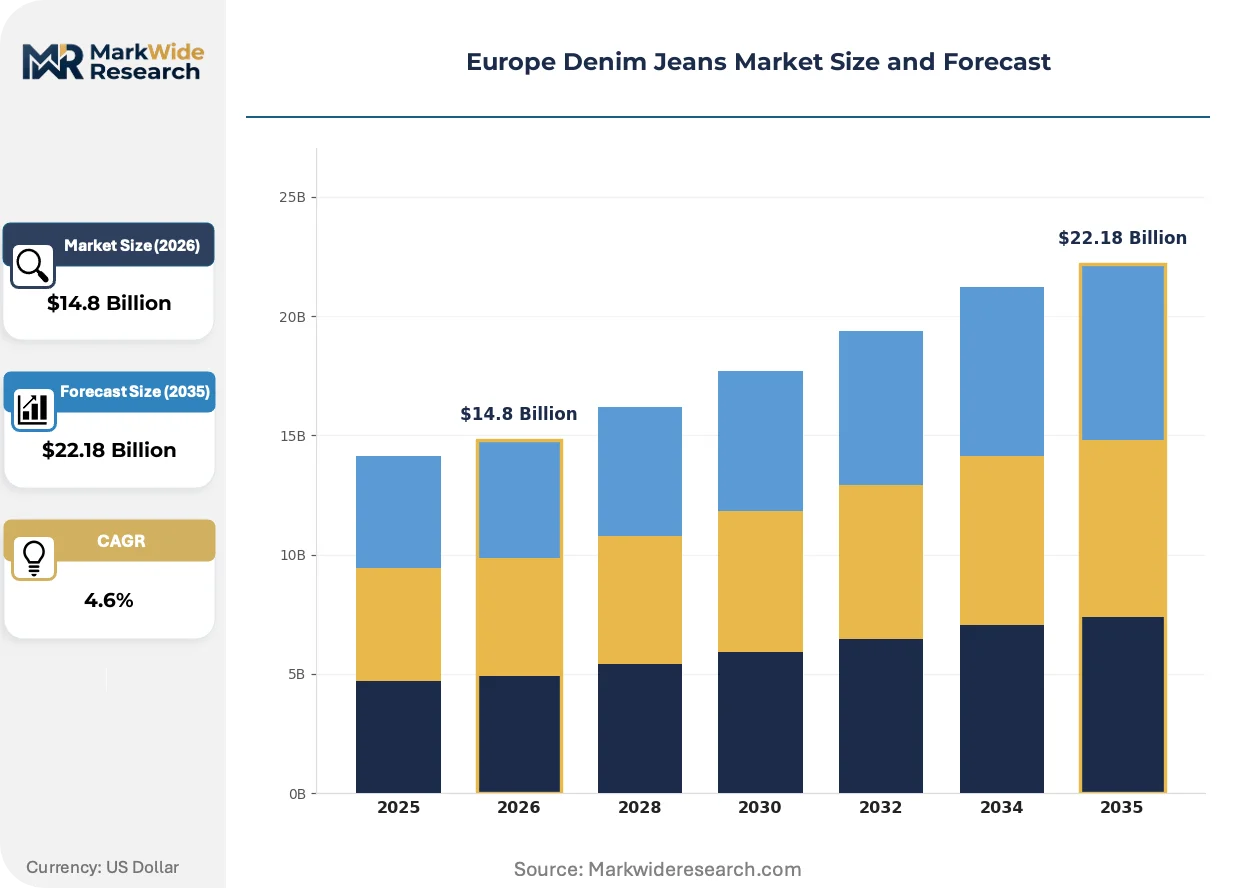
Market Dynamics
Growth Catalysts
Market Restraints
Strategic Opportunities
Industry Challenges
Report Scope
MarkWide ResearchAttributes Details Report Title Europe Denim Jeans Market Market Size in 2026 $14.8 Billion Market Size in 2035 $22.18 Billion CAGR (2026 – 2036) 4.6% Historical Year 2020-2024 Base Year 2025 Forecast Period 2026-2036 Segmentation Companies Covered H&M Group, MUD Jeans, Levi Strauss & Co, Hiut Denim, Armed Angels, Inditex, Nudie Jeans Co., EDWIN Europe, Gap Inc, Others Regions Covered Europe Denim Jeans Market Trends and Innovations
Europe Denim Jeans Market Segmentation
Product Type:
End User:
Fabric Type:
Price Range:
Regional Outlook
Germany
France
Italy
Netherlands
United Kingdom
Europe Denim Jeans Market Competitive Landscape
Leading Market Players H&M Group MUD Jeans Levi Strauss & Co Hiut Denim Armed Angels Inditex Nudie Jeans Co. EDWIN Europe Gap Inc Others Pricing and Supply Chain Analysis
Pricing Analysis
Supply Chain Analysis
Analyst Recommendations
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Cotton Supply Agreement | Secures fiber traceability documentation required by German and Dutch extended producer responsibility frameworks. |
| Laser-Ozone Finishing Certification | Eliminates hazardous discharge compliance costs while compressing sample-to-production lead times for REACH adherence. |
| Lease-Return Infrastructure Buildout | Captures regulatory tailwind from France's AGEC anti-waste law mandating take-back obligations. |
| Blockchain-Fiber Verification Integration | Automates provenance documentation for CSRD Scope 3 emissions disclosure requirements. |
| Central and Eastern Europe Distribution Expansion | Establishes first-mover positioning in underdeveloped premium denim retail channels in Poland and Romania. |
Research Methodology
Independent corroboration across brand sustainability officers, Turkish mill procurement leads, and Dutch retail category buyers underwrites the qualitative findings. Primary fieldwork encompassed supply chain directors at heritage manufacturers in Veneto, circular operations managers at Amsterdam-based lease-return platforms, and ECHA compliance specialists at Lyon technical institutes. Secondary validation drew from EU textile trade statistics, REACH authorization procedure filings, and AGEC repairability index documentation. Bottom-up demand modeling triangulated against top-down value chain assessments.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product type, end-user cohort, fabric specification, and price tier. CAGRs derived from historical shipment data, retail sell-through rates, and input cost elasticity modeling. Forecast inputs incorporated organic cotton yield volatility patterns and ECHA enforcement timeline probabilities.
Underlying measurement precision varies by segment; premium and luxury tiers carry tighter precision than budget tiers where informal channel activity obscures volume capture. Forecasts reflect documented assumptions around regulatory implementation schedules and fiber certification adoption curves. REACH reformulation delays and Turkish energy price shocks warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Luxury Fashion Market
Apparel & Footwear
Swimwear and Beachwear Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Insulated Jacket Market
Apparel & Footwear
Europe Jeans Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
Yoga Clothing Market
Apparel & Footwear
Maternity Activewear Market
Apparel & Footwear
Innerwear Market